
 North America and Europe Medical Technology Market | 2026-2036
North America and Europe Medical Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Medical Technology Market Intelligence
Market Context
Biomedical engineering talent scarcity is unwinding expansion timelines for device manufacturers across the transatlantic corridor. Medtronic leverages its Irish operational base and Minnesota R&D footprint to sustain catheter and pacemaker supply chains on both sides of the Atlantic. Siemens Healthineers anchors its imaging dominance through German manufacturing scale and direct hospital system partnerships in the United States.
Technical Definition and Segment Structure
North America and Europe Medical Technology encompasses electromechanical devices, software-integrated instruments, and consumable diagnostics governed by biocompatibility standards ISO 10993 and IEC 60601 electrical safety parameters, designed to intervene in, monitor, or diagnose human disease states in clinical settings. Imaging Systems generates the largest revenue pool due to MRI and CT replacement cycles in aging hospital infrastructure, while Robotics within surgical applications captures the fastest expansion trajectory as da Vinci-compatible platforms proliferate in European university hospitals and American ambulatory surgery centers. AI-based Systems in diagnostic equipment concentrates margin pools where FDA-cleared algorithms and CE-marked machine learning modules command premium pricing against conventional interpretation workflows.
Regulatory Framework and Outlook
FDA premarket notification and approval pathways, EU MDR transition deadlines, and Health Canada licensing requirements collectively lengthen product commercialization timelines while elevating barriers for non-compliant manufacturers. EMA notified body capacity constraints and FDA breakthrough device designation incentives are diverging regulatory investment strategies between European conformity assessment emphasis and American predicate-based clearance pursuit. Stakeholders must monitor MDR Article 120 transition timeline negotiations and FDA software-as-medical-device guidance evolution to calibrate portfolio registration priorities.
Market Dynamics
EU MDR transition deadlines and FDA software-as-medical-device guidance expansion are compressing commercialization timelines while fragmenting notified body capacity across the transatlantic corridor. Manufacturers face divergent investment requirements between European conformity assessment and American predicate-based clearance pathways.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for AI-integrated diagnostics compress time-to-revenue for algorithm developers targeting American hospital systems. The designation attracts venture capital toward cardiovascular and neurology applications.
- German Hospital Consolidation:Tertiary care networks in Bavaria and North Rhine-Westphalia are centralizing procurement of robotic surgical platforms. Volume aggregation creates favorable pricing leverage for da Vinci-compatible systems.
- ISO 13485:2016 Harmonization:Quality management system alignment across North American and European manufacturing sites reduces audit duplication. Medical device exporters leverage unified documentation for dual-market registration.
Market Restraints
- Notified Body Bottlenecks:EMA-designated conformity assessment organizations face 18-24 month backlog for MDR technical documentation review. Small-cap manufacturers lack capital reserves to sustain pre-revenue intervals.
- Rare Earth Magnet Dependency:MRI system manufacturers rely on Chinese-processed neodymium for superconducting magnet assemblies. Supply concentration creates input cost volatility and forced geographic diversification mandates.
- Reimbursement Code Lag:CMS and German Federal Joint Committee (G-BA) procedural code updates trail FDA and BfArM device approvals by 24-36 months. Novel interventional technologies face commercialization delays despite regulatory clearance.
Strategic Opportunities
- Polish Manufacturing Expansion:Warsaw and Krakow industrial zones offer EU regulatory access with 40% labor cost differential versus Western European assembly. Contract manufacturers are establishing MDR-compliant cleanroom capacity for disposable catheter production.
- Software-as-Medical-Device Convergence:Cloud-native diagnostic algorithms paired with edge-computing hardware create recurring revenue models. Radiology departments in American academic medical centers pilot subscription-based AI interpretation.
- EU Green Deal Procurement Mandates:Public hospital tenders above threshold values now require lifecycle carbon disclosure. Energy-efficient imaging equipment and reprocessed single-use devices gain preferential scoring in French and Dutch procurement frameworks.
Industry Challenges
- Biomedical Firmware Engineering Scarcity:Embedded systems specialists with IEC 62304 software lifecycle expertise command 35% compensation premiums. Device manufacturers compete with automotive and aerospace sectors for talent in Munich and Boston corridors.
- Legacy PACS Integration Friction:AI-enhanced imaging platforms require DICOM conformance testing against heterogeneous hospital IT architectures. Implementation timelines extend 6-12 months beyond contractual delivery dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Medical Technology Market |
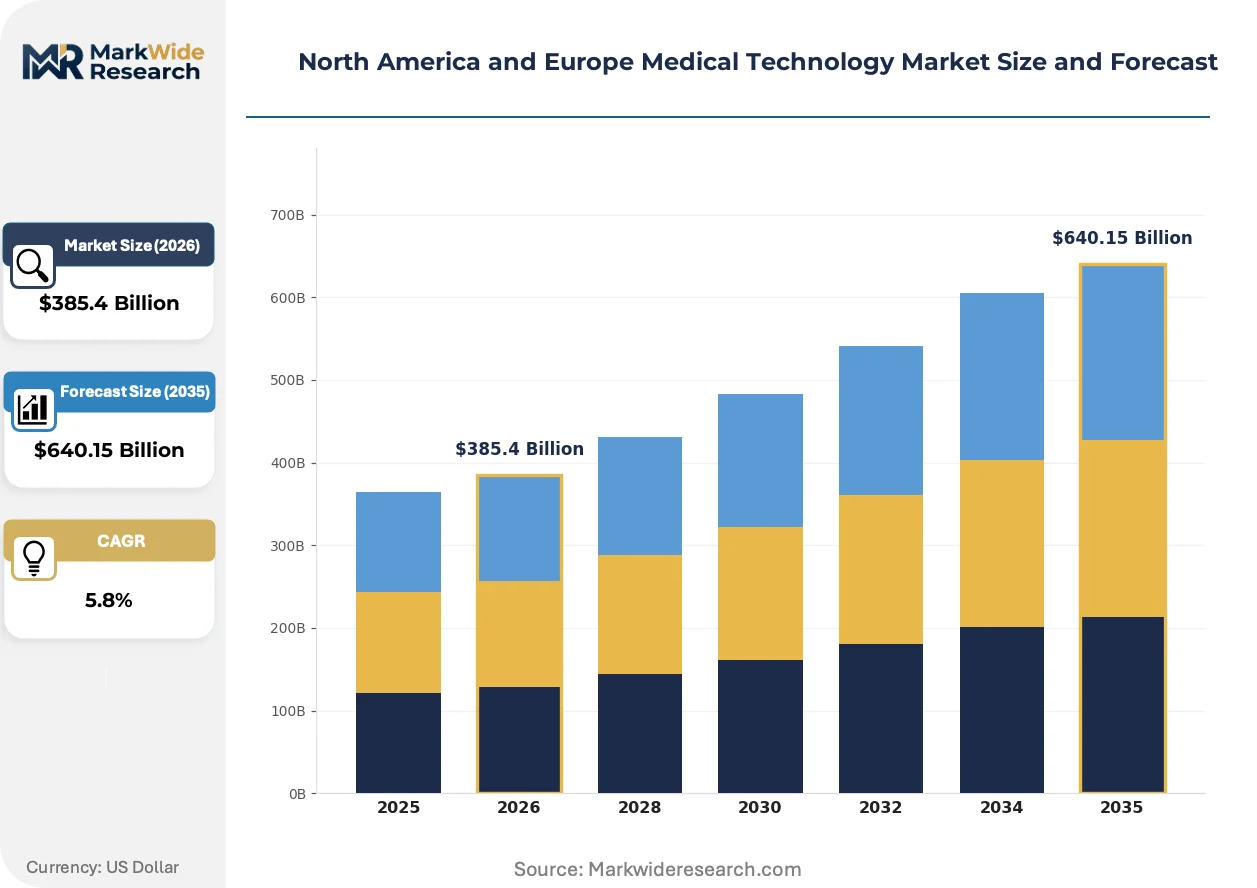
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $640.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Surgical Instruments, Diagnostic Equipment, Monitoring Devices End User: Hospitals, Clinics, Rehabilitation Centers, Diagnostic Labs Technology: Wearable Technology, AI-based Systems, Telemedicine Solutions, Robotics Application: Surgery, Rehabilitation, Patient Monitoring, Diagnostics |
| Companies Covered | Medtronic, Johnson & Johnson Services, Abbott Laboratories, Siemens Healthineers, GE Healthcare, Koninklijke Philips, Boston Scientific Corporation, Stryker, Fresenius Medical Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Medical Technology Market Strategic Shifts & Innovations
Digital pathology and intraoperative imaging are converging to reshape diagnostic workflows across American and European hospital networks. Three developments are compressing traditional equipment replacement cycles and altering vendor competitive positioning.
Photonic-based tissue analysis is supplanting conventional histochemical staining in oncology biopsy processing. Academic medical centers in the United States and Switzerland are deploying coherent Raman scattering microscopes for real-time margin assessment during tumor resection. The technology compresses pathology turnaround from days to minutes, forcing traditional slide scanner manufacturers toward hybrid optical-software architectures.
EU AI Act risk classification frameworks are mandating conformity assessment for machine learning modules embedded in diagnostic equipment. High-risk algorithm categories now require notified body evaluation alongside MDR technical documentation. European imaging OEMs are restructuring quality management systems to accommodate dual regulatory streams, with German manufacturers facing the steepest compliance cost escalation.
Hospital procurement departments are unbundling equipment acquisition from multi-year service contracts. American IDN procurement teams negotiate separate vendor relationships for hardware, software licensing, and preventive maintenance. The disintermediation trend concentrates in cardiovascular and orthopedic device categories, where third-party independent service organizations capture 15-20% of aftermarket revenue from incumbent OEMs.
North America and Europe Medical Technology Market Segmentation
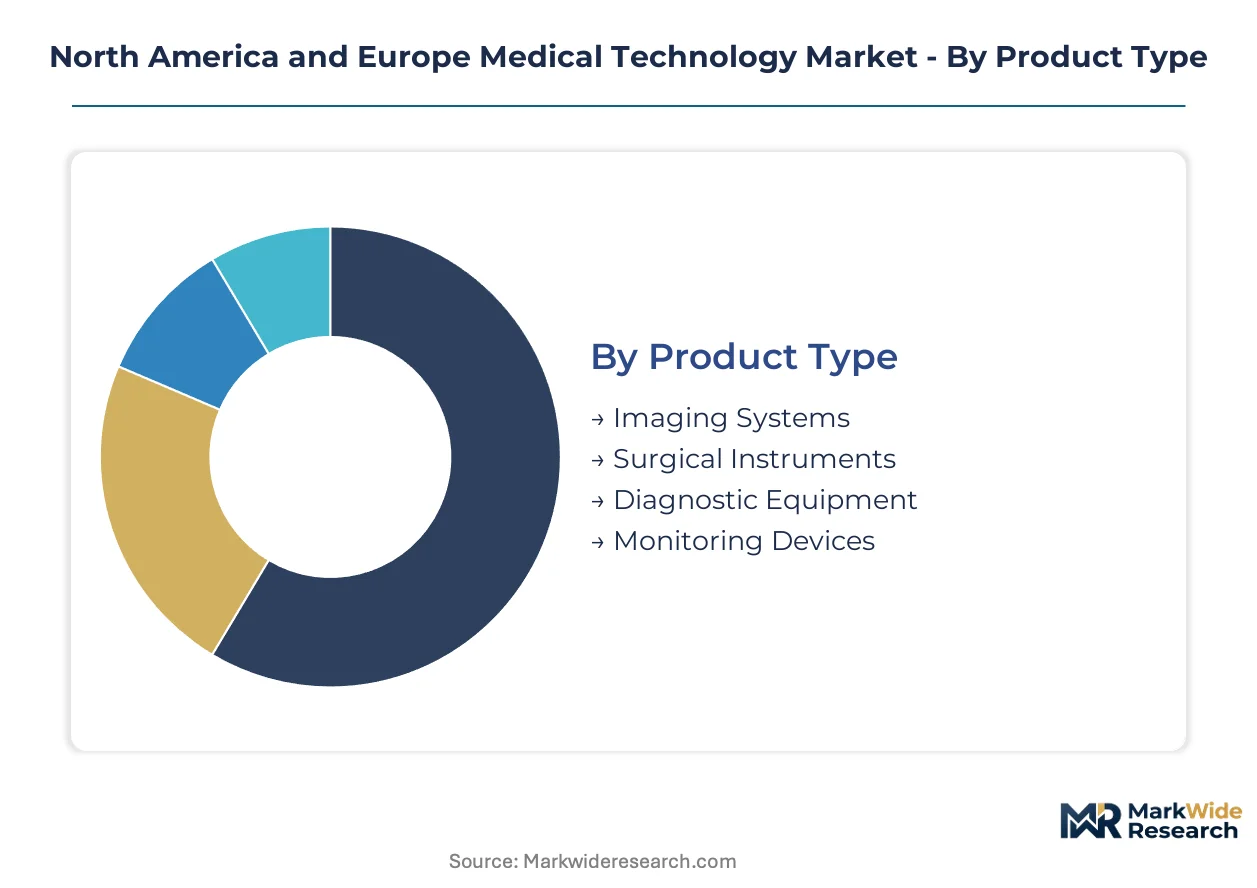
Segmentation in the North America and Europe Medical Technology Market reveals how procurement channels, reimbursement pathways, and regulatory requirements fragment demand across institutional buyers and clinical applications. Manufacturers calibrate product portfolios to match these structural divides.
Product Type:
Channel distribution varies sharply by product complexity—capital equipment flows through direct sales to hospital systems, while consumables and mid-tier devices route through distributor networks serving outpatient facilities.
- Imaging Systems:MRI, CT, and ultrasound platforms with superconducting magnet assemblies and DICOM-compliant software architectures. German university hospitals and American IDNs drive replacement demand as aging infrastructure reaches end-of-life cycles. FDA 510(k) and MDR Class IIb certification requirements elongate sales cycles.
- Surgical Instruments:Electromechanical devices spanning laparoscopic graspers to powered staplers with biocompatible coatings per ISO 10993. Bavarian and Texan tertiary centers concentrate procurement of robotic-compatible instrument sets. Reprocessing economics favor stainless steel reusables over single-use polymer alternatives.
- Diagnostic Equipment:In-vitro analyzers and point-of-care testing platforms with CLIA-waived or laboratory-grade regulatory status.
- Monitoring Devices:Multi-parameter bedside units and ambulatory telemetry systems with wireless connectivity modules.
By volume, Surgical Instruments leads procurement frequency. By growth pace, Imaging Systems is ahead as replacement cycles accelerate.
End User:
Customer type determines pricing tolerance and service contract structure—acute care networks negotiate enterprise agreements while independent clinics prioritize capital efficiency.
- Hospitals:Tertiary and community acute care facilities with centralized procurement functions and dedicated biomedical engineering departments. North Rhine-Westphalia hospital networks and American IDNs aggregate purchasing power for robotic surgical platforms.
- Clinics:Outpatient surgical and specialty care facilities with limited in-house technical support and preference for turnkey service bundles.
- Rehabilitation Centers:Post-acute facilities emphasizing mobility restoration and neurological recovery equipment.
- Diagnostic Labs:Independent and hospital-affiliated reference laboratories with high-throughput automation requirements.
By installed base, Hospitals dominate. By expansion rate, Diagnostic Labs is climbing the fastest as decentralized testing models proliferate.
Technology:
Maturity gradients separate established modalities from emerging platforms still seeking reimbursement codes and clinical validation at scale.
- Wearable Technology:Continuous glucose monitors, cardiac event recorders, and pulse oximetry patches with Bluetooth Low Energy transmission protocols.
- AI-based Systems:Machine learning modules for radiology interpretation and pathology screening embedded in diagnostic workflows. FDA breakthrough device designation and EU AI Act high-risk classification create dual regulatory streams for algorithm developers.
- Telemedicine Solutions:Remote patient monitoring platforms and virtual consultation infrastructure with HIPAA and GDPR compliance architectures.
- Robotics:Surgical assistance platforms with haptic feedback and instrument articulation capabilities. Da Vinci-compatible systems penetrate European university hospitals and American ambulatory surgery centers as G-BA and CMS reimbursement frameworks evolve.
By revenue concentration, AI-based Systems commands premium pricing. By deployment velocity, Telemedicine Solutions is gaining share fastest post-pandemic.
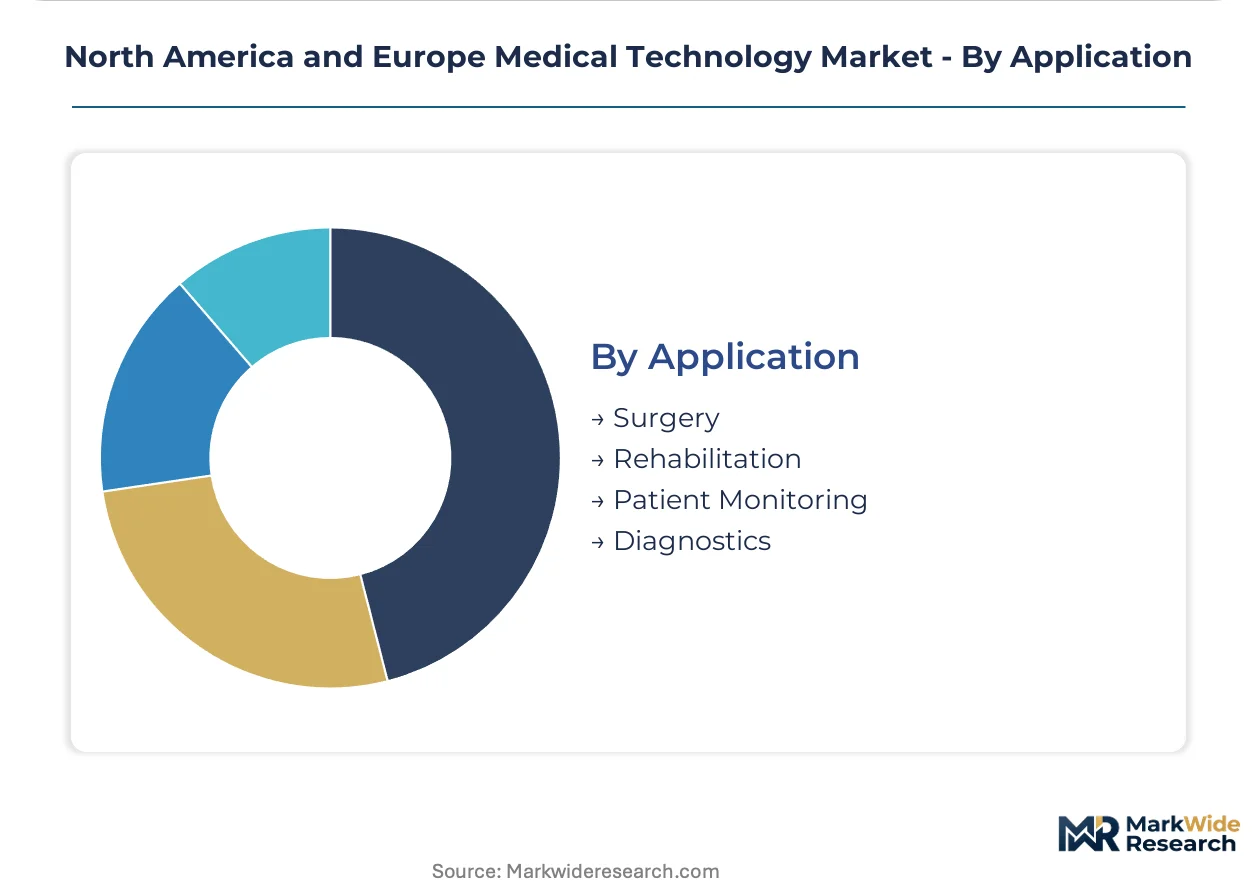
Application:
Clinical use case dictates performance specifications, sterilization requirements, and regulatory classification intensity.
- Surgery:Minimally invasive and open procedures requiring sterile field compatibility and real-time imaging integration. Robotic platforms reshape operative workflows in cardiovascular and urological specialties.
- Rehabilitation:Neuromuscular retraining and mobility restoration with quantified outcome measurement. Exoskeleton and robotic gait trainers concentrate in German and Swiss neurorehabilitation centers.
- Patient Monitoring:Continuous vital sign surveillance across acute and ambulatory settings with alarm management and EMR integration.
- Diagnostics:Disease detection and monitoring spanning laboratory analytics to point-of-care testing with workflow automation priorities.
By procedure volume, Diagnostics leads clinical utilization. By technology substitution intensity, Surgery is expanding most quickly as robotic platforms displace conventional laparoscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across the transatlantic corridor. American health systems prioritize capital equipment throughput and service contract unbundling, while European networks emphasize lifecycle carbon disclosure and multi-source supplier qualification under EU Green Deal procurement mandates.
United States
Integrated Delivery Networks in Texas and the Southeast aggregate purchasing power for robotic surgical platforms. FDA breakthrough device designation accelerates AI-integrated diagnostic commercialization timelines. The Greater Boston corridor concentrates venture capital deployment toward cardiovascular algorithm developers.
Germany
Tertiary care networks in Bavaria and North Rhine-Westphalia centralize procurement of da Vinci-compatible surgical systems. EU MDR transition deadlines and BfArM parallel review pathways elongate product registration intervals. The Munich-Stuttgart industrial axis anchors Siemens Healthineers imaging manufacturing and R&D infrastructure.
United Kingdom
NHS England procurement frameworks prioritize energy-efficient imaging equipment with lifecycle carbon scoring. MHRA recognition of FDA approvals streamlines dual-market registration for transatlantic manufacturers. The Oxford-Cambridge-London arc concentrates AI diagnostic startups targeting radiology workflow automation.
France
Public hospital tenders above threshold values mandate EU Green Deal compliance documentation. ANSM oversight of high-risk device categories converges with EU AI Act algorithm risk classification requirements. The Paris-Saclay cluster hosts medical imaging software development operations serving both domestic and export markets.
Canada
Provincial health authorities in Ontario and Quebec coordinate capital equipment procurement through shared service organizations. Health Canada licensing requirements and FDA recognition agreements reduce duplicate testing burdens for American manufacturers. The Toronto-Waterloo corridor concentrates health technology assessment and health economics research capabilities.
North America and Europe Medical Technology Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in imaging and surgical robotics. The upper tier commands direct hospital system relationships and multi-year service contracts, while mid-cap players compete on procedure-specific instrumentation and regional regulatory expertise. Three archetypes dominate: diversified conglomerates with cross-modal imaging portfolios, pure-play robotics specialists with haptic feedback capabilities, and disposable catheter manufacturers with MDR-compliant cleanroom networks. Competitive moves center on unbundling service contracts from equipment sales and establishing Polish or Mexican contract manufacturing to capture labor cost differentials.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson Services occupy positions spanning cardiovascular, surgical, and diabetes care verticals. Siemens Healthineers anchors the imaging-dominant archetype with German manufacturing scale and direct American hospital system partnerships. These three entities exemplify the integrated leader profile, leveraging transatlantic operational footprints to sustain supply chain continuity across FDA and EU MDR regulatory environments.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson Services |
| Abbott Laboratories |
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Boston Scientific Corporation |
| Stryker |
| Fresenius Medical Care |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements between American IDNs and German imaging OEMs lock in superconducting magnet allocation and freeze equipment pricing across multi-year procurement windows. These arrangements tether hospital capital budgets to rare earth supply chains while insulating buyers from spot-market volatility in neodymium processing.
Pricing Analysis
Project-based pricing for robotic surgical platforms dominates capital equipment transactions, with Bavarian hospital networks negotiating bundled hardware-software-service packages against unbundled component sourcing. Price differentiation separates FDA breakthrough-designated AI diagnostics from CE-marked conventional imaging, with algorithm-integrated systems commanding service-subscription premiums. Cost compression in mid-tier monitoring devices intensifies as Polish contract manufacturers enter MDR-compliant production. Outpatient clinics exhibit highest price sensitivity, while tertiary academic centers prioritize clinical outcome metrics over unit economics.
Supply Chain Analysis
Chinese rare earth processing chokepoints tether MRI magnet assembly to geopolitical supply risk, with neodymium-dysprosium alloy flows concentrated in Jiangxi and Inner Mongolia refining corridors. German superconducting wire manufacturers and American cryogenic system integrators draw from this concentrated upstream, while Japanese ceramic substrate suppliers provide insulation components. Single-source vulnerability in Chinese-processed heavy rare earths exposes OEMs to forced geographic diversification mandates. Distribution runs through direct hospital system contracts for capital equipment and distributor networks for disposable catheters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic surgical platform penetration remains below saturation thresholds in European ambulatory settings, creating runway for algorithm-integrated system deployment as reimbursement codes mature.
For Market Incumbents: Fortify service contract retention through predictive maintenance analytics and embedded biomedical engineering staffing at American IDN anchor accounts. Deepen backward integration into superconducting magnet assembly to offset Chinese rare earth processing concentration. Prioritize MDR Article 120 transition compliance investments ahead of notified body capacity constraints. For New Entrants and Emerging Players: AI-powered pathology workflow automation represents the most penetrable white-space segment, with Swiss and British academic medical centers piloting cloud-native diagnostic algorithms. Target Polish and Mexican manufacturing zones for MDR-compliant cleanroom capacity to capture labor cost differentials against Western European assembly. Pursue FDA breakthrough device designation as the primary go-to-market accelerant for cardiovascular and neurology applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-as-medical-device developers with radiology department subscription contracts. Long-term viability across the projection horizon favors algorithm developers with dual FDA-CE marking pathways and hospital system pilot data. Monitor CMS procedural code updates and G-BA reimbursement decisions as the critical inflection signal for robotic surgical platform commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Expedited review compresses time-to-revenue for AI-integrated diagnostics targeting American hospital systems. |
| CE Marking Pathway Acceleration | MDR technical documentation preparation ahead of notified body bottlenecks secures European market access timing. |
| Hospital System Partnership Formation | Direct relationships with North Rhine-Westphalia networks and American IDNs anchor robotic platform procurement pipelines. |
| Software Companion Development | Cloud-native diagnostic algorithms paired with edge hardware create recurring subscription revenue against capital equipment cyclicality. |
| Reimbursement Strategy Execution | CMS and G-BA procedural code alignment unlocks commercialization for novel interventional technologies post-regulatory clearance. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at imaging and surgical device manufacturers. Primary fieldwork with clinicians and hospital purchasing committees across Bavarian tertiary networks and American IDNs validated secondary data on robotic platform adoption patterns. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product type, end user, technology, and application segments structured the analytical framework over the projection horizon. CAGRs derived from replacement cycle timing, reimbursement code evolution, and regulatory approval velocity. Forecast inputs incorporated superconducting magnet supply constraints, notified body capacity utilization, and AI algorithm clinical validation timelines.
Forecasts assume regulatory continuity in FDA premarket review pathways and EU MDR transition timelines; material policy shifts in either regime would require re-modeling. Practitioners should keep alternative scenarios live as rare earth supply chain reconfiguration and reimbursement code lag dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Contact Lenses Market
Medical Devices
Nasal Irrigation Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Drug and Gene Delivery Devices Market