
 Infrared Sauna Blankets Market | 2026-2036
Infrared Sauna Blankets Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Sauna Blankets Market Insights
Asset-light leasing and subscription rental models are reshaping competitive entry in infrared sauna blankets, lowering capital barriers for wellness startups and direct-to-consumer brands. HigherDOSE leverages its celebrity-backed brand architecture to sustain premium positioning across urban wellness corridors. LifePro anchors its portfolio in fitness-adjacent recovery, competing on price-accessibility through Amazon-dominated channels. Sun Home Saunas controls a vertically integrated manufacturing footprint that extends its margin capture from component sourcing to final assembly.
Infrared sauna blankets are portable, heat-emitting body wraps constructed from layered fabrics incorporating carbon fiber or ceramic heating elements, typically operating at temperatures between 110°F and 160°F to induce thermal therapy through far or near infrared radiation. The primary commercial purpose centers on delivering detoxification, circulation enhancement, and muscle recovery benefits without fixed installation requirements. Multi-layer configurations command the deepest margin pools due to superior heat retention engineering and perceived therapeutic efficacy, while far infrared technology dominates unit economics through established consumer familiarity and lower production complexity. Home users represent the structurally dominant end-user segment, though physiotherapy clinics present the fastest-growing installation base as practitioners integrate thermal modalities into rehabilitation protocols.
The FDA regulates infrared heating devices under 21 CFR 890.5500, mandating electrical safety and electromagnetic emission standards that determine market access for US-bound manufacturers. ETL and UL certifications operate as de facto gatekeeping mechanisms across North American retail channels, with non-compliant products excluded from Amazon's restricted categories and major wellness distributors. The EU's REACH framework and CE marking requirements impose additional material substance and low-voltage directive compliance burdens on brands seeking European market penetration. Stakeholders must monitor evolving electromagnetic field exposure guidelines from the FCC and international health agencies, as emerging research on prolonged infrared exposure could trigger classification shifts or warning label mandates that reshape product design priorities and liability exposure.
Market Dynamics
Post-pandemic preventive health habits have permanently shifted consumer spending toward at-home thermal therapy solutions, compressing the traditional clinic-dependent recovery model and forcing brands to build direct-to-consumer infrastructure.
Growth Catalysts
- Class II medical device pathways:FDA's 21 CFR 890.5500 framework creates compliance clarity that accelerates US market entry for engineered heating products with documented safety profiles.
- Carbon fiber heating elements:Advances in flexible conductive textiles enable uniform heat distribution at lower wattage, reducing energy costs for home users while improving portability.
- Physiotherapy clinic integration:Rehabilitation practitioners in Germany and Australia are embedding thermal modalities into post-surgical recovery protocols, expanding institutional demand beyond retail channels.
Market Restraints
- Ceramic heating component concentration:Sourcing of far-infrared emitting ceramics clusters among East Asian suppliers, exposing margins to freight volatility and geopolitical friction.
- Electromagnetic emission thresholds:FCC guidelines on prolonged EMF exposure create design constraints that extend R&D cycles and limit maximum operating temperatures.
- Traditional sauna substitution:Fixed-installation infrared cabins and steam rooms retain preference among high-net-worth consumers with dedicated wellness space, capping blanket penetration in luxury segments.
Strategic Opportunities
- Brazilian wellness market expansion:ANVISA's evolving medical device classification framework presents first-mover potential for brands establishing local compliance infrastructure ahead of competitor entry.
- Subscription rental channels:Asset-light leasing models lower consumer trial barriers and generate recurring revenue streams distinct from one-time hardware sales.
- Near-infrared technology convergence:Integration of red light therapy wavelengths with thermal emission creates dual-modality products commanding premium positioning in athletic recovery segments.
Industry Challenges
- ETL/UL certification timelines:Third-party electrical safety validation for heating elements extends product launch schedules by four to six months, compressing competitive response windows.
- Biomedical engineering talent scarcity:Cross-functional expertise combining thermal physics, textile engineering, and regulatory compliance remains concentrated among a narrow specialist pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Sauna Blankets Market |
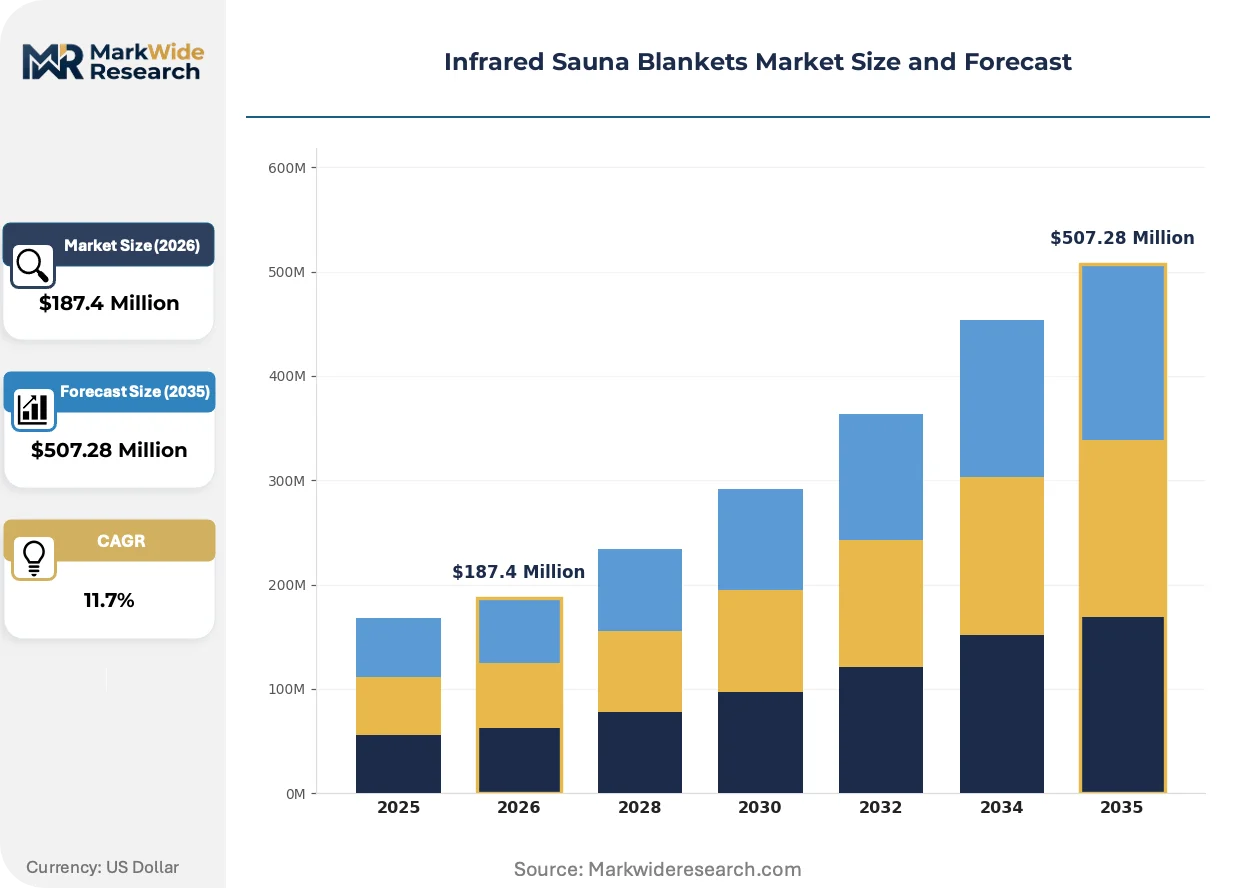
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-layer, Multi-layer, Portable, Non-portable Material: Cotton, Polyester, Nylon, neoprene Heat Technology: Far Infrared, Near Infrared, Carbon Fiber, Ceramic End User: Home Users, Spa Centers, Physiotherapy Clinics, Gyms |
| Companies Covered | HigherDOSE, LifePro, Sun Home Saunas, Hydragun, Hooga, Reviiv, Ete Etmate, Health Mate, MiHIGH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Sauna Blankets Market Trends and Innovations
Product architecture is converging around multi-layer thermal engineering and connected health monitoring, while distribution migrates toward subscription-based access models that decouple revenue from unit shipments.
Graphene-infused conductive films are collapsing the performance gap between portable blankets and fixed sauna installations. Home users seeking clinical-grade thermal therapy are adopting graphene-lined configurations at accelerating rates. This material transition is collapsing price premiums previously commanded by ceramic-based systems and compressing replacement cycles across the installed base.
REACH framework substance restrictions are reshaping material selection across European supply chains. Manufacturers reformulating flame-retardant and adhesive chemistries to meet SVHC disclosure requirements face reformulation costs. German and French distributors are prioritizing suppliers with pre-certified material documentation to accelerate customs clearance and reduce liability exposure.
Rental and lease-to-own arrangements are displacing outright purchase in urban wellness corridors. Direct-to-consumer brands and boutique fitness chains are unbundling hardware ownership from service access. This pattern concentrates in United States coastal metros where apartment dwellers lack storage for seasonal wellness equipment and prefer flexible commitment structures.
Infrared Sauna Blankets Market Segmentation
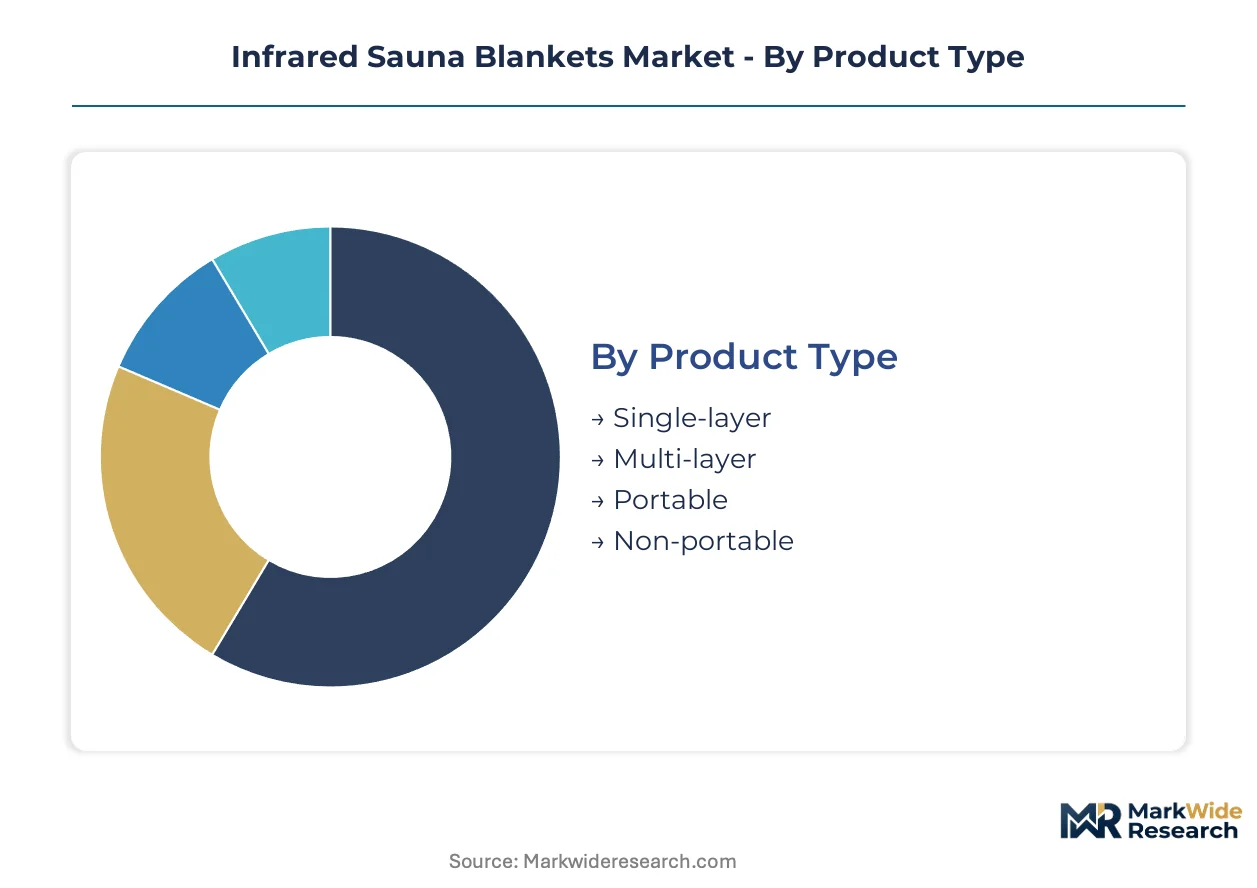
Segmentation in infrared sauna blankets reveals divergent replacement cycles and margin profiles across thermal engineering approaches. Material selection and heating technology drive the widest spreads in unit economics and customer lifetime value.
Product Type:
Multi-layer configurations turn over every three to four years as heat retention degradation accelerates replacement, while single-layer variants compress to eighteen-to-twenty-four month cycles due to faster element wear. Portable units cycle fastest among all product architectures.
- Multi-layer:Constructed from three to five laminated fabric sheets with embedded carbon fiber or ceramic matrices, achieving superior thermal retention through trapped air chambers. Demand concentrates in United States urban wellness corridors where apartment dwellers prioritize clinical-grade heat delivery without fixed installation. Premium positioning sustains despite graphene-lined alternatives compressing price umbrellas.
- Single-layer:Baseline construction with one conductive fabric sheet bonded to a waterproof outer shell, operating at reduced maximum temperatures. Entry-level home users in Germany and Australia drive volume through Amazon-dominated channels where price accessibility trumps therapeutic intensity.
- Portable:Collapsible designs under eight pounds with battery-compatible power draw, targeting athletic recovery on competition circuits. Travel-oriented consumers and boutique fitness chains sustain demand.
- Non-portable:Stationary units requiring dedicated 120V/240V outlets with integrated control panels, favored by physiotherapy clinics embedding thermal modalities into rehabilitation protocols.
Multi-layer configurations anchor the volume base while portable units gain share at the steepest rate.
Material:
Cost tiers separate flame-retardant synthetics from natural fiber blends, with REACH-compliant reformulations adding fifteen to twenty percent to European-bound unit costs.
- Neoprene:Synthetic rubber polymer delivering waterproof integrity and chemical resistance, dominating clinical installations where sanitization protocols demand non-porous surfaces. German physiotherapy networks specify neoprene for institutional procurement contracts.
- Polyester:Woven synthetic with moisture-wicking treatments and dimensional stability under thermal cycling, capturing standard-tier home user demand across direct-to-consumer channels.
- Cotton:Natural fiber with breathable weave structures, preferred by wellness-focused consumers seeking reduced synthetic contact during extended sessions. Organic certification premiums apply.
- Nylon:High-tensile strength polymer resisting abrasion in high-frequency commercial use, specified by gym chains and spa centers with accelerated utilization schedules.
Polyester holds the installed base while neoprene expands most quickly through institutional procurement channels.
Heat Technology:
Technology selection determines electromagnetic emission profiles and FDA 21 CFR 890.5500 compliance pathways, with carbon fiber achieving fastest certification timelines.
- Far Infrared:Ceramic or carbon-emitting elements operating at 5.6 to 15 micron wavelengths, penetrating tissue to induce vasodilation through resonant water molecule absorption. Established consumer familiarity and lower production complexity sustain dominance in United States retail channels despite slower heat ramp times.
- Carbon Fiber:Flexible conductive textiles enabling uniform heat distribution at reduced wattage, collapsing energy costs for home users while improving portability. Australian wellness startups and direct-to-consumer brands prioritize this technology for subscription rental fleet deployment.
- Near Infrared:Wavelengths at 0.7 to 1.4 microns combined with red light therapy convergence, commanding premium positioning in athletic recovery segments where dual-modality efficacy drives purchase decisions.
- Ceramic:Solid-state emitting elements with highest thermal output density, constrained by sourcing concentration among East Asian suppliers exposing margins to freight volatility.
Far Infrared maintains volume leadership while carbon fiber climbs the fastest as energy efficiency priorities reshape home user preferences.
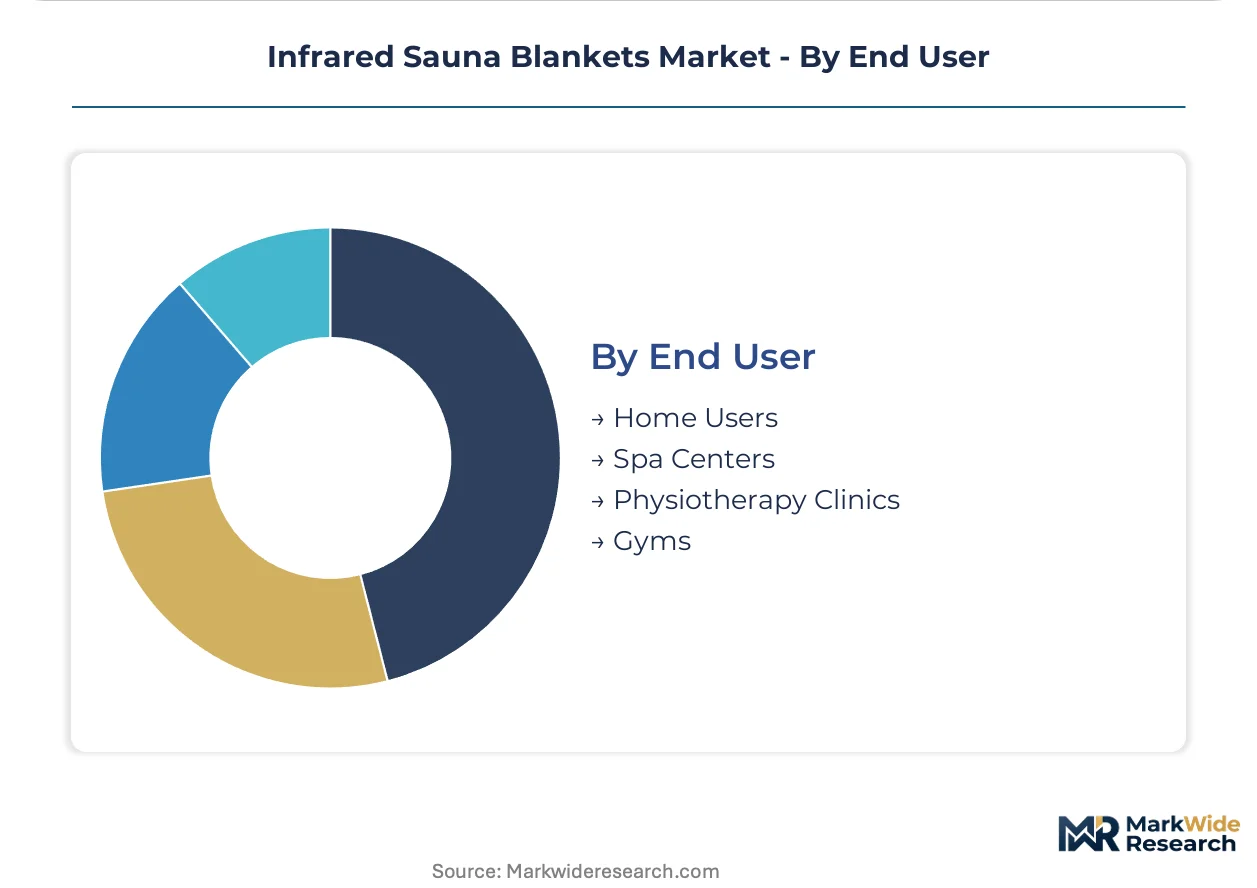
End User:
Customer type determines average session frequency, warranty claim rates, and attachment to subscription or leasing arrangements versus outright purchase.
- Home Users:Wellness-focused consumers with preventive health habits formed during pandemic disruption, averaging three to four weekly sessions. United States direct-to-consumer brands and subscription-based recovery services anchor regional consumption patterns.
- Physiotherapy Clinics:Rehabilitation practitioners in Germany and Australia embedding thermal modalities into post-surgical recovery protocols, representing the steepest expansion trajectory as institutional demand outpaces retail channel growth.
- Spa Centers:Wellness hospitality operators integrating blanket-based thermal therapy into service menus, favoring lease-to-own arrangements to manage seasonal demand fluctuations.
- Gyms:Fitness chains adding recovery zones to membership differentiation strategies, prioritizing durability specifications and bulk procurement terms.
Home Users anchor the volume base while Physiotherapy Clinics gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 21 CFR 890.5500 framework accelerates US market entry for compliant heating devices, while ANVISA's evolving medical device classification in Brazil and TGA's therapeutic goods administration in Australia reshape competitive entry sequencing across high-growth wellness corridors.
United States
Wellness-focused home users drive volume through direct-to-consumer brands and subscription-based recovery services. FDA oversight of Class II medical devices and heating equipment determines distribution access for Amazon-dominated channels. Urban wellness corridors concentrate demand in coastal metros where apartment dwellers prioritize portable thermal therapy.
Germany
Physiotherapy clinics embed thermal modalities into post-surgical rehabilitation protocols, expanding institutional demand faster than retail channels. REACH framework substance restrictions and CE marking requirements impose material compliance burdens on European-bound manufacturers. Industrial clusters in Bavaria and North Rhine-Westphalia host distributors prioritizing pre-certified material documentation.
Australia
Rehabilitation practitioners integrate thermal therapy into recovery protocols, with wellness startups deploying carbon fiber technology for subscription rental fleets. TGA therapeutic goods guidelines shape product registration pathways for medical-adjacent positioning. Sydney and Melbourne anchor consumption patterns among athletic recovery segments.
Brazil
ANVISA's evolving medical device classification framework presents first-mover potential for brands establishing local compliance infrastructure. Preventive health habits formed during pandemic disruption sustain wellness spending among urban middle-class consumers. São Paulo and Rio de Janeiro concentrate early adoption of asset-light leasing models.
Canada
Health Canada oversight of heating devices and electrical safety standards determines retail channel access for US-crossover brands. Urban apartment dwellers in Toronto and Vancouver drive portable configuration demand where storage constraints limit fixed-installation alternatives. Subscription rental channels gain traction in dense metropolitan markets.
Infrared Sauna Blankets Market Competitive Landscape
On the supply side, the industry is moderately concentrated around vertically integrated manufacturers, celebrity-backed wellness brands, and fitness-adjacent direct-to-consumer specialists. Three strategic archetypes dominate: premium-positioned lifestyle brands leveraging influencer architecture; price-accessible Amazon-native competitors; and integrated fabricators controlling component sourcing through final assembly. Competitive moves center on subscription rental channel expansion and graphene material transitions that compress replacement cycles.
Among North American wellness brands, HigherDOSE and LifePro exemplify divergent positioning archetypes, while Sun Home Saunas represents the vertically integrated manufacturing tier. HigherDOSE occupies a position within the celebrity-backed premium segment. LifePro exemplifies price-accessible, fitness-adjacent recovery positioning. Sun Home Saunas anchors the integrated production tier with control extending from component sourcing through final assembly.
| Leading Market Players |
|---|
| HigherDOSE |
| LifePro |
| Sun Home Saunas |
| Hydragun |
| Hooga |
| Reviiv |
| Ete Etmate |
| Health Mate |
| MiHIGH |
| Others |
Pricing and Supply Chain Analysis
Ceramic heating element concentration among East Asian suppliers exposes margin pools to freight volatility and tariff friction, compressing pricing spreads between premium multi-layer configurations and entry-level single-layer units while forcing brands toward carbon fiber substitution or backward integration into component sourcing. This sourcing chokepoint determines both the cost floor for clinical-grade certifications and the supply chain geography that brands must navigate to maintain FDA 21 CFR 890.5500 compliance.
Pricing Analysis
Certification level creates the primary spread between UL/ETL-validated premium tiers and uncertified economy alternatives, with three-tier pricing structure across premium, standard, and economy levels anchored by electrical safety validation timelines. Carbon fiber technology commands modest premiums over ceramic due to faster certification pathways and reduced energy operating costs, though graphene-lined configurations are collapsing historical price umbrellas. Cost compression in the standard tier intensifies as Amazon-native brands compete on accessibility, while physiotherapy clinics demonstrate lowest price sensitivity due to reimbursement-adjacent procurement protocols.
Supply Chain Analysis
Export-control scrutiny on advanced conductive textiles limits flows of graphene-infused films from Chinese specialty manufacturers, concentrating high-performance material access among South Korean and Japanese suppliers with established US customs documentation. Far-infrared emitting ceramics draw from concentrated East Asian foundries, while carbon fiber textiles source from Taiwan and South Korea. Single-source vulnerability in ceramic matrices exposes margins to geopolitical friction, with distribution running through direct-to-consumer channels and institutional procurement networks in Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a post-pandemic habit-formation cycle where preventive wellness spending recovery favors brands with established direct-to-consumer infrastructure and regulatory pre-certification.
For Market Incumbents: Insulate margin position by accelerating backward integration into carbon fiber textile production and securing multi-year ETL validation contracts that extend competitor launch timelines. Prioritize certification investment ahead of FCC electromagnetic emission guideline revisions that could trigger redesign cycles. For New Entrants and Emerging Players: Brazilian urban wellness corridors present the most penetrable geography for first-mover advantage ahead of ANVISA medical device classification finalization. Target subscription rental deployment in São Paulo and Rio de Janeiro, leveraging asset-light leasing to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive component supply and established FDA 510(k) pathways. Long-term viability across the projection horizon hinges on material transition capabilities, with acquisition focus on brands with graphene supply agreements and clinical channel penetration. Watch for FCC electromagnetic exposure guideline revisions as inflection signals that would reshape R&D prioritization and liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Rental Channel Expansion | Asset-light leasing in São Paulo and Rio de Janeiro captures urban apartment dwellers lacking storage capacity. |
| Graphene Material Transition | Graphene-infused conductive films collapse performance gaps with fixed sauna installations and compress replacement cycles. |
| ANVISA Compliance Infrastructure | Early establishment of Brazilian medical device registration creates defensive moats ahead of competitor entry. |
| Carbon Fiber Vertical Integration | In-house production of flexible conductive textiles reduces dependency on East Asian ceramic suppliers and freight exposure. |
| Physiotherapy Clinic Partnership | Institutional procurement contracts in Germany and Australia anchor recurring revenue beyond retail channel volatility. |
Research Methodology
Desk research of FDA 510(k) filings, ETL certification databases, and REACH SVHC substance registries preceded structured interviews with product development executives at direct-to-consumer wellness brands, regulatory affairs specialists, biomedical engineers at physiotherapy networks, and procurement managers at German clinic chains. Secondary validation drew from customs trade data, Amazon category sales estimates, and ANVISA medical device registration records. Bottom-up unit shipment modeling and top-down wellness spending allocation triangulated market sizing across product type, material, heat technology, and end-user segments.
Assumptions held fixed include prevailing FDA 21 CFR 890.5500 classification standards, REACH substance restriction timelines, and carbon fiber textile import tariff schedules, while variables included FCC electromagnetic emission guideline evolution and ANVISA regulatory finalization. Segmentation modeling spanned product architecture, conductive material, thermal wavelength technology, and customer type dimensions. CAGRs derived from regression analysis against wellness equipment spending indices and preventive health behavior surveys, with carbon fiber adoption curves and subscription rental penetration rates as industry-specific forecast inputs.
Practitioners should monitor FCC electromagnetic exposure guideline revisions, ANVISA medical device classification finalization, and East Asian ceramic supplier consolidation for early signals of forecast deviation. Forecasts reflect documented assumptions on regulatory stability and material cost trajectories. Material shifts in FDA device classification or REACH substance restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Tongue Scraper Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Patient Health Management Market
Personal Health
OTC Health Products Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Health Coaching Market
Personal Health
Earwax Removal Products Market
Personal Health
Medical Wellness Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Feminine Hygiene Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Hair Restoration Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Health Check-Up Market
Personal Health
Sleeping Aids Market