
 Flexible Intermediate Bulk Container Market | 2026-2036
Flexible Intermediate Bulk Container Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Intermediate Bulk Container Market Intelligence
Industrial packaging distribution is fragmenting as regional distributors lose ground to direct manufacturer relationships and specialized logistics integrators. Greif Inc. leverages its North American manufacturing footprint to control bulk container supply chains for chemical producers. SCHUTZ GmbH and Co. KGaA anchors European demand through its integrated reconditioning and recycling network. Berry Global Inc. competes on coated fabric technology leadership, extending proprietary laminate barriers into food-grade applications.
Flexible intermediate bulk containers are woven polypropylene or polyethylene fabric sacks, typically rated for 500 to 2,000 kilogram payloads, designed for dry flowable material handling across industrial supply chains. U-Panel designs dominate volume production due to simpler manufacturing and lower material waste, while Baffle configurations command premium positioning for space-constrained shipping. Polypropylene sustains the largest material share by tonnage, though Coated Fabric variants capture margin pools in moisture-sensitive chemical and pharmaceutical end uses.
UN certification frameworks govern hazardous goods transport, while FDA and EFSA compliance shapes food-grade and pharmaceutical adoption pathways. The EU Green Deal and emerging extended producer responsibility rules in Germany and France are forcing material recovery and recyclability redesigns. Stakeholders must monitor how regional packaging waste legislation reshapes material specifications and reconditioning economics before committing capital to capacity expansion.
Market Dynamics
Polypropylene woven fabric with UV stabilization is displacing multi-wall paper systems across chemical and agricultural supply chains, forcing incumbent converters to retool extrusion and coating lines or exit bulk packaging entirely.
Growth Catalysts
- UN Transport Certification:Chemical processors in Germany and India are expanding certified bulk container procurement to meet stricter hazardous goods transport frameworks governing cross-border shipments.
- Coated Fabric Barriers:Laminated polypropylene variants capture moisture-sensitive pharmaceutical and specialty chemical volumes previously served by rigid intermediate bulk containers.
- Yangtze River Delta Cluster:China's manufacturing concentration generates sustained demand for 1,000-1,500 kg payload configurations serving polymer and fertilizer export flows.
Market Restraints
- Polypropylene Resin Volatility:Propylene feedstock price swings compress converter margins and deter long-term supply contracts with agricultural distributors.
- Single-Source Woven Fabric Supply:Gujarat's chemical corridor depends on concentrated domestic tape extrusion capacity, creating geographic vulnerability to monsoon-disrupted logistics.
- Multi-Wall Paper Substitution Defense:Established paper-based systems retain cost advantage in short-haul domestic distribution where moisture exposure remains minimal.
Strategic Opportunities
- EU Green Deal Extended Producer Responsibility:German and French packaging waste rules are forcing material recovery redesigns that favor reconditioning service providers with integrated collection networks.
- Food-Grade Barrier Migration:FDA and EFSA compliance pathways enable coated fabric penetration into dairy powder and starch handling applications previously restricted to rigid formats.
- Pharmaceutical Active Ingredient Handling:Baffle-configuration space optimization aligns with air freight cost pressures for high-value excipient shipments from Indian API manufacturing zones.
Industry Challenges
- UN Certification Timeline Compression:Testing laboratory bottlenecks extend hazardous goods approval cycles, delaying new product launches for chemical sector customers.
- Reconditioning Network Integration:Reverse logistics coordination across dispersed industrial users demands ERP system upgrades that mid-size converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Intermediate Bulk Container Market |
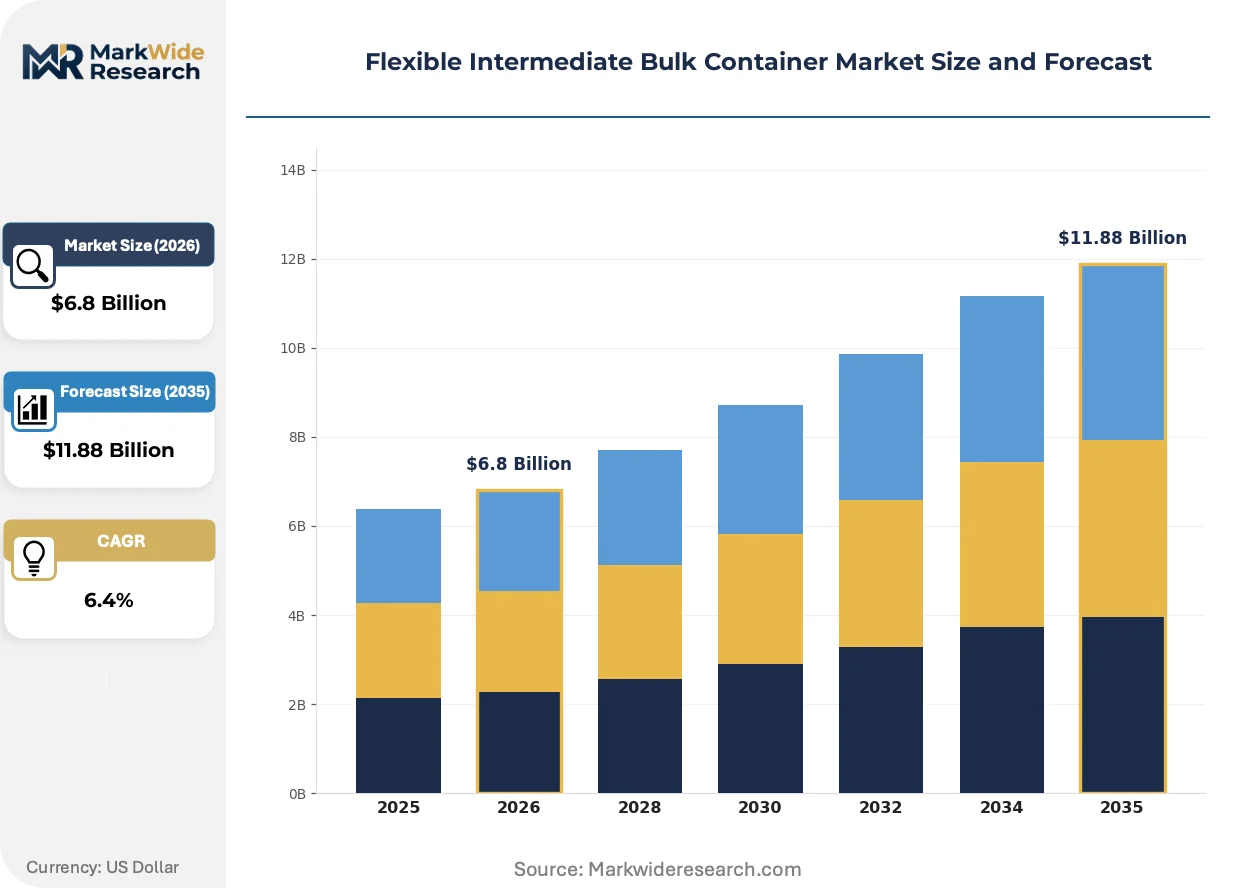
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross Corner, U-Panel, Four Panel, Baffle Material: Polyethylene, Polypropylene, Coated Fabric, Laminate End User: Agriculture, Chemicals, Food & Beverage, Pharmaceuticals Design Type: Standard, Heavy Duty, Customizable, Biodegradable |
| Companies Covered | JohnPac, Pursuit Industries, Berry Global Inc., Sonoco Products Co., SCHUTZ GmbH and Co. KGaA, Greif Inc., Rishi FIBC Solutions Pvt. Ltd., Global Pak Inc., BAG Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Intermediate Bulk Container Market Strategic Shifts & Innovations
Active RFID tagging and blockchain traceability layers are embedding into bulk container fleets, transforming asset tracking from periodic manual inspection to continuous digital monitoring across chemical and food-grade supply chains.
Radio-frequency identification with pressure-sensitive adhesive antennae is digitizing location and fill-level visibility for chemical processors managing just-in-time raw material flows. Major German automotive coating suppliers now mandate tagged container fleets for inbound pigment logistics. Real-time inventory positioning is compressing safety stock requirements and enabling dynamic route optimization for third-party logistics providers.
The EU Green Deal's packaging waste directive is accelerating recyclability mandates that force polypropylene fabric redesigns toward mono-material constructions. German converters must demonstrate closed-loop recovery rates to maintain preferred supplier status with chemical majors. France's extended producer responsibility implementation is creating compliance cost differentials between integrated reconditioning networks and asset-light trading houses.
Direct manufacturer relationships are displacing traditional distributor intermediaries in bulk container procurement for large chemical and agricultural buyers. Specialty logistics integrators now bundle container supply with washing, tracking, and reverse logistics in single-source contracts. This consolidation is most visible in India's Gujarat chemical corridor, where multinational agrochemical firms have consolidated vendor bases from twelve regional distributors to three integrated service providers.
Flexible Intermediate Bulk Container Market Segmentation
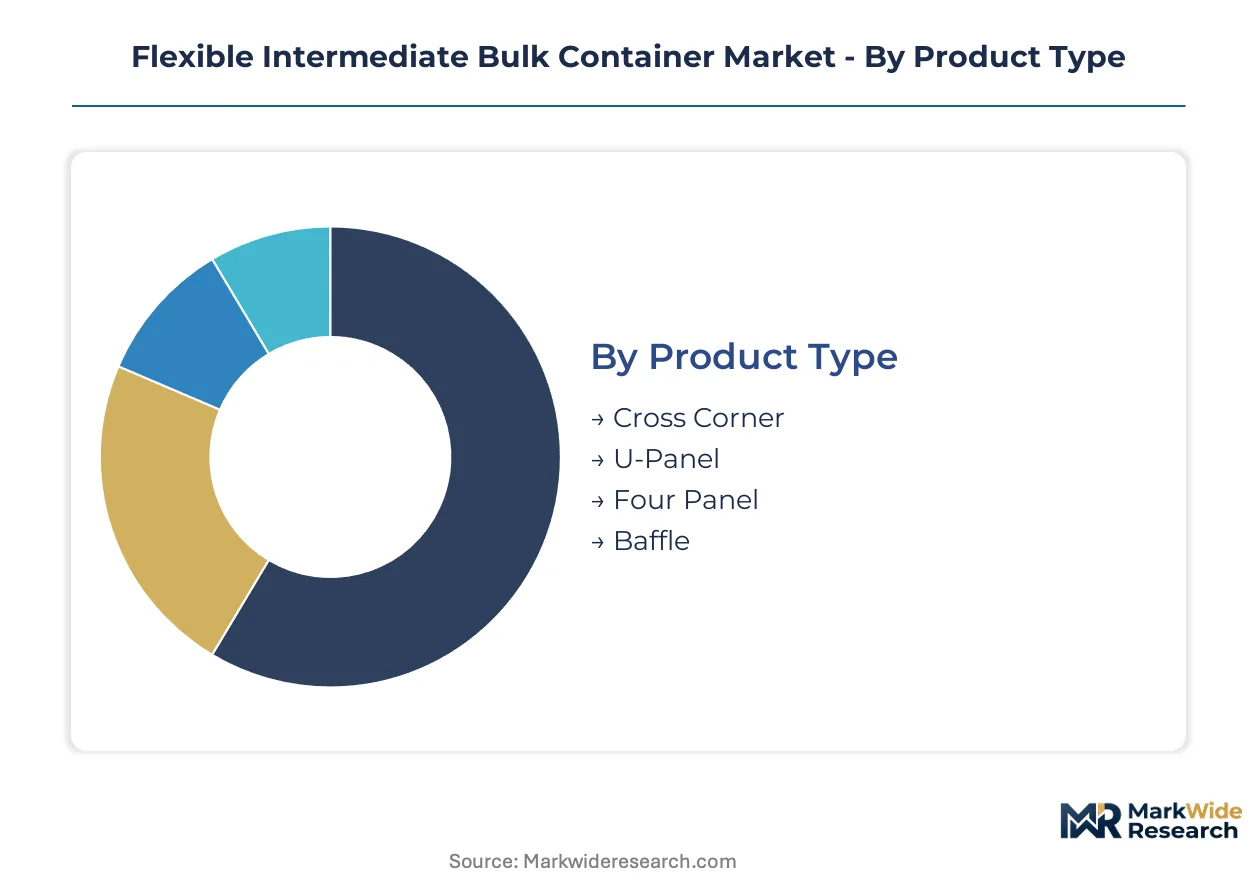
Flexible intermediate bulk container procurement patterns diverge sharply across payload specifications, material barriers, and regulatory compliance tiers. Chemical processors in Germany and pharmaceutical exporters in India drive demand toward certified configurations with traceable supply chains, while agricultural distributors in China's interior provinces prioritize cost-optimized standard designs.
Product Type:
Mature manufacturing processes dominate volume production, though emerging geometries are capturing premium positioning in space-constrained logistics.
- U-Panel:Two vertical seams and a flat bottom panel simplify extrusion and cutting operations, minimizing material scrap rates during high-volume runs. Chemical distributors across India's Gujarat corridor specify U-Panel configurations for 1,000 kg fertilizer shipments where pallet stability outweighs cubic efficiency concerns.
- Baffle:Internal fabric panels maintain rectangular form factors during filling, recovering 15-20% of shipping volume versus cylindrical alternatives. Pharmaceutical excipient exporters from Hyderabad's API manufacturing zones specify baffle designs for air freight optimization on high-value active ingredient shipments.
- Cross Corner:Corner seam reinforcement distributes lifting stress across four webbing points, suited for construction aggregate handling.
- Four Panel:Four-seam construction offers maximum dimensional stability for hygroscopic chemical powders.
U-Panel retains volume leadership; Baffle holds the steepest expansion curve.
Material:
Cost tiers separate commodity woven fabrics from engineered barrier systems serving moisture-sensitive applications.
- Polypropylene:Woven tape extrusion from homopolymer resin delivers tensile strength above 1,500 N/5cm at lowest unit cost. China's Yangtze River Delta manufacturing cluster consumes polypropylene tonnage for polymer pellet exports to Southeast Asian processors.
- Coated Fabric:Laminated polyethylene or polypropylene layers block moisture vapor transmission below 5 g/m²/day. German automotive coating suppliers mandate coated fabric for pigment logistics under EU REACH contamination prevention protocols.
- Polyethylene:Lower density alternative for food-grade applications requiring FDA compliance pathways.
- Laminate:Multi-layer coextrusion achieves oxygen barrier properties for pharmaceutical nitrogen flushing requirements.
Polypropylene dominates tonnage throughput; Coated Fabric captures the widest margin expansion.
End User:
Application-specific regulatory frameworks segment demand between hazardous goods certification and sanitary handling protocols.
- Chemicals:UN-certified configurations with 13H2 designation handle corrosive and flammable solids under cross-border transport frameworks. German processors expanding bulk packaging procurement face compressed testing laboratory timelines for new product qualification.
- Pharmaceuticals:FDA and EFSA compliance documentation accompanies every lot for excipient and API handling. Indian manufacturers in Hyderabad and Ahmedabad are migrating from rigid IBCs to flexible formats for air freight cost reduction on high-value shipments.
- Agriculture:Grain and fertilizer distributors prioritize UV stabilization for extended outdoor storage.
- Food & Beverage:Dairy powder and starch applications require migration-tested laminate barriers.
Chemicals anchor procurement volume; Pharmaceuticals is expanding most quickly.
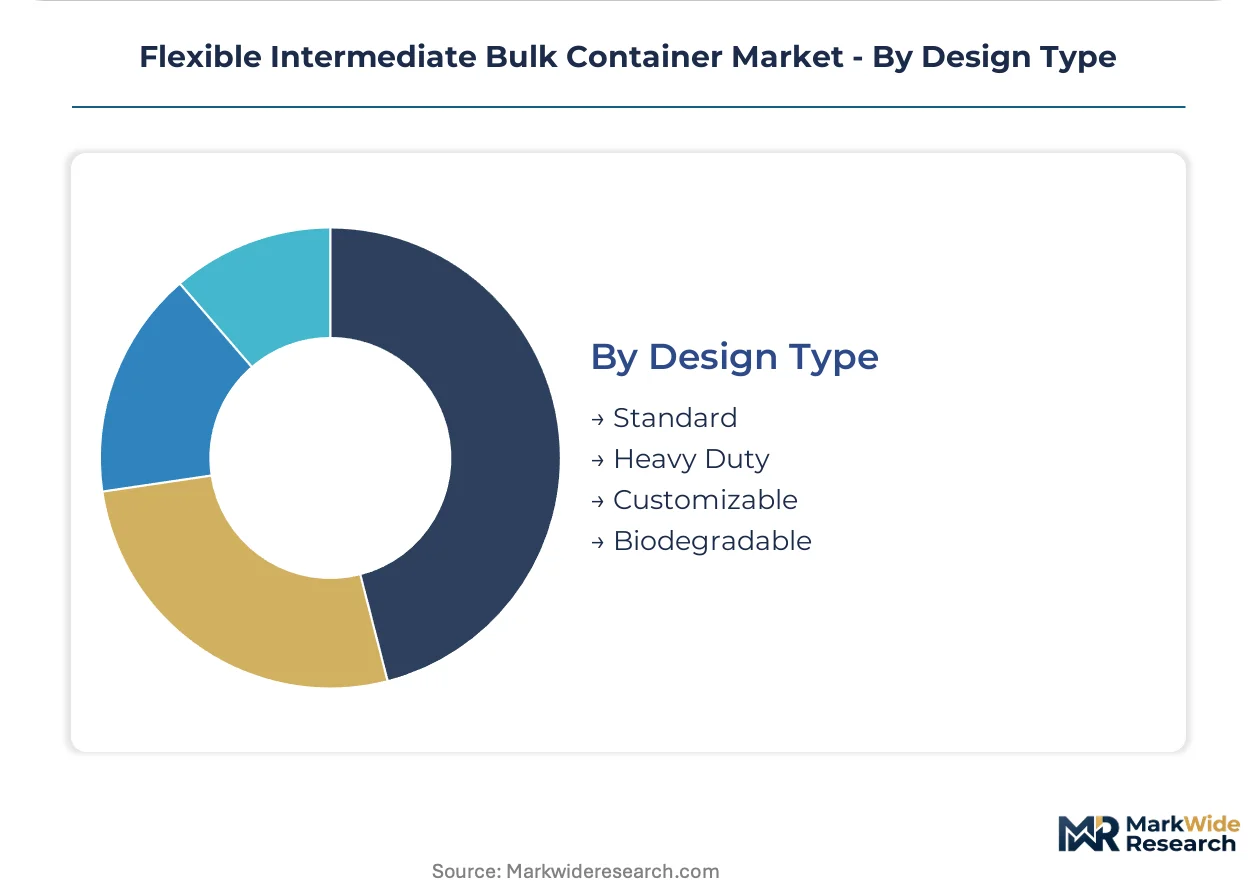
Design Type:
Customer type stratification separates commodity distributors from integrated service providers demanding asset-tracking integration.
- Standard:Basic 1,000-1,500 kg payload ratings without customization serve agricultural cooperatives and regional chemical distributors. Domestic short-haul networks in India's interior states specify standard designs where moisture exposure remains minimal and UN certification is not required.
- Heavy Duty:Reinforced body fabric and double-bottom construction achieve 2,000 kg safe working loads for dense mineral handling. German automotive suppliers specify heavy duty configurations for metal oxide pigment shipments with automated filling systems.
- Customizable:RFID tagging, color coding, and corporate branding options support fleet management integration.
- Biodegradable:Experimental starch-based woven tapes target EU Green Deal extended producer responsibility compliance.
Standard configurations retain the broadest installed base; Heavy Duty is climbing the fastest on automation-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging waste directives and India's PLI scheme for chemical manufacturing are redistributing procurement gravity across major industrial economies. National regulations on extended producer responsibility and hazardous goods certification now determine where converters expand woven fabric capacity.
China
Yangtze River Delta polymer processors generate sustained demand for 1,000-1,500 kg payload configurations serving fertilizer and resin export flows. MIIT's dual carbon goals pressure domestic tape extruders toward energy-efficient production lines. Ningbo and Shanghai port clusters concentrate container washing and reconditioning infrastructure for circular supply chains.
Germany
Automotive coating suppliers mandate UN-certified configurations for inbound pigment logistics under REACH contamination prevention protocols. The EU Green Deal forces converters to demonstrate closed-loop polypropylene recovery rates to maintain preferred supplier status. North Rhine-Westphalia's chemical corridor anchors reconditioning network integration for multinational agrochemical firms.
India
Hyderabad and Ahmedabad API manufacturers migrate from rigid IBCs to flexible formats for air freight cost reduction on high-value excipient shipments. CDSCO's tightening pharmaceutical packaging documentation requirements favor converters with integrated testing laboratories. Gujarat's chemical corridor has consolidated vendor bases from twelve regional distributors to three integrated service providers.
United States
Midwest agricultural cooperatives specify UV-stabilized polypropylene for extended outdoor grain storage where moisture exposure remains seasonal. FDA compliance pathways enable coated fabric penetration into dairy powder handling applications. Texas and Louisiana petrochemical complexes drive demand for hazardous goods certified configurations under DOT cross-border frameworks.
Brazil
São Paulo-state fertilizer distributors prioritize cost-optimized standard designs for domestic short-haul networks where UN certification is not required. ANVISA's pharmaceutical packaging regulations create compliance cost differentials between integrated converters and asset-light trading houses. The country's agricultural export expansion sustains procurement of 1,000 kg rated configurations for soybean and corn flows.
Flexible Intermediate Bulk Container Market Key Industry Players
On the supply side, the industry is consolidating around integrated reconditioning networks and specialized logistics bundlers. Tiered competitive positioning separates asset-heavy manufacturers with captive washing facilities from trading houses dependent on third-party service networks. Two strategic archetypes dominate: integrated reconditioning providers with reverse logistics control, and coated fabric specialists capturing moisture-sensitive premium volumes. Dominant competitive moves include ERP system integration for fleet tracking and geographic expansion through distributor acquisition.
Within the integrated service tier, SCHUTZ GmbH and Co. KGaA and Greif Inc. exemplify the reconditioning-network archetype, while Berry Global Inc. occupies a position among coated fabric technology leaders. Rishi FIBC Solutions Pvt. Ltd. represents Indian domestic scale fabrication serving regional chemical and agricultural procurement. These company structures illustrate how geographic origin and organizational form map onto competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| JohnPac |
| Pursuit Industries |
| Berry Global Inc. |
| Sonoco Products Co. |
| SCHUTZ GmbH and Co. KGaA |
| Greif Inc. |
| Rishi FIBC Solutions Pvt. Ltd. |
| Global Pak Inc. |
| BAG Corp. |
| Others |
Cost & Logistics Intelligence
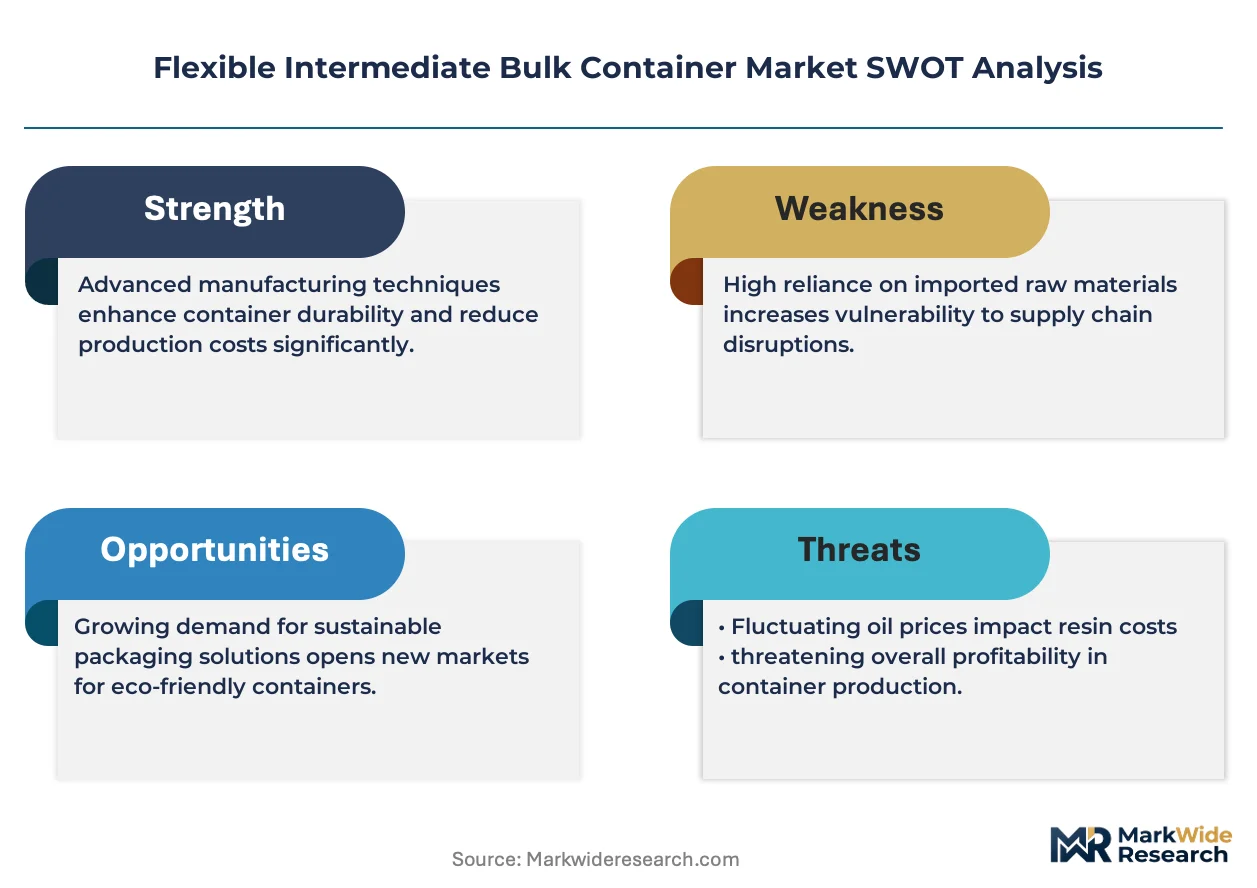
Yangtze River Delta port logistics corridors compress freight costs for polypropylene resin inbound flows, concentrating pricing power among Chinese tape extruders while forcing German and Indian converters toward UN-certified premium tiers to defend margin positions against commodity import competition.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with UN 13H2 hazardous goods configurations commanding substantial premiums over standard agricultural specifications. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by barrier performance, UV stabilization grade, and RFID traceability integration. Pricing pressure stems from propylene feedstock volatility that erodes converter margins on fixed-price annual contracts. Agricultural cooperatives in India's interior states exhibit highest price sensitivity, while German automotive coating suppliers demonstrate lowest sensitivity due to REACH-mandated contamination prevention requirements.
Supply Chain Analysis
Contract manufacturing concentrates among integrated reconditioning specialists in Germany, captive tape extrusion operations in China, and regional fabricators in India's Gujarat corridor. Raw material flows draw from Saudi Arabian and Chinese propylene crackers, Korean woven loom equipment, and domestic Indian UV stabilizer compounding. Single-source vulnerability pervades the Gujarat chemical corridor's dependence on monsoon-exposed domestic logistics. Distribution runs through direct manufacturer relationships displacing traditional distributor intermediaries, with specialty logistics integrators bundling container supply, washing, and reverse logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multinational agrochemical and chemical processors consolidate vendor bases from fragmented regional distributors toward integrated service providers with captive reconditioning networks.
For Market Incumbents: Pre-empt margin erosion from polypropylene resin volatility by securing backward integration into tape extrusion capacity in China or Saudi Arabia. Anchor preferred supplier status with German chemical majors by demonstrating closed-loop recovery rates under EU Green Deal extended producer responsibility rules before French implementation creates compliance cost differentials. For New Entrants and Emerging Players: Pharmaceutical excipient handling in Hyderabad's API manufacturing zones represents the most penetrable entry point, as air freight cost pressures accelerate migration from rigid IBCs toward baffle-configuration flexible formats. Target food-grade dairy powder applications in the US Midwest through FDA-compliant coated fabric barriers as an alternative to established multi-wall paper systems. Lead with RFID-enabled fleet management integration to differentiate against commodity fabricators lacking ERP system capabilities. For Investors and Strategic Acquirers: Integrated reconditioning networks with reverse logistics control and geographic density in Germany or India present the most defensible acquisition targets against asset-light trading houses facing extended producer responsibility compliance cost disadvantages. Long-term viability hinges on circular supply chain economics rather than virgin material conversion margins. Monitor CDSCO pharmaceutical packaging documentation tightening and EU Green Deal recyclability mandate acceleration as inflection indicators for reconditioning service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tape Extrusion | Captive propylene supply from Saudi crackers insulates German converters from feedstock volatility. |
| RFID Fleet Management Platform | Real-time fill-level visibility enables just-in-time pigment logistics for automotive coating suppliers. |
| UN Certification Laboratory Investment | In-house 13H2 testing compresses approval cycles for chemical sector new product launches. |
| Reconditioning Network Expansion | Geographic density in Gujarat corridor captures vendor consolidation from twelve distributors to three integrators. |
| Coated Fabric Barrier Development | Laminated polyethylene layers penetrate moisture-sensitive pharmaceutical applications under REACH protocols. |
Research Approach
The analysis maps U-Panel and Baffle configurations, polypropylene and coated fabric materials, and chemical, pharmaceutical, and agricultural end uses, each validated through procurement managers at multinational agrochemical firms, plant engineers at German automotive coating suppliers, and logistics directors at Indian API manufacturers. Primary interview findings triangulate against secondary sources including UN hazardous goods transport certification databases, EU Green Deal packaging waste directive implementation filings, and customs trade data for woven polypropylene fabric flows. Bottom-up demand modeling from end-use consumption patterns reconciles with top-down capacity assessments from tape extrusion and container fabrication facilities.
Assumptions held fixed include prevailing UN certification frameworks, EU extended producer responsibility implementation timelines, and propylene feedstock price band ranges, while variables included pharmaceutical air freight cost trajectories and agricultural distributor consolidation rates. Segmentation dimensions encompass product geometry, material barrier performance, regulatory compliance tier, and regional production cluster concentration. CAGRs derive from slope analysis of segment-level demand curves across the analysis window, with inputs including polymer pellet export volumes from Yangtze River Delta ports and pigment logistics automation adoption rates at German automotive suppliers.
Stress conditions across monsoon disruption severity for Gujarat logistics, CDSCO documentation timeline compression, and EU Green Deal recovery rate mandate stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including polypropylene resin price spike duration and reconditioning network integration capital availability. Quarterly review of UN testing laboratory backlog indicators and extended producer responsibility enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market