
 Mexico Flexible Packaging Market | 2026-2036
Mexico Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Flexible Packaging Market Foresight
Food service distribution channels are rewriting procurement patterns across Mexico's packaging supply base. Amcor PLC leverages its continental manufacturing footprint to sustain volume leadership in barrier films for protein packaging. Flexitek de Mexico SA de CV anchors regional supply through its specialized converting operations serving central Mexican processors. Huhtamaki OYJ differentiates via molded fiber and flexible hybrid formats targeting quick-service restaurant chains.
Flexible packaging denotes pliable material constructions—typically multilayer laminations of polyethylene, polypropylene, or foil substrates between 50–200 micrometers—engineered to protect contents from moisture, oxygen, and mechanical damage during distribution and shelf life. Stand-up pouches capture expanding shelf presence in retail formats due to material efficiency and display economics versus rigid alternatives. Polyethylene formulations dominate tonnage flows while foil laminations command premium positioning in pharmaceutical and extended-shelf-life food applications where oxygen transmission rates below 0.1 cc/m²/day prove critical.
SEMARNAT enforces Extended Producer Responsibility frameworks while NOM-161-SEMARNAT governs recyclable packaging content thresholds, collectively pressuring converters toward mono-material designs compatible with existing Mexican mechanical recycling infrastructure. COFEPRIS pharmaceutical packaging standards mandate specific barrier performance and traceability labeling that filter market access for imported flexible formats. Stakeholders must monitor regulatory alignment between state-level waste management programs and federal circular economy mandates to anticipate compliance-driven material transitions.
Market Dynamics
SEMARNAT's Extended Producer Responsibility frameworks are forcing converters to abandon multilayer laminations in favor of mono-material polyethylene constructions compatible with Mexico's mechanical recycling infrastructure.
Growth Catalysts
- Food and beverage processors:Protein packers in the Bajío corridor are specifying high-barrier foil laminations with oxygen transmission rates below 0.1 cc/m²/day for extended shelf-life applications.
- NOM-161-SEMARNAT:Recyclable content thresholds are accelerating adoption of polyethylene-rich formulations that flow through existing Mexican recycling streams without separation.
- Quick-service restaurant chains:Molded fiber and flexible hybrid formats are capturing drive-thru and delivery packaging volumes as operators eliminate rigid alternatives.
Market Restraints
- Resin import dependency:Polyethylene and polypropylene feedstock concentrates in US Gulf Coast petrochemical complexes, exposing Mexican converters to dollar-denominated input volatility and cross-border logistics friction.
- Mechanical recycling limitation:Existing Mexican infrastructure cannot process adhesives and print inks common in legacy flexible formats, creating technical lock-in for virgin material use.
- COFEPRIS pharmaceutical standards:Barrier performance and traceability labeling mandates filter market access for imported flexible formats, constraining supplier diversification.
Strategic Opportunities
- Querétaro-Guanajuato industrial corridor:Underpenetrated converting capacity in central Mexico offers brownfield expansion sites proximate to food processing clusters.
- Stand-up pouch formats:Material efficiency and shelf-display economics are displacing rigid containers in retail formats across mass-market grocery channels.
- State-level waste management alignment:Anticipated harmonization between federal circular economy mandates and local collection programs could unlock post-consumer recycled content certification premiums.
Industry Challenges
- Mono-material engineering talent:Scarcity of polymer scientists capable of reformulating barrier properties without aluminum foil layers limits converter R&D velocity.
- Legacy equipment retrofitting:Extrusion and laminating lines engineered for multilayer constructions require capital-intensive reconfiguration to process recyclable mono-material streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Flexible Packaging Market |
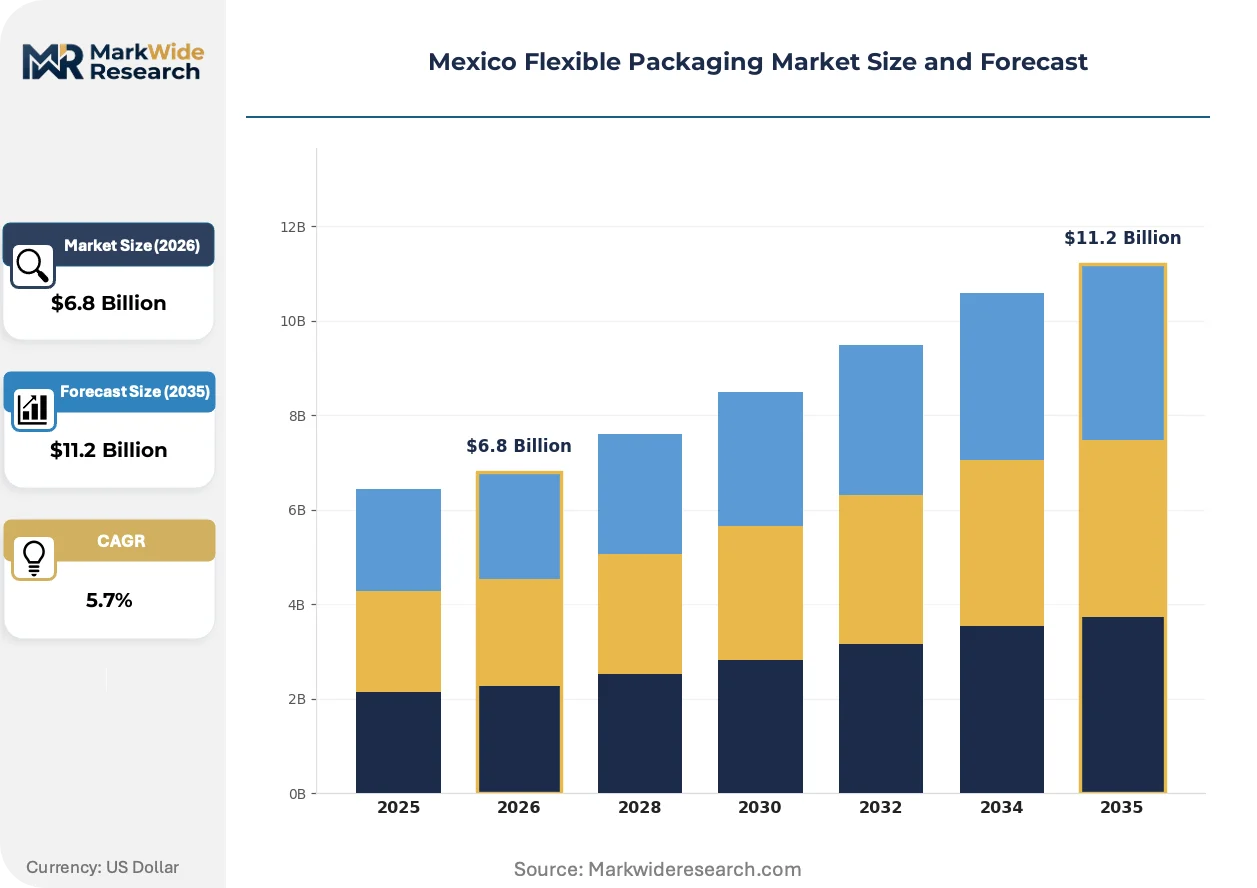
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Rollstock, Bags, Wraps Material: Polyethylene, Polypropylene, Paper, Foil Application: Food Beverages, Personal Care, Pharmaceuticals, Household End User: Retail, eCommerce, Food Service, Manufacturing |
| Companies Covered | Transcontinental Inc., Flexitek de Mexico SA de CV, Amcor PLC, Sonoco Products Company, Huhtamaki OYJ, Constantia Flexibles, Sealed Air Corporation, Printpack Inc., Berry Global Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Flexible Packaging Market Shifts & Advancements
Digital printing and inline quality systems are compressing run lengths and enabling mass customization across Mexico's converting base. Converter investments cluster in the Bajío region where food processor proximity justifies technology refresh cycles.
Digital flexographic printing systems are digitizing artwork changeovers and reducing plate costs for short-run specialty batches. Seasonal sauce and salsa packers in Jalisco and Michoacán are adopting these systems to compress lead times from weeks to days. The technology is digitizing procurement patterns as brands shift from annual volume contracts to on-demand replenishment models.
SEMARNAT's evolving NOM-161 standards are mandating design-for-recycling protocols that disqualify conventional adhesive laminations from shelf placement. Converters must validate mono-material constructions through third-party certification bodies to maintain retail channel access. Pharmaceutical and extended-shelf-life food segments face the steepest compliance timelines given their historical reliance on foil barrier layers.
Food service distributors are consolidating procurement authority previously dispersed across regional restaurant operators. National buying cooperatives are displacing fragmented local supplier relationships with centralized flexible packaging tenders specifying volume commitments and sustainability credentials. This concentration is most visible in Mexico City and Monterrey metropolitan zones where quick-service chain density supports dedicated distribution infrastructure.
Mexico Flexible Packaging Market Segmentation
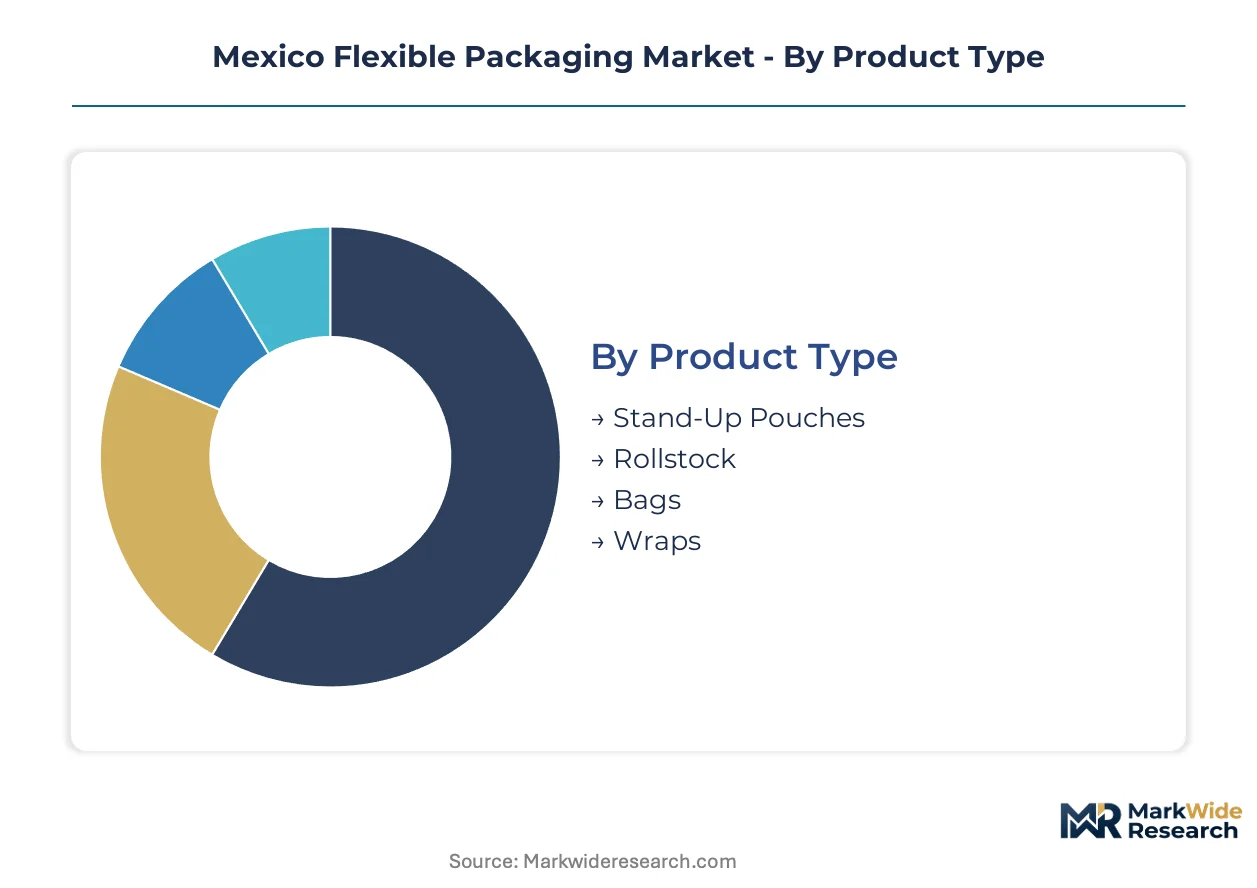
Segmentation in Mexico's flexible packaging market reveals how regulatory pressure and supply chain geography fragment purchasing behavior across converters. Material specifications and format choices increasingly correlate with proximity to Bajío food processors and SEMARNAT compliance timelines rather than traditional cost optimization alone.
Product Type:
Format selection tracks directly with shelf presence requirements and distribution channel economics across Mexican retail and food service networks.
- Stand-Up Pouches:Multilayer laminations with resealable zipper mechanisms and bottom gusset construction enable vertical shelf display while reducing material tonnage versus rigid alternatives. Protein packers in Guanajuato specify high-barrier variants with foil layers for extended shelf-life meat products distributed through refrigerated supply chains.
- Rollstock:Continuous web formats feed form-fill-seal operations at high-volume food processors, with polyethylene-rich constructions dominating thermoforming applications for cheese and deli meat packaging. Jalisco dairy cooperatives consume significant rollstock volumes for portion-controlled cheese formats exported to US Southwest markets.
- Bags:Side-seal and bottom-seal constructions serve bulk commodity packaging for rice, beans, and pet food distributed through traditional retail channels.
- Wraps:Cling film and stretch wrap formats concentrate in fresh produce distribution centers and protein processing facilities requiring oxygen-permeable yet moisture-retentive barriers.
Rollstock holds installed capacity. Stand-up pouches are rotating up the share rankings.
Material:
Substrate composition determines recyclability certification eligibility under evolving NOM-161-SEMARNAT thresholds and mechanical processing compatibility.
- Polyethylene:Low-density and linear low-density formulations dominate tonnage flows due to heat-seal performance and existing Mexican recycling stream compatibility. Mono-material polyethylene constructions are capturing share from multilayer alternatives as converters redesign for SEMARNAT compliance without aluminum foil barriers.
- Polypropylene:Cast and oriented films deliver stiffness and clarity for snack food and bakery applications where shelf visibility drives purchase decisions. Michoacán snack processors specify biaxially oriented polypropylene for tortilla chip bags requiring moisture barriers and print surface quality.
- Paper:Fiber-based substrates with polyethylene extrusion coatings serve quick-service restaurant packaging and limited retail applications where biodegradability messaging supports brand positioning.
- Foil:Aluminum laminations command premium positioning in pharmaceutical blister packs and extended-shelf-life retort applications where oxygen transmission rates below 0.1 cc/m²/day remain non-negotiable despite recycling incompatibility.
Polyethylene maintains volume leadership. Polypropylene is climbing the fastest as snack processing expands.
Application:
End-use verticals impose distinct barrier specifications, regulatory filing requirements, and procurement concentration patterns across Mexican converting demand.
- Food Beverages:The largest application vertical spans fresh protein, processed dairy, sauces, and beverages with specifications ranging from breathable films for respiring produce to high-barrier retort pouches for shelf-stable meals. COFEPRIS filing requirements for food contact materials filter supplier qualification to domestic converters with established compliance documentation.
- Personal Care:Sachets and flexible tubes for shampoo, conditioner, and lotion formats require chemical resistance and squeeze durability distinct from food-grade constructions. Monterrey-based personal care manufacturers drive demand for laminated tube stock with offset and flexographic decoration capabilities.
- Pharmaceuticals:Blister foils, strip packs, and sachet formats for solid dose and powder medications face COFEPRIS barrier performance and traceability labeling mandates that constrain imported flexible format market access.
- Household:Detergent pods, cleaning wipes, and air care refills utilize multilayer films with chemical resistance and child-resistant opening features where regulatory pressure lags food and pharmaceutical segments.
Food Beverages commands capacity allocation. Personal Care is gaining share fastest as northern Mexico manufacturing clusters expand.
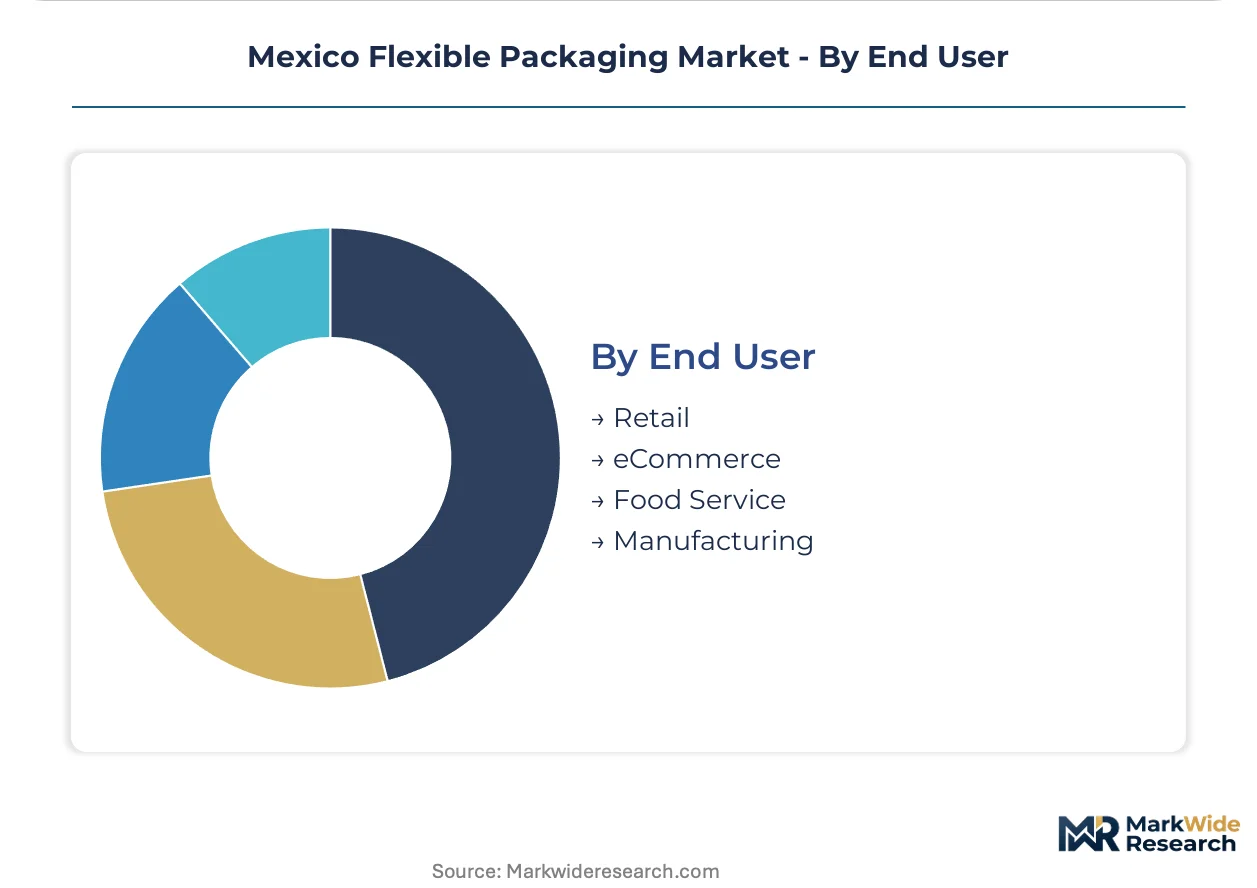
End User:
Customer type determines order scale, customization requirements, and sustainability credential demands across Mexican flexible packaging procurement.
- Retail:Mass-market grocery and club store channels specify high-volume standardized formats with print minimums that favor large-scale converting operations. Walmart de México and Chedraui centralize flexible packaging procurement through annual tenders with sustainability scorecard components.
- eCommerce:Direct-to-consumer fulfillment requires damage-resistant formats with reduced material profiles to optimize dimensional weight shipping economics. Mexico City logistics hubs are driving specification of padded mailers and lightweight pouches versus corrugated alternatives.
- Food Service:Quick-service restaurant chains and institutional catering operations are consolidating previously fragmented procurement through national buying cooperatives specifying volume commitments and recyclable format requirements.
- Manufacturing:Industrial processors of components and subassemblies utilize flexible formats for in-process protection and shipment, with specifications driven by export packaging standards rather than Mexican retail regulations.
Retail dominates installed demand. Food Service is rotating up the share rankings as chain consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lázaro Cárdenas deepwater port on Michoacán's Pacific coast anchors Mexico's flexible packaging distribution network, connecting Bajío converting capacity to Asian resin suppliers and U.S. export markets through multimodal rail corridors.
Bajío Region
Querétaro and Guanajuato host the densest concentration of food processing plants demanding high-barrier flexible formats. SEMARNAT's Extended Producer Responsibility frameworks apply federal compliance thresholds uniformly across these states. León's automotive supplier parks are cross-pollinating polymer engineering talent into nearby converting operations.
Nuevo León
Monterrey metropolitan manufacturers drive personal care and household flexible packaging procurement at scale. State-level waste management programs here operate ahead of federal harmonization timelines, creating early-mover advantages for certified recyclable formats. Apodaca industrial parks concentrate extrusion and laminating capacity serving northern Mexico's retail corridor.
Jalisco
Guadalajara anchors dairy and sauce processing clusters specifying portion-controlled flexible formats for U.S. Southwest export markets. COFEPRIS food contact material filings concentrate among Jalisco-based converters with established compliance documentation. Tlaquepaque's converting corridor specializes in short-run digital flexographic applications for seasonal specialty batches.
Mexico City Metro
The Valley of Mexico logistics hub concentrates e-commerce fulfillment demand for lightweight damage-resistant pouches and padded mailers. Federal district environmental regulations enforce stricter recyclable content verification than surrounding states. Toluca's manufacturing belt supplies food service distributors consolidating procurement for quick-service restaurant chains.
Northern Border States
Chihuahua and Tamaulipas maquiladora operations import U.S.-origin rollstock for immediate conversion and re-export under USMCA tariff preferences. Dollar-denominated resin pricing transmits volatility directly to border-zone converters without peso hedging buffers. Reynosa and Ciudad Juárez plants specialize in industrial protective packaging for cross-border automotive component shipments.
Mexico Flexible Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and niche converting. The Mexico flexible packaging market structures around three distinct tiers: multinational film producers with continental manufacturing footprints, regional converters with specialized equipment for barrier laminations, and local specialists serving single-state food processor clusters. Dominant competitive moves center on brownfield capacity expansion in underpenetrated central Mexican corridors and strategic partnerships between resin distributors and mid-scale converters seeking supply security.
Within the multinational tier, Amcor PLC and Huhtamaki OYJ occupy positions defined by continental scale and format diversification respectively. Flexitek de Mexico SA de CV exemplifies the regional specialist archetype, anchoring supply relationships through proximity to Bajío food processing clusters. These three entities collectively represent the competitive spectrum: global platform breadth, hybrid format innovation, and regional supply-chain integration.
| Leading Market Players |
|---|
| Transcontinental Inc. |
| Flexitek de Mexico SA de CV |
| Amcor PLC |
| Sonoco Products Company |
| Huhtamaki OYJ |
| Constantia Flexibles |
| Sealed Air Corporation |
| Printpack Inc. |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
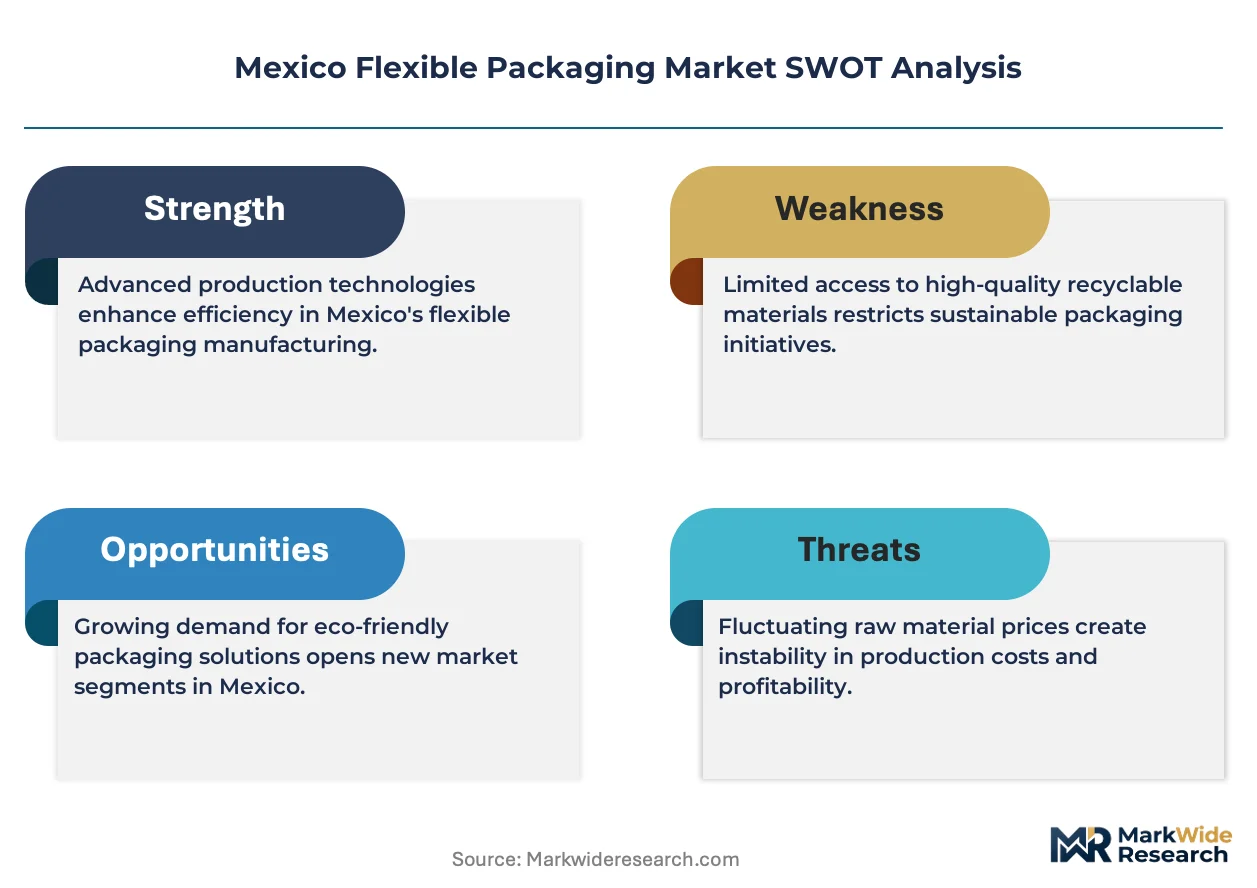
US Gulf Coast petrochemical complexes concentrate polyethylene and polypropylene feedstock supply, anchoring margin capture upstream while Mexican converters absorb dollar-denominated volatility and cross-border logistics friction downstream. NOM-161-SEMARNAT compliance timelines are compressing procurement cycles as buyers prioritize certified mono-material constructions over cost-optimized multilayer alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates foil-laminated pharmaceutical formats from polyethylene-rich food packaging and commodity rollstock. Price differentiation hinges on barrier performance certification and volume scale, with protein packers in Guanajuato negotiating annual offtake commitments against spot-market resin exposure. Cost compression in standard-tier polyethylene constructions is intensifying because converters pass through dollar-linked feedstock swings without hedging buffers. Small-scale Jalisco dairy cooperatives exhibit highest price sensitivity, while multinational quick-service chains absorb premium positioning for recyclable hybrid formats.
Supply Chain Analysis
Extended payment terms from Bajío food processors to regional converters are straining working capital, prompting supply-chain finance facilities backed by resin distributors. Raw material flows draw from US Gulf Coast petrochemical complexes, Korean biaxially-oriented polypropylene suppliers, and domestic Mexican recyclers. Single-source vulnerability concentrates in US-origin polyethylene resin subject to cross-border tariff exposure and rail corridor congestion. Distribution runs through Lázaro Cárdenas port multimodal networks connecting Asian substrate suppliers to central Mexican converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material engineering expertise represents the critical capability gap constraining converter R&D velocity as SEMARNAT deadlines approach. Polymer scientists capable of reformulating barrier properties without aluminum foil layers command scarcity premiums that reshape competitive access.
For Market Incumbents: Build certification moats around third-party NOM-161 validation to lock out unqualified imports. Deepen backward integration into post-consumer recycled polyethylene sourcing through partnerships with Jalisco collection cooperatives. SEMARNAT compliance timelines threaten multilayer-dependent competitors lacking reformulation capacity. For New Entrants and Emerging Players: Establish a beachhead in digital flexographic short-run specialty batches serving Tlaquepaque seasonal sauce packers. Underpenetrated converting capacity in the Querétaro-Guanajuato corridor offers brownfield expansion proximate to protein processing clusters. Go-to-market leverage rests on compressed lead times from weeks to days versus legacy annual contract models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale Bajío converters lacking capital for extrusion line retrofits. Five-to-ten year viability hinges on SEMARNAT enforcement intensity and mechanical recycling infrastructure buildout. Monitor state-level waste management harmonization signals as inflection indicators for post-consumer recycled content premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material R&D Partnership | Polymer science collaboration with León automotive supplier parks accelerates barrier reformulation without foil layers. |
| Brownfield Capacity Expansion | Underutilized Querétaro industrial sites capture food processor proximity advantages with lower capital intensity. |
| Digital Flexographic Investment | Inline quality systems compress Jalisco specialty batch lead times from weeks to days. |
| Recycled Content Certification | Third-party NOM-161 validation unlocks Walmart de México and Chedraui sustainability scorecard compliance. |
| Resin Supply Security Agreement | Long-term offtake contracts with US Gulf Coast producers hedge dollar-denominated input volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with converter operations directors, food processor procurement leads, SEMARNAT compliance officers, and resin distribution channel managers; and secondary validation through Mexican customs trade records, COFEPRIS food contact material filings, SEC 10-K disclosures from multinational packaging firms, and NOM-161 regulatory drafts. Bottom-up capacity assessments across Bajío converting clusters were triangulated against top-down demand estimates from protein packer and dairy cooperative volume disclosures.
Forecast inputs incorporated material format migration curves, SEMARNAT enforcement probability scenarios, and resin price elasticity coefficients across the projection horizon. Segmentation modeling spanned product type, substrate composition, application vertical, and end-user procurement concentration patterns. CAGRs were derived from slope-intercept analysis of historical tonnage flows and regulatory-driven substitution elasticities. Industry-specific inputs included mechanical recycling infrastructure deployment timelines and quick-service restaurant chain consolidation trajectories.
Stress conditions across peso-dollar exchange rate bands, resin import tariff regimes, and NOM-161 compliance deadline scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and collection infrastructure buildout. Macroeconomic deviation, regulatory delay, or breakthrough barrier coating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market