
 China Flexible Packaging Market | 2026-2036
China Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Flexible Packaging Market Analysis
Market Context
Capital-intensity divergence between integrated film producers and downstream converters is reorganizing competitive tiers in China's flexible packaging sector. Jiangsu Caihua Packaging Group leverages captive blown-film capacity to sustain margin control across polyethylene pouch lines. Huangshan Novel Co. Ltd. specializes in high-barrier laminates for pharmaceutical clients, occupying a premium niche with distinct technical accreditation requirements.
Technical Definition and Structural Segments
China flexible packaging comprises multi-layer polymer films, foils, and papers engineered into pouches, bags, sleeves, and roll stock, typically measuring 50–250 microns in total caliper with oxygen transmission rates below 0.1 cc/m²/day for barrier grades. These structures protect shelf-stable and perishable goods from moisture, oxygen, and light across ambient, chilled, and frozen supply chains. Stand-up pouches lead volume in food & beverage applications where spouted convenience formats command higher unit economics than flat alternatives. Barrier-featured materials extract disproportionate value from pharmaceutical and premium snack segments where polyester-aluminum-polyethylene laminates dominate compliance-sensitive demand.
Regulatory Frame and Outlook
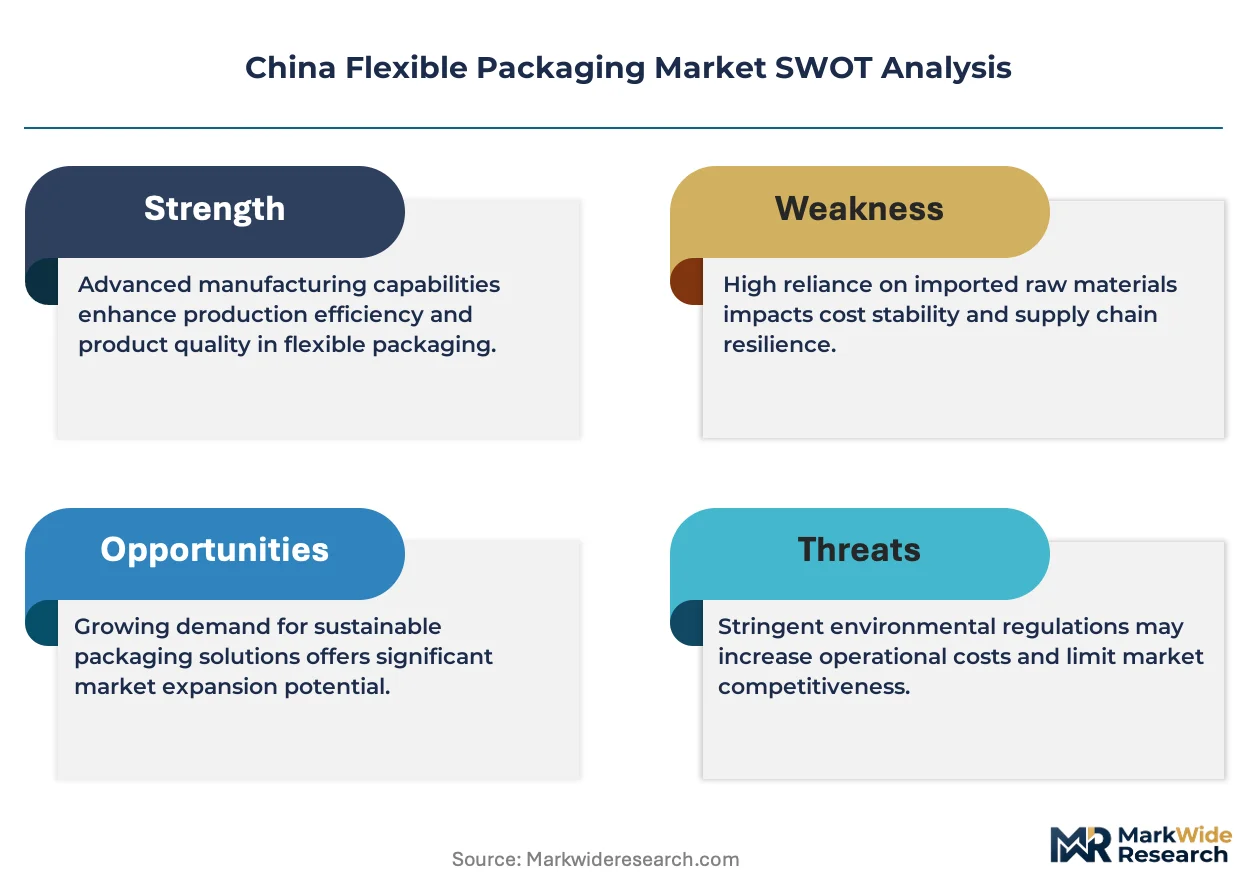
MIIT enforces GB standards for food-contact plastics while MEE implements dual carbon goals that restrict solvent-based adhesive use and mandate recyclability disclosures on consumer labels. SAMR's evolving packaging waste rules are shifting procurement criteria toward mono-material polyethylene and polypropylene structures that align with mechanical recycling infrastructure. Stakeholders must monitor whether provincial environmental bureaus accelerate Extended Producer Responsibility enforcement ahead of national timelines.
Market Dynamics
Dual carbon mandates from MEE are forcing solvent-based adhesive phaseouts while Yangtze River Delta film producers consolidate blown-film capacity to defend margin structures against resin volatility.
Growth Catalysts
- Ready-to-eat meal pouch formats:Food & Beverage brands are expanding spouted stand-up pouches for single-serve convenience, displacing rigid containers in ambient and chilled distribution.
- GB standard harmonization:MIIT's updated food-contact material rules are accelerating compliance upgrades across converter networks, filtering sub-scale suppliers from pharmaceutical barrier contracts.
- Jiangsu province cluster density:Manufacturing concentration around Shanghai enables same-day resin-to-pouch logistics, compressing working capital cycles for export-oriented converters.
Market Restraints
- Polyethylene resin import dependency:Feedstock exposure to Middle Eastern and US Gulf supply disruptions creates margin squeeze during freight rate spikes.
- Blown-film equipment oligopoly:German and Japanese machinery suppliers command 18-24 month delivery timelines, constraining capacity expansion for mid-tier converters.
- Aluminum foil laminate substitution ceiling:High-barrier pharmaceutical specifications resist full polymer replacement despite MEE pressure on multi-material structures.
Strategic Opportunities
- Western China logistics corridors:Chongqing-Chengdu manufacturing zones offer lower labor and energy costs for converters serving ASEAN export markets via rail-sea intermodal.
- Mono-material polyethylene compliance:SAMR's evolving EPR timelines create first-mover advantage for converters with validated mechanical recycling stream compatibility.
- Digital printing convergence:HP Indigo and Fujifilm inkjet platforms enable sub-5,000 unit customization for regional snack brands, collapsing traditional cylinder engraving lead times.
Industry Challenges
- Barrier film metallization expertise gap:Vacuum deposition technicians with pharmaceutical-grade cleanroom experience command premium wages that mid-scale converters struggle to absorb.
- Legacy solvent adhesive inventory stranding:MEE enforcement timelines create working capital impairment for converters holding polyurethane adhesive stockpiles ahead of compliance deadlines.
- Multi-layer structure delamination testing:SAMR's accelerated aging protocols for food-contact laminates extend certification cycles by 8-12 weeks, compressing new product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flexible Packaging Market |
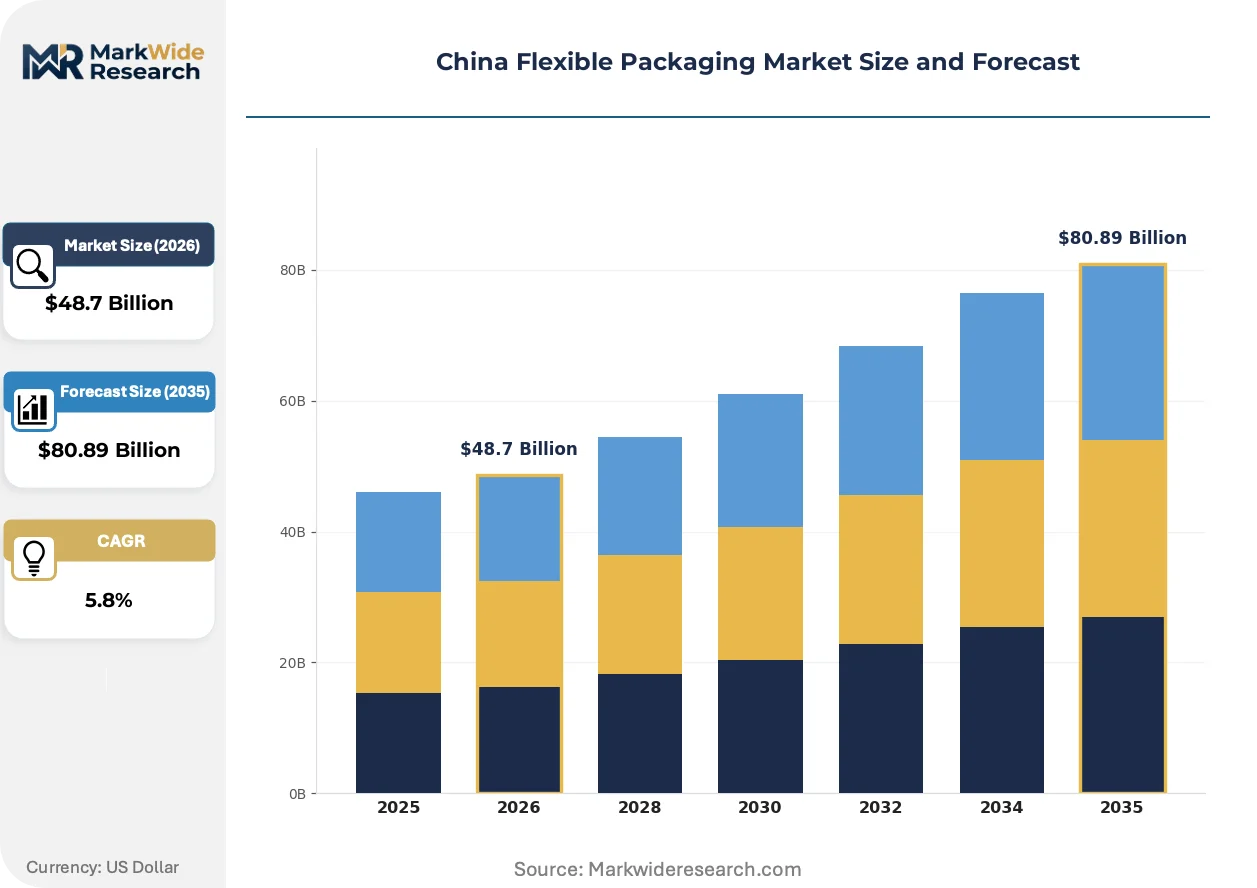
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Lay Flat Bags, Shrink Sleeves, Flexible Roll Stock Material: Polyethylene, Polypropylene, Polyester, Nylon End User: Food & Beverage, Personal Care, Pharmaceuticals, Home Care Feature: Recyclable, Barrier, Biodegradable, Custom Printed |
| Companies Covered | Shanghai AirPaq Packaging Technology Development Co. Ltd., Jiangsu Shenkai High-Tech Packaging Co. Ltd., Huangshan Novel Co. Ltd., Jiangsu Litel Green Packaging Co. Ltd., Hangzhou Hansin New Packing Material Co. Ltd., Zhejiang Chengde Packaging Technology Co. Ltd., Wuxi Huaxing Pharmaceutical Packaging Co. Ltd., DQ PACK, Jiangsu Caihua Packaging Group Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flexible Packaging Market Emerging Trajectories
Digital workflow integration and material science advances are compressing development cycles while regulatory chemistry restrictions reshape equipment investment priorities across converter tiers.
Water-based adhesive technology is miniaturizing drying energy requirements while maintaining bond strength parity with solvent systems. Tier-one converters in Zhejiang province are retrofitting existing laminators with infrared-assisted drying modules. This equipment adaptation is miniaturizing the capital barrier for mid-scale competitors seeking MEE compliance without greenfield investment.
MIIT's GB 4806 series updates for food-contact plastics are mandating substance-by-substance migration testing documentation. Converter quality departments are restructuring supplier qualification protocols to capture resin additive chain-of-custody records. Pharmaceutical pouch specialists face the steepest compliance burden, with some redirecting R&D budgets from barrier innovation to regulatory dossier preparation.
Direct-to-brand digital procurement platforms are fragmenting traditional distributor relationships in the Yangtze River Delta. Regional snack manufacturers now specify pouch structures through online configurators, bypassing converter sales engineering for standard barrier grades. This channel compression is most pronounced in Jiangsu province, where same-day sample delivery from cluster producers has normalized expectation-setting for specification turnaround.
China Flexible Packaging Market Segmentation
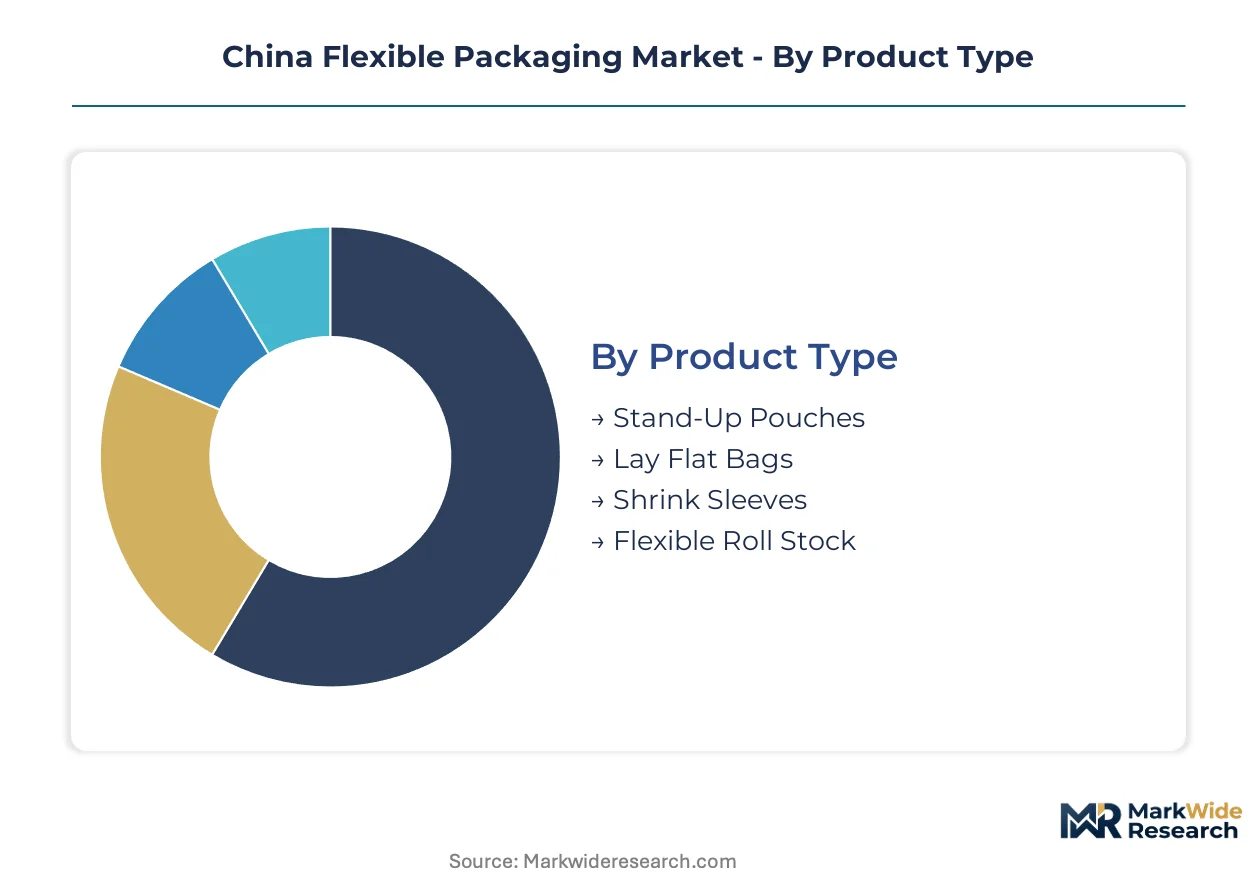
Channel configuration across China's flexible packaging sector follows distinct material-format pairings that determine margin capture and regulatory exposure. Each segment category carries specific route-to-market implications that shape converter investment priorities and downstream brand procurement patterns.
Product Type:
Stand-up pouches and lay flat bags move through divergent distribution channels, with spouted convenience formats commanding direct brand relationships while commodity roll stock flows through regional distributors.
- Stand-Up Pouches:Multi-layer structures with bottom gussets and optional spouts, typically 80–180 microns total caliper. Demand concentrates in ready-to-eat meal lines from Yangtze River Delta food brands where spouted formats displace rigid containers in chilled distribution. Spouted variants extract premium positioning through convenience functionality that flat alternatives cannot replicate.
- Lay Flat Bags:Two- or three-side seal configurations serving bulk commodity and frozen protein segments. Jiangsu province converters dominate this volume tier through same-day logistics to Shanghai export corridors, compressing working capital cycles for mid-scale buyers.
- Shrink Sleeves:Polyethylene terephthalate glycol or oriented polystyrene films engineered for 360-degree container decoration. Beverage and personal care brands in Guangdong province drive adoption for shelf differentiation.
- Flexible Roll Stock:Unconverted multi-layer webs supplied to downstream form-fill-seal operations. Pharmaceutical contract manufacturers in Zhejiang source barrier-grade laminates for cleanroom pouch fabrication.
Stand-up pouches dominate installed base. Spouted convenience variants are where expansion concentrates.
Material:
Cost tier stratification separates commodity polyolefins from engineered barrier polymers, with SAMR recyclability mandates accelerating mono-material procurement shifts.
- Polyethylene:Linear low-density and metallocene grades forming sealant layers and mono-material pouch bodies. Yangtze River Delta converters are retrofitting lines for all-PE structures ahead of Extended Producer Responsibility enforcement.
- Polypropylene:Cast and oriented films delivering stiffness and clarity for snack and confectionery windows. Demand clusters in high-transparency applications where polyester substitution faces cost barriers.
- Polyester:Biaxially oriented polyethylene terephthalate providing print surface and mechanical strength in laminate structures. Pharmaceutical barrier specifications resist full polymer replacement despite MEE pressure on multi-material formats.
- Nylon:Polyamide films delivering puncture resistance and oxygen barrier for vacuum-packed proteins and retort applications. Premium pricing reflects feedstock exposure to caprolactam supply volatility.
Polyethylene commands volume leadership. Mono-material compliance grades are climbing the fastest.
End User:
Application-specific performance requirements fragment converter capabilities, with pharmaceutical and food-contact segments demanding distinct accreditation portfolios.
- Food & Beverage:Ambient, chilled, and frozen supply chain protection spanning snack, dairy, and ready-to-eat categories. Spouted pouch expansion from Shanghai-based brands is displacing rigid containers in convenience retail channels.
- Personal Care:Sachets and stand-up formats for shampoo, conditioner, and skincare samples. Digital printing convergence enables sub-5,000 unit customization for regional brand test markets.
- Pharmaceuticals:High-barrier laminates with oxygen transmission rates below 0.1 cc/m²/day for moisture-sensitive dosage forms. MIIT's GB 4806 migration testing mandates are extending certification cycles for new structure approvals.
- Home Care:Refill pouches and measured-dose packaging for detergent and surface cleaner concentrates. Concentrate formats reduce shipping volume versus ready-to-use alternatives.
Food & Beverage anchors installed capacity. Pharmaceuticals is where technical premium extraction concentrates.
Feature:
Regulatory compliance and sustainability positioning are bifurcating procurement criteria between certified recyclable streams and legacy barrier performance.
- Recyclable:Mono-material polyethylene or polypropylene structures validated for mechanical recycling streams. SAMR's evolving EPR timelines create first-mover advantage for converters with third-party certification.
- Barrier:Metallized, coextruded, or laminated structures blocking oxygen, moisture, and light. Pharmaceutical and premium snack specifications maintain aluminum foil laminate dependency despite MEE multi-material restrictions.
- Biodegradable:PLA, PBAT, or starch-based films targeting industrial composting infrastructure. Limited adoption reflects collection infrastructure gaps and cost premiums versus conventional polymers.
- Custom Printed:Rotogravure, flexographic, or digital decoration enabling brand differentiation. HP Indigo and Fujifilm inkjet platforms collapse traditional cylinder engraving lead times for regional snack manufacturers.
Barrier features dominate current value extraction. Recyclable certification is where regulatory-driven replacement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province converters command pricing leverage over western China peers due to same-day logistics access to Shanghai export corridors. This asymmetry widens during polyethylene resin volatility when coastal inventory turns protect margin structures inland competitors cannot replicate.
Yangtze River Delta
Spouted stand-up pouch demand from Shanghai-based ready-to-eat meal brands is displacing rigid containers in chilled distribution. MIIT enforces GB standards for food-contact plastics across this manufacturing cluster. Jiangsu province film producers consolidate blown-film capacity to defend margins against resin price swings.
Pearl River Delta
Guangdong beverage and personal care brands drive shrink sleeve adoption for shelf differentiation in humid retail environments. MEE dual carbon goals restrict solvent-based adhesive use across converter networks. Shenzhen and Dongguan manufacturing zones specialize in digital printing integration for sub-5,000 unit customization.
Beijing-Tianjin-Hebei
Pharmaceutical contract manufacturers in Hebei source high-barrier laminates for moisture-sensitive dosage forms. SAMR's evolving packaging waste rules shift procurement toward mono-material structures. Tianjin port logistics enable resin import hedging strategies unavailable to interior competitors.
Sichuan-Chongqing
Western China logistics corridors offer lower labor and energy costs for converters serving ASEAN export markets via rail-sea intermodal. Provincial environmental bureaus monitor Extended Producer Responsibility enforcement timelines. Chongqing manufacturing zones attract mid-tier converters fleeing coastal cost pressures.
Shandong Peninsula
Qingdao-based converters supply frozen protein segments with puncture-resistant nylon laminates for vacuum-packed distribution. GB standard harmonization accelerates compliance upgrades across regional converter networks. Yantai film producers specialize in metallized barrier grades for premium snack specifications.
China Flexible Packaging Market Vendor Landscape
Concentration sits with integrated film producers and downstream converters reorganizing competitive tiers through capital-intensity divergence. Jiangsu-based groups leverage captive blown-film capacity to sustain margin control across polyethylene pouch lines. Huangshan-area specialists occupy premium niches with distinct technical accreditation requirements. Strategic moves center on capacity consolidation and mono-material line retrofitting ahead of SAMR enforcement timelines.
Among Jiangsu-based integrated producers, Jiangsu Caihua Packaging Group Co. Ltd. and Jiangsu Shenkai High-Tech Packaging Co. Ltd. exemplify the capital-intensive archetype controlling upstream film supply. Huangshan Novel Co. Ltd. represents the barrier-specialist tier where pharmaceutical-grade cleanroom capabilities command technical premiums. Shanghai AirPaq Packaging Technology Development Co. Ltd. anchors the innovation-focused segment serving ready-to-eat meal brands with spouted convenience formats. These three archetypes—integrated volume, technical premium, and format innovation—capture distinct value pools across the compliance-driven market restructuring.
| Leading Market Players |
|---|
| Shanghai AirPaq Packaging Technology Development Co. Ltd. |
| Jiangsu Shenkai High-Tech Packaging Co. Ltd. |
| Huangshan Novel Co. Ltd. |
| Jiangsu Litel Green Packaging Co. Ltd. |
| Hangzhou Hansin New Packing Material Co. Ltd. |
| Zhejiang Chengde Packaging Technology Co. Ltd. |
| Wuxi Huaxing Pharmaceutical Packaging Co. Ltd. |
| DQ PACK |
| Jiangsu Caihua Packaging Group Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Blown-film capacity consolidation across Jiangsu province creates asymmetric scale economies that simultaneously compress unit cost floors and amplify pricing power for coastal integrated producers versus inland competitors. This concentration dynamic feeds directly into procurement patterns, as Yangtze River Delta converters leverage same-day resin-to-pouch logistics to command premium positioning while western China peers absorb higher working capital cycles.
Pricing Analysis
The customization-premium spread between configured-to-order spouted pouches and standard lay-flat bags runs wide in this market. Three-tier pricing structure across premium, standard, and economy levels reflects barrier certification grade and volume scale, with pharmaceutical-grade laminates extracting technical premiums that commodity polyethylene cannot approach. Pricing pressure stems from MEE-mandated solvent adhesive phaseouts forcing equipment retrofit costs onto converters. Mid-tier export-oriented buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Middle Eastern and US Gulf polyethylene resin suppliers fluctuate with Shanghai port congestion and Red Sea container availability. Raw material supply concentrates in Saudi Arabia, South Korea, and Singapore for feedstock, with German and Japanese machinery suppliers controlling blown-film equipment. Single-source vulnerability sits with 18-24 month equipment delivery timelines from these machinery oligopolists. Distribution runs through Yangtze River Delta converter clusters serving Shanghai export corridors, with rail-sea intermodal emerging for western China-ASEAN lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's flexible packaging sector faces high-growth disruption as MEE dual carbon mandates and SAMR Extended Producer Responsibility timelines simultaneously force material chemistry transitions and reward first-mover recyclability certification.
For Market Incumbents: Secure mono-material polyethylene line retrofitting ahead of provincial EPR enforcement timelines. Defend margin structures by deepening captive blown-film capacity in Jiangsu province to buffer resin volatility. Prioritize pharmaceutical barrier accreditation maintenance against MIIT migration testing documentation requirements that filter sub-scale competitors. For New Entrants and Emerging Players: Lead with digital printing-enabled customization for regional snack brands in Sichuan-Chongqing manufacturing zones. Target the sub-5,000 unit short-run segment where HP Indigo and Fujifilm platforms collapse traditional cylinder engraving lead times. Pursue direct-to-brand procurement platform relationships that bypass established distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors barrier-specialist converters with pharmaceutical-grade cleanroom capabilities over commodity volume players. Long-term viability hinges on validated mechanical recycling stream compatibility as SAMR enforcement tightens. The signal to watch is provincial environmental bureau acceleration of EPR timelines ahead of national schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofitting | MEE compliance deadlines force capital allocation toward all-PE structures ahead of SAMR enforcement. |
| Digital Printing Platform Integration | HP Indigo and Fujifilm inkjet adoption collapses lead times for regional brand customization orders. |
| Pharmaceutical Barrier Certification | MIIT GB 4806 migration testing requirements extend dossier preparation cycles for new structure approvals. |
| Western China Manufacturing Footprint | Chongqing-Chengdu zones offer labor and energy cost arbitrage for ASEAN export market service. |
| Direct-to-Brand Procurement Channel | Online configurator platforms fragment traditional distributor relationships in Jiangsu province clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, SAMR packaging waste rule drafts, and Yangtze River Delta customs trade data. Primary interviews captured converter operations directors, pharmaceutical packaging procurement managers, resin supply planners, and blown-film equipment distributors. Secondary validation drew from MEE dual carbon policy circulars, GB standard harmonization notices, and polyethylene import statistics. Bottom-up demand modeling triangulates against top-down value chain aggregation.
Segmentation dimensions modeled span product type, material chemistry, end-use application, and feature certification across the projection horizon. CAGRs derive from installed base expansion rates, replacement demand cycles, and regulatory-driven material substitution elasticities. Forecast inputs incorporate MEE enforcement timeline scenarios and SAMR EPR rollout phasing assumptions.
The analysis sits within stated boundaries; outcomes outside MEE dual carbon adherence or SAMR EPR acceleration would require recalibration. Forecasts reflect documented assumptions around resin price stability and machinery delivery reliability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Canada Flexible Packaging Market