
 ASEAN Flexible Packaging Market | 2026-2036
ASEAN Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Flexible Packaging Market Analysis
Processed food exports from Thailand and Vietnam are restructuring procurement patterns across the ASEAN flexible packaging supply base. Amcor Limited leverages its regional film extrusion network to supply multinational brand owners with high-barrier laminates. Mondi Group anchors European sustainability specifications into Southeast Asian production lines through technical partnerships. Prepack Thailand Co., Ltd. competes on speed-to-market for domestic snack and instant noodle brands.
ASEAN flexible packaging comprises polymer-based or fiber-based materials engineered to conform to product shape during filling, typically specified in thickness ranges of 50 to 150 microns and manufactured through blown film extrusion, cast film, or adhesive lamination processes. Its primary purpose is to protect perishable goods from moisture, oxygen, and light while minimizing material weight versus rigid alternatives. Stand-up pouches now capture disproportionate margin pools as brand owners in personal care and household care shift from bottles to pouch formats for e-commerce compatibility. Plastic substrates still dominate volume, though biodegradable materials are gaining trial adoption among premium food and beverage exporters responding to EU Green Deal due diligence requirements.
Thailand's Roadmap on Plastic Waste Management, Indonesia's National Action Plan on Marine Plastic Debris, and Singapore's Resource Sustainability Act collectively mandate extended producer responsibility and recyclability disclosures that reshape converter R&D priorities. BIS-equivalent national standards bodies in Malaysia and Vietnam are aligning testing protocols for food-contact laminates with ASEAN harmonization frameworks. Stakeholders must monitor how rapidly Indonesia implements its planned packaging waste collection targets and whether Philippine FDA updates to food-contact notification procedures accelerate or delay new material qualifications.
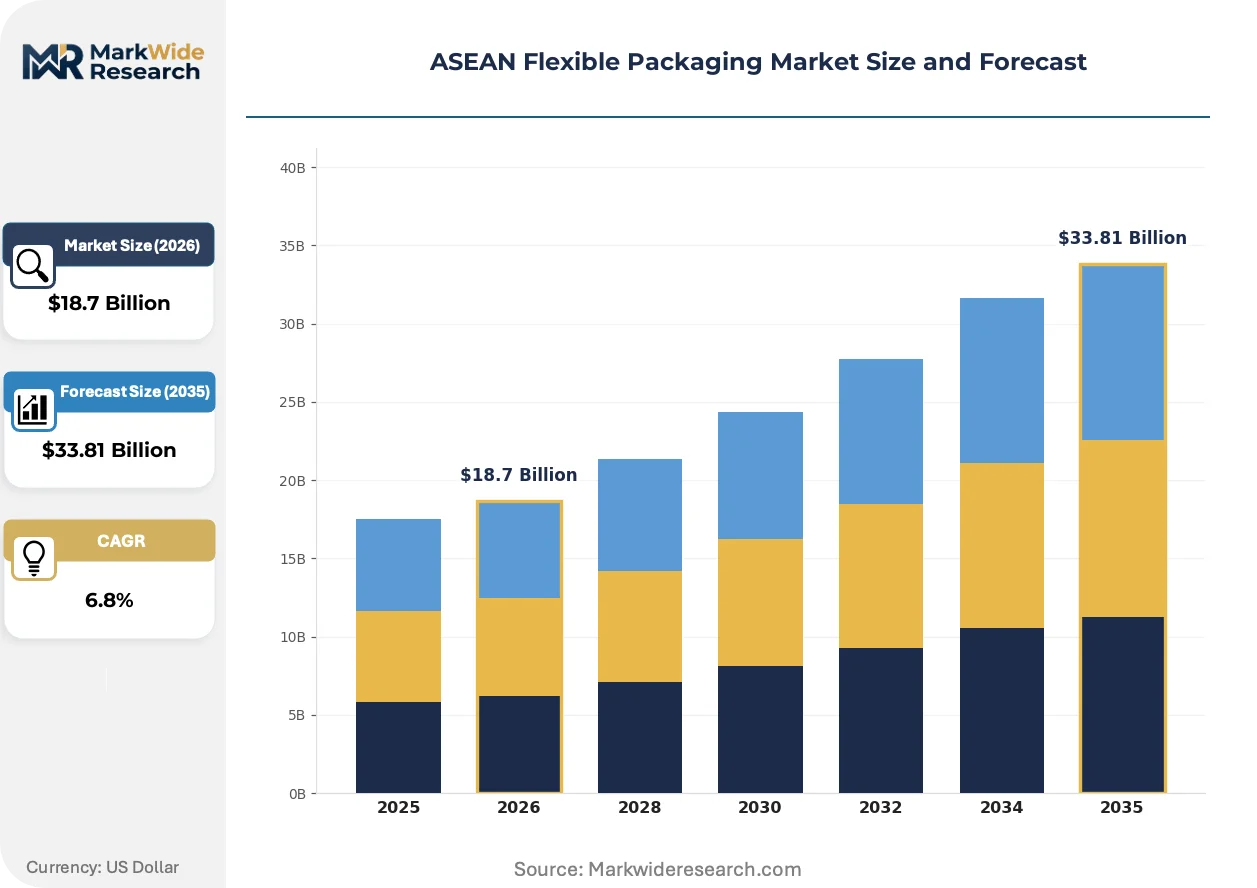
Market Dynamics
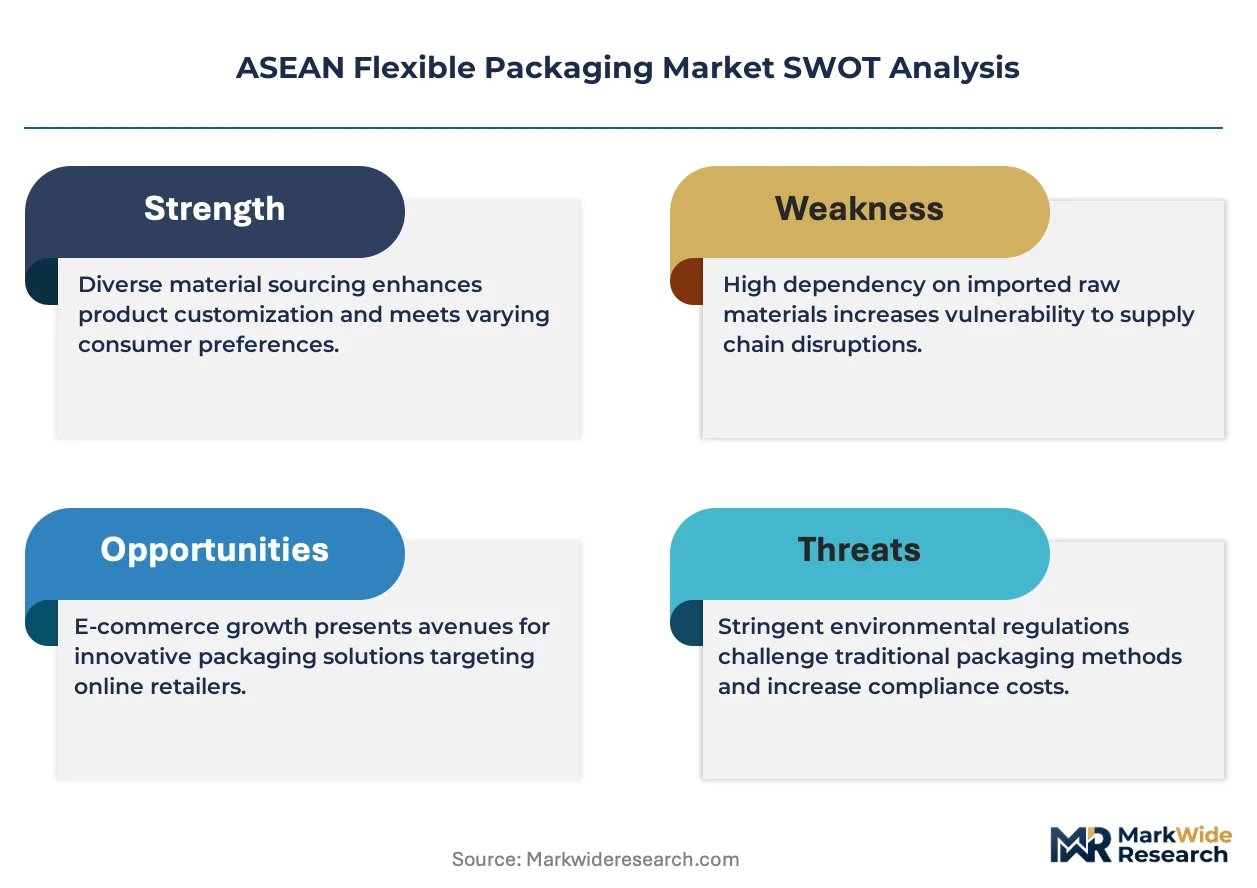
Thailand's Roadmap on Plastic Waste Management is forcing converters to requalify entire material portfolios, compressing development cycles and redistributing margin pools toward recyclate-compatible barrier technologies.
Growth Catalysts
- Retortable laminate demand:Food and beverage processors across Vietnam and Indonesia are specifying high-barrier structures for ambient-stable curry and seafood exports to EU markets.
- Indonesia's National Action Plan on Marine Plastic Debris:Extended producer responsibility mandates are pulling investment into collection infrastructure and mechanically recycled film feedstocks.
- Digital printing adoption:Short-run personalization for e-commerce snack bundles is expanding addressable SKU economics for mid-tier converters.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock exposure ties converter margins to naphtha-cracker economics in Singapore and Thailand.
- Barrier film supply concentration:Specialty EVOH and polyamide supply chains center on Japanese and Korean chemical producers, creating import dependency.
- Biodegradable performance gaps:PLA and PBAT blends currently fail oxygen-barrier specifications for retort applications above 121°C.
Strategic Opportunities
- Philippine modern retail expansion:Supermarket penetration in Cebu and Davao is pulling in pre-formed pouch formats previously concentrated in Metro Manila.
- Singapore's Resource Sustainability Act:Mandatory recyclability labeling creates first-mover advantage for converters with certified mono-material structures.
- Flexographic-digital hybrid workflows:Convergence of plate-based and inkjet systems enables cost-efficient versioning across 5,000-50,000 unit runs.
Industry Challenges
- Food-contact notification timelines:Philippine FDA qualification procedures for novel laminates extend 18-24 months, delaying commercialization.
- Recyclate contamination control:Post-consumer film sorting infrastructure remains underdeveloped across Indonesia's outer islands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Flexible Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Packaging, Flexible Pouches, Shrink Sleeves, Stand-Up Pouches End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Care Material: Plastic, Paper, Biodegradable, Aluminum Technology: Rotogravure, Flexography, Digital Printing, Lamination |
| Companies Covered | Mondi Group, Sonoco Products Company, Amcor Limited, AR Packaging Group, Constantia Flexibles Gmbh, Prepack Thailand Co., Ltd., Sealed Air Corporation, Huhtamaki Oyj, Berry Plastics, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Flexible Packaging Market Emerging Trajectories
Converters are rebuilding production lines around sustainability-verified output and digital-enabled responsiveness, collapsing traditional tradeoffs between barrier performance and end-of-life credentials.
Mono-material polyethylene laminates with plasma-deposited silicon oxide coatings are expanding into retort pouch applications previously reserved for aluminum-foil composites. Premium seafood exporters in Thailand are piloting these structures for EU-bound tuna and crabmeat packs. The technology is expanding into shelf-stable segments by eliminating multi-polymer separation requirements at recycling facilities.
Singapore's Resource Sustainability Act mandates extended producer responsibility for packaging waste, compelling brand owners to fund collection and recycling infrastructure. Converters must now submit recyclability disclosures to the National Environment Agency prior to product launch. Personal care and household segments are responding fastest, reformulating multilayer bottles into all-PE pump pouches.
E-commerce fulfillment requirements are compressing packaging development cycles from 12 months to 6-8 weeks for snack and beverage trial SKUs. Brand owners in Jakarta and Bangkok are bypassing traditional distributor networks to commission direct converter relationships for flash promotions. This pattern is most visible in Indonesia's instant noodle and coffee sachet segments, where TikTok-commerce volumes are reshaping minimum order quantities and print versioning economics.
ASEAN Flexible Packaging Market Segmentation
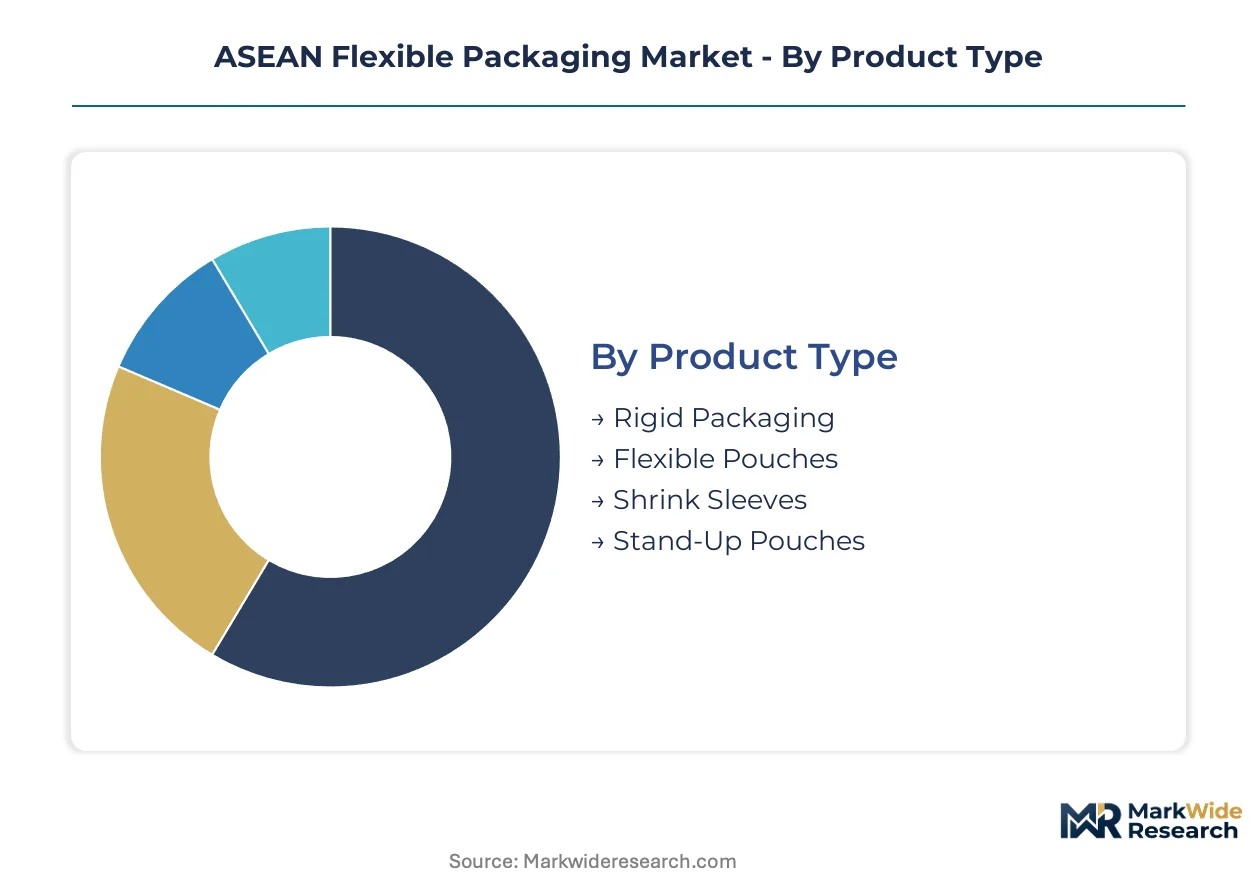
Flexible packaging procurement across Southeast Asia fragments along performance specifications, regulatory compliance tiers, and channel velocity requirements. Each segmentation axis reveals distinct margin pools and capability barriers that converters must navigate to capture share in Indonesia's modern retail expansion and Thailand's sustainability-mandated material transitions.
Product Type:
Structural format determines barrier engineering complexity and end-of-life recyclability pathways.
- Stand-Up Pouches:Multi-layer laminates with bottom gusset construction enable vertical shelf presentation and reduced shipping cube versus rigid alternatives. Indonesian instant noodle and coffee brands in Jakarta and Surabaya are pulling capacity toward high-speed form-fill-seal compatibility for e-commerce bundle formats.
- Flexible Pouches:Flat pillow or three-side-seal configurations in 80-120 micron thickness ranges dominate ambient snack and confectionery applications. Vietnamese seafood exporters specify these for IQF shrimp and pangasius fillets bound for EU retail private label programs.
- Shrink Sleeves:PET-G or OPS substrates with 360-degree graphics coverage conform to contoured bottles and cans through heat-tunnel application. Thailand's beverage sector deploys these for seasonal promotional runs requiring rapid artwork changeovers.
- Rigid Packaging:Thermoformed trays and lidding films for modified atmosphere applications in fresh produce and ready-meal segments. Singapore's supermarket chains specify these for premium meat and seafood counter presentations.
Mature deployment sits with Flexible Pouches. Newer deployment is concentrated in Stand-Up Pouches.
End Use Industry:
Application-specific barrier requirements and regulatory exposure reshape converter qualification priorities.
- Food & Beverage:Retortable laminates with aluminum oxide or silicon oxide coatings achieve 0.1 cc/m2/day oxygen transmission rates for 121°C sterilization cycles. Thai curry paste and Vietnamese fish sauce exporters require these for ambient shelf stability in tropical distribution.
- Personal Care:All-polyethylene pump pouches with flip-top dispensing fitments replace rigid bottles for shampoo and body wash formats. Singapore's Resource Sustainability Act recyclability mandates accelerate mono-material transitions in this segment.
- Pharmaceuticals:Blister lidding foils and child-resistant pouch structures meeting ASEAN harmonized stability testing protocols. Philippine FDA notification timelines extend material qualification cycles for novel barrier combinations.
- Household Care:Stand-up spout pouches for liquid detergent and fabric softener with chemical resistance to surfactant loading. Indonesian modern retail expansion in secondary cities pulls pre-formed pouch demand beyond Metro Manila concentration.
Volume concentration remains with Food & Beverage. Steepest expansion trajectory appears in Personal Care.
Material:
Substrate selection balances barrier performance, mechanical integrity, and end-of-life compliance costs.
- Plastic:Multi-polymer laminates combining PE, PP, PET, EVOH, and polyamide layers through adhesive or extrusion lamination. Indonesia's National Action Plan on Marine Plastic Debris forces requalification toward recyclate-compatible mono-material structures.
- Biodegradable:PLA, PBAT, and starch-based blends targeting home and industrial composting certifications. Premium food exporters responding to EU Green Deal due diligence requirements pilot these for short-shelf-life applications below 80°C.
- Paper:Fiber-based substrates with extruded PE or bio-based barrier coatings for dry goods and confectionery. Thailand's Roadmap on Plastic Waste Management pushes trial adoption in bakery and snack segments.
- Aluminum:Foil laminates in 7-12 micron gauges for absolute light and oxygen barrier in pharmaceutical and premium food retort applications. Supply concentration among Japanese and Korean metal rolling mills creates import dependency for ASEAN converters.
Current volume dominance sits with Plastic. Regulatory pressure is accelerating Biodegradable trial volumes.
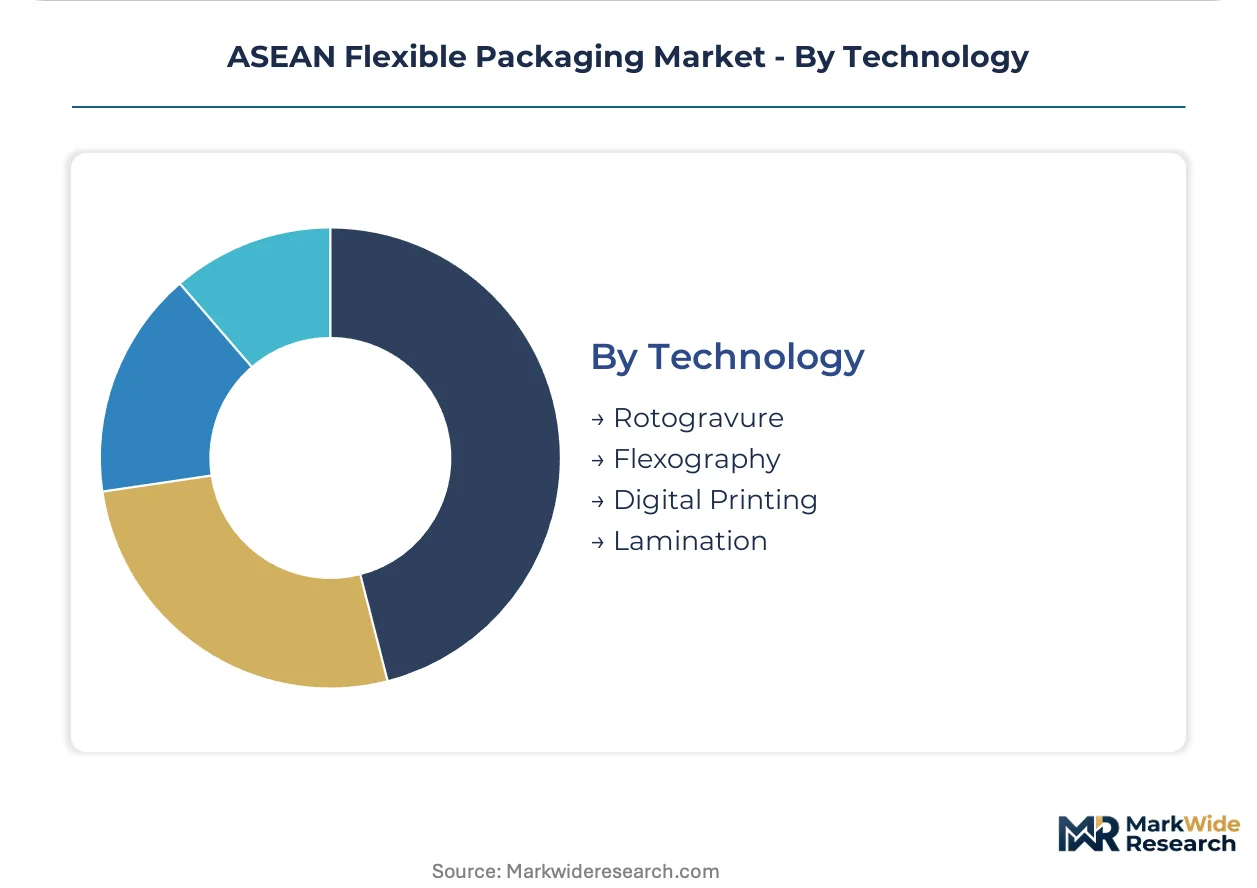
Technology:
Print and converting process selection determines run-length economics, color consistency, and versioning agility.
- Flexography:Central impression cylinder presses with solvent-based or water-based inks achieve 175+ line screen resolution at speeds exceeding 300 meters per minute. Mid-tier Indonesian converters deploy these for 50,000+ unit snack and noodle pouch runs.
- Digital Printing:Single-pass inkjet systems with UV-curable or water-based formulations eliminate plate costs and enable lot-size-one personalization. TikTok-commerce flash promotions in Jakarta and Bangkok compress development cycles to 6-8 weeks through direct converter relationships.
- Rotogravure:Electronically engraved cylinders deliver photographic quality and precise ink laydown for premium export packaging. Thai seafood and Vietnamese coffee brands specify these for EU and Japanese retail shelf presence.
- Lamination:Solventless, solvent-based, and extrusion bonding processes combine dissimilar substrates into functional barrier structures. Thailand's Ministry of Industry tightened volatile organic compound regulations push solventless system adoption.
Established capacity concentrates in Flexography. Capacity expansion is climbing fastest in Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor in Thailand and Batam's free trade zone in Indonesia concentrate flexible packaging investment through tax holidays and import duty exemptions for converting equipment.
Indonesia
Urbanization in Jakarta and Surabaya drives demand for stand-up pouches in instant noodle and coffee sachet segments. The National Action Plan on Marine Plastic Debris mandates extended producer responsibility for packaging waste collection. Converters in Bekasi and Tangerang industrial zones are installing digital printing lines to serve TikTok-commerce flash promotions with 6-8 week development cycles.
Thailand
Processed food exports of curry paste and seafood require retortable laminates with aluminum oxide barrier coatings for EU market access. The Roadmap on Plastic Waste Management forces requalification of material portfolios toward mono-material recyclability. Rayong and Chonburi provinces host the densest concentration of film extrusion and lamination capacity serving multinational brand owners.
Vietnam
Seafood exporters in Ho Chi Minh City specify high-barrier flexible pouches for IQF shrimp and pangasius fillets bound for European private label programs. BIS-equivalent national standards alignment with ASEAN harmonization frameworks accelerates food-contact laminate qualifications. Industrial parks in Binh Duong and Dong Nai provinces attract investment in rotogravure printing for premium export packaging.
Singapore
The Resource Sustainability Act creates first-mover advantage for converters with certified mono-material structures in personal care and household segments. Mandatory recyclability labeling to the National Environment Agency precedes product launch approvals. Tuas and Jurong industrial zones concentrate technical partnerships anchoring European sustainability specifications into regional production lines.
Philippines
Supermarket penetration in Cebu and Davao pulls pre-formed pouch demand beyond Metro Manila concentration. Philippine FDA notification timelines for novel laminates extend 18-24 months, delaying commercialization of advanced barrier structures. Laguna and Cavite provinces host mid-tier converters competing on speed-to-market for domestic snack brands.
ASEAN Flexible Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational material science firms commanding high-barrier laminate supply to processed food exporters while domestic converters capture velocity-driven personal care and e-commerce snack volumes. The vendor base organizes into three tiers: integrated film extruders with regional scale, mid-tier specialists in digital-enabled short runs, and local job shops serving traditional rotogravure contracts. Consolidation pressure concentrates among converters lacking recyclate-compatible barrier technology or mono-material certification capabilities. Geographic expansion through technical partnerships and capacity additions in Indonesian industrial zones represent the dominant competitive moves.
Among European-anchored multinationals, Mondi Group and Amcor Limited exemplify the integrated material science archetype with regional film extrusion networks supplying multinational brand owners. Prepack Thailand Co., Ltd. occupies a position within the domestic specialist tier, competing on speed-to-market for Thai snack and instant noodle brands. These three companies represent distinct strategic postures: sustainability-anchored technical partnership models, scale-driven barrier laminate supply, and velocity-focused local responsiveness.
| Leading Market Players |
|---|
| Mondi Group |
| Sonoco Products Company |
| Amcor Limited |
| AR Packaging Group |
| Constantia Flexibles Gmbh |
| Prepack Thailand Co., Ltd. |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Berry Plastics |
| Others |
Supply Flow & Price Mechanics
Multinational brand owners in processed food exports command pricing power through long-term offtake contracts, while domestic snack converters compete on spot-market resin procurement and short-run digital print agility. This buyer concentration bifurcation splits the market into contract-anchored premium tiers and velocity-driven spot tiers with divergent margin structures.
Pricing Analysis
Short lead-time premiums of 15-25% apply to digital-printed stand-up pouches for TikTok-commerce flash promotions, while spot inventory of commodity PE laminates trades at discounts to contract benchmarks. Three-tier pricing structure across premium barrier laminates, standard multi-polymer films, and economy-grade commodity substrates reflects certification grade and volume scale differentiation. Pricing pressure stems from naphtha-cracker feedstock volatility in Singapore and Thailand. Domestic instant noodle brands exhibit highest price sensitivity; EU-bound seafood exporters show lowest sensitivity due to barrier performance requirements.
Supply Chain Analysis
Food-contact laminate qualification under ASEAN harmonization frameworks gates supplier access to multinational brand owner procurement lists. Raw material supply concentrates in Thailand, Indonesia, and Vietnam for film extrusion, while specialty EVOH and polyamide feedstocks draw from Japanese and Korean chemical producers. Resin price volatility and import dependency on barrier polymers constitute primary supply chain risk. Distribution runs through converter-direct relationships for e-commerce velocity SKUs and distributor networks for traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN flexible packaging sits in a technology-transition phase where mono-material barrier coatings displace aluminum-foil composites in retort applications. Plasma-deposited silicon oxide technology is replacing legacy multi-polymer laminates in premium seafood export segments.
For Market Incumbents: To counter digital-native entrants capturing TikTok-commerce volumes, Amcor Limited and Mondi Group should accelerate flexographic-digital hybrid workflow deployment in Indonesian industrial zones. Mono-material certification investment under Singapore's Resource Sustainability Act creates channel control leverage against recyclate-incompatible competitors. For New Entrants and Emerging Players: Indonesia's National Action Plan on Marine Plastic Debris in Java opens a window for mechanically recycled film feedstock specialists to capture extended producer responsibility-mandated collection infrastructure contracts. Target Bekasi and Tangerang industrial zones with speed-to-market positioning for domestic snack brand direct relationships. For Investors and Strategic Acquirers: The window for entry favors mid-tier converters with digital printing capability and mono-material certification. Long-term viability hinges on recyclate-compatible barrier technology ownership rather than scale alone. Watch Indonesia's packaging waste collection target implementation velocity as inflection indicator for feedstock security.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Program | Singapore's Resource Sustainability Act mandates recyclability disclosures prior to National Environment Agency product launch approvals. |
| Digital Printing Capacity Expansion | Flexographic-digital hybrid workflows enable 6-8 week development cycles for Jakarta TikTok-commerce flash promotions. |
| Recyclate Feedstock Integration | Indonesia's National Action Plan on Marine Plastic Debris pulls investment into collection infrastructure and mechanically recycled film streams. |
| Barrier Technology Partnership | Plasma-deposited silicon oxide coating alliances anchor European sustainability specifications into Thai seafood export production lines. |
| Regional Industrial Zone Footprint | Thailand's Eastern Economic Corridor tax holidays concentrate film extrusion and lamination capacity in Rayong and Chonburi provinces. |
Methodological Framework
Independent corroboration across converter plant managers, procurement leads at multinational brand owners, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Primary interviews combined with secondary validation from customs/trade data, ASEAN harmonization framework documentation, national plastic waste management roadmaps, and SEC filings of listed packaging multinationals. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical resin price cycles and regulatory implementation timelines structured the forecast window across the analysis window. Segmentation dimensions modeled include product type, end-use industry, material substrate, and print technology tier. CAGRs derived from elasticity-adjusted demand projections incorporating urbanization rates, modern retail penetration, and e-commerce channel growth. Forecast inputs include naphtha-cracker operating rates and food-contact notification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for biodegradable barrier materials would alter the outlook. Forecasts reflect assumptions regarding Indonesia's collection infrastructure buildout velocity and Philippine FDA harmonization progress. A model refresh is warranted upon material change in EU Green Deal due diligence enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market