
 Middle East and Africa Flexible Plastic Packaging Market | 2026-2036
Middle East and Africa Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Flexible Plastic Packaging Market Insights
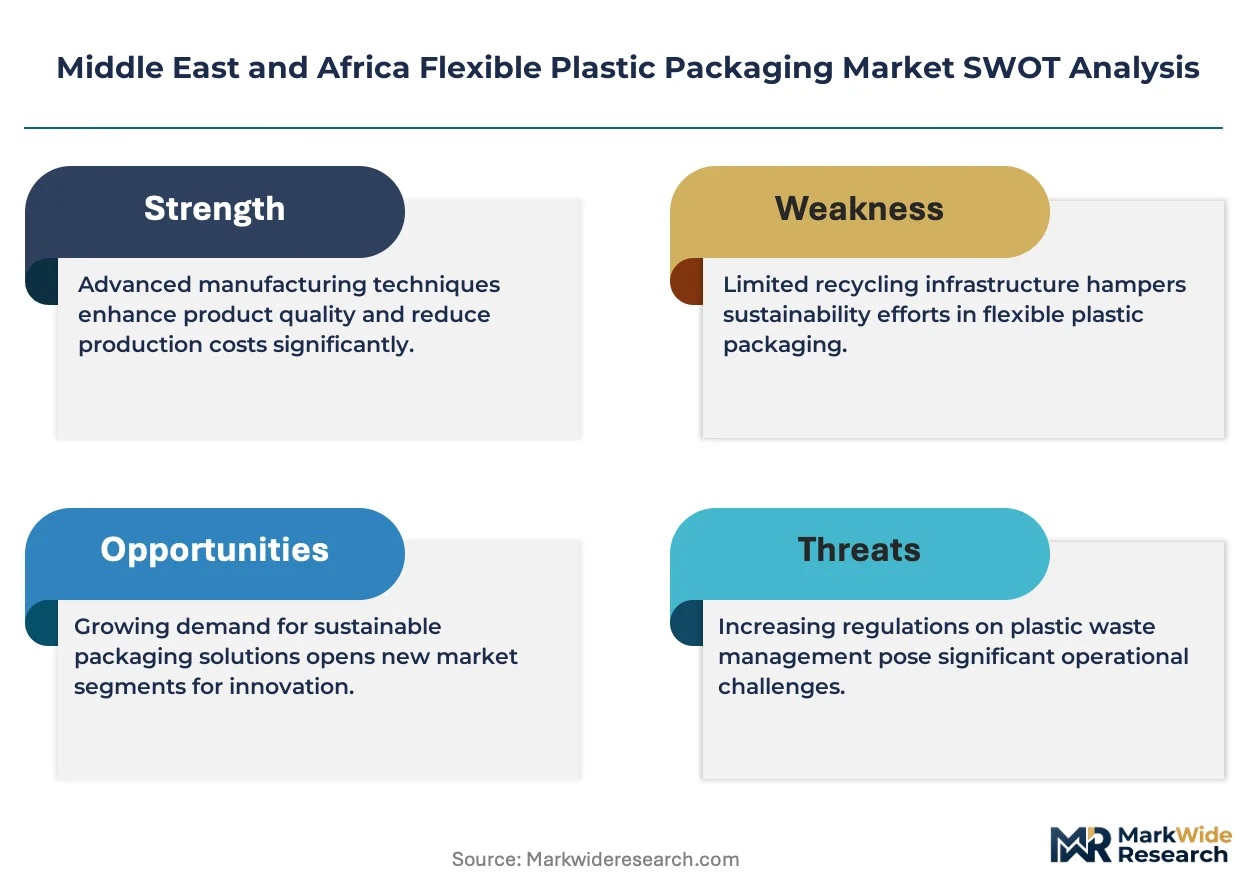
CE marking alignment for food-contact materials is redrawing competitive access across the Middle East and Africa. Amcor PLC leverages its multi-layer extrusion capabilities to sustain supply contracts with multinational food brands operating in the Gulf. Napco National anchors Saudi Arabia's domestic packaging supply through integrated film production. Hotpack Packaging Industries LLC dominates the UAE's quick-service restaurant and hospitality segment with specialized pouch formats.
Flexible plastic packaging comprises polymer-based films, laminates, and formed containers typically below 250 microns in thickness, engineered to conform to product shape while providing moisture, oxygen, and light barriers through coextrusion or adhesive lamination processes. The primary purpose centers on extending shelf stability and reducing transportation cost for perishable and consumer goods. Polyethylene formulations lead volume production due to cost scalability and heat-seal performance, while biodegradable polymers represent the fastest-expanding material class as Gulf regulators tighten disposal requirements. Stand-up pouches capture premium margin pools in personal care and branded food segments across South Africa and Nigeria.
Saudi Food and Drug Authority standards and South Africa's National Regulator for Compulsory Specifications govern food-contact migration limits and labeling protocols, forcing reformulation of PVC-containing structures. ECHA REACH substance restrictions increasingly influence import acceptance at UAE and Egyptian ports, elevating testing costs for non-compliant suppliers. Stakeholders must monitor the divergence between Gulf harmonization initiatives and country-specific enforcement timelines to calibrate regional manufacturing investments.
Market Dynamics
Retail modernization across Gulf Cooperation Council states is compressing traditional wholesale channels and forcing packaging converters to reconfigure production lines for shorter-run, higher-SKU formats demanded by supermarket chains.
Growth Catalysts
- SFDA food-contact standards:Saudi Arabia's migration limit protocols are accelerating replacement of PVC-based structures with polyethylene and polypropylene laminates, opening reformulation contracts for compliant suppliers.
- Quick-service restaurant expansion:UAE and Saudi Arabia's foodservice chains are specifying high-barrier pouches for sauce and condiment portion packs, pulling specialized coextrusion capacity into the region.
- Biodegradable polymer R&D:Polyhydroxyalkanoate formulations are achieving cost parity in pilot volumes, positioning early adopters for Gulf disposal mandate compliance.
Market Restraints
- Ethylene feedstock volatility:Naphtha price swings tied to Brent crude fluctuations compress margin predictability for polyethylene-dominant producers.
- Masterbatch import concentration:Colorant and additive supply routes through European ports create lead-time vulnerability for Egyptian and Nigerian converters.
- Multi-layer recycling incompatibility:Current mechanical reprocessing infrastructure cannot separate adhesive-laminated structures, limiting post-consumer collection economics.
Strategic Opportunities
- Nigeria's underpenetrated retail:Formal supermarket penetration below fifteen percent leaves white space for pre-packaged food formats as cold-chain infrastructure expands.
- Pharmaceutical blister compliance:ECHA-aligned substance restrictions are elevating demand for barrier-certified films in South Africa's generic drug export sector.
- Digital printing convergence:Inkjet deposition onto oriented polypropylene is enabling run-length flexibility that gravure cannot match, unlocking micro-brand contracts.
Industry Challenges
- Coextrusion technician scarcity:Gulf-based converters face recruitment gaps for blown-film line operators capable of calibrating seven-layer barrier structures.
- REACH documentation timelines:ECHA substance notification requirements are extending new material qualification cycles by four to six months for UAE importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Flexible Plastic Packaging Market |
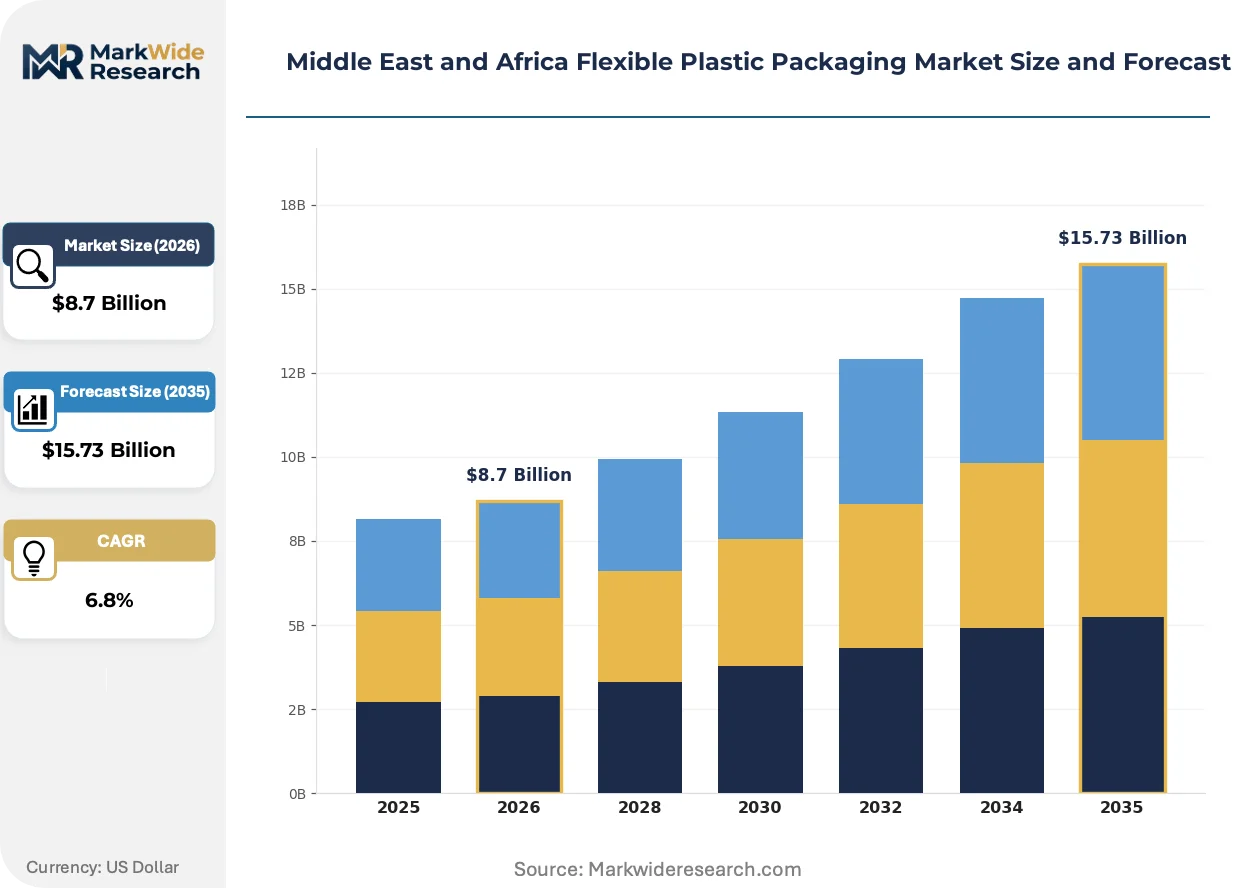
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Wraps, Bags Material: Polyethylene, Polypropylene, PVC, Biodegradable Polymers Application: Food Packaging, Medical Supplies, Personal Care, Electronics Packaging End User: Food & Beverage, Healthcare, Consumer Goods, Industrial |
| Companies Covered | Amcor PLC, Huhtamaki Oyj, Napco National, ENPI Group, Mondi Group, Constantia Flexibles, Hotpack Packaging Industries LLC, Cosmoplast Industrial Company LLC, Integrated Plastics Packaging LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Flexible Plastic Packaging Market Trends and Innovations
Active barrier technologies and digital production workflows are reconfiguring how converters align capacity with fragmenting end-use specifications across the Middle East and Africa.
High-barrier ethylene vinyl alcohol coextrusion is supplanting metallized polyethylene terephthalate in premium snack and coffee applications where microwaveability conflicts with metal detection requirements. Saudi and South African brand owners are specifying these structures for export-oriented production lines. The shift is compressing aluminum vapor deposition equipment investments while expanding tie-layer adhesive formulation demand.
South Africa's National Regulator for Compulsory Specifications is tightening food-contact migration testing protocols for imported laminates, forcing non-African suppliers to establish local certification partnerships. The industrial consequence is a bifurcation between pre-qualified suppliers and those facing port detention risk. Nigerian and Kenyan converters are most affected, accelerating in-house laboratory investment to pre-validate shipments.
Consolidated procurement by Gulf retail chains is compressing supplier bases and unbundling design services from volume manufacturing contracts. Regional supermarket operators are specifying direct-to-converter relationships for private-label packaging, displacing traditional trading-house intermediaries. This pattern is most visible in Dubai and Jeddah, where Carrefour and Lulu formats dominate shelf-space allocation.
Middle East and Africa Flexible Plastic Packaging Market Segmentation
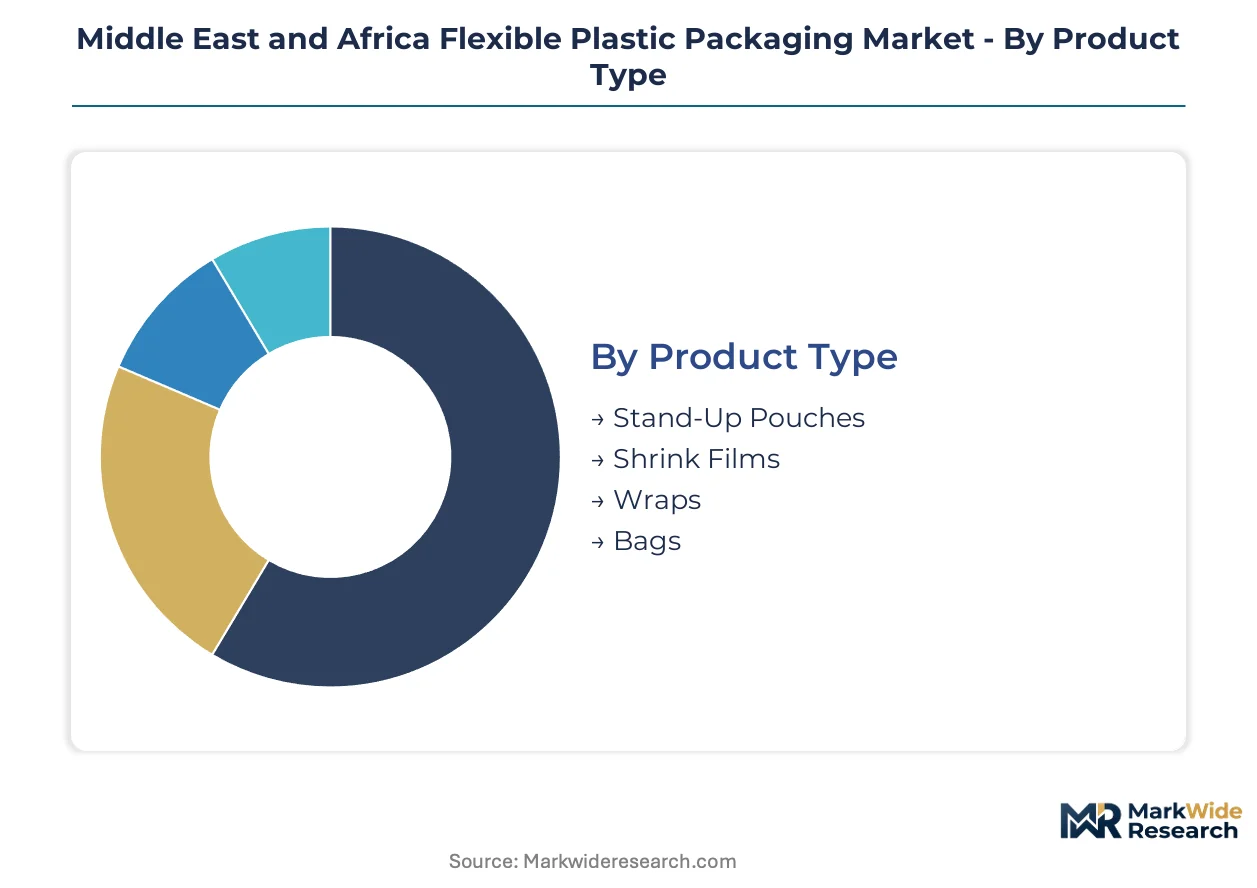
Segmentation across the Middle East and Africa flexible plastic packaging market reveals divergent pressure points from regulatory substitution mandates, feedstock cost volatility, and shifting retail format requirements. Each dimension carries distinct margin and compliance implications for converters operating across Gulf and sub-Saharan supply corridors.
Product Type:
Substitution pressure from rigid formats and paper-based alternatives varies sharply across pouch and film constructions, with microwaveability and barrier performance serving as the primary defense vectors.
- Stand-Up Pouches:Multi-layer laminates with resealable fitments command premium positioning in Saudi Arabia's packaged dates and South African nut exports. Carrefour and Lulu private-label specifications are consolidating procurement around high-barrier EVOH structures that resist paper substitution.
- Shrink Films:Polyethylene-based collation wraps dominate beverage multipacks across UAE's quick-service restaurant supply chains. SFDA migration limit enforcement is accelerating PVC displacement in favor of polyolefin alternatives.
- Wraps:Cling film formulations face intensifying biodegradable polymer competition in Egypt's fresh produce retail transition.
- Bags:Side-seal polyethylene configurations serve commodity bulk packaging with minimal differentiation pressure.
Shrink films anchor the volume base while stand-up pouches gain share at the steepest rate.
Material:
Cost tier stratification separates commodity polyolefins from compliance-driven premium grades, with regulatory timelines dictating reformulation investment sequencing.
- Polyethylene:Linear low-density and metallocene grades constitute the dominant feedstock for blown film extrusion across Nigerian and Kenyan converters. Brent crude volatility compresses margin predictability for naphtha-derived resin consumers.
- Polypropylene:Biaxially oriented films serve snack lamination and label face-stock applications where stiffness and clarity specifications resist polyethylene substitution. South Africa's pharmaceutical blister export sector is specifying barrier-certified PP structures under ECHA-aligned substance restrictions.
- PVC:Cling film and blister pack legacy applications face phased displacement under Gulf harmonization initiatives.
- Biodegradable Polymers:Polyhydroxyalkanoate pilot volumes are achieving cost parity in UAE disposal mandate anticipation.
Polyethylene dominates absolute tonnage while biodegradable polymers are climbing the fastest on regulatory pull-through.
Application:
Application-level margin concentration tracks cold-chain infrastructure maturity and branded retail penetration across national markets.
- Food Packaging:Modified atmosphere laminates for fresh protein and dairy applications concentrate demand in South Africa's supermarket modernization and Saudi Arabia's poultry processing expansion. Shelf-life extension specifications drive seven-layer coextrusion complexity.
- Medical Supplies:Sterile barrier films for syringe and IV packaging face qualification timelines extended by REACH documentation requirements at UAE ports.
- Personal Care:Sachet and pouch formats for shampoo and detergent samples serve Nigeria's informal retail density.
- Electronics Packaging:Anti-static films for component shipping represent a specialized niche with concentrated Gulf demand.
Food packaging commands the revenue base while medical supplies face the steepest compliance-driven qualification delays.
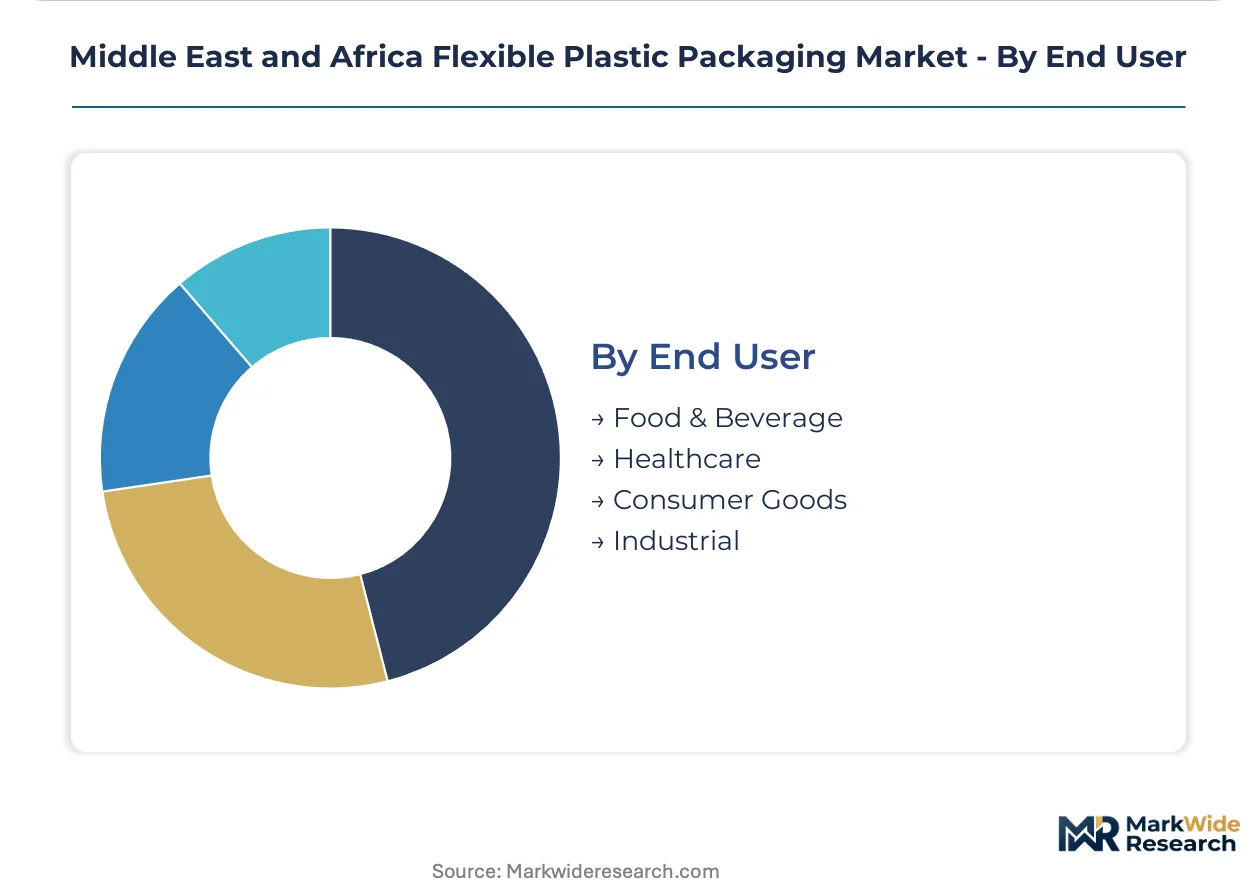
End User:
Customer-type procurement concentration is bifurcating between consolidated retail chain direct relationships and fragmented trading-house intermediation.
- Food & Beverage:Multinational brand owners and regional private-label retailers are unbundling design services from volume manufacturing contracts, forcing converter capability expansion into pre-press and structural design.
- Healthcare:South Africa's generic drug export sector is elevating barrier certification requirements for blister and pouch formats under tightening ECHA-aligned protocols.
- Consumer Goods:Personal care and home care brand owners in Nigeria and Kenya specify high-impact printed films with shorter run lengths enabled by digital inkjet convergence.
- Industrial:Construction chemical and agricultural input packaging demands heavy-duty woven and laminated structures with UV stabilization.
Food and beverage anchors procurement volume while healthcare exhibits the steepest specification escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food brands and Gulf retail chains concentrate procurement decisions in Dubai and Jeddah, while South African supermarket operators anchor sub-Saharan demand patterns.
Saudi Arabia
Domestic poultry processing expansion and packaged dates exports drive modified atmosphere laminate consumption. SFDA migration limit protocols are accelerating PVC displacement in favor of polyethylene and polypropylene structures. Jeddah's industrial corridor hosts integrated film production facilities serving Carrefour and Lulu private-label specifications.
United Arab Emirates
Quick-service restaurant chains and hospitality operators specify high-barrier pouches for sauce and condiment portion packs. MOHAP-aligned import documentation requirements are extending qualification timelines for European masterbatch suppliers. Dubai's Jebel Ali free zone concentrates coextrusion capacity serving regional foodservice distribution.
South Africa
Supermarket modernization and generic pharmaceutical exports generate dual demand streams for barrier-certified films. The National Regulator for Compulsory Specifications is tightening food-contact migration testing protocols for imported laminates. Gauteng province's packaging industrial parks are attracting laboratory investment for pre-validation capabilities.
Nigeria
Informal retail density and expanding cold-chain infrastructure create white space for pre-packaged food formats. The country's national food safety regulator is developing phased compliance timelines for imported packaging materials. Lagos and Abuja metropolitan areas concentrate converter investment in digital printing-enabled sachet production.
Egypt
Fresh produce retail transition and biodegradable polymer mandate anticipation are reshaping cling film specifications. Port authority enforcement of ECHA-aligned documentation is elevating testing costs for non-compliant resin suppliers. Cairo-Alexandria corridor converters are establishing captive laboratory capacity to manage import detention risk.
Middle East and Africa Flexible Plastic Packaging Market Competitive Landscape
Player mix skews toward regional integrated producers and multinational specialists with Gulf supply contracts. Market structure exhibits moderate concentration, with top-tier converters capturing private-label and multinational brand relationships while mid-scale operators serve trading-house intermediation channels. Strategic archetypes include vertically integrated resin-to-film producers, specialized high-barrier coextrusion specialists, and digital printing-enabled short-run converters. Competitive moves center on backward integration into resin compounding and strategic partnerships with retail chains for direct procurement relationships.
Within the multinational specialist tier, Amcor PLC and Mondi Group exemplify scale-driven barrier film capabilities serving cross-border food brand requirements. Among Gulf-based integrated producers, Napco National and Hotpack Packaging Industries LLC occupy positions anchoring domestic supply security for Saudi and UAE retail channels respectively. These named entities represent archetype diversity across global technical standards and regional procurement proximity.
| Leading Market Players |
|---|
| Amcor PLC |
| Huhtamaki Oyj |
| Napco National |
| ENPI Group |
| Mondi Group |
| Constantia Flexibles |
| Hotpack Packaging Industries LLC |
| Cosmoplast Industrial Company LLC |
| Integrated Plastics Packaging LLC |
| Others |
Pricing and Supply Chain Analysis
Ninety-day resin inventory cycles at Jebel Ali free zone converters compress margin buffers when Brent crude volatility spikes, concentrating pricing power with integrated producers who control captive polyethylene supply. This lead-time exposure forces non-integrated Egyptian and Nigerian converters into spot market vulnerability, amplifying cost pass-through negotiations with multinational food brands.
Pricing Analysis
Cost-plus contracts indexed to ICIS Middle East naphtha assessments dominate resin procurement for Gulf-based converters. Three-tier pricing structure across premium barrier-certified, standard food-grade, and economy commodity tiers separates EVOH coextrusion specialists from basic polyethylene film producers. Pricing pressure stems from Egyptian port authorities tightening ECHA-aligned documentation enforcement, elevating testing costs for non-compliant imports. Quick-service restaurant chains in UAE and Saudi Arabia exhibit lowest price sensitivity due to specification lock-in, while Nigerian trading-house intermediaries face margin compression from informal retail price ceilings.
Supply Chain Analysis
Saudi Arabia and the UAE anchor regional polyethylene resin production through integrated petrochemical complexes serving downstream film extrusion. Raw material flows draw from naphtha crackers, imported masterbatch colorants through European ports, and specialty tie-layer adhesives from German and Italian suppliers. Single-source vulnerability concentrates in colorant additive supply routes, where Rotterdam port congestion propagates lead-time risk to Egyptian converters. Distribution runs through Dubai and Jeddah procurement hubs that consolidate volume for sub-Saharan redistribution, with Lagos and Cairo serving as secondary logistics nodes for local converter supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable polymer mandate timelines across Gulf Cooperation Council states are disrupting established polyethylene supply relationships, creating first-mover advantage windows for compliant converters. This regulatory inflection compresses reformulation investment horizons and reconfigures competitive access rules.
For Market Incumbents: Compound barrier technology differentiation through seven-layer coextrusion capability expansion in Saudi Arabia's Jeddah industrial corridor. SFDA migration limit enforcement is accelerating PVC displacement, opening reformulation service contracts for polyethylene and polypropylene laminate specialists. Backward integration into resin compounding secures margin control against naphtha price volatility.
For New Entrants and Emerging Players: Anchor in Nigeria's sachet packaging white space where cold-chain infrastructure expansion meets informal retail density. Digital inkjet-enabled short-run production unlocks micro-brand contracts that multinational converters dismiss. Partner with Lagos-based trading houses for last-mile distribution leverage rather than building direct retail relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from European multinational packaging parents seeking Gulf market exit amid REACH documentation complexity escalation. Five-to-ten year viability hinges on compliance infrastructure depth rather than scale alone. Monitor ECHA substance restriction list updates as the critical inflection signal for import acceptance risk at UAE and Egyptian ports.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates margin from Brent crude volatility at Saudi production hubs. |
| Digital Printing Platform Deployment | Inkjet deposition onto oriented polypropylene unlocks micro-brand contracts in Nigeria's fragmented retail. |
| SFDA Pre-Qualification Laboratory Investment | Local migration testing capability eliminates port detention risk for Egyptian and Nigerian importers. |
| Biodegradable Polymer Pilot Scale-Up | Polyhydroxyalkanoate cost parity achievement positions early adopters for Gulf disposal mandate compliance. |
| Direct Retail Chain Procurement Relationships | Carrefour and Lulu private-label specifications displace trading-house intermediation in Dubai and Jeddah. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with blown-film line operators, procurement managers at multinational food brands, SFDA compliance officers, and quick-service restaurant supply chain directors; alongside secondary validation through customs trade databases, Saudi Food and Drug Authority regulatory filings, ICIS resin price assessments, and SEC disclosures from listed packaging multinationals. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic drivers across the Middle East and Africa.
Across the analysis window, the forecast framework modeled volume and value trajectories through segmentation across product type, material grade, application, and end-user procurement concentration. CAGRs derived from trend extrapolation of historical resin consumption patterns, retail modernization indices, and regulatory implementation timelines. Key inputs included cold-chain infrastructure investment pipelines, supermarket penetration rates, and ECHA substance restriction adoption schedules at UAE and Egyptian ports.
Underlying assumptions cover sustained Gulf retail modernization, SFDA enforcement continuity, and naphtha price correlation with crude benchmarks, with deviation risk concentrated in biodegradable polymer cost curve acceleration and regional regulatory harmonization delays. Recalibration cycles align with material shifts in Gulf standardization protocols and port authority documentation enforcement practices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market