
 Converted Flexible Packaging Market | 2026-2036
Converted Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Converted Flexible Packaging Market Analysis
Buyer concentration among multinational food and beverage brands is consolidating procurement volumes toward fewer, larger converted flexible packaging suppliers. Amcor leverages its global manufacturing footprint to secure multi-year supply agreements with these consolidated buyers. Mondi Group anchors European demand through specialty kraft-paper and high-barrier film solutions tailored to refrigerated and shelf-stable formats. Berry Global differentiates via healthcare-grade cleanroom production capabilities that serve pharmaceutical contract packagers with exacting validation requirements.
Converted flexible packaging comprises pre-engineered films, laminates, and formed substrates that are cut, sealed, printed, and finished into functional containers such as stand-up pouches, roll stock, bags, and shrink sleeves, typically achieving oxygen transmission rates below 0.1 cc per square meter per day in high-barrier constructions. Stand-up pouches command the widest end-use penetration across food, personal care, and pharmaceutical applications due to their shelf presence and material efficiency. Polyethylene and BOPP dominate material tonnage for cost-sensitive commodity applications, while PET and aluminium foil concentrate in premium barrier segments where extended shelf life justifies higher unit economics.
The US FDA regulates direct food-contact substances through 21 CFR compliance pathways, while the EU enforces REACH substance restrictions and PPWR recyclability mandates that reshape material selection across the value chain. China's SAMR enforces GB standards for composite packaging safety that influence both domestic production and export-bound supply chains. Stakeholders must monitor how diverging extended producer responsibility frameworks across these jurisdictions will alter cost structures and competitive access over the forecast horizon.
Market Dynamics
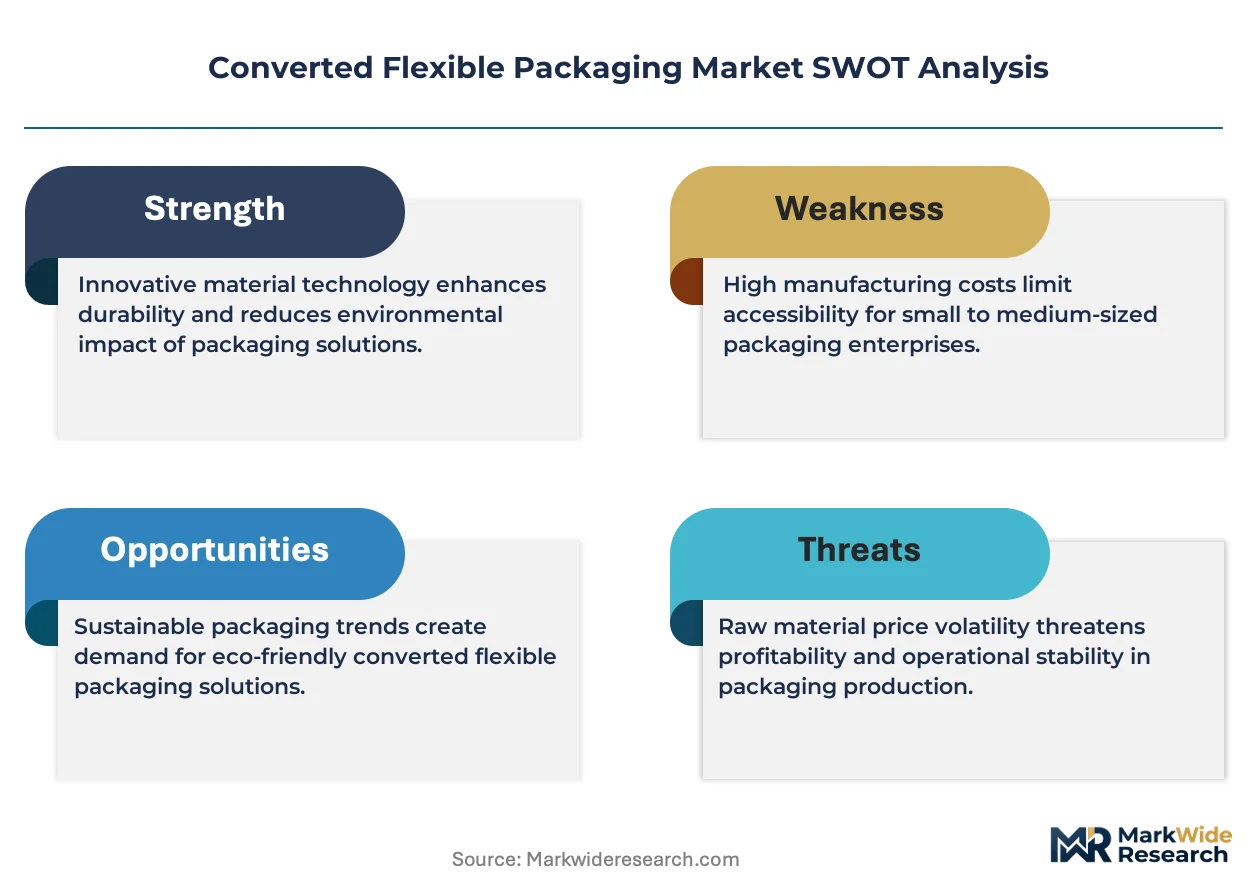
Consolidation among multinational food and beverage buyers is compressing supplier margins while simultaneously awarding multi-year contracts to converters with scale-advantaged manufacturing footprints and validated barrier-film capabilities.
Growth Catalysts
- E-commerce grocery fulfillment:China's snack-food localization and cold-chain expansion for shelf-stable proteins are accelerating pouch-format adoption in last-mile delivery networks.
- REACH substance traceability:Europe's Packaging and Packaging Waste Regulation is forcing material provenance investments that favor integrated converters with polymer-recycling capabilities.
- High-barrier PET constructions:Extended shelf-life requirements for ready-to-eat meals are displacing lower-performance polyethylene formats in premium retail channels.
Market Restraints
- Aluminium foil supply concentration:Premium barrier segments depend on concentrated primary metal sourcing from specific smelter geographies, exposing converters to input volatility.
- Cleanroom validation timelines:Pharmaceutical contract packagers face 18-24 month qualification periods for healthcare-grade flexible packaging that delay revenue recognition.
- Mechanical recycling incompatibility:Multi-layer laminate structures resist current sorting infrastructure, creating stranded cost risk under emerging extended producer responsibility frameworks.
Strategic Opportunities
- Mono-material pouch platforms:Polyethylene-only constructions that satisfy PPWR recyclability mandates while maintaining oxygen barrier below 0.5 cc per square meter per day.
- Digital printing convergence:Integration of HP Indigo and UV-ink systems with form-fill-seal lines enables SKU proliferation without plate-change downtime.
- Healthcare vertical expansion:Sterile barrier systems for biologic drug delivery represent underpenetrated demand with validation premiums 3-4x above food-grade equivalents.
Industry Challenges
- Barrier film coextrusion expertise:The specialized polymer rheology knowledge required for 9+ layer structures concentrates among retiring technical workforces in Germany and Japan.
- Legacy ERP integration:Real-time production traceability demanded by EU Digital Product Passports conflicts with decades-old MES architectures at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converted Flexible Packaging Market |
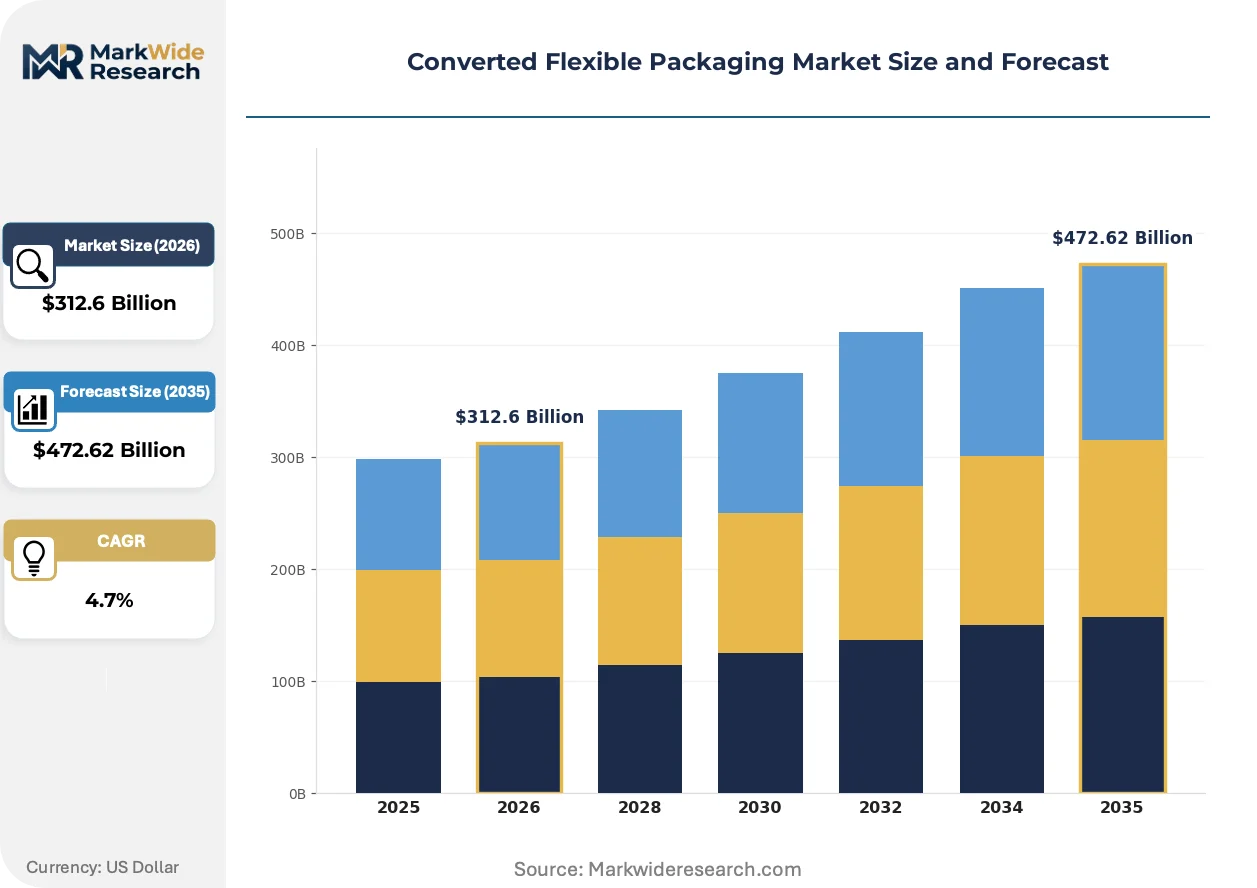
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Roll Stock, Bags, Shrink Sleeves Material: Polyethylene, BOPP, PET, Aluminium Foil Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Closure Type: Zipper, Spout, Adhesive, Tear Notch |
| Companies Covered | Constantia Flexibles, Mondi Group, Amcor, Huhtamaki, ProAmpac, Berry Global, Sonoco Products, Winpak, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converted Flexible Packaging Market Emerging Trajectories
Active and intelligent packaging functionalities are migrating from pharmaceutical containment into food-grade flexible formats, driven by sensor-cost reduction and shelf-life transparency demands from direct-to-consumer grocery channels.
Digital watermarking and invisible marker technologies are integrating into printed flexible substrates to enable automated sorting at materials recovery facilities. Major European retailers are mandating these markers for private-label packaging by 2027. This capability is integrating converter operations with waste management infrastructure, compressing the traditional separation between packaging production and end-of-life accountability.
China's GB standards for composite packaging safety are tightening migration limits for heavy metals and primary aromatic amines in adhesives and inks. Domestic converters serving export markets must dual-certify production lines under both SAMR and FDA 21 CFR pathways. High-barrier constructions for infant formula and nutraceuticals face the steepest compliance cost escalation.
Direct store delivery networks for beverage and dairy brands are compressing order cycles from monthly to weekly replenishment. This pattern fragments production runs and elevates changeover frequency on form-fill-seal equipment. North American co-packers serving these channels are prioritizing quick-change tooling and automated splice systems to maintain throughput economics.
Converted Flexible Packaging Market Segmentation
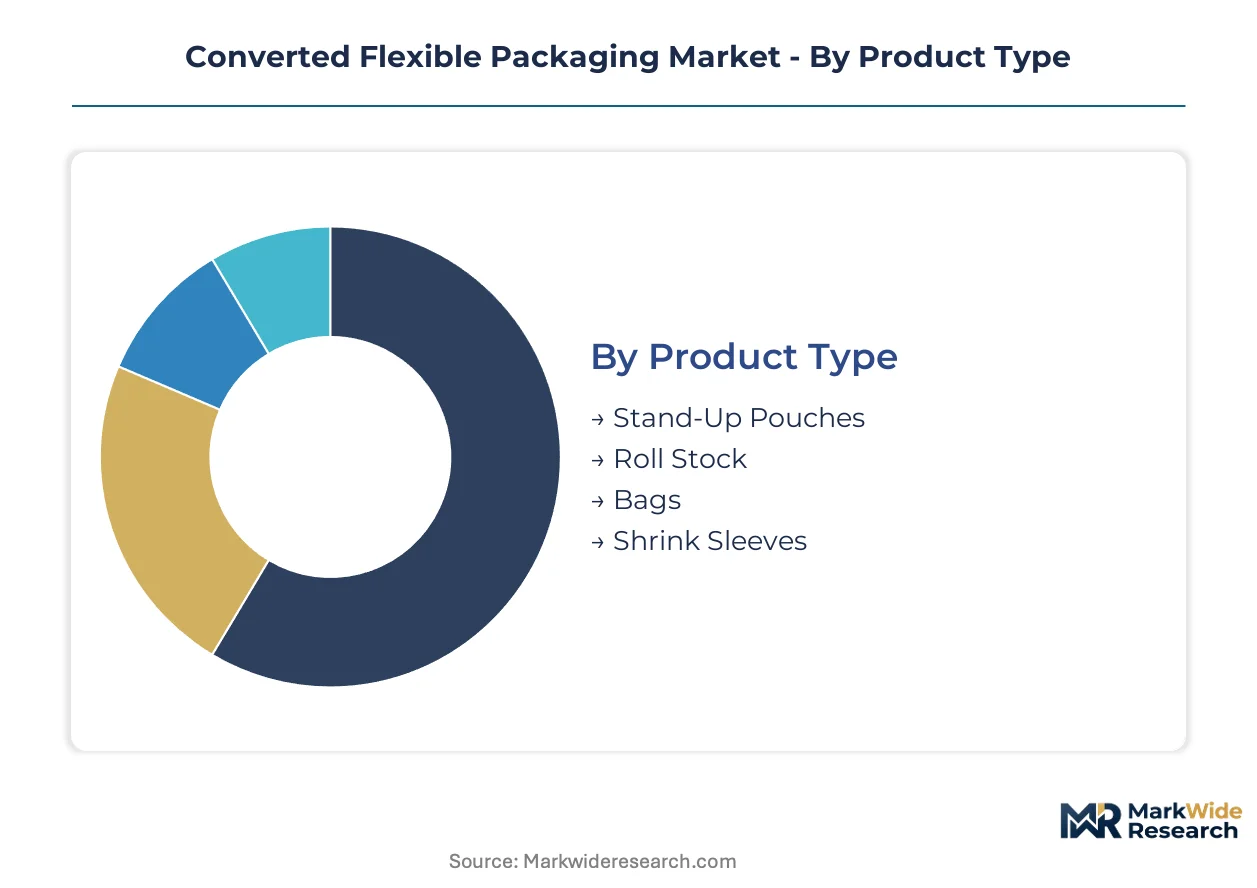
Converted flexible packaging segments diverge sharply in regulatory burden, with food-contact formats demanding FDA 21 CFR compliance and pharmaceutical constructions requiring cleanroom validation. Material selection and closure architecture further stratify certification pathways across end-use applications.
Product Type:
Certification intensity varies by product geometry, with stand-up pouches facing the most complex multi-jurisdictional approval requirements for food-contact layers and child-resistant features.
- Stand-Up Pouches:Multi-layer laminates with bottom gusset construction achieve oxygen transmission rates below 0.1 cc per square meter per day in high-barrier specifications. Demand concentrates in China's e-commerce grocery channels for shelf-stable proteins and ready-to-eat meals, driven by last-mile delivery format requirements.
- Roll Stock:Unformed continuous web supplied to downstream form-fill-seal operations, typically coextruded in 5-9 layer structures for barrier tunability. North American co-packers serving direct store delivery networks favor this format for quick-change production economics and SKU proliferation flexibility.
- Bags:Pre-formed three-side-seal or side-gusset configurations dominate cost-sensitive commodity applications. Polyethylene and BOPP constructions serve bulk dry goods with minimal barrier requirements.
- Shrink Sleeves:Heat-activated PET or OPS films conforming to contoured containers for 360-degree decoration and tamper evidence. Beverage and personal care brands leverage this format for shelf differentiation in premium retail channels.
Stand-up pouches sit at the top of the volume ranking, with roll stock climbing the fastest as co-packers prioritize production flexibility.
Material:
Material selection determines cost tier positioning and recyclability compliance under emerging extended producer responsibility frameworks.
- Polyethylene:Dominates tonnage in commodity applications through mono-material constructions that satisfy EU PPWR recyclability mandates. China's domestic converters leverage PE for snack-food localization in e-commerce fulfillment networks.
- BOPP:Biaxially oriented polypropylene delivers clarity and moisture barrier at mid-tier economics. Cereal and confectionery packaging represent concentrated demand centers.
- PET:High-barrier metallized or coextruded constructions displace lower-performance alternatives in premium ready-to-eat meal segments. Extended shelf-life requirements in European refrigerated channels drive specification upgrades.
- Aluminium Foil:Ultra-high barrier layer in pharmaceutical blister packs and retort pouch applications. Supply concentration in specific smelter geographies exposes converters to input volatility and qualification complexity.
Polyethylene maintains volume leadership, while PET gains share fastest on premium format displacement.
Application:
End-use application dictates validation timeline and margin structure, with pharmaceutical formats commanding 3-4x premiums over food-grade equivalents.
- Food & Beverage:Largest addressable demand spanning shelf-stable proteins, ready-to-eat meals, and snack-food localization. China's SAMR enforces GB standards for composite packaging safety that influence both domestic production and export-bound supply chains.
- Pharmaceuticals:Healthcare-grade cleanroom production with 18-24 month qualification periods for sterile barrier systems. Berry Global anchors this segment through validated manufacturing capabilities serving contract packagers.
- Personal Care:Shrink sleeves and stand-up pouches for cosmetics and toiletries with emphasis on decoration and dispensing convenience.
- Household:Detergent and cleaning product formats prioritizing chemical resistance and child-resistant closure integration.
Food and beverage sits at the top of the volume ranking, with pharmaceuticals climbing the fastest on biologic drug delivery expansion.
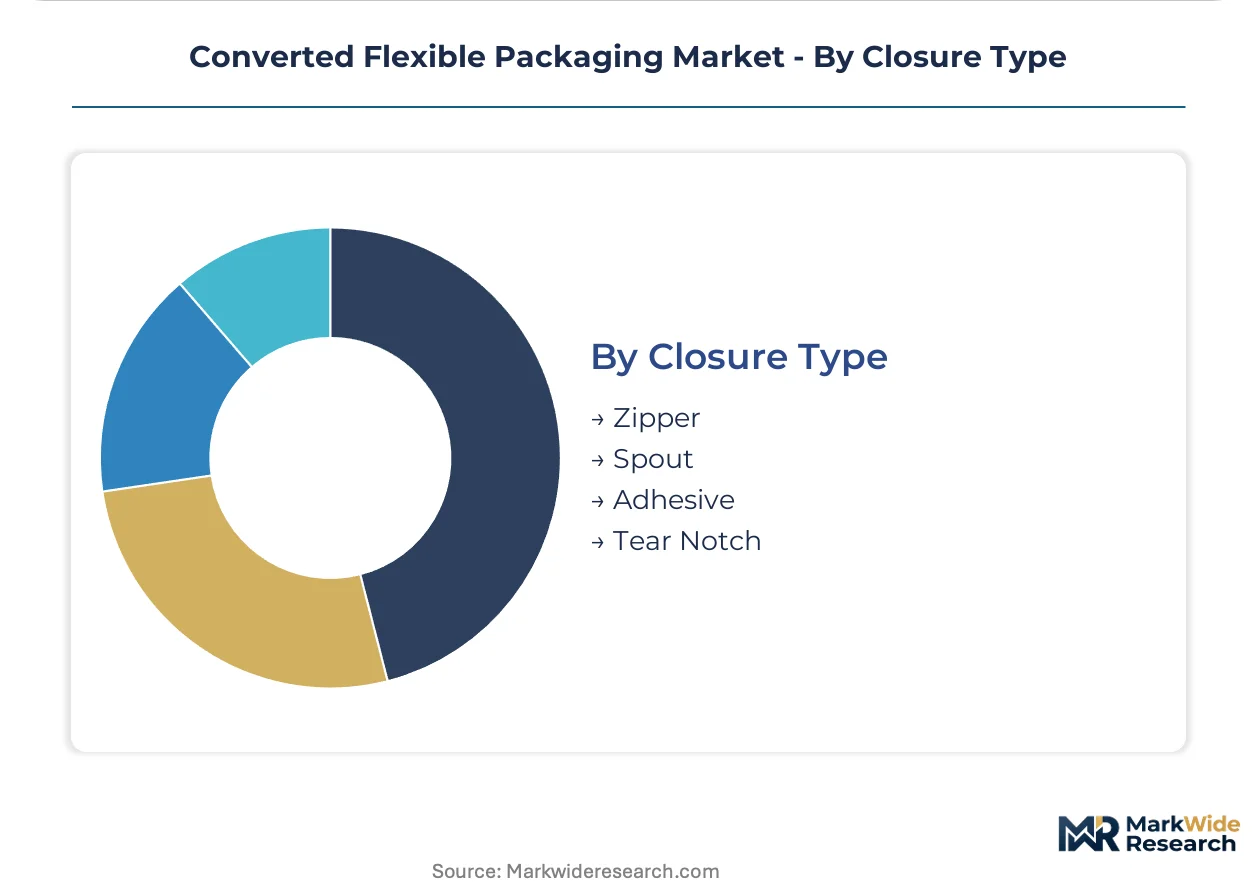
Closure Type:
Closure architecture determines reseal functionality and regulatory classification, with child-resistant mechanisms requiring specialized testing protocols.
- Zipper:Interlocking plastic profiles enabling repeated reseal for multi-serve food and personal care formats. Premium retail channels specify this feature for convenience differentiation.
- Spout:Integrated dispensing fitments for liquid and semi-liquid contents in beverage and household applications. Tooling investment limits adoption to high-volume SKUs.
- Adhesive:Pressure-sensitive or cold-seal coatings for tamper-evident and resealable lidding. Cost-minimized option for single-serve portions.
- Tear Notch:Laser-scored or die-cut initiation features for clean opening without tools. Universal specification across commodity bag formats.
Zipper closures sit at the top of the volume ranking, with spout integration climbing the fastest in beverage format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's e-commerce grocery fulfillment networks consume pouches at volumes that dwarf Germany's specialty barrier-film demand, yet both geographies face converging pressure on material traceability and recyclability compliance.
China
Snack-food localization and cold-chain expansion for shelf-stable proteins drive pouch-format adoption in last-mile delivery networks. SAMR enforces GB standards for composite packaging safety that tighten migration limits for heavy metals and primary aromatic amines. Domestic converters in Yangtze River Delta clusters dual-certify production lines under both SAMR and FDA 21 CFR pathways for export-bound infant formula packaging.
Germany
REACH substance traceability and PPWR recyclability mandates force material provenance investments favoring integrated converters with polymer-recycling capabilities. ECHA enforcement of extended producer responsibility frameworks alters cost structures for multi-layer laminate structures. Technical workforces in Bavaria and Baden-Württemberg concentrate the specialized polymer rheology knowledge required for 9+ layer coextrusion structures.
United States
Direct store delivery networks for beverage and dairy brands compress order cycles from monthly to weekly replenishment, fragmenting production runs. FDA regulates direct food-contact substances through 21 CFR compliance pathways. Co-packers in the Midwest and Southeast prioritize quick-change tooling and automated splice systems to maintain throughput economics under elevated changeover frequency.
India
FSSAI enforcement of food-contact material safety standards intersects with BIS certification requirements for imported barrier films. Domestic demand for ready-to-eat meals and shelf-stable proteins expands pouch adoption in modern trade and e-commerce channels. Converters in Maharashtra and Gujarat invest in metallized PET capacity to serve pharmaceutical contract packagers requiring healthcare-grade cleanroom validation.
Japan
PMDA oversight of pharmaceutical packaging materials creates qualification complexity for sterile barrier systems in biologic drug delivery. METI promotes mono-material pouch platforms to align with circular economy roadmaps. Technical expertise for high-barrier coextrusion concentrates in Chubu and Kansai industrial clusters where retiring workforces threaten knowledge continuity.
Converted Flexible Packaging Market Vendor Landscape
European producers anchor one tier; North American specialists hold scale-advantaged manufacturing footprints that secure multi-year supply agreements with consolidated multinational buyers. The supplier base organizes around three strategic archetypes: integrated global converters with polymer-recycling capabilities, regional specialists in high-barrier film constructions, and healthcare-grade cleanroom operators serving pharmaceutical validation requirements. Competitive moves concentrate on backward integration into resin compounding and capacity expansion in Asia-Pacific e-commerce corridors.
Among the integrated global tier, Amcor plc and Mondi Group exemplify archetypes of geographic diversification and specialty material focus respectively. Berry Global occupies a position within healthcare-grade cleanroom production capabilities. These three entities represent the spectrum from commodity scale to premium validation tiers without overstating specific strategic actions or market positions.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Mondi Group |
| Amcor |
| Huhtamaki |
| ProAmpac |
| Berry Global |
| Sonoco Products |
| Winpak |
| Sealed Air |
| Others |
Supply Flow & Price Mechanics
Multi-year procurement consolidation by multinational food and beverage brands is compressing supplier margins and forcing converters to absorb material volatility through contract structures rather than pass-through mechanisms.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for polyethylene-based mono-material pouches. Three-tier pricing structure across premium barrier, standard mid-tier, and economy commodity levels stratifies by oxygen transmission performance and certification grade. Cost compression in standard tiers is intensifying because European PPWR recyclability mandates require capital-intensive requalification. Private-label retail buyers exhibit highest price sensitivity; pharmaceutical contract packagers show lowest sensitivity due to validation switching costs.
Supply Chain Analysis
Post-consumer laminate collection and mechanical recycling flows remain underdeveloped, creating stranded cost exposure under emerging extended producer responsibility frameworks. Primary aluminium foil sourcing draws from concentrated smelter geographies in China and Russia, exposing converters to input volatility. Multi-layer film production rests on biaxially oriented polypropylene and metallized PET supply from Germany, Japan, and South Korea. Single-source vulnerability concentrates in pharmaceutical-grade cleanroom resin compounding. Distribution runs through converter-direct relationships with multinational brand procurement hubs and regional co-packer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converted flexible packaging functions as a stable compounder anchored by irreversible format substitution toward pouches in e-commerce grocery channels.
For Market Incumbents: To counter margin compression from buyer consolidation, deepen backward integration into polymer recycling capabilities serving EU PPWR compliance requirements. Anchor multi-year supply agreements through validated barrier-film manufacturing footprints in Asia-Pacific e-commerce corridors. For New Entrants and Emerging Players: Launch via digital printing convergence partnerships with regional co-packers serving fragmented direct store delivery networks. White-space concentrates in healthcare-grade sterile barrier systems for biologic drug delivery and mono-material pouch platforms qualifying under European recyclability mandates. Prioritize quick-change tooling capabilities for weekly replenishment cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing healthcare cleanroom validation and untapped Asia-Pacific capacity expansion rights. Long-term viability over a multi-year window favors targets with integrated polymer-recycling assets and established multinational brand relationships. Monitor European Digital Product Passport implementation timelines as inflection indicator for traceability compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Development | Polyethylene-only constructions satisfying PPWR mandates capture premium positioning in European retail channels. |
| Healthcare Cleanroom Validation | Eighteen-to-twenty-four month qualification periods create switching-cost moats around pharmaceutical contract packaging. |
| Digital Printing Integration | HP Indigo and UV-ink convergence with form-fill-seal lines enables SKU proliferation without plate-change downtime. |
| Backward Integration into Recycling | In-house polymer-recycling capabilities defray material provenance investments demanded by REACH traceability. |
| Asia-Pacific Capacity Expansion | Manufacturing footprints in China's e-commerce corridors secure volume allocation from consolidating multinational buyers. |
Methodological Framework
Direct dialogue with converter operations managers, multinational brand procurement directors, pharmaceutical contract packaging executives, and polymer recycling technology suppliers grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, ECHA REACH substance registrations, FDA 21 CFR compliance databases, and trade flow records for aluminium foil and barrier film imports. Bottom-up and top-down triangulation cross-checked volume estimates against capacity announcements and end-use consumption patterns.
Bottom-up modeling aggregated product-type, material-grade, application-segment, and closure-architecture dimensions across the projection horizon. Top-down verification anchored total addressable demand against food and beverage production volumes, pharmaceutical packaging spend, and e-commerce grocery fulfillment growth trajectories. CAGRs derived from segment-level elasticity analysis relative to input cost movements and regulatory compliance cost escalations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt extended producer responsibility fee implementation or aluminium supply disruption scenarios. Practitioners should monitor European Digital Product Passport regulatory drafts and China's GB standard revision timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Flexible Containers Market