
 Global Flexible Packaging Market | 2026-2036
Global Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Packaging Market Analysis
Skilled polymer chemist availability in Western Europe is collapsing as retirement waves outpace university pipeline output, tightening formulation innovation capacity. Amcor plc leverages its integrated film-to-pouch manufacturing footprint across multiple continents to sustain delivery reliability for multinational food brands. Mondi anchors European demand through kraft paper-based flexible solutions that compete directly with conventional plastic laminates. Sealed Air differentiates via active and intelligent packaging technologies that extend shelf life for protein and pharmaceutical shipments.
Flexible packaging comprises pliable material structures—typically multilayer films, foils, or paper laminates between 10 and 150 micrometers thick—engineered to conform to product shape while providing barrier protection against moisture, oxygen, and light. These structures are produced through extrusion coating, adhesive lamination, or coextrusion processes and serve primarily to reduce material usage, transportation cost, and food spoilage relative to rigid alternatives. Films and pouches command the largest share of product type demand, driven by single-serve convenience formats in food service and retail channels. Plastic substrates still dominate material volumes, though biodegradable and recyclable grades are gaining fastest as brand owners respond to extended producer responsibility frameworks. Specialty grade laminates with high oxygen barrier properties occupy the strongest margin pools, particularly in pharmaceutical blister and retort pouch applications.
The US EPA regulates volatile organic compound emissions from solvent-based lamination processes, pushing converters toward water-based or solventless adhesive systems. REACH and the EU Packaging and Packaging Waste Regulation impose substance restrictions and recyclability targets that reshape material specifications across European supply chains. India's BIS certification requirements for food-contact plastics create compliance thresholds that filter import competition. Stakeholders must monitor how divergent national recycling infrastructure capabilities constrain the commercial viability of supposedly universal sustainable packaging claims.
Market Dynamics
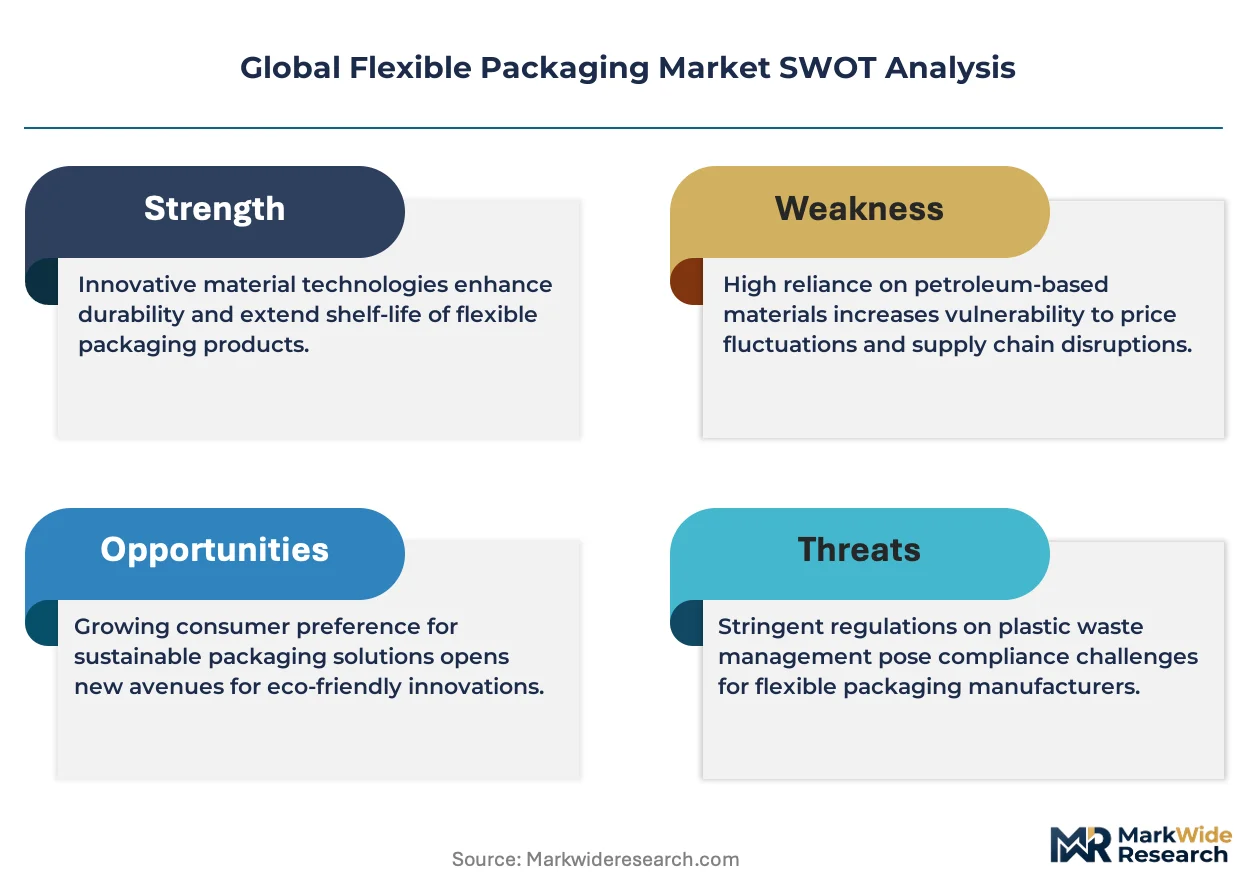
The EU Packaging and Packaging Waste Regulation is forcing material substitution across European supply chains, compressing demand for conventional multilayer plastics while redirecting investment toward mono-material and fiber-based structures. This regulatory pressure operates in parallel with raw material cost volatility and shifting procurement priorities among multinational food brands.
Growth Catalysts
- India's BIS certification thresholds:Domestic food-contact compliance requirements filter import competition, creating protected growth corridors for local converters expanding film-to-pouch capacity.
- E-commerce fulfillment acceleration:Last-mile delivery networks in Southeast Asia and Latin America adopt lightweight pouch formats to reduce dimensional weight charges and damage rates.
- Retort pouch technology:High-barrier laminates enable shelf-stable protein and ready-meal formats without refrigerated distribution infrastructure.
Market Restraints
- Ethylene and propylene feedstock volatility:Crude oil price swings transmit directly to polyethylene film costs, compressing converter margins and destabilizing annual contract pricing.
- Western European polymer chemist scarcity:Retirement waves outpace university pipeline output, tightening formulation innovation capacity for specialty barrier coatings.
- Mechanical recycling incompatibility:Conventional multilayer structures resist standard sorting and reprocessing infrastructure, limiting circular economy claims.
Strategic Opportunities
- India's domestic consumption expansion:Rising middle-class protein demand and organized retail penetration create white space for converted flexible packaging capacity.
- Pharmaceutical cold-chain logistics:Temperature-sensitive biologics shipments require active barrier solutions with integrated sensors and phase-change materials.
- Paper-based flexible substrates:Kraft and specialty paper laminates capture regulatory tailwinds from EU Green Deal circular economy targets.
Industry Challenges
- Adhesive system reconfiguration:US EPA volatile organic compound rules push converters toward water-based or solventless lamination, requiring capital-intensive equipment replacement.
- Extended producer responsibility compliance:Divergent national recycling infrastructure capabilities constrain universal sustainable packaging claims across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Packaging Market |
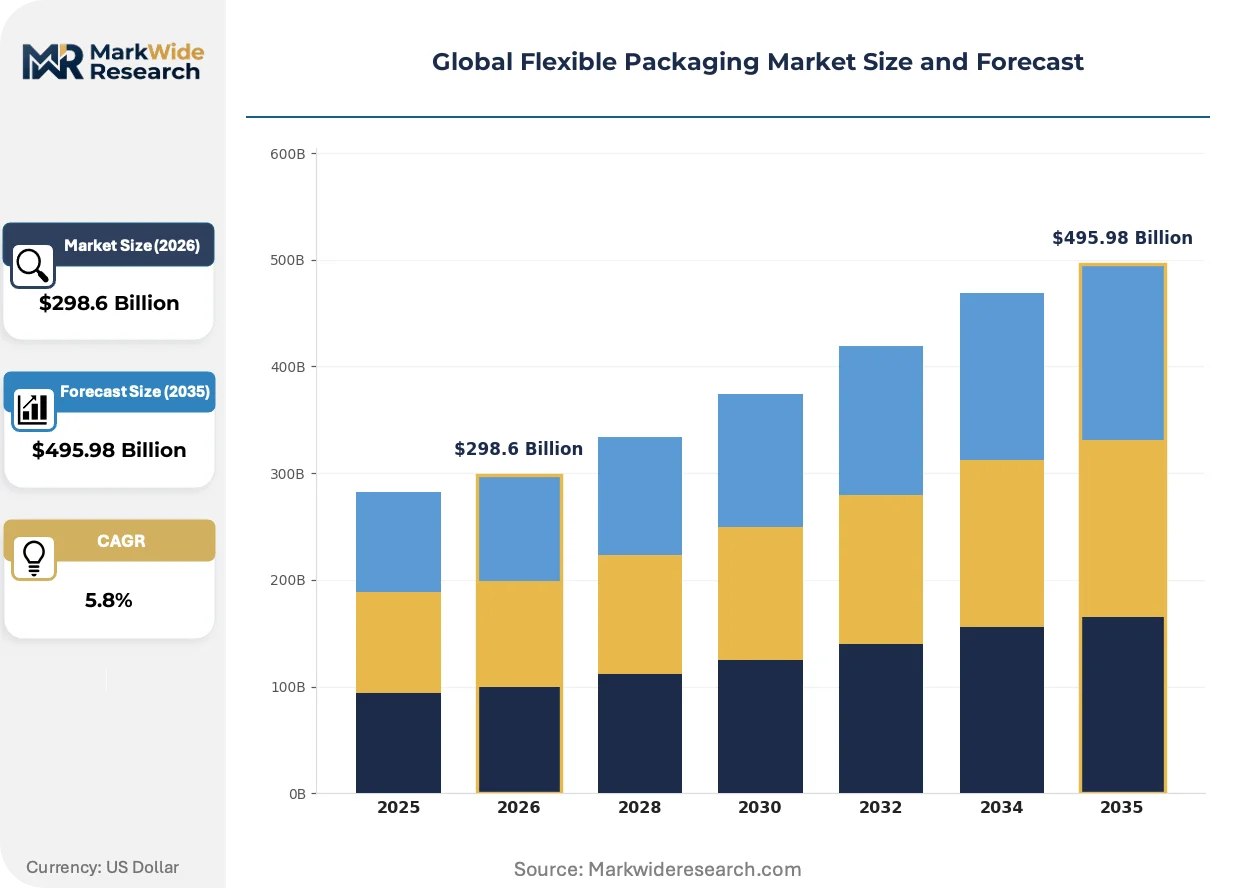
| Market Size in 2026 | $298.6 Billion |
| Market Size in 2035 | $495.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps Material: Plastic, Paper, Aluminum, Composites End Use Industry: Food & Beverages, Pharmaceuticals, Personal Care, Home Care Grade: Standard, Biodegradable, Recyclable, Specialty |
| Companies Covered | Amcor plc, Mondi, Sealed Air, Huhtamaki Oyj, Constantia Flexibles, Sonoco Products Company, Transcontinental Inc., Smurfit Westrock, UFlex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Packaging Market Emerging Trajectories
Active and intelligent packaging systems are migrating from pharmaceutical cold-chain applications into premium food segments, embedding sensors and indicators directly into flexible substrates. These developments intersect with regulatory mandates on recyclability and brand-owner pressure to demonstrate measurable shelf-life extension.
Mono-material polyethylene laminates are supplanting conventional multilayer structures in snack and frozen food applications. Nestlé and Unilever procurement teams have accelerated qualification timelines for these structures. The shift is compressing demand for ethylene vinyl alcohol copolymer barrier layers while expanding investment in metallocene polyethylene catalyst technology.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are reshaping material specifications across European supply chains. Converters must eliminate certain phthalate plasticizers and demonstrate recyclability by design. Pharmaceutical blister and retort pouch applications face the steepest compliance timelines due to stringent barrier performance requirements.
Brand-owner sustainability scorecards now weight packaging circularity in supplier selection criteria. Multinational food manufacturers in Germany and France prioritize converters with certified closed-loop collection systems. This behavioral shift concentrates procurement volumes among integrated film-to-pouch operators with established mechanical recycling partnerships.
Global Flexible Packaging Market Segmentation
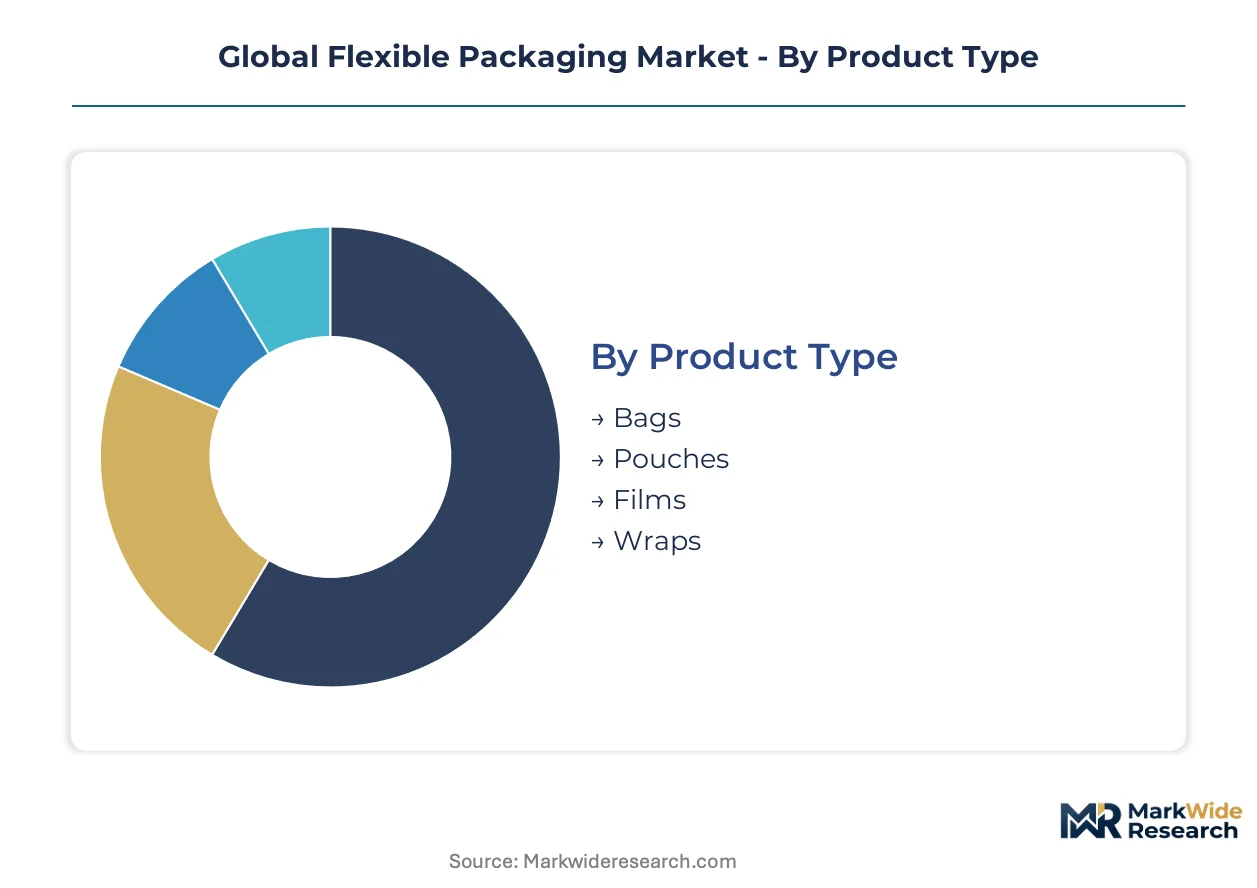
Flexible packaging segmentation reveals how material science, regulatory pressure, and end-use performance requirements fragment procurement decisions across global supply chains. Each dimension carries distinct margin profiles and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Pouches face the most intense substitution pressure from rigid alternatives in premium segments, while films confront margin compression from commodity-grade overcapacity.
- Pouches:Stand-up and flat pouch formats dominate single-serve convenience applications. Nestlé and Unilever procurement teams accelerated qualification timelines for mono-material polyethylene structures in snack and frozen food segments.
- Films:Cast and blown polyethylene films between 10-150 micrometers thick form the substrate foundation for most laminate structures. Indian converters expanding film-to-pouch capacity draw multinational supplier interest amid domestic consumption growth.
- Bags:Gusseted and wicketed bag formats serve bulk dry goods and produce distribution. Retail consolidation in Germany and France concentrates volumes among integrated film-to-pouch operators with certified closed-loop collection systems.
- Wraps:Stretch and shrink wrap applications cling to pallet stabilization and fresh produce protection. E-commerce fulfillment networks in Southeast Asia and Latin America adopt lightweight formats to reduce dimensional weight charges.
Pouches anchor the volume base while specialty films gain share at the steepest rate.
Material:
Cost tier stratification separates commodity substrates from barrier-grade laminates with pharmaceutical and retort applications commanding premium positioning.
- Plastic:Polyethylene and polypropylene substrates still dominate material volumes, though biodegradable and recyclable grades are gaining fastest as brand owners respond to extended producer responsibility frameworks.
- Paper:Kraft and specialty paper laminates capture regulatory tailwinds from EU Green Deal circular economy targets. Mondi anchors European demand through kraft paper-based flexible solutions that compete directly with conventional plastic laminates.
- Aluminum:Foil layers provide absolute moisture and light barrier properties in pharmaceutical blister and retort pouch applications. REACH substance restrictions impose the steepest compliance timelines on aluminum-plastic composite structures.
- Composites:Multilayer structures combining plastic, foil, and paper deliver tailored barrier performance. Mechanical recycling incompatibility limits circular economy claims for conventional multilayer configurations.
Plastic substrates retain the largest volume position while paper-based alternatives expand most quickly.
End Use Industry:
Application-driven specification divergence separates food-grade compliance requirements from pharmaceutical validation protocols and personal care aesthetic demands.
- Food & Beverages:Lightweight pouch formats reduce shipping costs and shelf-space requirements for beverage and ready-meal manufacturers. Retort pouch technology enables shelf-stable protein formats without refrigerated distribution infrastructure.
- Pharmaceuticals:Temperature-sensitive biologics shipments require active barrier solutions with integrated sensors and phase-change materials. Sealed Air differentiates via active and intelligent packaging technologies that extend shelf life for protein and pharmaceutical shipments.
- Personal Care:Flexible sachets and pouches serve emerging market single-use consumption patterns. BIS certification requirements for food-contact plastics in India create compliance thresholds that filter import competition in adjacent personal care segments.
- Home Care:Refill pouches for liquid detergents and cleaning concentrates reduce rigid packaging waste. US EPA volatile organic compound rules push converters toward water-based or solventless lamination for home care adhesive labels.
Food and beverage applications anchor the volume base while pharmaceutical cold-chain logistics gains share at the steepest rate.
Grade:
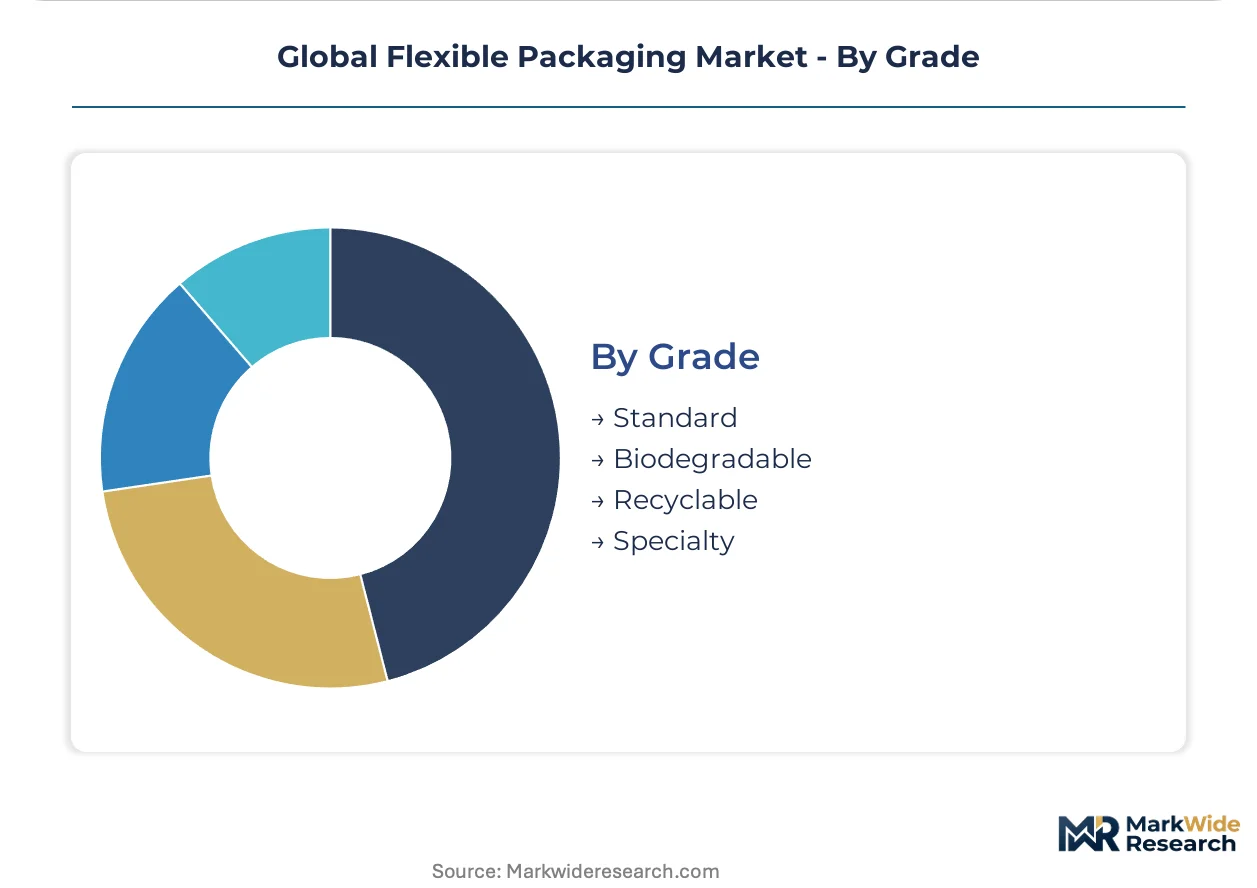
Margin concentration pools in specialty barrier coatings as standard grades confront commoditization and sustainability premiums reshape procurement weightings.
- Specialty:High oxygen barrier laminates occupy the strongest margin pools, particularly in pharmaceutical blister and retort pouch applications. Skilled polymer chemist availability in Western Europe is collapsing as retirement waves outpace university pipeline output.
- Recyclable:Mono-material polyethylene laminates are supplanting conventional multilayer structures in snack and frozen food applications. The EU Packaging and Packaging Waste Regulation imposes recyclability targets that reshape material specifications across European supply chains.
- Biodegradable:Starch-based and polylactic acid substrates respond to brand-owner sustainability scorecards. Divergent national recycling infrastructure capabilities constrain the commercial viability of supposedly universal sustainable packaging claims.
- Standard:Commodity-grade polyethylene and polypropylene films serve cost-sensitive bulk applications. Ethylene and propylene feedstock volatility transmits directly to standard grade pricing, compressing converter margins.
Standard grades anchor the volume base while recyclable formulations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany command pricing premiums for recyclable laminates that Indian suppliers cannot match, while Southeast Asian producers undercut both on standard-grade commodity films. This asymmetry fragments procurement strategies across multinational brand portfolios.
United States
E-commerce fulfillment networks in California and Texas adopt lightweight pouch formats to reduce dimensional weight charges. The EPA regulates volatile organic compound emissions from solvent-based lamination processes. Chicago-area converters invest in water-based adhesive systems to maintain compliance while serving Nestlé and Unilever procurement teams.
Germany
Brand-owner sustainability scorecards in Bavaria and North Rhine-Westphalia prioritize converters with certified closed-loop collection systems. REACH substance restrictions and the EU Packaging and Packaging Waste Regulation impose recyclability targets. The Hamburg industrial cluster concentrates integrated film-to-pouch operators serving pharmaceutical cold-chain logistics.
India
Rising middle-class protein demand and organized retail penetration create white space for converted flexible packaging capacity. BIS certification requirements for food-contact plastics filter import competition. Maharashtra and Gujarat host domestic converters expanding film-to-pouch capacity to capture protected growth corridors.
China
Dual carbon goals accelerate material substitution toward mono-material and fiber-based structures in Yangtze River Delta manufacturing zones. The Ministry of Ecology and Environment tightens emissions standards for extrusion coating operations. Zhejiang and Jiangsu provinces attract investment in metallocene polyethylene catalyst technology.
Brazil
Last-mile delivery networks in São Paulo adopt flexible formats to reduce damage rates in humid distribution conditions. ANVISA pharmaceutical packaging regulations create compliance thresholds for barrier-grade laminates. The São Paulo state industrial corridor concentrates converters serving both domestic food brands and export pharmaceutical shipments.
Global Flexible Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated multinationals commanding premium segments and regional specialists dominating commodity volumes. The market structures around three tiers: global film-to-pouch integrators, substrate-focused material suppliers, and application-specific packaging engineers. Competitive moves concentrate on M&A for recycling infrastructure access and capacity expansion in India and Southeast Asia.
Among integrated multinationals, Amcor plc and Mondi exemplify the technology-architecture archetype, while Sealed Air occupies a position in active barrier solutions. These three represent divergent strategic postures: captive resin-to-pouch integration, fiber-based substitution, and intelligent packaging specialization respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi |
| Sealed Air |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Sonoco Products Company |
| Transcontinental Inc. |
| Smurfit Westrock |
| UFlex Limited |
| Others |
Supply Flow & Price Mechanics
Mono-material polyethylene substitution for conventional multilayer laminates is compressing specialty-grade margins while redrawing procurement geography toward Indian and Southeast Asian converters with metallocene catalyst access. This input transition simultaneously erodes Western European formulation premiums and elevates price competition in standard-grade film markets.
Pricing Analysis
The customization-premium spread separates configured-to-order specialty barrier laminates from spot-market commodity films. Contract-based long-term offtake dominates pharmaceutical and retort applications, while transactional per-unit pricing governs standard-grade polyethylene volumes. Price differentiation rests on certification grade—EU Packaging and Packaging Waste Regulation compliance commands measurable premiums over uncertified alternatives. Cost compression in standard grades is intensifying because Indian converters exploit BIS-protected domestic corridors. Multinational food brands exhibit lowest price sensitivity in cold-chain pharmaceutical segments, while bulk dry goods distributors drive hardest bargain hunting.
Supply Chain Analysis
Strategic stockpiling of ethylene and propylene feedstock dominates converter behavior given crude oil price volatility, while just-in-time resin delivery persists only among integrated multinationals with captive supply. Geographic supply concentrates in China, India, and Germany—Zhejiang and Jiangsu provinces anchor metallocene polyethylene catalyst production, Maharashtra and Gujarat host expanding film-to-pouch capacity, and the Hamburg industrial cluster serves pharmaceutical cold-chain logistics. Raw material dependencies draw from naphtha crackers, metallocene catalyst systems, and adhesive resin formulations. Single-source vulnerability in specialty barrier coating polymer chemists—Western European retirement waves outpace university pipeline output—threatens formulation continuity. Distribution runs through integrated film-to-pouch operators with certified closed-loop collection systems serving Nestlé and Unilever procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise is vanishing faster than replacement pipelines can replenish it, concentrating innovation capacity among integrated multinationals with captive R&D infrastructure and deepening competitive moats against commodity converters.
For Market Incumbents: Secure polymer chemist talent pools through university partnership pipelines and retention premiums before retirement waves accelerate. Deepen backward integration into metallocene polyethylene catalyst technology to control input costs against feedstock volatility. The EU Packaging and Packaging Waste Regulation recyclability mandates threaten multilayer laminate incumbents who lag mono-material qualification timelines. For New Entrants and Emerging Players: BIS certification fast-track programs unlock protected growth corridors in Maharashtra and Gujarat food-contact markets filtered against import competition. Target India's rising middle-class protein demand with retort pouch capacity positioned for organized retail penetration. Pursue pharmaceutical cold-chain logistics as the most penetrable premium segment, leveraging active barrier sensor integration as differentiated go-to-market positioning against commodity film competitors. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors integrated film-to-pouch operators with mechanical recycling partnerships and certified closed-loop collection systems. Long-term viability across the next decade hinges on regulatory compliance architecture rather than scale alone. Watch EU Green Deal implementation velocity as the critical inflection signal—accelerated material substitution timelines would strand conventional multilayer laminate assets and revalue paper-based flexible substrate capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Catalyst Production | Captive supply of high-performance polyethylene resin insulates margin compression from naphtha price volatility. |
| Mono-Material Laminate Qualification Acceleration | Nestlé and Unilever procurement teams prioritize suppliers with EU Packaging and Packaging Waste Regulation-compliant structures. |
| Active Barrier Sensor Technology Development | Sealed Air's pharmaceutical cold-chain positioning demonstrates shelf-life extension commands measurable procurement premiums. |
| Mechanical Recycling Partnership Certification | German and French brand-owner sustainability scorecards weight closed-loop collection systems in supplier selection criteria. |
| India Film-to-Pouch Capacity Expansion | Maharashtra and Gujarat domestic consumption growth creates protected corridors against BIS-filtered import competition. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymer chemists, converter plant managers, multinational food brand procurement leads, pharmaceutical packaging engineers, and adhesive system technical directors. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of listed packaging companies, EU Packaging and Packaging Waste Regulation impact assessments, and Indian BIS certification registry records. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic consumption projections.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, material substrate, end-use industry vertical, and grade tier dimensions. CAGRs were derived from regression analysis of historical capacity utilization rates, feedstock cost pass-through elasticity, and regulatory compliance timeline acceleration. Forecast inputs incorporated ethylene and propylene feedstock volatility scenarios, EU Green Deal implementation pace, and Indian organized retail penetration curves.
Underlying assumptions cover sustained crude oil price corridor stability, EU recyclability target enforcement consistency, and Indian BIS certification threshold maintenance, with deviation risk concentrated in Western European polymer chemist availability collapse and divergent national recycling infrastructure capabilities. Revision becomes warranted when EU Packaging and Packaging Waste Regulation compliance timelines accelerate beyond current converter adaptation capacity or when Indian domestic consumption growth decelerates below organized retail expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
China Flexible Plastic Packaging Market