
 Benelux Flexible Plastic Packaging Market | 2026-2036
Benelux Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Flexible Plastic Packaging Market Insights
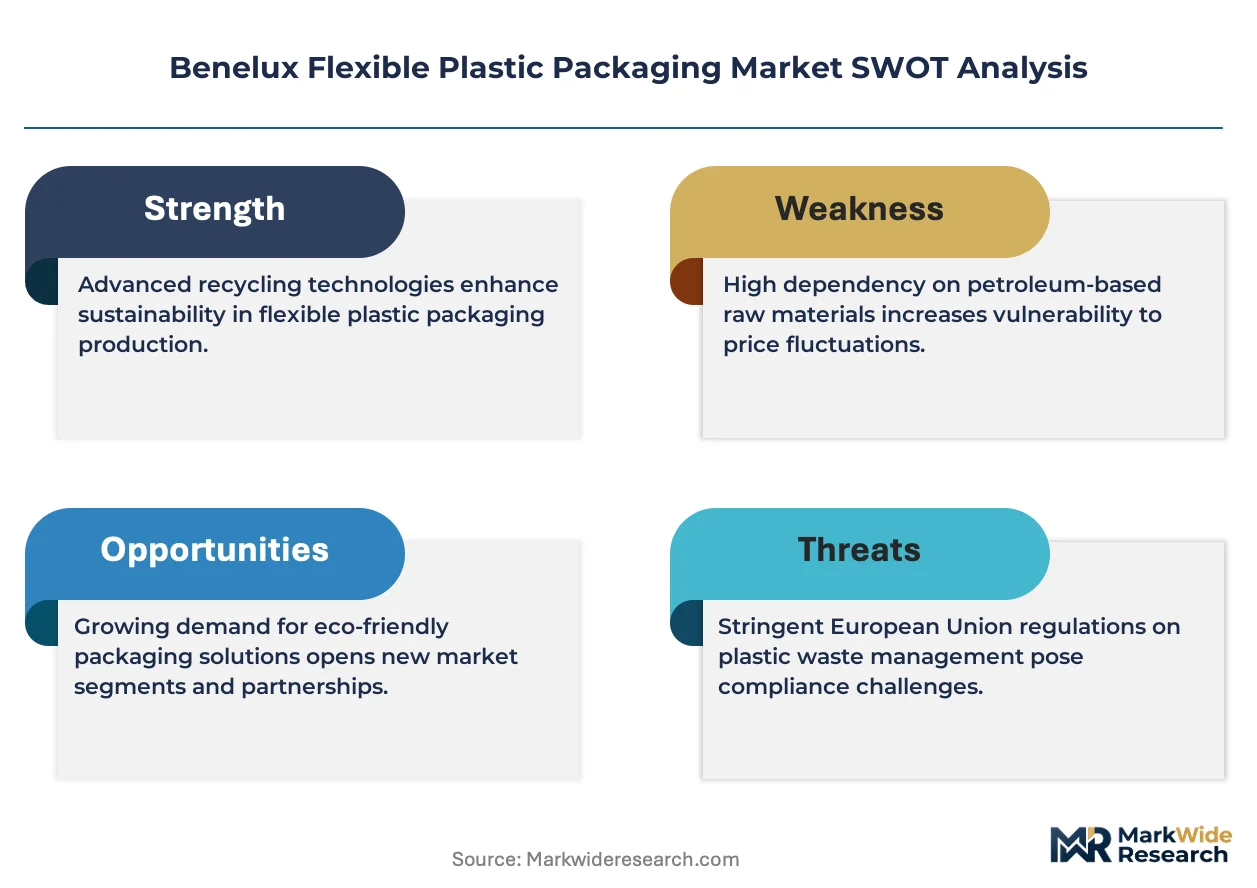
Mono-material polyethylene structures is tilting flexible packaging design away from complex multi-layer laminates that complicate mechanical recycling. Constantia Flexibles leverages its Austrian-headquartered European network to supply pharmaceutical blister films into Belgian drug packaging lines. Amcor PLC anchors global R&D spending on recyclable flexible formats, positioning its Benelux operations as a testbed for circular packaging pilots. Berry Global Inc competes through scale in stretch and shrink films serving Dutch horticultural export packaging.
Flexible plastic packaging denotes pliable polymer-based containment systems—typically under 250 micrometers in thickness—that conform to product shape through forming, filling, and sealing operations, with primary functions including moisture barrier, oxygen exclusion, and mechanical protection during distribution. Pouches and films dominate volume flows in the Benelux corridor, with pouches capturing margin pools in premium personal care sachets and retort food applications while films sustain commodity throughput in agricultural and industrial wrapping. Bioplastics represent the fastest-expanding material category, though polyethylene retains volume leadership across thin and medium gauge specifications.
The EU Packaging and Packaging Waste Regulation and REACH compliance obligations enforced by ECHA are mandating recycled content thresholds and restricting certain additive chemistries, forcing converters to reformulate sealant layers and validate new substrate combinations. Belgium's Flanders region operates extended producer responsibility schemes that penalize non-recyclable flexible formats, while Dutch regulators align with the EU Green Deal's plastic reduction targets. Stakeholders must monitor how the EU AI Act's traceability requirements intersect with packaging serialization mandates, particularly as pharmaceutical end-use demands unit-level tracking.
Market Dynamics
Mono-material polyethylene structures are displacing complex multi-layer laminates across Benelux converting lines as ECHA-enforced REACH compliance and the EU Packaging and Packaging Waste Regulation tighten recycled content mandates. Dutch food processors and Belgian pharmaceutical packagers now face reformulation deadlines that favor simplified polymer streams over barrier-rich heritage designs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds force converters toward mono-material PE and PP structures that mechanical recycling infrastructure can process, accelerating substrate simplification across Flanders and the Netherlands.
- Rotterdam logistics clustering:The port's film distribution hub reduces inland transport costs for German and French converters sourcing Benelux-produced rollstock, concentrating procurement decisions in the Randstad region.
- Retort pouch expansion:Dutch ready-to-eal meal processors are migrating from rigid trays to high-barrier pouches, driving demand for coextruded PA/PE films with improved thermal resistance.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in the Antwerp-Rotterdam-Amsterdam refining corridor swing with Brent crude differentials, compressing converter margins on thin-gauge commodity film contracts.
- Mechanical recycling contamination limits:Current sorting infrastructure cannot handle adhesive-labeled flexibles or metallized laminates, stranding legacy packaging formats without circular pathways.
- Bioplastics cost premium:PLA and bio-PE resins trade at multiples of fossil-derived polyethylene, limiting penetration beyond premium personal care sachets and certified organic food lines.
Strategic Opportunities
- Dutch horticultural export packaging:Belgian and Luxembourg converters can capture stretch film demand from Westland greenhouse clusters shipping potted plants and cut flowers to German retail chains.
- Digital watermark integration:HolyGrail 2.0 sorting technology convergence with blockchain traceability platforms enables premium pricing for packaging with verified recycled content claims.
- Luxembourg pharmaceutical serialization:The EU AI Act's traceability requirements intersect with FMD mandates, creating demand for unit-dose blister films with embedded authentication features.
Industry Challenges
- Multi-layer delamination expertise:Converters lack sufficient polymer scientists capable of reformulating adhesive tie layers that maintain barrier performance while enabling mechanical recycling.
- Recycled content certification timelines:ECHA validation of post-consumer feedstock streams for food-contact applications extends qualification cycles by 18-24 months.
- Legacy extrusion asset retrofitting:Coextrusion lines designed for seven-layer barrier films require capital-intensive rebuilds to run mono-material structures at commercial yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Flexible Plastic Packaging Market |
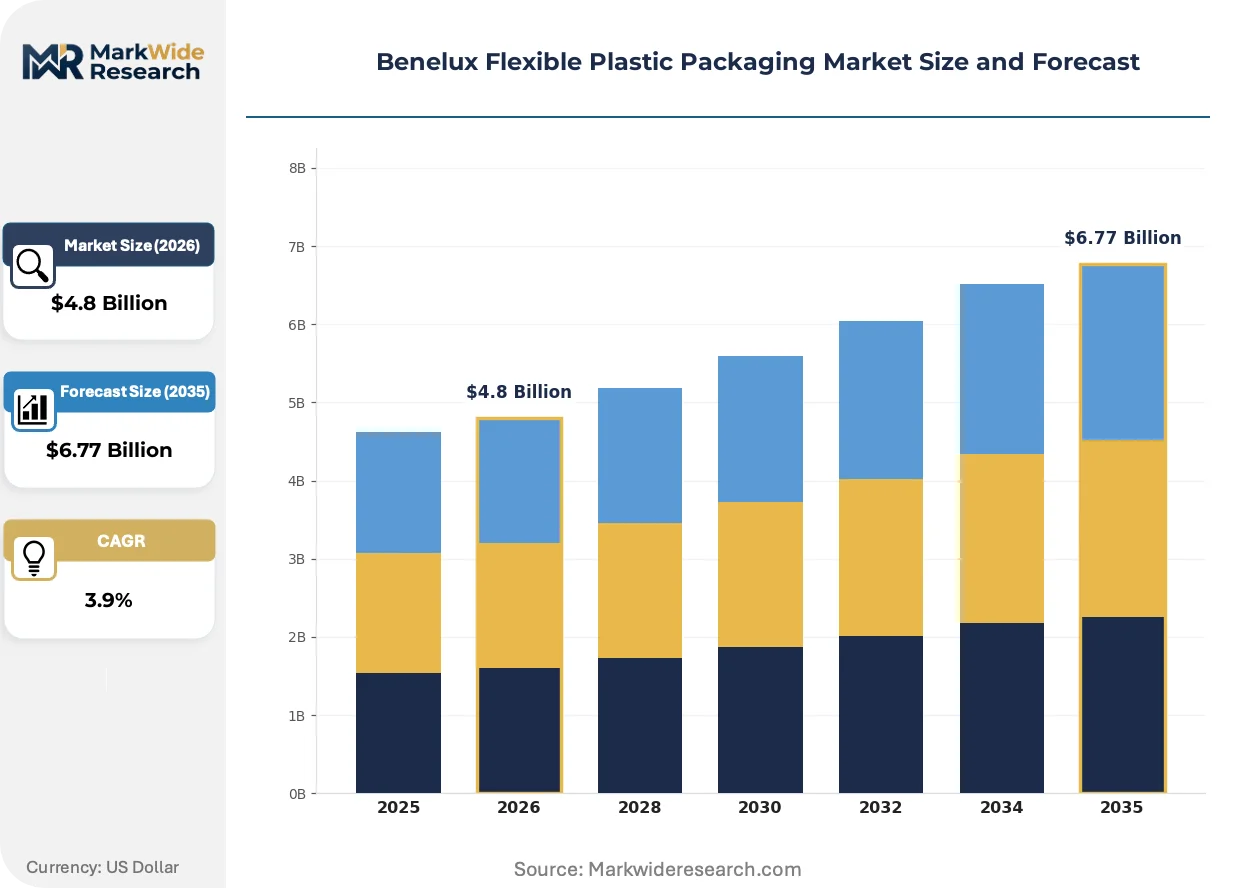
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps End Use Industry: Food, Beverage, Personal Care, Pharmaceuticals Material: Polyethylene, Polypropylene, Polyester, Bioplastics Thickness: Thin, Medium, Thick, Multi-Layer |
| Companies Covered | Sonoco Products Company, Constantia Flexibles, Amcor PLC, Berry Global Inc, Optimum Group, Berlin Packaging Netherlands BV, Epoca Products SA, Sudpack Holding GmbH, Huhtamaki, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Flexible Plastic Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability that regulatory frameworks now mandate. These shifts favor nimble mid-scale converters over high-volume commodity specialists.
Water-based barrier coatings applied to mono-material PE substrates are rendering obsolete aluminum oxide metallized films that require energy-intensive vacuum deposition and complicate mechanical recycling streams. Dutch personal care brands and Belgian dairy processors are piloting these coatings at 10,000-unit test scales. The technology is compressing lead times from 12-week gravure cylinder production to 48-hour digital plateless runs.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) in food-contact materials are forcing reformulation of grease-resistant paper and board laminates used in Belgian quick-service packaging. ECHA's 2023 restriction proposal targets fluorinated barriers in popcorn bags and bakery wraps. Dutch converters are responding with clay-based mineral coatings and bio-wax barriers that sacrifice some oil resistance for regulatory compliance.
Consolidated buying desks at Albert Heijn, Colruyt, and Delhaize are unbundling packaging procurement from finished goods contracts, inserting direct converter relationships that bypass traditional brand-owner specification control. This disintermediation concentrates volume with approved supplier lists of 3-5 film vendors per substrate category. The shift is most visible in Dutch private-label fresh produce, where retail technical teams now specify breathable film specifications directly.
Benelux Flexible Plastic Packaging Market Segmentation
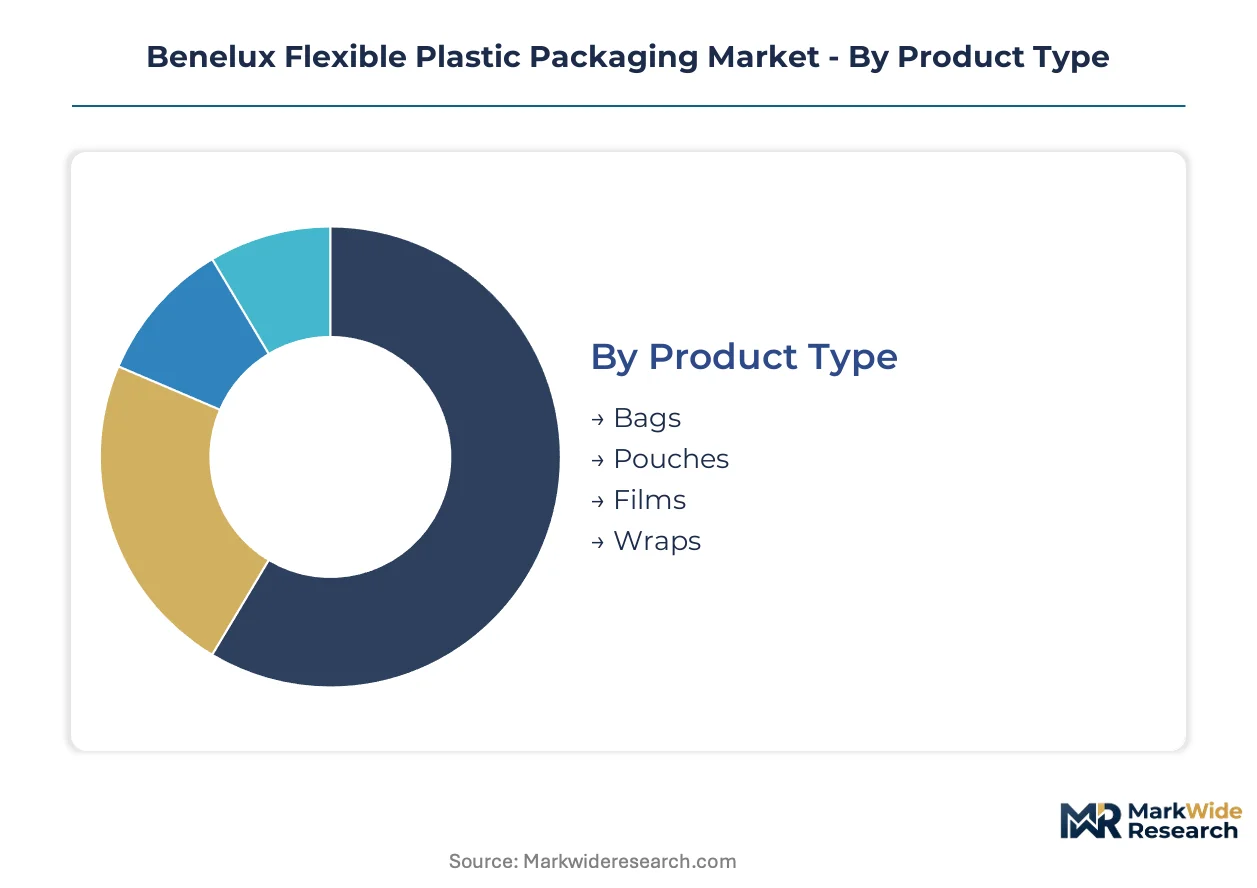
Flexible plastic packaging in Benelux demands granular segmentation because Rotterdam's logistics hub concentrates procurement decisions while EU Packaging and Packaging Waste Regulation mandates reshape substrate choices across Dutch, Belgian, and Luxembourg converters.
Product Type:
Converters across the Randstad region and Flanders corridor supply formats ranging from commodity wraps to precision-engineered pouches, with each product type commanding distinct margin profiles and technical specifications.
- Pouches:High-barrier coextruded structures with PA/PE or EVOH layers enable retort sterilization for Dutch ready-to-eat meal processors. Demand concentrates in premium personal care sachets and pharmaceutical unit-dose formats where shelf differentiation justifies higher substrate costs.
- Films:Stretch and shrink formulations dominate volume flows, serving Westland greenhouse clusters shipping horticultural exports to German retail chains. Belgian converters supply breathable OPP films for fresh produce display packs specified directly by Albert Heijn and Colruyte technical teams.
- Bags:Side-seal and bottom-gusset configurations handle bulk agricultural inputs and industrial components, with Flanders extruders specializing in UV-stabilized polyethylene for outdoor storage applications.
- Wraps:Cling film and industrial pallet wrap sustain commodity throughput, though ECHA REACH restrictions on phthalate plasticizers force reformulation of food-contact grades.
Established volume favors Films; emerging adoption favors Pouches.
End Use Industry:
Customer concentration in Dutch retail buying desks and Belgian pharmaceutical clusters creates divergent specification pressures across end-use segments.
- Food:Dutch processors migrating from rigid trays to flexible retort pouches drive coextruded barrier film demand, while Flanders dairy operations specify breathable films for cheese ripening applications.
- Pharmaceuticals:Belgian blister packaging lines serving European drug distribution require cold-form foil laminates and high-barrier PVC/PVDC structures, with Luxembourg serialization mandates adding traceability layer complexity.
- Personal Care:Premium sachets and sample formats utilize digital printing compatibility for short-run customization, with Dutch brands piloting bio-based PE at 10,000-unit test scales.
- Beverage:Stand-up pouches with fitment closures gain share in smoothie and dairy alternative segments, though carbonated applications remain limited by CO2 barrier constraints.
Food commands current procurement volume; Pharmaceuticals offers steepest margin expansion trajectory.
Material:
Substrate selection in Benelux converts under mechanical recycling infrastructure limitations and ECHA-enforced recycled content thresholds.
- Polyethylene:Mono-material LDPE and LLDPE structures dominate thin and medium gauge specifications, with Dutch converters leading substrate simplification to enable mechanical recycling compatibility.
- Bioplastics:PLA and bio-PE resins expand most quickly in certified organic food lines and premium personal care, though cost multiples limit penetration beyond niche applications.
- Polypropylene:Cast and oriented PP films serve high-clarity food display and pharmaceutical blister applications, with Belgian converters specializing in metallized variants for barrier enhancement.
- Polyester:PET films provide dimensional stability and printability for lidding and industrial applications, though crystallinity challenges complicate flexible format processing.
Polyethylene anchors installed capacity; Bioplastics captures specification attention.
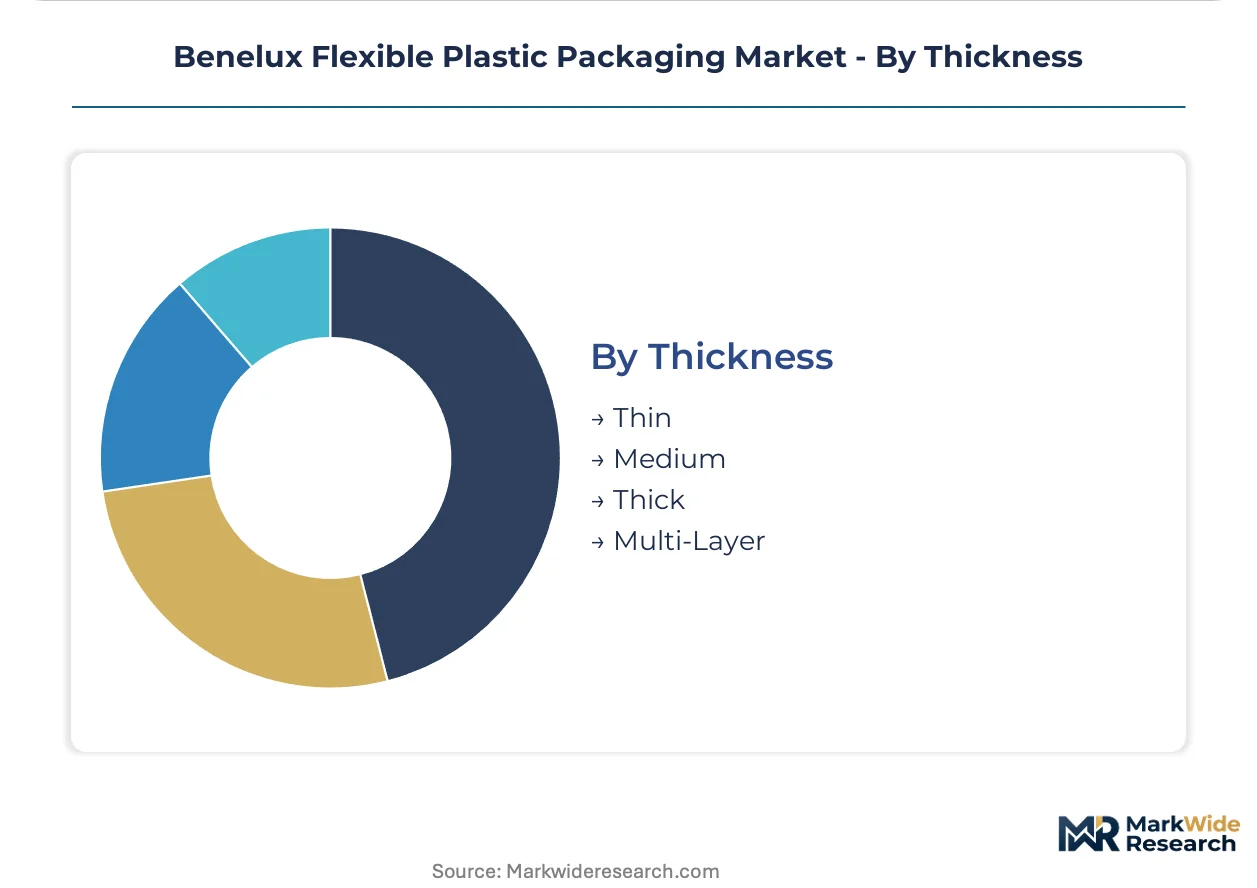
Thickness:
Gauge selection reflects the tension between downgauging economics and barrier performance requirements across Benelux converting lines.
- Thin:Sub-50 micrometer specifications serve overwrap and label applications where material cost minimization outweighs structural rigidity needs.
- Multi-Layer:Coextruded and laminated structures above 150 micrometers combine EVOH or aluminum oxide barriers for pharmaceutical and retort food applications, though recycling complexity faces EPR penalties in Flanders.
- Medium:50-150 micrometer range balances processability with functional performance across the majority of food and industrial formats.
- Thick:Heavy-duty specifications above 200 micrometers serve chemical and construction material containment with puncture resistance priorities.
Medium gauge sustains production throughput; Multi-Layer faces regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's film distribution hub channels Benelux-produced rollstock to German and French converters, concentrating procurement decisions in the Randstad corridor while Dutch and Belgian regulators enforce divergent extended producer responsibility schemes.
Netherlands
Dutch food processors migrating from rigid trays to retort pouches drive coextruded barrier film demand, while the national packaging authority aligns with EU Green Deal plastic reduction targets. Westland greenhouse clusters in the Randstad region source stretch films for horticultural exports to German retail chains.
Belgium
Flanders dairy operations specify breathable films for cheese ripening applications, and the regional extended producer responsibility scheme penalizes non-recyclable flexible formats. Antwerp-Rotterdam-Amsterdam refining corridor naphtha crackers supply ethylene feedstock to Belgian extrusion lines.
Luxembourg
Pharmaceutical serialization mandates from the EU AI Act intersect with FMD traceability requirements, creating demand for unit-dose blister films. The Grand Duchy's financial services infrastructure supports packaging procurement platforms serving cross-border drug distribution.
Germany
German converters source Benelux-produced mono-material PE structures to meet national recycled content quotas under the EU Packaging and Packaging Waste Regulation. North Rhine-Westphalia chemical clusters import Dutch rollstock for downstream converting operations.
France
French food packagers procure high-barrier pouches from Belgian suppliers to serve ready-to-eal meal retail chains. The national environmental agency enforces REACH compliance on imported flexible packaging formats.
Benelux Flexible Plastic Packaging Market Competitive Landscape
On the supply side, the industry is moderately consolidated with global diversified packaging groups operating alongside specialized regional converters. Three strategic archetypes dominate: multinational film and converter conglomerates with integrated European supply chains, mid-scale national specialists focused on substrate simplification, and horticultural packaging providers serving Dutch export agriculture. Competitive moves center on mechanical recycling compatibility investments and direct retail procurement relationships that bypass traditional brand-owner specification control.
Among Benelux-based and European-anchored packaging groups, Constantia Flexibles, Amcor PLC, and Berry Global Inc represent the dominant competitive set. Constantia Flexibles anchors pharmaceutical and food packaging supply through its Austrian-headquartered European network. Amcor PLC exemplifies global R&D investment in recyclable flexible formats with Benelux operations serving as circular packaging testbeds. Berry Global Inc occupies the scale-driven position in stretch and shrink films for agricultural export applications.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Constantia Flexibles |
| Amcor PLC |
| Berry Global Inc |
| Optimum Group |
| Berlin Packaging Netherlands BV |
| Epoca Products SA |
| Sudpack Holding GmbH |
| Huhtamaki |
| Others |
Pricing and Supply Chain Analysis
Rotterdam's port-centric film distribution cluster concentrates polyethylene rollstock capacity within a 50-kilometer radius, granting Dutch extruders disproportionate leverage over German and French converters who lack alternative sourcing within equivalent transport economics. This geographic chokepoint enables Randstad-based suppliers to extract premium pricing on mono-material specifications while commodity film margins compress under naphtha feedstock volatility.
Pricing Analysis
Digital printing technology generation gaps separate incumbent gravure-based converters from next-generation plateless operations, with the latter commanding 15-20 percent premiums on short-run personal care sachets despite lower unit production costs. Three-tier pricing structure across premium certified-recycled, standard virgin-content, and economy commodity grades reflects ECHA validation status and volume scale. Pricing pressure stems from consolidated retail buying desks at Albert Heijn and Colruyt unbundling procurement from finished goods contracts. Food processors exhibit highest price sensitivity due to thin margins on private-label produce, while pharmaceutical packers absorb premiums for serialization-ready blister films.
Supply Chain Analysis
Extended payment terms stretching to 90 days from Belgian dairy processors and Dutch retail chains strain working capital across Flanders converting operations, with supply-chain finance facilities increasingly intermediating resin procurement. Ethylene feedstock draws from Antwerp-Rotterdam-Amsterdam refining corridor naphtha crackers, with EVOH barrier resins and bio-PE specialty grades imported from Germany and Austria. Single-source vulnerability concentrates in metallized film deposition equipment, where two European OEMs control installed base maintenance. Distribution runs through Rotterdam's bonded warehousing directly to North Rhine-Westphalia chemical clusters and Paris Basin food packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that obsolete multi-layer heritage designs, creating a high-growth disruption window for substrate-simplification specialists. This regulatory inflection compresses reformulation timelines to 18-24 months while ECHA validation bottlenecks constrain qualified supplier pools.
For Market Incumbents: Build mechanical recycling compatibility moats through captive post-consumer feedstock partnerships with Flanders extended producer responsibility schemes. Retrofit coextrusion assets for mono-material PE structures at commercial yields before legacy seven-layer lines strand. Threat from Dutch horticultural export packagers bypassing traditional converters for direct Chinese film sourcing necessitates backward integration into resin compounding. Certification investment in ECHA food-contact validation secures preferred supplier status with consolidated retail buying desks.
For New Entrants and Emerging Players: Mid-scale digital printing operations serving Belgian pharmaceutical serialization and Dutch personal care sample markets represent the most penetrable entry point given minimum order quantity compression and 48-hour turnaround capabilities. Luxembourg unit-dose blister films with embedded authentication features offer steepest margin expansion trajectory amid EU AI Act traceability convergence. Go-to-market angle should target direct relationships with Albert Heijn and Colruyt technical teams that now specify breathable film specifications independently of brand owners.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with digital printing assets and validated mono-material substrate portfolios over legacy gravure-dependent operations with stranded multi-layer expertise. Long-term viability across the next decade hinges on ECHA food-contact certification depth and direct retail procurement relationships. Acquisition target archetype: Flanders-based mid-cap specialists with 5,000-15,000 tonne annual capacity and active HolyGrail 2.0 digital watermark pilots. Signal to watch is ECHA restriction proposal finalization on per- and polyfluoroalkyl substances, which would accelerate clay-based barrier coating adoption and obsolete fluorinated film inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Substrate Transition | ECHA-enforced recycling mandates render multi-layer laminates economically unviable across Flanders and Netherlands. |
| Digital Printing Platform Integration | HolyGrail 2.0 watermark convergence with blockchain traceability enables premium pricing for verified recycled content claims. |
| Backward Integration into Resin Compounding | Captive bio-PE and recycled feedstock supply hedges against naphtha-cracker margin volatility in Antwerp-Rotterdam corridor. |
| Direct Retail Procurement Relationships | Bypassing brand-owner specification control captures volume from unbundled Albert Heijn and Colruyt buying desks. |
| Pharmaceutical Serialization Capability Buildout | EU AI Act traceability intersection with FMD mandates creates demand for unit-dose blister films with embedded authentication. |
Research Methodology
Desk research of EU regulatory filings, ECHA restriction proposals, and trade flow databases preceded structured interviews with plant managers at Dutch extrusion facilities, procurement leads at Belgian dairy processors, technical specification directors at consolidated retail buying desks, and regulatory affairs specialists navigating REACH compliance. Secondary validation drew from customs records tracking polyethylene rollstock movements through Rotterdam, SEC filings of listed packaging groups, and extended producer responsibility scheme reports from Flanders and Netherlands authorities. Bottom-up capacity assessments across Randstad converting operations were triangulated against top-down demand estimates from horticultural export and ready-to-eat meal processing clusters.
Assumptions held fixed include EU Packaging and Packaging Waste Regulation recycled content thresholds, ECHA enforcement timelines for per- and polyfluoroalkyl substance restrictions, and Rotterdam port capacity for film distribution logistics. Variables stress-tested across the projection horizon encompass naphtha-cracker margin volatility, bio-PE resin cost multiples, and digital printing adoption curves. Segmentation dimensions modeled include product type, end-use industry, material substrate, and thickness gauge, with regional procurement clustering as an industry-specific overlay. CAGRs were derived from elasticity-adjusted volume projections tied to downstream food processing and pharmaceutical packaging demand.
Stress conditions across ethylene feedstock pricing, ECHA validation backlog durations, and consolidated retail buyer concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and mechanical recycling infrastructure deployment. Macroeconomic deviation, regulatory acceleration or delay, or breakthrough barrier coating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market