
 Europe Flexible Packaging Market | 2026-2036
Europe Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flexible Packaging Market Analysis
Market Context
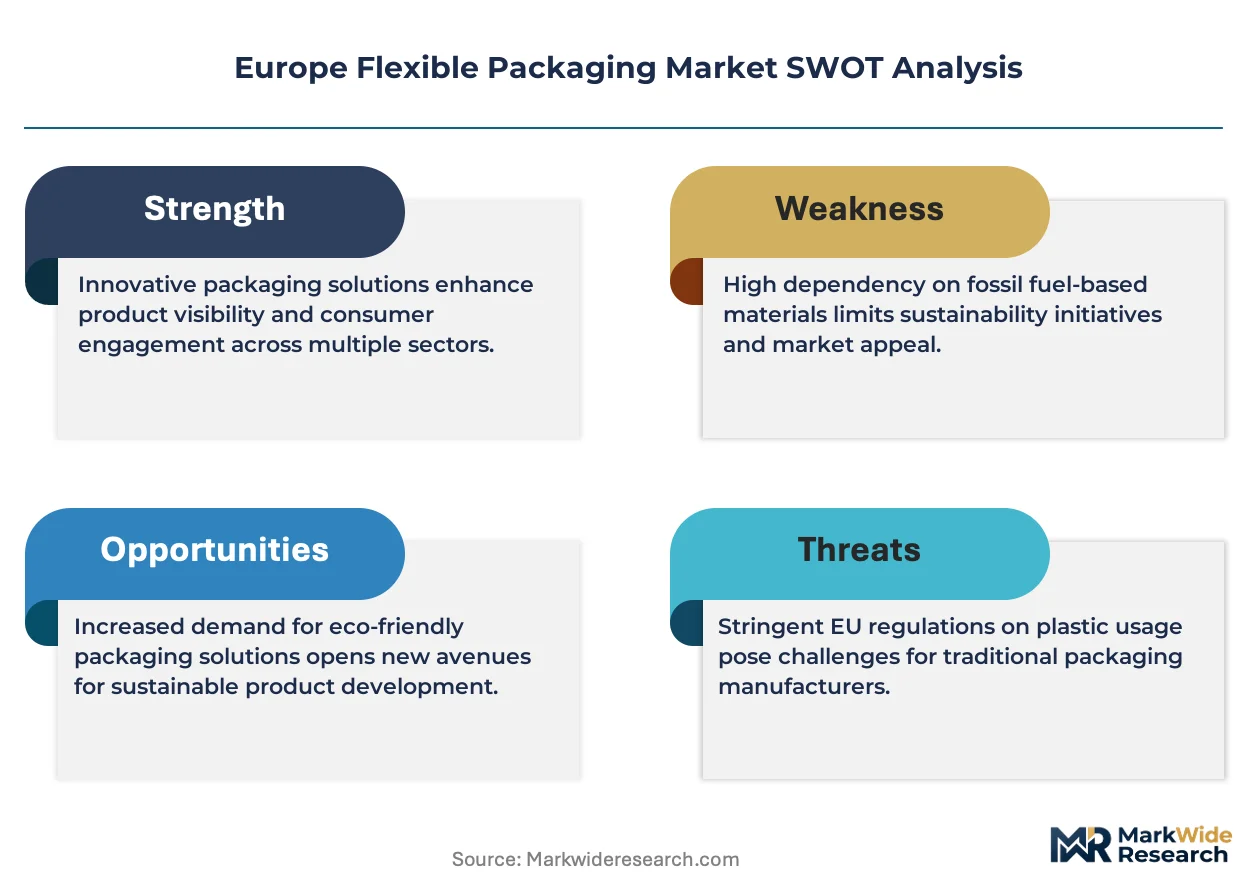
Modular pouch configurations is restructuring buyer procurement across European food and personal care supply chains. Huhtamaki Oyj leverages its Nordic manufacturing footprint to dominate barrier-film supply for dairy applications. Mondi Group anchors its position through integrated kraft paper and flexible film operations. Constantia Flexibles specializes in pharmaceutical blister lidding and cold-form foils across Central European plants.
Technical Definition and Segment Structure
Europe Flexible Packaging comprises pliable substrates—typically polyethylene, polypropylene, or laminated combinations below 250 micrometres—that conform to product shape during filling, sealing, and distribution. These structures provide moisture barriers, oxygen scavenging, and printability for shelf-ready presentation. Plastic films and pouches lead volume due to their dominance in food retail and e-commerce fulfillment, while aluminum foil laminates command premium margins in pharmaceutical barrier applications. Paper-based segments are gaining structural share as brand owners reformulate packaging to meet recyclability thresholds.
Regulatory Framework
The EU Packaging and Packaging Waste Regulation, REACH chemical restrictions, and EFSA food-contact compliance frameworks collectively dictate material substitution timelines and recyclability claims across European supply chains. ECHA substance evaluations are forcing reformulation of certain plasticizers and adhesives, redirecting R&D spend toward approved alternatives. Stakeholders must monitor delegated acts under the EU Green Deal that will set mandatory recycled content floors for flexible formats.
Market Dynamics
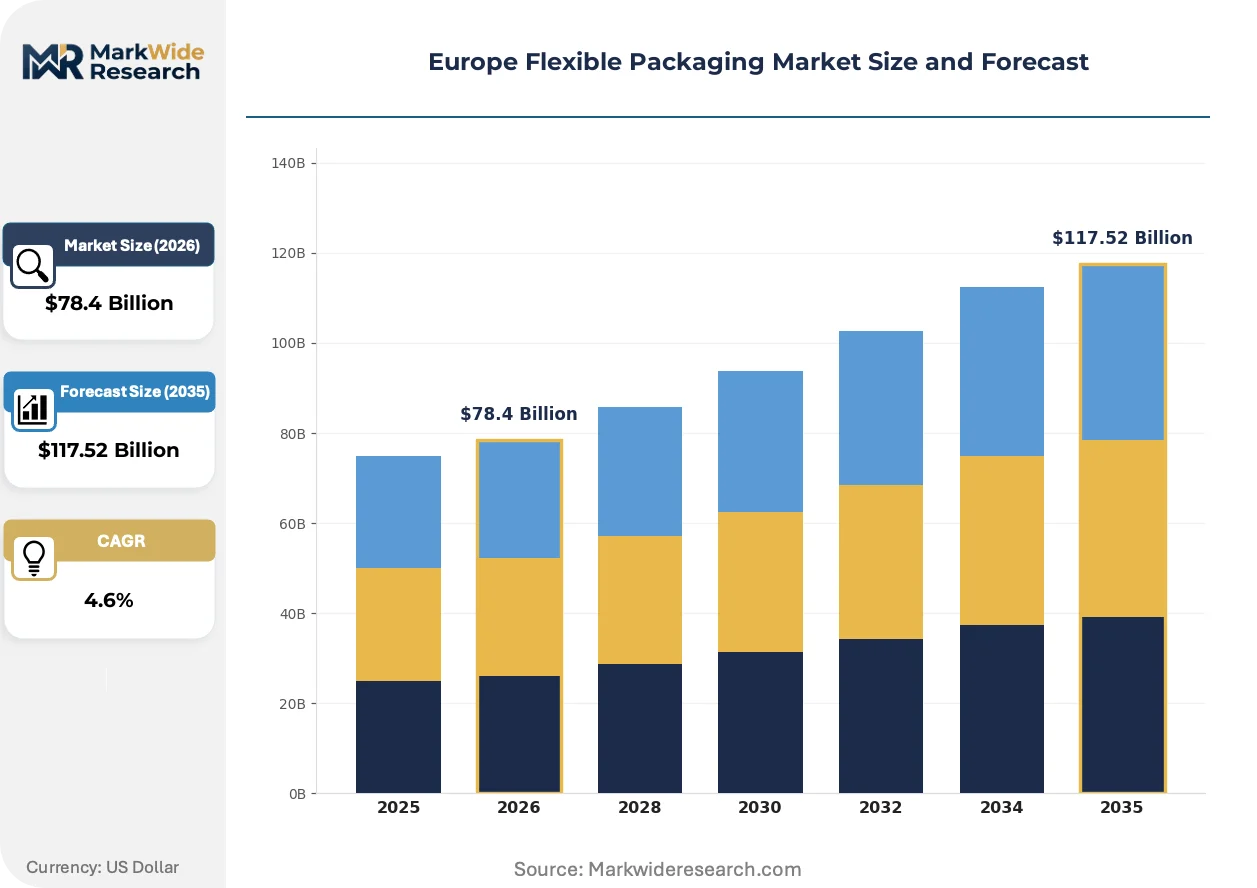
Mono-material film structures are displacing multi-layer laminates across European food and pharmaceutical supply chains as recyclability mandates harden under the EU Packaging and Packaging Waste Regulation.
Growth Catalysts
- EU Green Deal packaging mandates:Mandatory recycled content floors for flexible formats are redirecting capital toward compatible extrusion and printing lines.
- Pouch-based ready-to-eat formats:German food processors are expanding retort-capable stand-up pouch lines for chilled meal solutions.
- Barrier film substitution in dairy:Ethylene vinyl alcohol copolymers and metallized polyethylene terephthalate are capturing oxygen-sensitive applications previously served by aluminum laminates.
Market Restraints
- Polypropylene resin concentration:European polymer supply hinges on a limited set of crackers in the ARA region, exposing converters to feedstock volatility.
- Multi-layer technical lock-in:Existing high-barrier lines cannot accommodate mono-material structures without substantial retooling of sealing jaws and forming collars.
- ECHA substance evaluations:Restrictions on certain phthalate plasticizers and epoxy-based adhesives are forcing qualified material requalification cycles.
Strategic Opportunities
- Central European pharmaceutical cold-chain:Temperature-indicating flexible formats for biologics distribution remain underdeveloped in Poland and Czechia.
- Digital watermark integration:HolyGrail 2.0 sorting trials are creating first-mover advantage for converters embedding machine-readable markers in polyethylene films.
- Italy's cosmetic sample sachet conversion:Single-dose flexible formats for premium skincare are migrating from multi-layer to recyclable polyethylene structures.
Industry Challenges
- Mono-material barrier engineering:Matching oxygen transmission rates of aluminum foil laminates with polymer-only structures requires nanocomposite expertise that remains scarce.
- Extended producer responsibility accounting:National packaging registries in France, Germany, and Italy impose divergent reporting formats that complicate pan-European product stewardship.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flexible Packaging Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Laminates Material: Plastic, Paper, Aluminum Foil, Composites End User: Food & Beverage, Healthcare, Personal Care, Industrial Application: Retail, E-commerce, Food Service, Bulk Packaging |
| Companies Covered | Huhtamaki Oyj, Coveris, Amcor PLC, ProAmpac, Bischof + Klein, Mondi Group, Constantia Flexibles, Berry Global Group, Wipak Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flexible Packaging Market Emerging Trajectories
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability demanded by food safety auditors and pharmaceutical regulators.
Water-based flexographic ink systems are modularizing short-run production for private-label food brands. Retailers in France and the Netherlands are adopting these systems to compress new product introduction cycles from twelve weeks to under four. The technology is modularizing converter capacity allocation, enabling shared production slots across multiple brand owners.
REACH chemical restrictions are forcing systematic substitution of bisphenol-derived coatings in food-contact films. ECHA's 2024 substance evaluation roadmap has accelerated migration testing protocols for can coatings and lidding structures. Pharmaceutical blister applications are responding fastest, with cold-form foil suppliers reformulating polyamide-based contact layers ahead of enforcement deadlines.
Consolidated retail procurement is concentrating flexible packaging specification authority among fewer buying centers. Discounters in Germany and hard-format specialists in Scandinavia are unbundling design, material, and logistics decisions that converters previously negotiated separately. This concentration is most visible in private-label dairy, where three retail groups now dictate barrier specifications across northern European supply bases.
Europe Flexible Packaging Market Segmentation
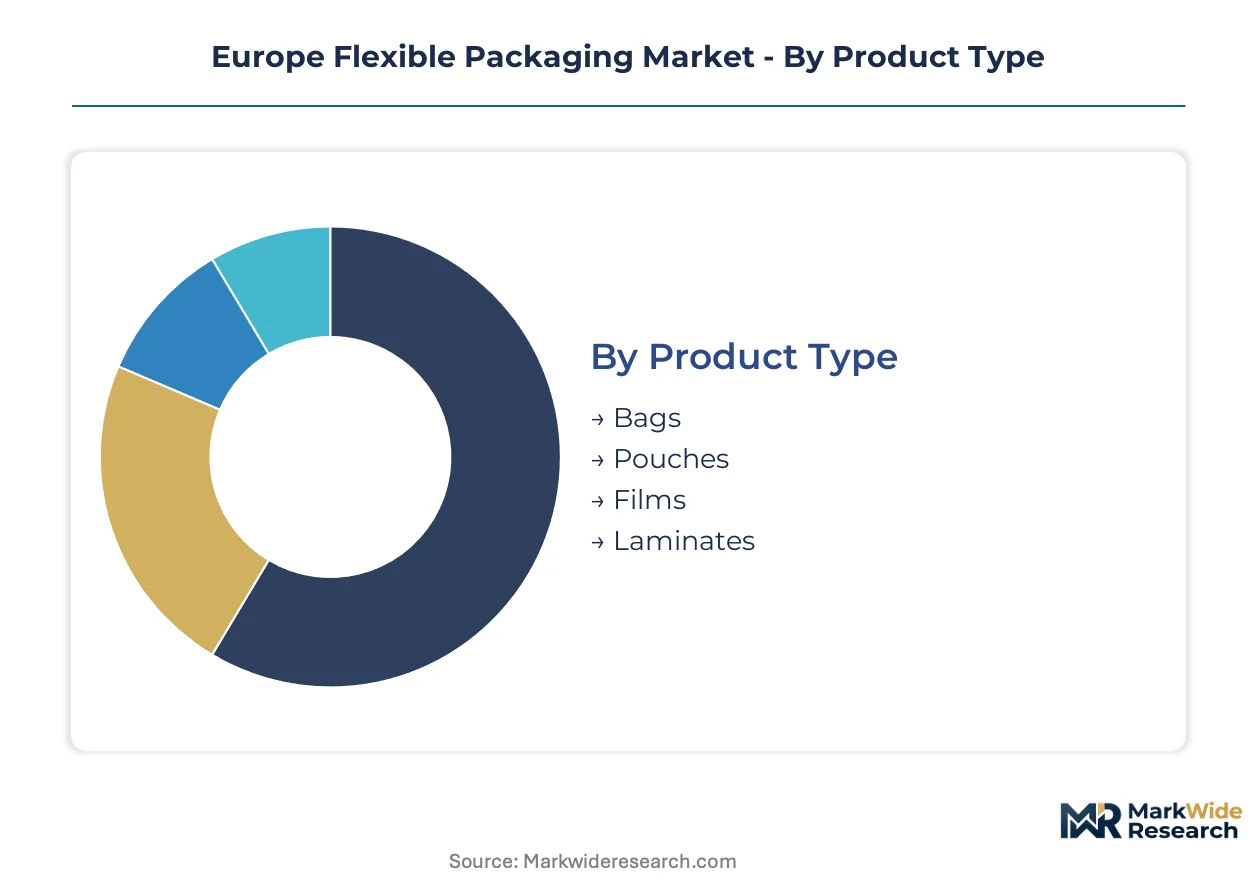
Segmentation in European flexible packaging reveals how regulatory pressure and supply chain reconfiguration are fragmenting procurement patterns across converter tiers. Material substitution timelines and recyclability mandates now dictate which product formats capture capital allocation from brand owners.
Product Type:
Supply concentration among German and Italian converters favors pouch and film formats with scalable extrusion infrastructure.
- Pouches:Stand-up and retort-capable configurations dominate ready-to-eat meal applications. German food processors are expanding pouch lines for chilled meal solutions under tightening EU Packaging and Packaging Waste Regulation compliance deadlines.
- Films:Cast and blown polyethylene structures serve high-volume food retail and e-commerce fulfillment. Demand clusters in France and the Netherlands where retailers are compressing new product introduction cycles through digital printing integration.
- Bags:Gusseted and wicketed formats persist in bakery and produce applications across Central European retail chains.
- Laminates:Multi-layer aluminum and polymer combinations retain pharmaceutical barrier applications despite recyclability pressures.
Today's leader: Films. Tomorrow's challenger: Pouches.
Material:
Cost tier differentiation separates commodity polymer supply from certified recyclable and pharmaceutical-grade alternatives.
- Plastic:Polyethylene and polypropylene films command volume leadership through conversion efficiency. European polymer supply hinges on ARA region crackers, exposing converters to feedstock volatility that shapes margin structures.
- Paper:Kraft and glassine substrates are gaining structural share as brand owners reformulate packaging to meet EU Green Deal recyclability thresholds. Nordic integrated producers anchor supply through captive pulp and paper operations.
- Aluminum Foil:Cold-form and blister lidding applications retain premium positioning in pharmaceutical barrier segments despite ECHA pressure on processing chemistry.
- Composites:Fiber-based hybrid structures are emerging as technical intermediates between full plastic and paper solutions.
Plastic retains volume dominance. Paper climbs the fastest on regulatory tailwinds.
End User:
Application maturity varies sharply across customer types, with food and beverage procurement cycles running shortest and pharmaceutical qualification protocols longest.
- Food & Beverage:Dairy, meat, and ready-to-eat categories drive pouch and barrier film specification. Consolidated retail procurement in Germany and Scandinavia is concentrating buying authority among fewer decision centers.
- Healthcare:Pharmaceutical blister and cold-form foil demand concentrates in Central European plants with EMA compliance certification. Temperature-indicating formats for biologics remain underdeveloped in Poland and Czechia.
- Personal Care:Single-dose sachets for premium skincare are migrating from multi-layer to recyclable polyethylene structures, with Italian cosmetic brands leading conversion.
- Industrial:Heavy-duty shipping sacks and FIBC liners serve construction and chemical distribution with lower barrier requirements.
Food and beverage anchors current volume. Healthcare offers the steepest expansion trajectory on cold-chain biologics growth.
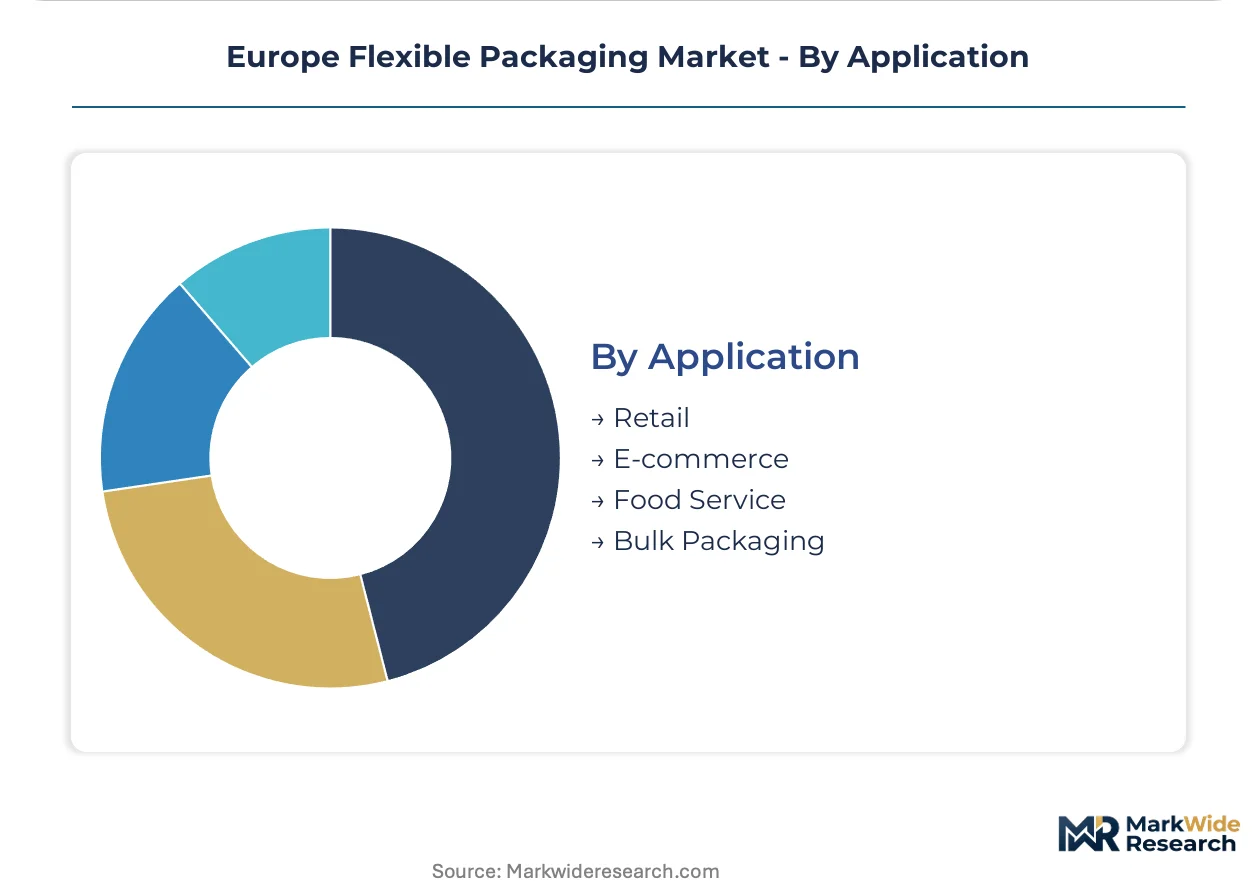
Application:
Customer type fragmentation separates high-frequency retail replenishment from project-based bulk procurement with diverging service expectations.
- Retail:Shelf-ready presentation and print quality specifications dominate private-label dairy and fresh produce across French and German supermarket chains.
- E-commerce:Lightweight, damage-resistant formats are displacing corrugated alternatives in fulfillment networks. Dutch and Belgian distribution hubs are piloting digital watermark integration for automated sorting.
- Food Service:Portion-control pouches and dispensing bags serve institutional catering with standardized volume requirements.
- Bulk Packaging:FIBCs and industrial liners serve chemical and agricultural supply chains with extended production runs and lower SKU complexity.
Retail commands specification authority. E-commerce gains share fastest on fulfillment network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible packaging manufacturing first scaled in Germany's post-war chemical corridor, where polyethylene extrusion lines clustered around the ARA refining hub. This industrial lineage shaped European converter geography for decades.
Germany
Retort-capable pouch demand from chilled meal processors drives specification intensity in Bavaria and North Rhine-Westphalia. The EU Packaging and Packaging Waste Regulation accelerates mono-material conversion timelines for converters serving Aldi and Lidl procurement centers. Hamburg anchors barrier film supply for Nordic dairy export markets.
France
Consolidated retail buying at Carrefour and Intermarché concentrates private-label dairy packaging decisions in Île-de-France. ECHA substance evaluations on phthalate plasticizers force reformulation of lidding structures for cheese applications. The Auvergne-Rhône-Alpes corridor hosts specialized converters for pharmaceutical blister formats.
Italy
Premium cosmetic sachet conversion from multi-layer to recyclable polyethylene structures concentrates demand in Lombardy and Emilia-Romagna. The EU Green Deal recyclability thresholds push brand owners toward certified mono-material alternatives. Bologna-area converters supply single-dose formats for luxury skincare brands.
Netherlands
E-commerce fulfillment network expansion drives lightweight mailer film specification around Rotterdam and Amsterdam distribution hubs. Digital watermark integration for automated sorting trials creates pilot demand for HolyGrail 2.0-compatible polyethylene structures. Dutch retailers compress new product introduction cycles through shared digital printing slots.
Poland
Temperature-indicating flexible formats for biologics distribution remain underdeveloped relative to cold-chain infrastructure growth in Warsaw and Kraków clusters. EMA compliance certification requirements extend qualification timelines for pharmaceutical converters. Central European plants serve as cost-competitive alternatives for standard barrier film production.
Europe Flexible Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier technology and regulatory certification dimensions. The vendor base separates into integrated pulp-to-film operators, specialized pharmaceutical barrier suppliers, and regional pouch converters serving private-label retail. Three archetypes dominate: Nordic integrated paper-film hybrids, Central European pharmaceutical specialists, and scale-driven polymer converters. M&A activity concentrates on mono-material technology acquisition, while capacity expansion targets recyclable extrusion lines in Germany and Poland.
Among Nordic integrated operators, Huhtamaki Oyj and Mondi Group exemplify the backward-integrated archetype with captive pulp and polymer supply chains. Constantia Flexibles occupies a position within the pharmaceutical barrier tier, anchoring cold-form foil and blister lidding specialization across Central European manufacturing footprints.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Coveris |
| Amcor PLC |
| ProAmpac |
| Bischof + Klein |
| Mondi Group |
| Constantia Flexibles |
| Berry Global Group |
| Wipak Group |
| Others |
Supply Flow & Price Mechanics
Polyethylene resin costs cascade through three distinct pricing tiers as converters pass ARA feedstock volatility downstream to brand owners with varying contract structures. German dairy processors and French retail buying centers absorb these fluctuations differently depending on volume commitments and barrier specification complexity.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships between major converters and consolidated retail groups across Germany and France. Price differentiation rests on certification grade—EFSA food-contact compliance and EU Green Deal recyclability thresholds separate premium mono-material supply from standard multi-layer alternatives. Pricing pressure stems from polypropylene resin concentration in the ARA region, squeezing margin structures for mid-tier converters without backward-integrated polymer supply. Discounters in Germany exhibit highest price sensitivity, while pharmaceutical barrier specialists in Central Europe maintain lowest sensitivity due to extended qualification protocols and premium positioning.
Supply Chain Analysis
EMA and EFSA certification requirements gate supply relationships, extending qualification timelines for pharmaceutical and food-contact applications. Manufacturing concentrates in Germany, France, and Italy where extrusion infrastructure clusters around historical chemical corridors. Raw material dependencies draw from ARA region polymer crackers, Nordic pulp operations for paper-based substrates, and specialized aluminum rolling mills for pharmaceutical foil. Single-source vulnerability runs through polypropylene supply given limited European cracking capacity. Distribution runs through converter-direct relationships with consolidated retail procurement centers and pharmaceutical OEM supply bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Flexible Packaging Market compounds steadily as regulatory mandates force systematic material substitution across food and pharmaceutical supply chains. EU Packaging and Packaging Waste Regulation compliance deadlines create predictable demand visibility for qualified converters.
For Market Incumbents: To counter margin compression from resin volatility, Huhtamaki Oyj and Mondi Group should deepen backward integration into Nordic pulp and captive polymer supply. Incumbents must also accelerate mono-material R&D to defend specification authority as Aldi and Lidl procurement centers harden recyclability requirements. For New Entrants and Emerging Players: Begin with temperature-indicating flexible formats for biologics distribution in Poland and Czechia, where cold-chain infrastructure outpaces qualified converter supply. Target Italian cosmetic sample sachet conversion as the most penetrable segment, leveraging HolyGrail 2.0 digital watermark integration as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mono-material technical expertise concentrates among mid-cap specialists without scale. Five-to-ten year viability favors converters with EMA certification and EU Green Deal-aligned product pipelines. Watch for delegated acts establishing mandatory recycled content floors as the inflection signal triggering accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Investment | EU Packaging and Packaging Waste Regulation compliance secures specification authority with German retail buying centers. |
| Digital Watermark Integration | HolyGrail 2.0 compatibility creates first-mover positioning for automated sorting trials in Dutch distribution hubs. |
| Pharmaceutical Barrier Certification | EMA compliance opens cold-form foil and blister lidding opportunities in Central European biologics supply chains. |
| Backward Integration into Polymer Supply | Captive polyethylene production insulates margin structures from ARA region feedstock volatility. |
| Water-Based Flexographic Printing Adoption | Short-run digital capabilities compress new product introduction cycles for French and Dutch private-label brands. |
Methodological Framework
Direct dialogue with converter operations managers, retail procurement directors, pharmaceutical supply chain leads, and EFSA regulatory consultants grounded qualitative insights. Secondary validation drew from EU Packaging and Packaging Waste Regulation delegated acts, ECHA substance evaluation roadmaps, Cefic polymer trade data, and SEC filings of listed packaging groups. Bottom-up volume estimates triangulated with top-down market sizing across material, product type, and end-use dimensions.
Segment-level outputs across plastic, paper, aluminum foil, and composite materials were generated over the projection horizon. Modeled dimensions included product format, material substrate, end-use industry, and geographic production cluster. CAGRs were derived from regression analysis of historical conversion capacity expansion and regulatory-driven substitution timelines. Forecast inputs incorporated EU Green Deal implementation pace and EMA pharmaceutical packaging qualification cycles.
Several conditions sit outside the modeled scope, including abrupt ECHA substance bans, polymer supply disruptions from ARA refinery outages, and faster-than-anticipated retail procurement consolidation. Forecasts reflect documented assumptions about regulatory enforcement consistency and converter technology adoption curves. A model refresh is warranted upon material change in delegated act timelines for mandatory recycled content floors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market