
 France Metal Packaging Market | 2026-2036
France Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Metal Packaging Market Foresight
Digital printing on metal substrates is fragmenting legacy offset-coating workflows across French converting plants. Ball Corporation leverages its European beverage-can footprint to supply major bottlers from plants near Reims and Dunkirk. Crown Holdings Inc. anchors its position through backward integration into aluminum sheet supply and captive end-making equipment. Massilly Group specializes in food-safe tinplate closures and dominates the premium preserves segment through proprietary sealing technologies.
France metal packaging comprises rigid containers fabricated from aluminum, tinplate, or steel, typically formed through deep drawing, wall ironing, or three-piece welding to achieve hermetic sealing and stackable geometry for liquid and semi-solid goods. Aluminum cans lead beverage applications due to lightweighting potential and infinite recyclability, while tinplate containers retain structural importance in food processing where oxygen barrier performance dictates shelf stability. Steel drums command the automotive fluids segment through UN-certified hazardous-material compliance and reuse protocols, though aerosol cans represent the fastest-growing product type as personal care brands switch from plastic propellant housings.
France's environmental agency enforces extended producer responsibility frameworks that obligate metal packaging producers to finance collection and recycling infrastructure, tightening material traceability requirements. ANSM and DGCCRF monitor food-contact and consumer safety standards, compelling manufacturers to maintain migration-tested lacquer systems and batch-level compliance documentation. Stakeholders must weigh aluminum price volatility against regulatory recycling-rate targets when committing to capacity expansion or substrate conversion decisions.
Market Dynamics
France's metal packaging sector faces intensifying pressure from the EU Green Deal's packaging waste directive, which mandates recycled-content thresholds that force converters to reengineer supply chains and lacquer systems simultaneously.
Growth Catalysts
- Extended Producer Responsibility:France's environmental agency enforces collection and recycling financing obligations that accelerate investment in closed-loop aluminum recovery infrastructure.
- Craft beverage expansion:Small-batch carbonated drink producers in the Hauts-de-France corridor are procuring aluminum cans at volumes that justify dedicated production lines.
- Aerosol substitution:Personal care brands are abandoning plastic propellant housings for tinplate aerosols to meet single-use plastic bans.
Market Restraints
- Aluminum price volatility:London Metal Exchange pricing swings compress margin predictability for beverage can manufacturers locked into annual supply contracts.
- Tinplate supply concentration:European steel mill consolidation leaves food container producers dependent on a narrowing supplier base for electrolytic tinplate.
- Migration testing complexity:ANSM's food-contact lacquer certification timelines extend six to nine months, delaying new product launches.
Strategic Opportunities
- Digital printing convergence:UV-cured inkjet systems are virtualizing legacy offset workflows, enabling short-run customization for regional beverage brands.
- Steel drum reuse protocols:UN-certified hazardous material containers for automotive fluids command premium pricing through circular service models.
- CSRD disclosure alignment:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for metal packaging with verified recycled-content traceability.
Industry Challenges
- Deep-drawing technician scarcity:Specialized tool-and-die expertise for tinplate forming is retiring faster than vocational programs replenish the workforce.
- Lacquer formulation IP:Proprietary epoxy-phenolic systems for acidic food contact face patent thickets that complicate new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Metal Packaging Market |
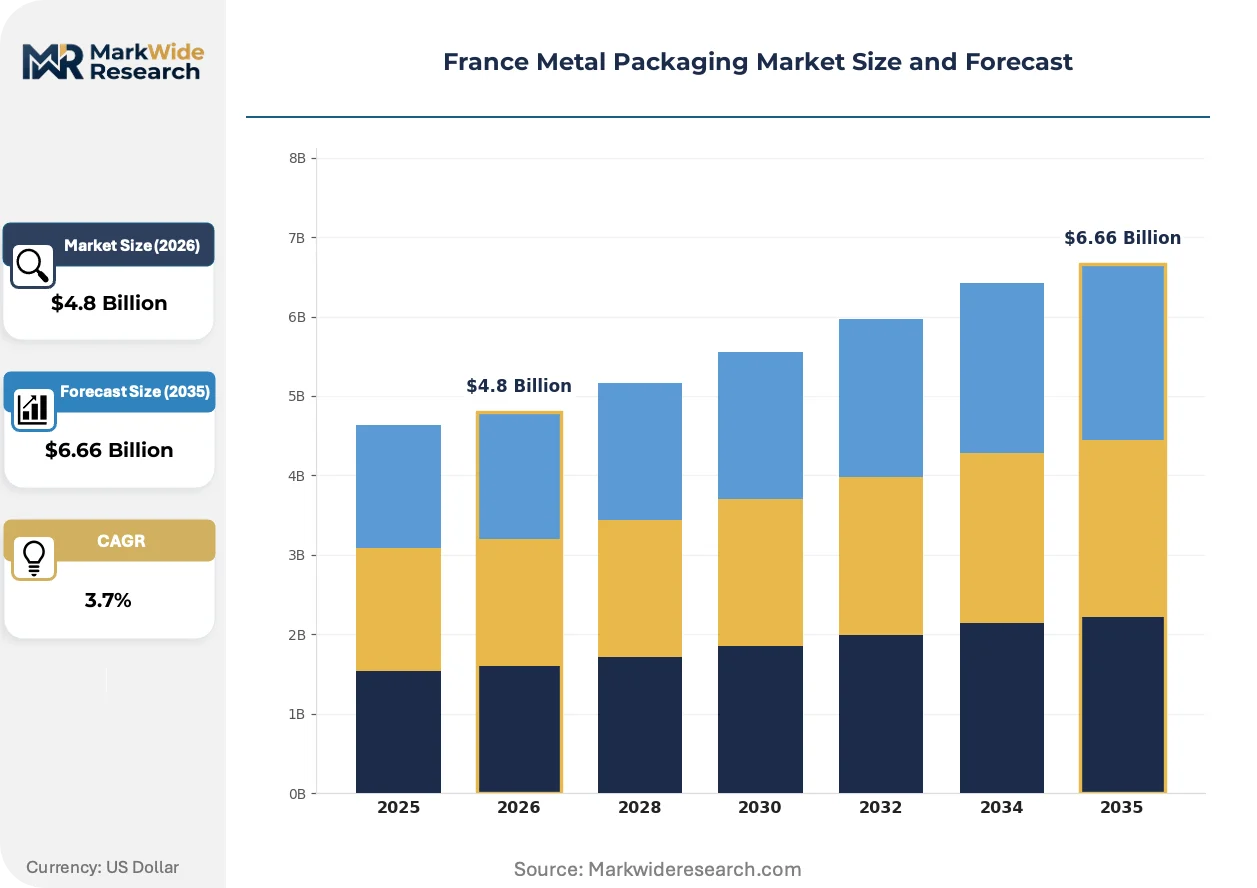
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Drums, Tinplate Containers, Aerosol Cans, Metal Bottles Application: Beverages, Personal Care, Household Chemicals, Food Processing, Automotive Fluids End User: Food & Beverage Manufacturers, Cosmetic Brands, Chemical Producers, Lubricant Suppliers Packaging Type: Tins, Canisters, Jars, Pails, Carboys |
| Companies Covered | Envases Group, Ball Corporation, Massilly Group, Can-Pack SA, Crown Holdings Inc., Groupe Soulier, Ardagh Group, Tecnocap Group, COFEM Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Metal Packaging Market Shifts & Advancements
Digital manufacturing workflows and regulatory disclosure mandates are compressing traditional production timelines while fragmenting batch economics across French converting plants.
UV-cured inkjet deposition on aluminum and tinplate substrates is virtualizing legacy offset-coating workflows across French converting plants. Regional beverage brands are adopting short-run digital decoration to support seasonal and limited-edition launches without cylinder engraving delays. This capability compression enables micro-lot production economics that were previously unviable for runs below fifty thousand units.
France's enforcement of extended producer responsibility frameworks tightens material traceability requirements for metal packaging producers financing collection infrastructure. The industrial consequence is mandatory batch-level documentation linking container origin to recycling outcome. Food-contact manufacturers face the steepest compliance burden as DGCCRF audits intensify around lacquer migration testing protocols.
Direct procurement relationships between beverage brands and can manufacturers are displacing traditional converter-mediated supply chains. Major bottlers near Reims and Dunkirk are negotiating volume commitments that bypass regional distributors. This channel compression concentrates negotiation leverage among Hauts-de-France production clusters while marginalizing smaller converting operations without captive end-making equipment.
France Metal Packaging Market Segmentation
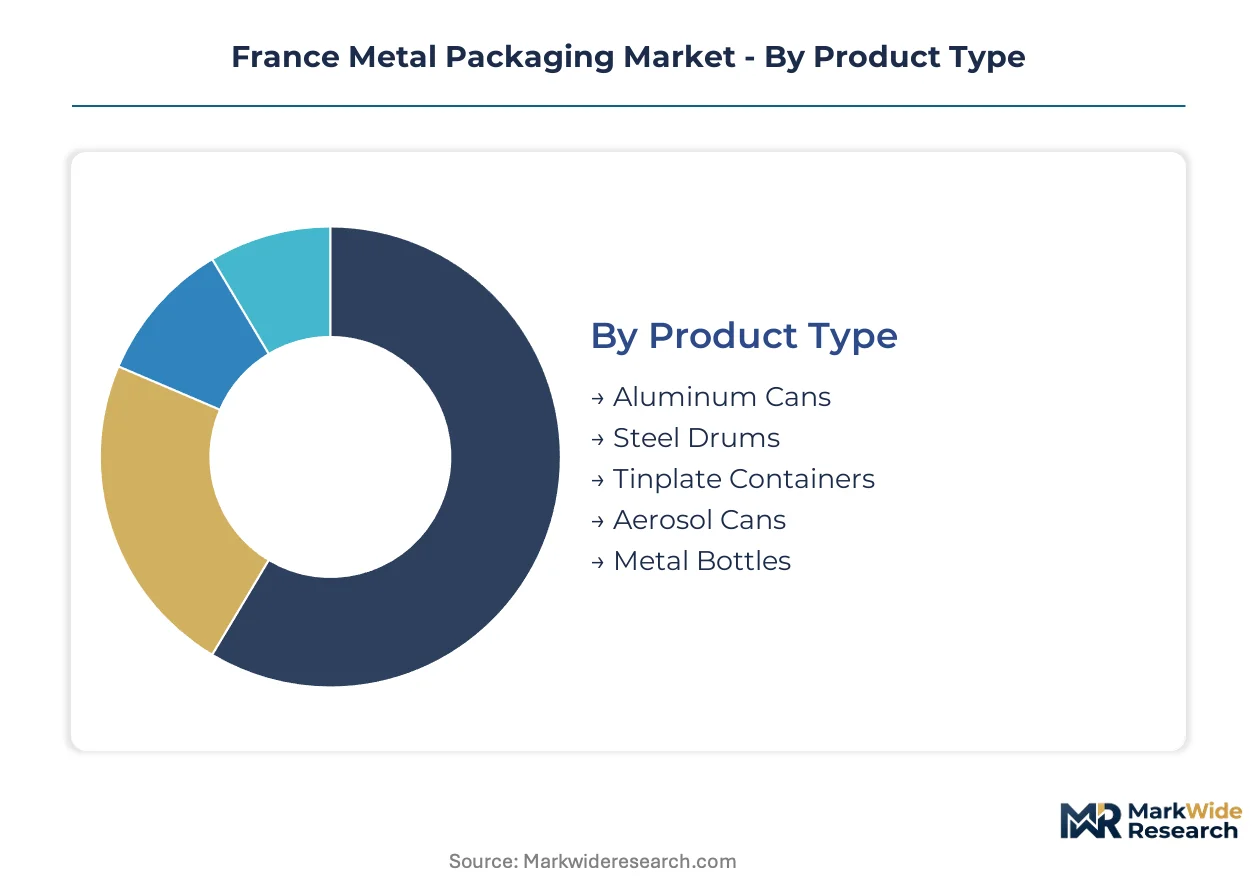
Metal packaging segmentation in France reflects divergent technical requirements across beverage carbonation pressures, hazardous material compliance, and food-contact migration thresholds. Each category channels distinct procurement patterns, regulatory burdens, and aftermarket service intensities that reshape converter economics.
Product Type:
After-sales service intensity varies sharply across product categories, with refillable steel drums demanding fleet management logistics while aluminum cans require minimal post-delivery support.
- Aluminum Cans:Deep-drawn and wall-ironed single-piece containers achieve hermetic sealing through double-seamed ends. Beverage bottlers near Reims and Dunkirk are locking in multi-year procurement contracts as craft carbonated drinks expand shelf space. ANSM migration testing mandates extend certification timelines for new lacquer formulations.
- Steel Drums:UN-certified cylindrical containers with rolling hoops withstand hazardous material transport and repeated reconditioning cycles. Automotive fluid packagers in Hauts-de-France command premium pricing through circular reuse protocols that track container lifecycle across multiple filling rotations.
- Tinplate Containers:Three-piece welded food cans with electrolytic tin coating provide oxygen barrier performance for shelf-stable preserves.
- Aerosol Cans:Pressurized tinplate housings with domed bottoms and valve crimping accommodate propellant systems for personal care applications.
- Metal Bottles:Threaded-neck aluminum containers for premium beverage positioning and refillable cosmetic applications.
Aluminum cans hold the largest share; momentum sits with aerosol cans as personal care brands abandon plastic propellant housings.
Application:
Cost tier stratification separates commodity beverage volumes from premium personal care positioning and regulated hazardous material compliance.
- Beverages:Carbonated soft drinks, craft beers, and ready-to-drink cocktails dominate aluminum can offtake. Massilly Group supplies proprietary sealing technologies for premium preserves while Ball Corporation operates dedicated production lines near Reims.
- Personal Care:Deodorants, hair sprays, and shaving foams drive tinplate aerosol conversion from plastic alternatives. EU Green Deal packaging waste directives accelerate substitution timelines for single-use plastic bans.
- Household Chemicals:Corrosion-resistant steel pails and carboys contain solvents, detergents, and agricultural formulations.
- Food Processing:Acidic and low-acid canned goods require epoxy-phenolic lacquer systems with batch-level DGCCRF compliance documentation.
- Automotive Fluids:Engine oils, coolants, and brake fluids move through UN-certified steel drums with reconditioning service contracts.
Beverages command the greatest volume; personal care applications are expanding most quickly amid plastic substitution mandates.
End User:
Customer type determines contract structure, with multinational beverage manufacturers consolidating procurement leverage against fragmented cosmetic brand portfolios.
- Food & Beverage Manufacturers:Large-scale bottlers negotiate direct supply relationships that bypass regional distributors. Crown Holdings anchors positions through backward integration into aluminum sheet supply.
- Cosmetic Brands:Mid-tier personal care companies procure short-run aerosol lots enabled by UV-cured inkjet digital printing systems.
- Chemical Producers:Industrial solvent and agrochemical packagers specify UN-certified steel drum fleets with circular logistics.
- Lubricant Suppliers:Automotive and industrial oil blenders demand reconditioning documentation and traceable container histories.
Food and beverage manufacturers absorb the highest tonnage; cosmetic brands are gaining share fastest through aerosol conversion.
Packaging Type:
Supply concentration clusters around Hauts-de-France converting corridors where deep-drawing tool-and-die expertise remains geographically anchored.
- Tins:Rectangular and cylindrical tinplate containers for confectionery, tobacco, and promotional packaging. Massilly Group dominates premium preserves through proprietary sealing technologies.
- Canisters:Round or oval closed containers with slip lids or friction-fit closures for dry goods and chemicals.
- Jars:Wide-mouth tinplate or aluminum containers with threaded or lug closures for viscous food products and cosmetics.
- Pails:Tapered cylindrical steel containers with bail handles and friction-fit or lug covers for paints and adhesives.
- Carboys:Large-capacity narrow-neck containers for laboratory and industrial chemical transport.
Tins retain the largest installed base; jars are climbing the fastest as premium food brands adopt transparent lid viewing panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aluminum sheet producers supply deep-drawn coil to French beverage can plants along the Rhine-Ruhr corridor. Italian tinplate mills export electrolytic steel to Massilly Group's closure manufacturing sites near Lyon.
Île-de-France
Paris-region cosmetic headquarters drive aerosol can procurement for premium personal care brands. ANSM enforces food-contact lacquer migration testing protocols that extend certification timelines. Neuilly-sur-Seine hosts decision centers for multinational beverage procurement teams negotiating direct supply contracts.
Hauts-de-France
Deep-drawing tool-and-die expertise concentrates in Lille-Dunkirk industrial corridor where beverage bottlers lock in aluminum can volumes. The EU Green Deal packaging waste directive tightens recycled-content thresholds for converters operating near the Belgian border. Reims and Dunkirk plants supply carbonated drink producers with wall-ironed single-piece containers.
Auvergne-Rhône-Alpes
Lyon-based food processors demand tinplate containers with epoxy-phenolic lining systems for acidic preserves. DGCCRF audits intensify around batch-level compliance documentation for shelf-stable goods. Saint-Étienne metal forming shops specialize in three-piece welded food cans with proprietary sealing technologies.
Provence-Alpes-Côte d'Azur
Marseille-Fos port infrastructure handles imported aluminum ingot for regional rolling mills serving beverage applications. Extended producer responsibility frameworks obligate producers to finance Mediterranean collection infrastructure. Toulon chemical packagers specify UN-certified steel drums for hazardous material export to North African markets.
France Metal Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base separates into multinational converters with captive end-making equipment, regional fabricators serving food-contact niches, and specialty closure manufacturers with proprietary sealing IP. Dominant competitive moves include backward integration into aluminum sheet supply and strategic partnerships between beverage brands and can manufacturers that bypass traditional distribution channels.
Within the multinational converter tier, Ball Corporation and Crown Holdings Inc. occupy positions defined by scale-driven supply relationships with Hauts-de-France bottlers. Massilly Group exemplifies the product-specialist archetype through its concentration on food-safe tinplate closures. These three entities represent the competitive spectrum from beverage can volume production to premium preserves segment specialization.
| Leading Market Players |
|---|
| Envases Group |
| Ball Corporation |
| Massilly Group |
| Can-Pack SA |
| Crown Holdings Inc. |
| Groupe Soulier |
| Ardagh Group |
| Tecnocap Group |
| COFEM Industries |
| Others |
Supply & Pricing Matrix
Overcapacity in German aluminum rolling mills is compressing sheet pricing for French beverage can producers while simultaneously pressuring converters to absorb volatility through longer contract tenors. This utilization dynamic concentrates negotiation leverage among Hauts-de-France bottlers locking in multi-year offtake agreements.
Pricing Analysis
Legacy offset-coating workflows command premium pricing against emerging UV-cured inkjet systems that enable short-run customization. Pricing stratifies across premium lacquer-certified food contact, standard beverage-grade aluminum, and economy-tier unprinted steel drums. Cost compression in standard beverage cans is intensifying because London Metal Exchange aluminum pricing swings compress margin predictability for manufacturers locked into annual supply contracts. Multinational beverage manufacturers exhibit lowest price sensitivity through volume consolidation, while mid-tier cosmetic brands procurement of aerosol lots show highest sensitivity to per-unit decoration costs.
Supply Chain Analysis
Tariff exposure between German aluminum producers and French converting plants dominates supply chain risk calculus for beverage can manufacturers. German, Belgian, and Italian mills anchor European electrolytic tinplate and aluminum coil supply for French food container and beverage applications. Raw material dependencies rest on aluminum ingot, electrolytic tinplate, and epoxy-phenolic lacquer resin systems. Single-source vulnerability concentrates in European steel mill consolidation that leaves food container producers dependent on a narrowing supplier base. Distribution runs through direct procurement relationships between beverage brands and can manufacturers that bypass traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as craft beverage expansion and aerosol substitution create specialized demand niches that reward focused capabilities over scale.
For Market Incumbents: Harden backward integration into aluminum sheet supply to offset London Metal Exchange volatility exposure. Anchor capacity positions in Hauts-de-France corridor where deep-drawing tool-and-die expertise concentrates against emerging digital printing competitors. Prioritize DGCCRF-compliant lacquer certification investments that extend compliance timelines and raise barriers for new entrants.
For New Entrants and Emerging Players: Auvergne-Rhône-Alpes food processors represent underpenetrated demand for epoxy-phenolic lined tinplate containers with batch-level traceability documentation. Target cosmetic brand procurement of short-run aerosol lots enabled by UV-cured inkjet digital printing systems bypassing cylinder engraving delays. Pursue partnership positioning with regional beverage brands seeking seasonal and limited-edition launch capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward product-specialist players with proprietary sealing IP and food-contact certification infrastructure rather than commodity beverage can volume producers. Long-term viability centers on converters with verified recycled-content traceability aligning with EU Corporate Sustainability Reporting Directive disclosure mandates. Monitor aluminum price volatility inflection as signal for contract structure renegotiation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sheet Supply | Crown Holdings anchors position through captive supply controlling input cost volatility. |
| Digital Printing Capability Deployment | UV-cured inkjet systems enable Massilly Group to serve regional craft beverage micro-lots. |
| Extended Producer Responsibility Compliance Infrastructure | Ball Corporation finances closed-loop aluminum recovery meeting ANSM traceability mandates. |
| Proprietary Sealing Technology Development | Massilly Group dominates premium preserves segment through food-safe tinplate closure IP. |
| Direct Procurement Relationship Establishment | Beverage bottlers near Reims and Dunkirk bypass distributors concentrating negotiation leverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage procurement directors, food container plant managers, cosmetic brand packaging leads, and steel drum reconditioning service heads. Secondary validation drew from ANSM food-contact compliance filings, DGCCRF audit documentation, EU Green Deal packaging waste directive implementation reports, and London Metal Exchange aluminum pricing data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the French metal packaging value chain.
Calibration against historical capacity utilization rates and contract tenor patterns informed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and packaging format alongside regional production cluster concentration. CAGRs were derived through regression analysis of input cost trajectories and substitution elasticity parameters. Industry-specific forecast inputs incorporated aluminum price volatility indices and lacquer certification timeline distributions.
Practitioners should monitor aluminum price volatility spikes, EU Green Deal recycled-content threshold adjustments, and ANSM migration testing protocol revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
India Metal Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Asia-Pacific Metal Packaging Market