
 Italy Flexible Plastic Packaging Market | 2026-2036
Italy Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Flexible Plastic Packaging Market Insights
Skilled polymer conversion labor is collapsing across Emilia-Romagna and Lombardy, constraining output expansion for mid-tier converters. Amcor PLC leverages integrated film extrusion and printing capabilities to sustain volume leadership in barrier laminates for chilled food. Constantia Flexibles GmbH anchors premium pharmaceutical and dairy flexible packaging through specialized clean-room production lines near Verona. Mondi PLC competes on kraft-paper hybrid flexible solutions, positioning its Italian operations to capture sustainability-driven brand switches.
Italy flexible plastic packaging encompasses polymer-based, deformable containment systems manufactured through blown film extrusion, cast film processing, or lamination, typically ranging from twenty to two hundred microns in thickness, engineered to protect perishables from moisture, oxygen, and mechanical damage during distribution and shelf display. Stand-up pouches and rollstock dominate value generation, with pouches capturing premium branded food applications and rollstock serving high-volume automated form-fill-seal operations across pasta, cured meat, and ready-meal sectors. Polyethylene and polypropylene laminates lead material demand, though regulatory pressure on recyclability is accelerating trials in mono-material structures that simplify post-consumer sorting.
Italy's Ministry of Ecological Transition enforces EU Packaging and Packaging Waste Regulation targets through CONAI, the national packaging consortium, mandating minimum recycled content thresholds and extended producer fee modulation. CE marking under EU harmonized standards governs food-contact compliance, with EFSA-evaluated substances restricting certain adhesive and barrier chemistries in direct-contact layers. Stakeholders must monitor pending EU PPWR implementation timelines and CONAI fee restructuring to decide between retrofitting existing lamination assets or transitioning capital toward certified recyclable mono-material platforms.
Market Dynamics
Italy's flexible plastic packaging sector faces acute labor scarcity in polymer conversion across Emilia-Romagna and Lombardy, forcing converters to automate or cede volume to integrated multinationals with captive film extrusion capacity.
Growth Catalysts
- EU PPWR Recycled Content Mandates:CONAI's fee modulation rewards mono-material structures, pulling investment toward polyethylene and polypropylene laminates that simplify post-consumer sorting streams.
- Chilled Food Barrier Demand:High-barrier pouches for cured meats and ready-meals command premium positioning as northern Italian food manufacturers seek shelf-life extension without preservatives.
- Pharmaceutical Clean-Room Expansion:Verona's specialized production corridors attract flexible packaging for sterile drug delivery systems, leveraging Italy's established pharma formulation base.
Market Restraints
- Ethylene and Propylene Feedstock Volatility:Polyolefin resin costs fluctuate with naphtha-cracker margins, compressing converter margins when spot prices spike.
- Skilled Extrusion Operator Scarcity:Technical institutes in Lombardy graduate fewer blown-film technicians than retirement attrition absorbs, constraining output expansion.
- Paper-Fiber Substitution Pressure:Kraft-paper hybrid formats from Mondi's Italian operations capture sustainability-driven brand switches in dry-food segments.
Strategic Opportunities
- Mono-Material Platform Certification:CEFLEX guidelines and CONAI eco-modulation create first-mover advantage for converters achieving Design for Recycling approval.
- Southern Italy Automation Gap:Campania and Sicily automated packaging penetration lags the north, offering greenfield deployment of form-fill-seal rollstock systems.
- Digital Printing Convergence:UV-inkjet integration with cast film lines enables short-run customization for regional food brands without cylinder changeover costs.
Industry Challenges
- EFSA Food-Contact Substance Approval Timelines:Novel adhesive and barrier chemistries face 18-24 month safety evaluations, delaying laminate innovation cycles.
- Lamination Asset Stranding Risk:Multi-layer solvent-based lines require costly retrofit or replacement to produce recyclable mono-material structures compliant with pending PPWR enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Flexible Plastic Packaging Market |
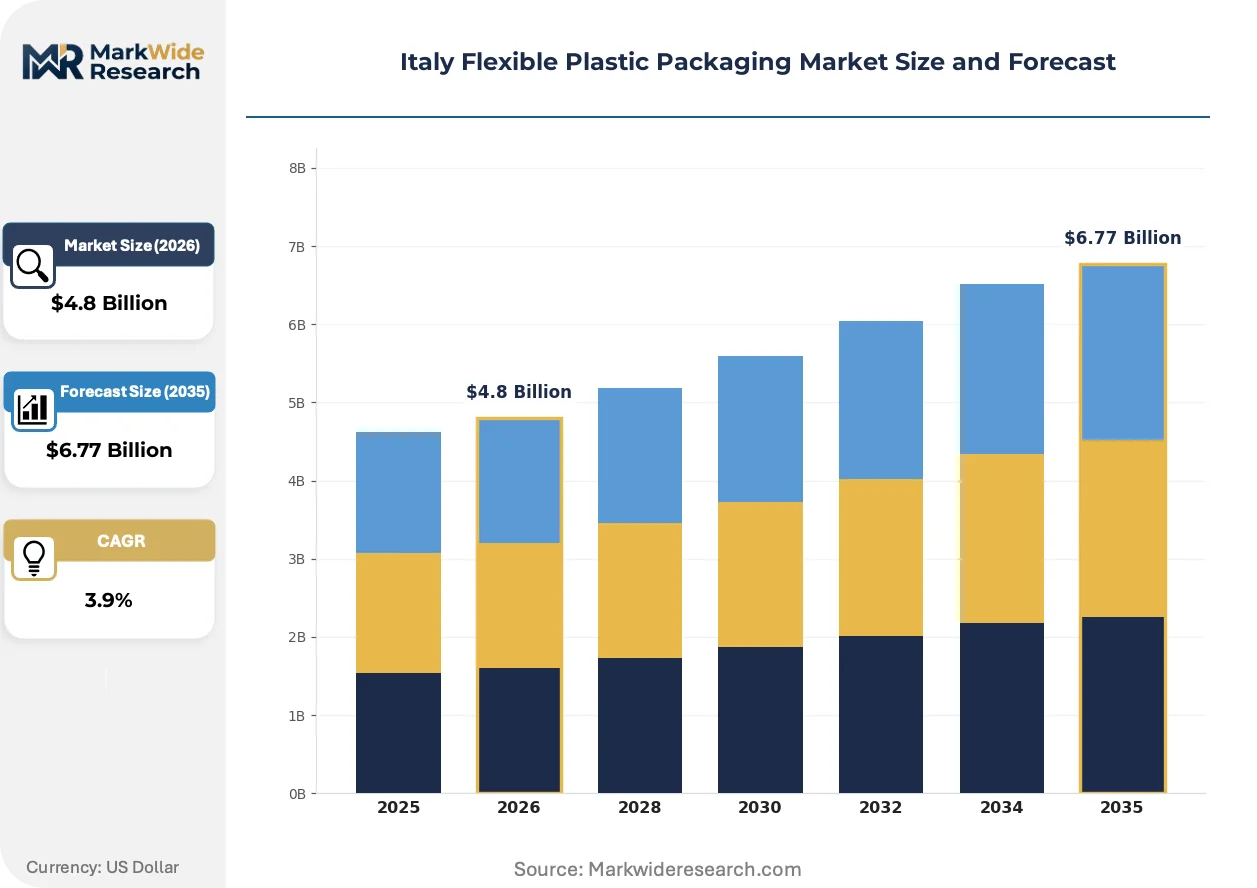
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Shrink Films, Rollstock Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Laminates End User: Food & Beverage, Personal Care, Healthcare, Household Products Thickness: Thin, Medium, Thick, Ultra-Thick |
| Companies Covered | Amcor PLC, Constantia Flexibles GmbH, Berry Global Inc, Mondi PLC, Flex-Pack SRL, DODACO SRL, Mainetti SpA, Pogliano Flexible Packaging SRL, Rotofil SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Flexible Plastic Packaging Market Trends and Innovations
Active transformation in Italy's flexible packaging landscape centers on material redesign for circularity, regulatory compliance acceleration, and supply chain digitization reshaping converter-brand relationships.
Mono-material polyethylene structures is bifurcating the barrier laminate market. Food manufacturers in the pasta and cured meat sectors are adopting these formats at accelerating pace to preempt CONAI fee penalties. This technology is compressing demand for legacy multi-layer nylon-ethylene vinyl alcohol constructions that require energy-intensive delamination for recycling.
Italy's Ministry of Ecological Transition is accelerating PPWR transposition timelines ahead of Brussels-mandated deadlines. Industrial consequence includes mandatory recycled content thresholds rising faster than domestic reprocessing capacity can supply. Northern Italian converters serving multinational food brands face the steepest compliance curves, driving joint ventures with European recyclers to secure certified flake supply.
Brand procurement teams are consolidating flexible packaging suppliers to reduce audit burden and secure volume commitments. Regional Italian food manufacturers historically sourcing from 8-12 converters are narrowing to 3-4 strategic partners with integrated extrusion-to-printing capabilities. This concentration is most visible in the Emilia-Romagna meat processing cluster, where procurement directors prioritize converters with in-house EVOH coextrusion and digital proofing workflows.
Italy Flexible Plastic Packaging Market Segmentation
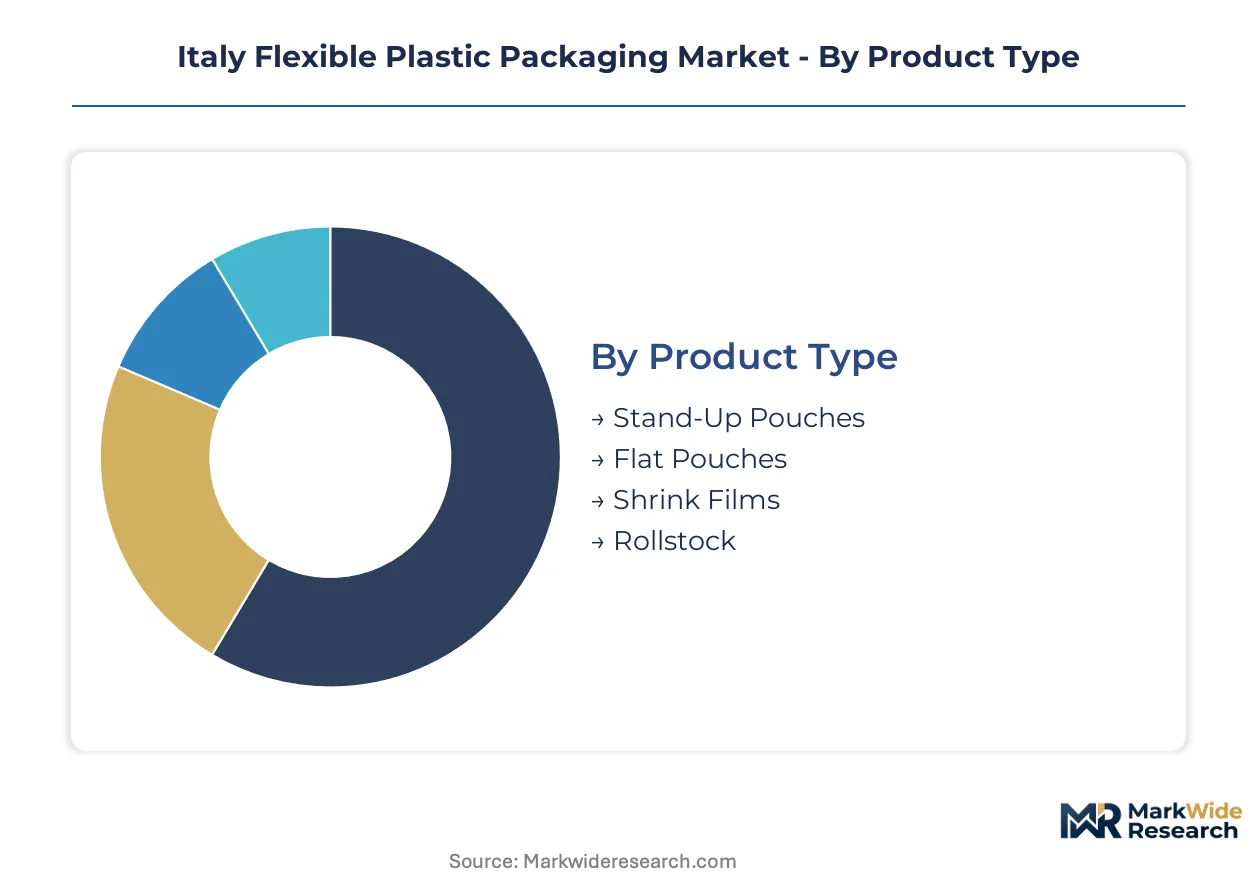
Segmentation in Italy's flexible plastic packaging market reveals how material choices and format specifications map to distinct procurement channels. Brand owners in the northern industrial corridor select formats based on automation compatibility and CONAI eco-modulation incentives rather than unit cost alone.
Product Type:
Channel flow varies sharply by format complexity, with premium pouches routing through specialized converters while commodity films move via distributor networks.
- Stand-Up Pouches:Multi-layer constructions incorporating EVOH barriers dominate chilled food and ready-meal applications. Milan-based meat processors specify these formats for extended shelf-life positioning in retail delis.
- Rollstock:Continuous web material feeds automated form-fill-seal lines across pasta and bakery sectors. Bologna's packaging machinery cluster drives specification standardization toward 200-micron polyethylene variants compatible with high-speed equipment.
- Flat Pouches:Three-side-seal configurations serve portion-controlled pharmaceutical and personal care sachets. Verona's clean-room corridor concentrates demand for medical-grade laminates.
- Shrink Films:Polyolefin sleeves bundle multi-pack beverages and household products. Turin's logistics hub generates volume for pallet stabilization applications.
By volume, Rollstock leads. By growth pace, Stand-Up Pouches is climbing the fastest as barrier technology migrates down the price curve.
Material:
Cost tier stratification separates commodity polyolefins from engineered laminates, with recycled content thresholds forcing mid-tier converters toward platform consolidation.
- Polyethylene:Linear low-density grades dominate mono-material trials for pasta and cured meat packaging. CONAI fee modulation accelerates adoption of all-polyethylene structures that bypass complex delamination.
- Laminates:Multi-layer nylon-EVOH-polyethylene constructions retain barrier performance leadership in oxygen-sensitive applications. Retirement of solvent-based lamination assets in Lombardy is compressing supply for legacy formats.
- Polypropylene:Cast film clarity suits premium confectionery and snack visibility requirements. Cast extrusion capacity constraints in Emilia-Romagna limit expansion.
- Polyvinyl Chloride:Pharmaceutical blister lidding and medical device overwrap sustain niche demand despite recyclability penalties. Specialized calendering operations near Verona serve this residual segment.
Polyethylene captures the largest volume share. Laminates face steepest substitution pressure as Design for Recycling protocols mature.
End User:
Application-specific performance requirements dictate thickness, barrier, and certification specifications across customer categories.
- Food & Beverage:Oxygen transmission rates below 1 cc/m²/day define chilled meat and cheese packaging specifications. Northern Italian food manufacturers drive adoption of high-barrier pouches with modified atmosphere compatibility.
- Healthcare:Sterile barrier systems for drug delivery require ISO 15378 compliance and particulate-controlled manufacturing environments. Verona's pharmaceutical formulation base anchors flexible packaging demand for blister foils and IV overwrap.
- Personal Care:Sachet and pouch formats for cosmetics and toiletries prioritize print quality and tear propagation resistance. Digital printing adoption enables short-run regional brand customization.
- Household Products:Chemical resistance and child-resistance features dominate detergent and cleaner packaging. Refill pouch formats are gaining traction in sustainability-focused retail channels.
Food & Beverage commands the volume base. Healthcare delivers the highest margin per square meter due to certification barriers.
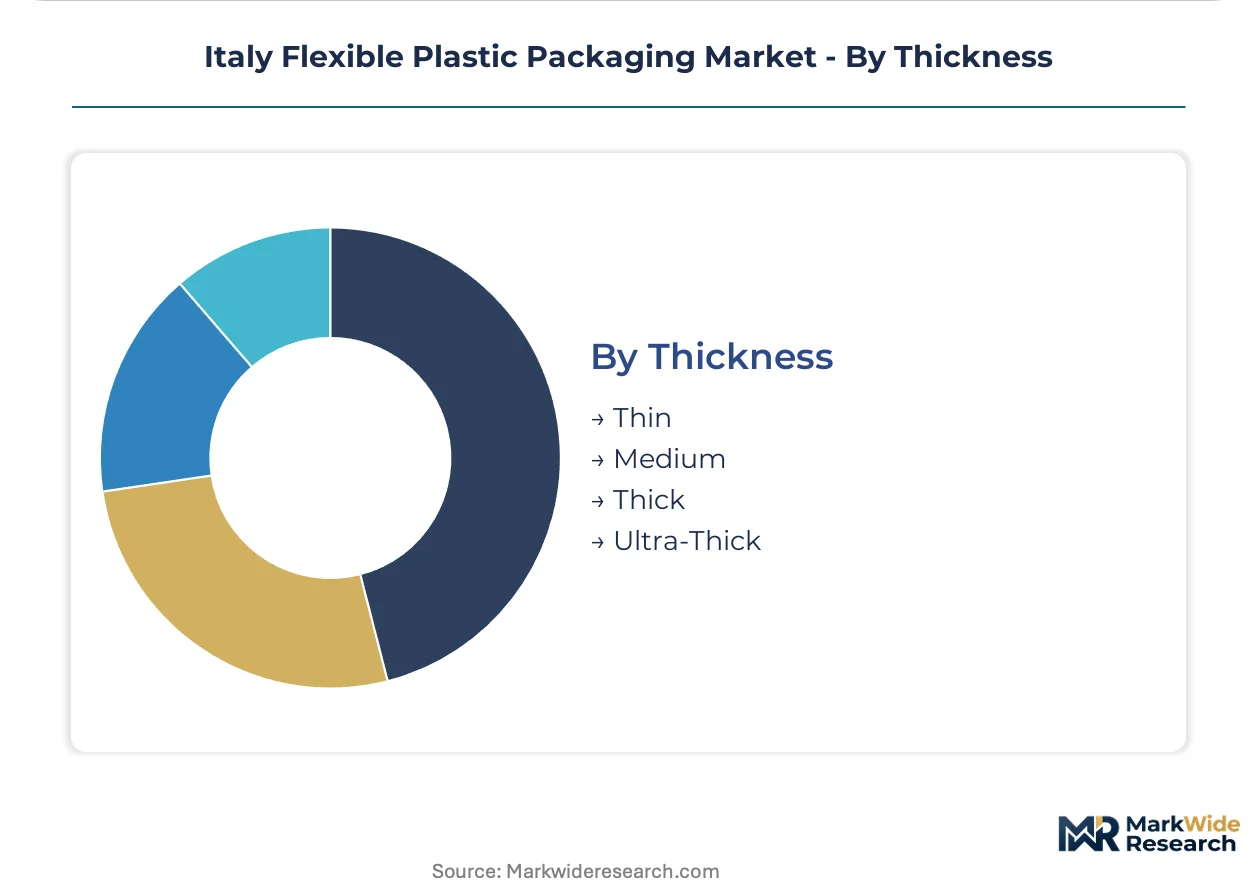
Thickness:
Volume scale inversely correlates with specification tier, as commodity applications standardize on thinner gauges while premium segments absorb material cost for performance.
- Medium:50-100 micron specifications balance mechanical protection with material efficiency across pasta, bakery, and frozen food applications. Automated lines in Emilia-Romagna calibrate around this standard range.
- Thin:Sub-50 micron films serve overwrap and secondary packaging where barrier demands are minimal. Lightweighting pressure from CONAI eco-modulation pushes more applications toward this threshold.
- Thick:100-150 micron constructions protect abrasive or puncture-prone contents including hardware and agricultural inputs. Limited converter capacity for heavy-gauge blown film constrains supply.
- Ultra-Thick:Above-150 micron specifications anchor industrial bulk liners and heavy-duty shipping sacks. Southern Italy's underdeveloped extrusion infrastructure imports most of this category.
Medium thickness dominates unit volume. Ultra-Thick specifications face supply constraints from equipment specialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CONAI, Italy's national packaging consortium, anchors regulatory enforcement across the northern industrial corridor where flexible plastic packaging demand concentrates. The Ministry of Ecological Transition transposes EU PPWR mandates through fee modulation that rewards mono-material structures. Regional output variations reflect automation penetration gaps between northern manufacturing clusters and southern greenfield opportunities.
Lombardy
Milan anchors chilled food packaging demand from meat processors requiring high-barrier pouch specifications. CONAI's eco-modulation penalties accelerate converter investment in polyethylene mono-material trials. The Brianza machinery corridor sustains automated form-fill-seal rollstock consumption for pasta and bakery applications.
Emilia-Romagna
Bologna's packaging machinery cluster standardizes equipment specifications around 200-micron polyethylene variants. Technical institutes in the region graduate fewer blown-film technicians than retirement attrition absorbs, constraining output expansion. Parma's cured meat processors drive adoption of extended shelf-life laminates with modified atmosphere compatibility.
Veneto
Verona's pharmaceutical formulation base generates flexible packaging demand for sterile barrier systems and blister foils. CE marking under EU harmonized standards governs food-contact compliance for regional converters. The clean-room production corridor attracts investment in ISO 15378-certified manufacturing environments.
Piedmont
Turin's logistics hub generates volume for shrink film pallet stabilization applications across beverage distribution networks. Polyolefin resin cost volatility compresses converter margins when naphtha-cracker margins spike. The region's automotive supply chain heritage transfers engineering talent toward extrusion equipment maintenance.
Campania
Naples anchors southern Italy's underdeveloped flexible packaging infrastructure with lagging automated packaging penetration. Greenfield deployment opportunities exist for form-fill-seal rollstock systems serving regional food brands. Import dependency for ultra-thick industrial bulk liners reflects equipment specialization gaps.
Italy Flexible Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Italy's flexible plastic packaging sector. Integrated multinationals with captive film extrusion capacity sustain volume leadership against mid-tier converters facing skilled labor scarcity. Three archetypes dominate: multinational integrated players with backward polymer control, regional specialists with clean-room certification, and automation-driven mid-caps serving commodity segments. Competitive moves concentrate on lamination asset retrofitting for mono-material compliance and strategic partnerships with European recyclers to secure certified flake supply.
Among integrated multinationals, Amcor PLC and Mondi PLC exemplify divergent strategic positioning within the Italian market. Amcor PLC represents the integrated film extrusion archetype leveraging captive capacity to sustain barrier laminate leadership. Mondi PLC anchors the sustainability-driven vector through kraft-paper hybrid solutions capturing brand switches in dry-food segments. Constantia Flexibles GmbH occupies the specialized clean-room tier, serving pharmaceutical and dairy applications near Verona. Regional Italian players including Flex-Pack SRL and DODACO SRL sit within the mid-cap automation tier competing on short-run flexibility and regional logistics proximity.
| Leading Market Players |
|---|
| Amcor PLC |
| Constantia Flexibles GmbH |
| Berry Global Inc |
| Mondi PLC |
| Flex-Pack SRL |
| DODACO SRL |
| Mainetti SpA |
| Pogliano Flexible Packaging SRL |
| Rotofil SRL |
| Others |
Pricing and Supply Chain Analysis
Scale economies in blown-film extrusion capacity concentrate pricing power among integrated multinationals operating captive resin conversion, compressing margin floors for mid-tier Italian converters dependent on spot polymer purchases. Northern Italy's machinery corridor standardizes equipment specifications around 200-micron polyethylene variants, locking regional food manufacturers into volume-commitment contracts that insulate integrated players from commodity volatility.
Pricing Analysis
Milan-to-Bologna price spreads for barrier laminates exceed commodity film differentials by factor of three, reflecting certification-grade segmentation across ISO 15378 pharmaceutical tiers and standard food-contact specifications. Pricing stratifies across premium clean-room laminates, standard high-barrier pouches, and economy mono-material rollstock, with CONAI eco-modulation penalties accelerating cost compression in legacy multi-layer formats. Brand procurement consolidation toward 3-4 strategic partners reduces price transparency, though southern Italian food manufacturers retain higher sensitivity due to fragmented converter alternatives. Cost compression in solvent-based lamination is intensifying because of pending PPWR retrofit requirements.
Supply Chain Analysis
Germany and Belgium anchor European resin supply for Italian converters, with naphtha-cracker margins in Rotterdam-Antwerp corridor transmitting directly to Lombardy extrusion cost structures. Polyolefin pellet feedstock draws from German petrochemical complexes, while EVOH barrier resins source from Belgian and Japanese specialty polymer producers. Single-source vulnerability concentrates in pharmaceutical-grade adhesive chemistries facing EFSA approval bottlenecks. Distribution runs through Bologna's packaging machinery cluster for equipment-integrated rollstock, with Milan-based meat processors receiving direct mill-to-plant pouch deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's flexible plastic packaging sector presents a defensive-moat structure anchored in regulatory entrenchment: CE marking and EFSA food-contact compliance create 18-24 month approval barriers that protect incumbent converter relationships with multinational food brands.
For Market Incumbents: Fortify barrier laminate leadership by retrofitting solvent-based assets to mono-material polyethylene platforms before CONAI fee modulation penalties accelerate. Prioritize captive extrusion capacity expansion in Emilia-Romagna to offset skilled operator scarcity, while securing certified recycled flake supply through European recycler joint ventures ahead of domestic reprocessing shortfalls. For New Entrants and Emerging Players: Differentiate on digital printing convergence for short-run regional food brands in Campania and Sicily, where automated packaging penetration lags northern benchmarks by half. Target southern Italy's greenfield form-fill-seal deployment gap with UV-inkjet integrated cast film lines, bypassing cylinder changeover cost barriers that constrain incumbent response speed. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with integrated extrusion-to-printing capabilities serving consolidated multinational food brand panels. Long-term viability across the analysis window favors acquisition targets with CEFLEX Design for Recycling certification progress and established CONAI eco-modulation compliance infrastructure. Monitor EFSA novel substance approval timelines as inflection signal for laminate innovation cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Certification | CEFLEX approval secures CONAI fee advantages and locks in multinational brand switching costs. |
| Backward Integration into Film Extrusion | Captive polyethylene capacity insulates margins from Rotterdam-Antwerp naphtha-cracker volatility. |
| Digital Printing Line Integration | UV-inkjet cast film convergence enables short-run customization without cylinder inventory burden. |
| Southern Italy Automation Deployment | Campania and Sicily greenfield form-fill-seal systems capture regional brand consolidation. |
| Recycled Flake Supply Partnership | European recycler joint ventures secure certified feedstock ahead of domestic reprocessing constraints. |
Research Methodology
Desk research of EU regulatory filings, CONAI fee modulation schedules, and EFSA food-contact substance evaluations preceded structured interviews with blown-film plant managers, procurement directors at northern Italian meat processors, pharmaceutical packaging engineers in Verona's clean-room corridor, and Bologna-based packaging machinery OEM technical directors. Secondary validation drew from customs trade data, SEC filings of listed packaging multinationals, and CEFLEX circular economy platform documentation. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand segmentation from food manufacturer packaging specifications.
Variance decomposition across product type, material platform, end-use application, thickness specification, and regional production cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate synthesis applied to baseline volume estimates, with explicit modeling of CONAI eco-modulation phase-in impacts and PPWR recycled content threshold compliance curves. Industry-specific forecast inputs included polymer resin price elasticity coefficients and pharmaceutical clean-room capacity expansion pipelines.
Forecasts assume regulatory continuity in EU PPWR transposition through Italy's Ministry of Ecological Transition and CONAI enforcement protocols; material policy shifts or accelerated recycled content timelines would require re-modeling. Specific risks that could revise projections include EFSA approval delays for novel barrier chemistries, naphtha-cracker margin spikes compressing converter viability, and southern Italy infrastructure investment acceleration altering regional demand distribution. Recalibration cycles align with material shifts in regulatory enforcement timelines and polymer feedstock cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market