
 GCC Shrink Sleeves Market | 2026-2036
GCC Shrink Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Shrink Sleeves Market Foresight
Decorative labeling services is reshaping margin pools away from commodity sleeve production across the GCC. Taghleef Industries leverages film manufacturing scale to anchor supply security for regional converters. Golden Line Printing & Packaging specializes in high-definition gravure printing for premium beverage accounts. Avery Dennison Corporation extends materials science capabilities into tamper-evident adhesive formulations suited for Gulf climate conditions.
Shrink sleeves are heat-activated polymer films, typically PETG or PVC between 40-70 microns, that conform to container contours at 80-120°C to deliver 360-degree graphics coverage with integral tamper-evident seals. PETG compositions dominate GCC procurement due to superior shrinkage control and print clarity on irregular bottle geometries. Beverage bottling commands the largest end-use share, while pharmaceutical applications exhibit the fastest structural expansion driven by track-and-trace serialization mandates. Decorative labeling captures disproportionate margin pools versus commodity informative labeling as brand owners prioritize shelf differentiation in hypermarket environments.
SFDA in Saudi Arabia enforces pharmaceutical serialization standards that mandate tamper-evident sleeve integration, while UAE's Ministry of Climate Change and Environment advances plastic circularity rules affecting substrate selection. BIS-equivalent conformity assessment procedures across Kuwait, Oman, and Qatar create fragmented market access protocols for imported film substrates. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and substrate substitution timelines to align capacity investments with compliance trajectories.
Market Dynamics
SFDA pharmaceutical serialization mandates and UAE plastic circularity rules are compressing substrate selection windows while elevating compliance costs for regional converters.
Growth Catalysts
- Pharmaceutical serialization mandates:Saudi Arabia's SFDA requires tamper-evident sleeve integration for track-and-trace compliance, forcing packaging upgrades across domestic drug manufacturing.
- Beverage bottling clusters:Riyadh-Jeddah corridor concentration of FMCG manufacturing creates procurement density that rewards localized sleeve production capacity.
- PETG material performance:Superior shrinkage control and print clarity on irregular bottle geometries is displacing PVC alternatives in premium beverage applications.
Market Restraints
- Petrochemical feedstock volatility:Crude-linked resin pricing creates margin compression for film extruders serving regional converters.
- Import dependency for substrate films:Limited domestic PETG and PVC film manufacturing concentrates supply risk with Taghleef Industries and select Gulf petrochemical complexes.
- Extended Producer Responsibility timelines:Unclear implementation schedules for UAE and Saudi circularity frameworks delay substrate substitution investments.
Strategic Opportunities
- Oman and Kuwait manufacturing bases:Underpenetrated converter capacity in these markets offers first-mover positioning as beverage bottling expands beyond Saudi-UAE core.
- High-definition gravure printing:Premium beverage accounts seek 360-degree decorative labeling that commands margin premiums over commodity informative sleeves.
- Digital printing convergence:Combination of inkjet technologies with shrink sleeve formats enables short-run customization for seasonal beverage promotions.
Industry Challenges
- Gravure cylinder lead times:High-definition printing for premium accounts requires specialized tooling with 8-12 week procurement cycles that compress campaign launch windows.
- Multi-jurisdiction conformity assessment:BIS-equivalent procedures across Kuwait, Oman, and Qatar create fragmented certification pathways for imported film substrates.
- Heat tunnel calibration expertise:Sleeve application at 80-120°C demands skilled technicians to prevent distortion on irregular container geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Shrink Sleeves Market |
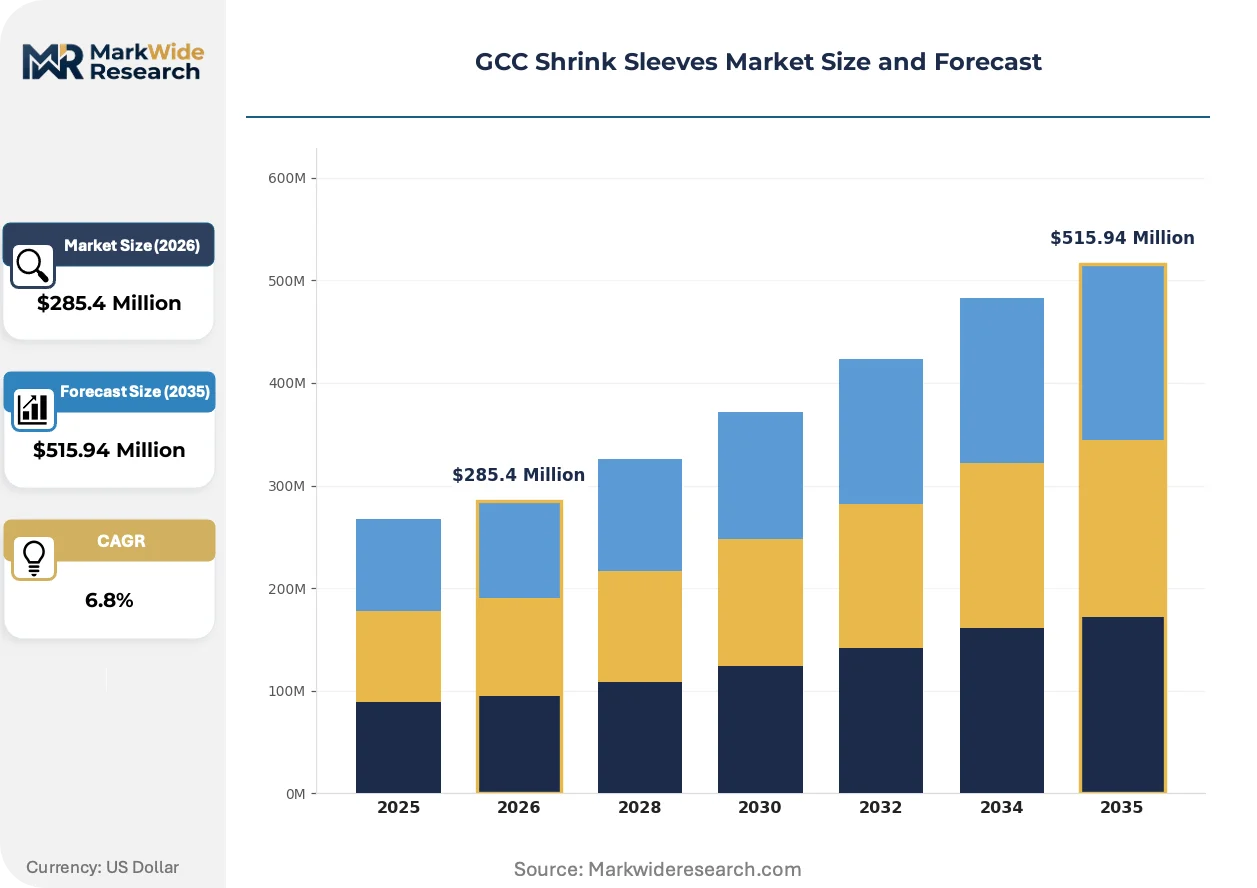
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, PETG, OPS, Polyolefin, PET End Use Industry: Beverage Bottling, Cosmetics, Household Chemicals, Pharmaceuticals, Electronics Packaging Application: Brand Protection, Tamper Evident, Decorative Labeling, Informative Labeling, Product Identification Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers, Contract Packaging Companies |
| Companies Covered | Golden Line Printing & Packaging, Taghleef Industries, ASPCO, Huhtamaki, Avery Dennison Corporation, Saudi Modern Packaging Co. (Printopack), Matrixpack, Amcor plc, Primex, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Shrink Sleeves Market Shifts & Advancements
Digital printing technologies and regulatory-driven substrate substitution are compressing traditional gravure-dominated production models across GCC packaging converters.
Digital inkjet printing is collapsing the economics of short-run shrink sleeve production. Beverage brands in the UAE are adopting digitally printed sleeves for limited-edition campaigns and seasonal promotions. This technology is collapsing minimum order quantity thresholds that previously locked out mid-tier brands from premium 360-degree labeling.
UAE's Ministry of Climate Change and Environment is advancing plastic circularity rules that mandate recycled content thresholds in packaging substrates. Industrial consequence includes accelerated R&D into rPETG formulations compatible with existing heat tunnel infrastructure. Pharmaceutical applications in Saudi Arabia face the tightest compliance timelines as SFDA serialization deadlines approach.
Brand owners are consolidating sleeve procurement through direct converter relationships, bypassing traditional distributor networks. Hypermarket chains in Saudi Arabia now specify sleeve performance standards that favor suppliers with in-house design and pre-press capabilities. This consolidation is most visible in Riyadh-Jeddah corridor beverage manufacturing clusters where procurement centralization is displacing fragmented supplier bases.
GCC Shrink Sleeves Market Segmentation
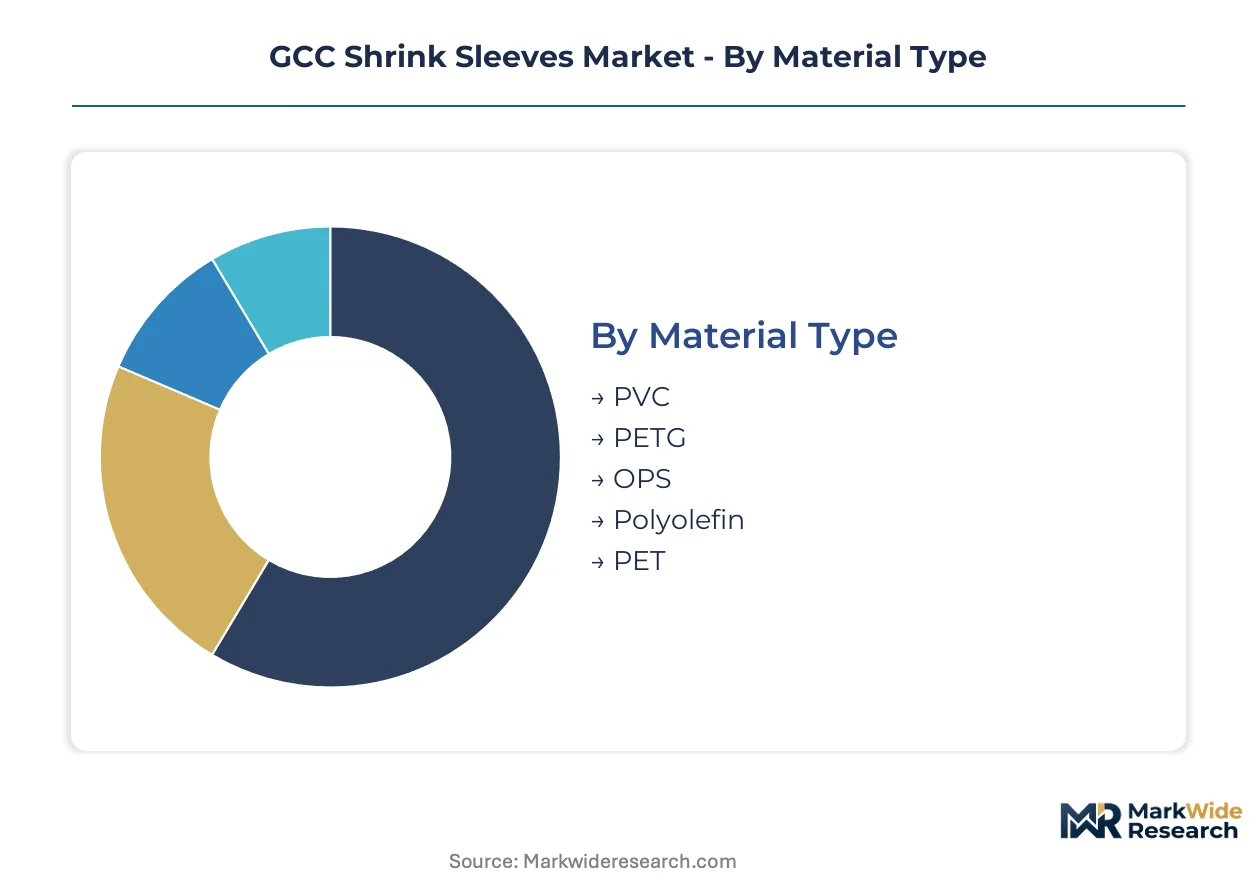
Shrink sleeve procurement patterns across the GCC diverge sharply by substrate performance requirements and end-use compliance intensity. Material selection, application purpose, and channel configuration each create distinct margin architectures that converters must navigate.
Material Type:
Cost tier differentiation in film substrates separates premium beverage accounts from commodity pharmaceutical and chemical labeling.
- PETG:Glycol-modified polyester delivers controlled shrinkage between 65-78% with superior print clarity on irregular bottle geometries. Saudi beverage bottlers in the Riyadh-Jeddah corridor specify PETG for premium carbonated and juice applications where 360-degree graphics registration is critical. SFDA serialization mandates are accelerating PETG adoption in pharmaceutical track-and-trace applications due to tamper-evident seal integrity.
- PVC:Polyvinyl chloride films between 40-50 microns offer cost positioning for standard beverage and chemical containers with regular geometries. UAE plastic circularity rules are compressing PVC procurement windows as recycled content thresholds tighten, though legacy heat tunnel infrastructure sustains volume in mid-tier beverage accounts.
- OPS:Oriented polystyrene provides high-shrink capability exceeding 75% for contoured cosmetic containers and specialty pharmaceutical vials where conformability trumps durability.
- Polyolefin:Cross-linked polyethylene and polypropylene formulations serve household chemical applications requiring chemical resistance and moisture barrier properties.
- PET:Standard polyester without glycol modification occupies niche positions in electronics packaging where dimensional stability under moderate heat is prioritized over shrinkage performance.
PETG holds installed capacity across Gulf converter networks. PVC is rotating down the share rankings as circularity frameworks advance.
End Use Industry:
Application maturity across GCC manufacturing clusters creates divergent growth trajectories and compliance cost burdens.
- Beverage Bottling:Carbonated soft drinks, bottled water, and juice segments command procurement density in Saudi Arabia's Riyadh-Jeddah corridor and UAE's Dubai-Abu Dhabi axis. Seasonal promotional cycles and hypermarket shelf differentiation requirements sustain demand for high-definition gravure and emerging digital print formats.
- Pharmaceuticals:SFDA serialization mandates and tamper-evident compliance requirements are forcing packaging upgrades across domestic Saudi drug manufacturing. Track-and-trace integration with shrink sleeve seals represents the steepest expansion trajectory among all end-use segments.
- Cosmetics:Premium skincare and fragrance brands in UAE retail environments specify decorative 360-degree labeling with metallic and holographic effects that command margin premiums over standard informative sleeves.
- Household Chemicals:Detergent and disinfectant bottling in Kuwait and Oman utilizes commodity-grade sleeves with chemical-resistant substrates and functional barrier properties.
- Electronics Packaging:Consumer electronics and accessories in UAE distribution hubs employ shrink sleeves for product identification and retail-ready presentation in duty-free and export channels.
Beverage bottling maintains revenue concentration. Pharmaceuticals is climbing the fastest as regulatory deadlines approach.
Application:
Margin architecture separates decorative premium positioning from functional compliance-driven procurement.
- Decorative Labeling:360-degree graphics coverage with high-definition gravure printing and specialty finishes targets hypermarket shelf differentiation in Saudi and UAE beverage and cosmetics sectors.
- Tamper Evident:Integral seal designs satisfy SFDA pharmaceutical serialization and food safety requirements across Gulf state regulators, with heat-activated perforation patterns providing visible breach indication.
- Brand Protection:Holographic elements, microtext, and covert authentication features serve premium cosmetics and electronics applications in UAE retail environments.
- Informative Labeling:Standard regulatory text and barcode applications occupy commodity positioning in household chemicals and basic beverage segments.
- Product Identification:SKU differentiation and logistics coding functions support warehouse and retail operations across GCC distribution networks.
Decorative labeling captures margin premiums. Tamper evident is expanding most quickly under pharmaceutical mandate pressure.
Distribution Channel:
Customer type configuration is shifting from fragmented distributor networks toward direct converter relationships.
- Direct Sales:Large-volume beverage and pharmaceutical manufacturers in Saudi Arabia's Riyadh-Jeddah corridor are consolidating procurement through direct converter agreements that bundle design, pre-press, and application technical support.
- Distributors:Regional packaging material distributors serve mid-tier accounts in Kuwait, Oman, and Qatar with inventory pooling and localized logistics.
- Contract Packaging Companies:Third-party bottling and filling operations in UAE free zones specify sleeve performance standards as part of integrated packaging service agreements.
- Wholesalers:Traditional bulk supply channels sustain commodity-grade sleeve flow to smaller beverage and chemical processors.
- Online Retail:Digital procurement platforms are emerging for standard substrate films and consumables among independent converters.
Direct sales commands relationship value. Contract packaging companies are gaining share fastest as outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across GCC states. Saudi buyers absorb premium PETG substrates for pharmaceutical compliance, while Kuwait and Oman processors remain anchored to cost-optimized PVC alternatives.
Saudi Arabia
SFDA serialization mandates for pharmaceuticals and Riyadh-Jeddah beverage bottling clusters drive substrate demand. The national pharmaceutical regulator enforces tamper-evident sleeve integration with track-and-trace systems. Domestic drug manufacturers in Riyadh and Jeddah are retrofitting packaging lines to meet compliance deadlines.
United Arab Emirates
Dubai-Abu Dhabi hypermarket chains and cosmetics retail expansion sustain decorative labeling procurement. MOCCAE plastic circularity rules are compressing PVC windows and accelerating rPETG formulation trials. Contract packaging operations in Jebel Ali free zones specify sleeve performance standards for integrated beverage services.
Kuwait
Household chemical bottling and mid-tier beverage processing dominate sleeve consumption. National standards bodies apply BIS-equivalent conformity assessment for imported film substrates. Industrial zones south of Kuwait City concentrate commodity-grade converter operations serving price-sensitive accounts.
Oman
Underpenetrated converter capacity and expanding beverage bottling create first-mover positioning opportunities. Environmental regulatory frameworks remain less prescriptive than UAE or Saudi standards. Sohar and Salalah industrial ports are attracting regional film distributors seeking Gulf market access.
Qatar
Food and beverage packaging for domestic consumption and export channels sustains steady sleeve demand. Import certification protocols for polymer substrates align with broader GCC technical regulations. Manufacturing clusters in Doha's industrial area serve localized bottling operations with limited domestic film extrusion.
GCC Shrink Sleeves Market Competitive Landscape
Regional film manufacturers and specialized converters split the market between upstream substrate control and downstream print differentiation. The competitive structure concentrates around petrochemical-linked supply security and gravure printing capability. Two archetypes dominate: integrated film extruders with captive resin access, and design-forward converters with pre-press and application technical support. Capacity expansion and direct procurement relationships with beverage bottlers represent the primary competitive vectors.
Among regional specialists, Golden Line Printing & Packaging exemplifies the high-definition gravure tier, while Taghleef Industries anchors upstream film manufacturing scale. Avery Dennison Corporation occupies a position bridging materials science and adhesive formulation for climate-adapted applications.
| Leading Market Players |
|---|
| Golden Line Printing & Packaging |
| Taghleef Industries |
| ASPCO |
| Huhtamaki |
| Avery Dennison Corporation |
| Saudi Modern Packaging Co. (Printopack) |
| Matrixpack |
| Amcor plc |
| Primex |
| Others |
Supply & Pricing Matrix
Jebel Ali Port freight corridors feed cost dynamics that amplify supply concentration effects across PETG film sourcing while compressing margin pools for downstream converters serving price-differentiated beverage accounts.
Pricing Analysis
After-sales technical service contracts for heat tunnel calibration and gravure cylinder maintenance drive lifetime value capture for sleeve converters. Three-tier pricing structure across premium, standard, and economy levels separates high-definition gravure beverage accounts from commodity pharmaceutical serialization sleeves and basic household chemical labeling. Cost compression in mid-tier PVC alternatives is intensifying because UAE plastic circularity rules accelerate substrate substitution timelines. Beverage bottlers in Saudi Arabia's Riyadh-Jeddah corridor show least price sensitivity due to SFDA compliance mandates, while Kuwait household chemical processors anchor to economy-tier procurement.
Supply Chain Analysis
Export-control restrictions on advanced film extrusion equipment limit technology transfer to domestic GCC manufacturing bases. PETG and PVC film supply concentrates in Saudi Arabia's petrochemical complexes, UAE's Jebel Ali industrial zones, and Taghleef Industries' regional extrusion assets. Raw material dependencies draw from crude-linked resin feedstocks, imported glycol modifiers, and specialized gravure cylinder tooling. Single-source vulnerability runs through limited domestic PETG film manufacturing capacity. Distribution runs through direct converter relationships with large-volume beverage and pharmaceutical manufacturers, supplemented by regional distributors serving mid-tier accounts in Kuwait, Oman, and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC shrink sleeve demand faces substitution pressure from pressure-sensitive labels and direct-to-container digital printing technologies that threaten 360-degree decorative sleeve volume in premium beverage applications.
For Market Incumbents: Insulate core beverage relationships through captive pre-press design capabilities and bundled heat tunnel technical service contracts that lock in switching costs. Deepen backward integration into rPETG formulation R&D ahead of UAE circularity compliance deadlines. Pharmaceutical serialization mandates from Saudi Arabia's SFDA create defensive moats for converters with tamper-evident seal integration expertise.
For New Entrants and Emerging Players: Pursue underpenetrated converter capacity in Oman's Sohar and Salalah industrial ports where beverage bottling expansion outpaces localized sleeve supply. Target high-definition digital printing convergence for seasonal promotional campaigns among mid-tier UAE beverage brands seeking short-run flexibility without gravure cylinder lead time penalties. Position through contract packaging company partnerships in Jebel Ali free zones.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core sleeve converting assets amid substrate transition uncertainty. Five-to-ten-year viability hinges on rPETG scale-up execution and digital printing technology integration. Watch for SFDA serialization deadline enforcement as inflection indicator for pharmaceutical-focused acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| rPETG Formulation Scale-Up | UAE MOCCAE circularity rules mandate recycled content thresholds that reshape substrate procurement. |
| Digital Printing Technology Integration | Inkjet convergence collapses minimum order quantities for seasonal beverage promotional campaigns. |
| Backward Integration into Film Extrusion | Captive PETG supply security reduces import dependency and petrochemical feedstock volatility exposure. |
| Direct Converter Relationship Consolidation | Hypermarket procurement centralization in Riyadh-Jeddah corridor displaces fragmented distributor networks. |
| Tamper-Evident Seal Capability Investment | SFDA pharmaceutical serialization mandates force packaging upgrades across domestic Saudi drug manufacturing. |
Research Methodology
Cross-validation between primary field interviews and secondary trade data anchors the qualitative findings on converter capacity and procurement patterns. Packaging plant managers, beverage brand procurement leads, pharmaceutical regulatory affairs specialists, and film distribution channel partners provided operational perspectives. Secondary sources include customs import records for PETG and PVC substrates, GCC petrochemical industry association reports, and SFDA regulatory filings. Bottom-up sleeve volume estimates triangulated against top-down packaging market sizing.
Calibration against historical CAGRs and elasticity assumptions shaped the projection framework across material type, end-use industry, application purpose, and distribution channel dimensions. Modeled outputs reflect substrate substitution timelines, digital printing adoption curves, and regulatory compliance cost burdens. Pharmaceutical serialization mandate deadlines and plastic circularity implementation schedules served as scenario inputs.
Macroeconomic conditions sit as an overlay; deviation in crude-linked resin pricing or Gulf petrochemical export volumes would shift the trajectory. Forecasts reflect documented assumptions about SFDA enforcement intensity and UAE circularity rule finalization. Material shifts in substrate technology breakthroughs or alternative labeling format cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market