
 North America Flexible Plastic Packaging Market | 2026-2036
North America Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flexible Plastic Packaging Market Insights
Market Context with Strategic Players
Capital-intensity divergence between integrated resin producers and specialized converters is rotating competitive advantage toward firms with captive polymer supply. Amcor plc leverages vertical integration across blown film extrusion to control cost volatility in polyethylene supply chains. Berry Global sustains manufacturing scale across multi-layer barrier film platforms that serve high-volume food processors. Sealed Air Corporation differentiates through engineered bubble and vacuum-seal technologies that command premium positioning in protective packaging segments.
Technical Definition and Structural Segments
North America Flexible Plastic Packaging comprises pliable polymer structures typically below 250 microns in thickness, manufactured through extrusion, blown film, or vacuum forming processes to provide containment, preservation, and transport protection for consumer and industrial goods. The primary commercial purpose centers on reducing material weight versus rigid alternatives while maintaining barrier performance against moisture, oxygen, and light intrusion. Pouches and bags capture the dominant share of food & beverage end-use demand driven by convenience-oriented portion control and resealability requirements. Polyethylene formulations anchor volume production due to cost efficiency and heat-seal compatibility, though polyethylene terephthalate layers gain traction in premium applications demanding clarity and printability.
Regulatory Frame and Forward-Looking Close
The US EPA oversees recycling infrastructure mandates and resin identification standards that directly influence converter material selection, while state-level extended producer responsibility laws in California and Maine impose fee structures favoring recyclable mono-material constructions. Health Canada and PMRA regulate food-contact substances and migration limits that determine acceptable additive packages and coextrusion architectures. FDA compliance for indirect food additives remains a non-negotiable market access threshold for all domestic and imported flexible packaging sold into US food channels. Stakeholders must monitor evolving state-by-state EPR implementation timelines and resin recycling certification requirements to preempt compliance-driven sourcing disruptions.
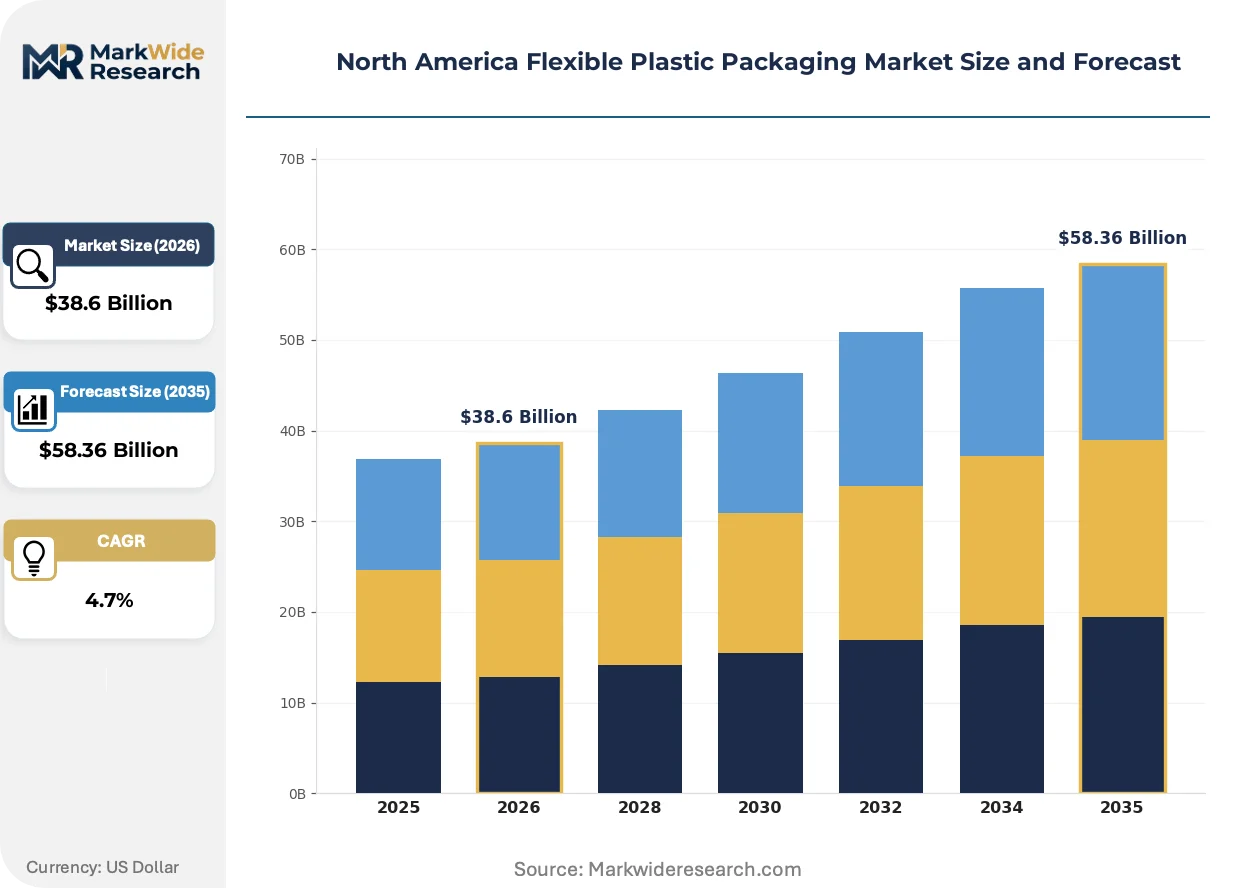
Market Dynamics
Extended producer responsibility frameworks across California and Maine are forcing converters to abandon multi-layer barrier films in favor of recyclable mono-material designs, compressing formulation flexibility while demanding capital redeployment toward compatible extrusion lines.
Growth Catalysts
- EPR fee structures in California:State-level extended producer responsibility laws impose cost penalties on non-recyclable packaging, accelerating converter investment in polyethylene-compatible pouch platforms for food brands seeking compliance certainty.
- Ready-to-eat meal portioning:Food processors are expanding pouch-based packaging for single-serve and resealable applications, pulling demand toward high-clarity polyethylene terephthalate laminates with modified atmosphere barrier properties.
- Midwest manufacturing corridor concentration:Resin supply proximity to blown film extrusion facilities in Illinois and Ohio reduces freight-in costs for converters serving regional food & beverage customers.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings transmit directly to polyethylene resin contracts, compressing converter margins during upstream cost spikes without immediate pass-through mechanisms.
- Multi-layer technical lock-in:Existing high-barrier coextrusion lines cannot accommodate mono-material specifications without substantial retooling, stranding capital in incompatible equipment.
- Aluminum foil substitution threat:Metalized films and foil laminates retain superior oxygen barrier performance for extended shelf-life applications, limiting polyethylene penetration in premium meat and dairy segments.
Strategic Opportunities
- Ontario industrial packaging cluster:Underpenetrated demand from Canadian agricultural exporters creates white space for converters offering bulk agricultural film with cold-weather flexibility specifications.
- Chemical recycling infrastructure:Emerging pyrolysis and depolymerization facilities in Texas and Louisiana enable circular feedstock claims for brands targeting California's recycled content mandates.
- Smart packaging convergence:Integration of time-temperature indicators and RFID tags with flexible substrates opens premium positioning for pharmaceutical and perishable food logistics applications.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing heat-seal performance with recyclability requirements command premium compensation, constraining mid-tier converter R&D velocity.
- FDA food-contact notification timelines:Novel additive packages for enhanced barrier properties face 120-day review cycles, delaying product launches and compressing innovation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flexible Plastic Packaging Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps End User: Food & Beverage, Healthcare, Personal Care, Industrial Material: Polyethylene, Polypropylene, Polyethylene Terephthalate, Others Technology: Extrusion, Vacuum Forming, Injection Molding, Blown Film |
| Companies Covered | Amcor plc, Sealed Air Corporation, Sonoco Products Company, Berry Global, Mondi Group, ProAmpac, Transcontinental Inc., Huhtamaki Oyj, Novolex Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flexible Plastic Packaging Market Trends and Innovations
Material science advances and regulatory compliance mandates are converging to reshape converter capabilities, with sustainability claims and functional performance now requiring simultaneous optimization rather than sequential trade-offs.
Mono-material polyethylene barrier films is bifurcating the market between legacy multi-layer converters and specialized single-polymer specialists. Major food retailers are mandating store-dropoff recyclable packaging by 2027, forcing rapid adoption of ethylene vinyl alcohol coextrusions that sacrifice some oxygen barrier for sortation compatibility. The structural consequence is compressing demand for nylon and aluminum oxide layers while expanding capacity for high-performance polyethylene variants.
California's SB 54 implementation timeline is creating phased compliance obligations that escalate through 2032. The regulation mandates 30% recycled content thresholds and source reduction targets that directly influence converter resin procurement contracts. Food & beverage brands with national distribution footprints are most affected, responding by consolidating supplier bases toward converters with verified mass-balance certification and mechanical recycling partnerships.
Direct-to-retailer procurement contracts are displacing traditional distributor-mediated purchasing for mid-volume flexible packaging buyers. Large grocery chains and meal-kit services are establishing preferred supplier programs that bypass regional packaging distributors, extracting volume commitments in exchange for multi-year contract security. This pattern is most visible in the US Southeast and Texas markets where retail consolidation has advanced furthest.
North America Flexible Plastic Packaging Market Segmentation
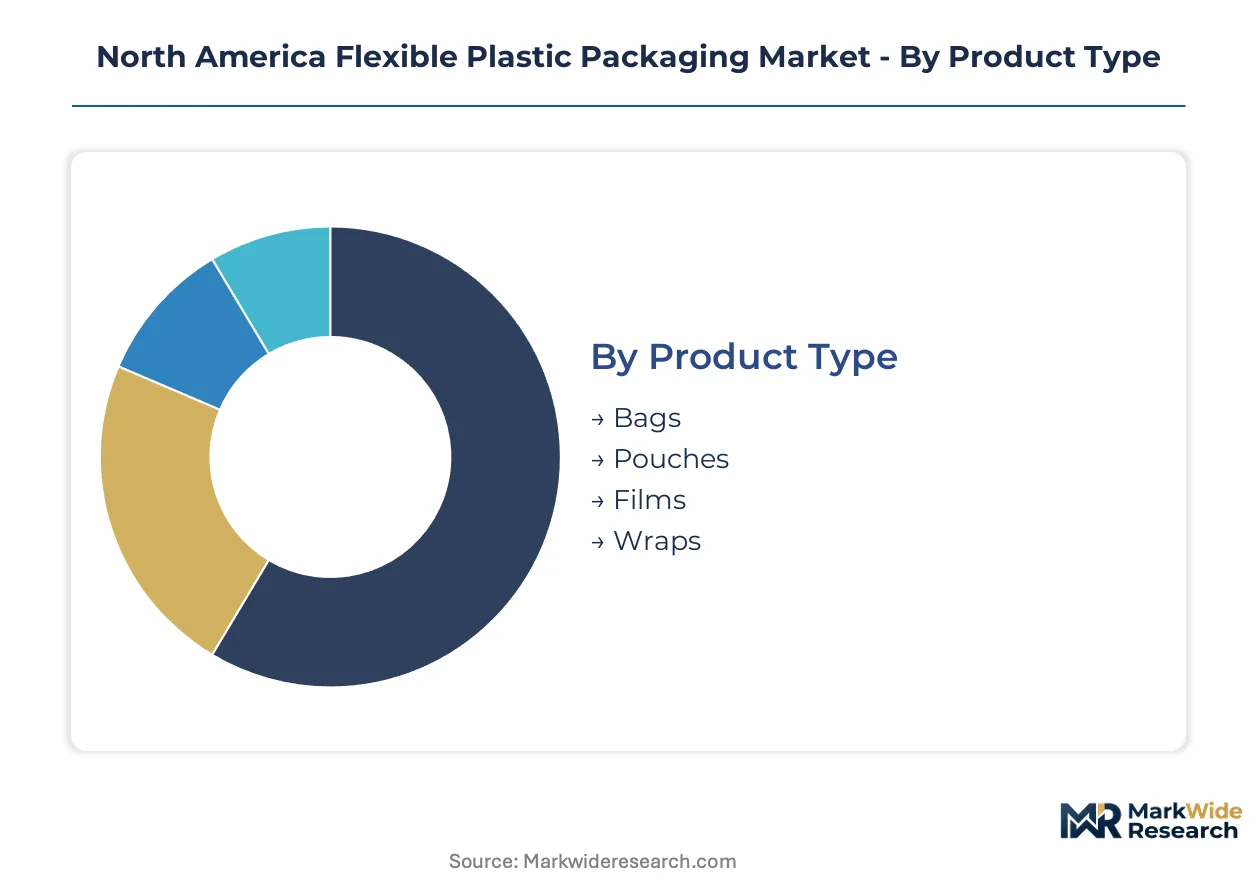
Segmentation in flexible plastic packaging reveals how regulatory pressure and material science constraints reshape procurement patterns across distinct product categories. Food safety mandates from FDA and state EPR frameworks fragment demand along material compatibility lines, forcing converters to align technical capabilities with compliance requirements rather than pure cost optimization.
Product Type:
FDA food-contact notification requirements and California SB 54 recyclability standards differentiate pouch and bag specifications from film and wrap alternatives, with mono-material constructions commanding procurement preference in regulated channels.
- Pouches:Multi-layer barrier structures with resealable zipper closures and spout fitments dominate ready-to-eat meal applications. Demand concentrates in the US Midwest manufacturing corridor where blown film extrusion facilities supply regional food processors with modified atmosphere packaging for extended shelf-life proteins.
- Bags:Gusseted and wicketed polyethylene formats with high-clarity sealant layers serve bulk food and retail carryout applications. Ontario's industrial packaging cluster drives specialized demand for cold-weather flexibility specifications in agricultural export logistics.
- Films:Cast and oriented polyethylene terephthalate laminates provide printability and barrier performance for lidding and overwrap applications.
- Wraps:Cling film and stretch hood formats prioritize load containment and breathability for fresh produce distribution.
Pouches handle the majority of throughput; bags are the fastest mover on share.
End User:
Customer procurement scale and regulatory exposure stratify converter relationships, with national food brands demanding mass-balance certification unavailable to smaller personal care and industrial buyers.
- Food & Beverage:Modified atmosphere packaging for proteins, dairy, and prepared meals requires oxygen barrier performance combined with FDA compliance for indirect food additives. California's recycled content mandates pull national brands toward verified mechanical recycling partnerships, consolidating supplier bases.
- Healthcare:Sterile barrier systems for medical devices and pharmaceutical products demand validated seal integrity and particulate control. FDA 510(k) clearance timelines and USP Class VI biocompatibility requirements constrain material selection to established resin grades with documented extractables profiles.
- Personal Care:Stand-up pouches and sachets for cosmetics and toiletries prioritize print registration and shelf presence over barrier performance.
- Industrial:Heavy-duty shrink film and pallet wrap applications emphasize puncture resistance and load stability for manufacturing supply chains.
Food & Beverage commands the dominant procurement volume; Healthcare shows the steepest expansion trajectory as sterile barrier demand climbs.
Material:
Resin selection balances heat-seal performance, barrier properties, and sortation compatibility under evolving state-level extended producer responsibility frameworks.
- Polyethylene:Linear low-density and metallocene catalyzed grades anchor volume production due to cost efficiency, heat-seal compatibility, and emerging chemical recycling pathway viability. Texas and Louisiana pyrolysis facilities enable circular feedstock claims for brands targeting California compliance thresholds.
- Polypropylene:Cast and oriented films provide stiffness and temperature resistance for retort and hot-fill applications. Biaxially oriented variants gain traction in snack food lidding where clarity and dead-fold characteristics matter.
- Polyethylene Terephthalate:Amorphous and glycol-modified grades deliver premium clarity and printability for beverage labels and high-visibility food packaging.
- Others:Nylon and ethylene vinyl alcohol coextrusions serve niche high-barrier applications despite recyclability penalties.
Polyethylene carries the volume base; Polypropylene is expanding most quickly as retort pouch adoption spreads.
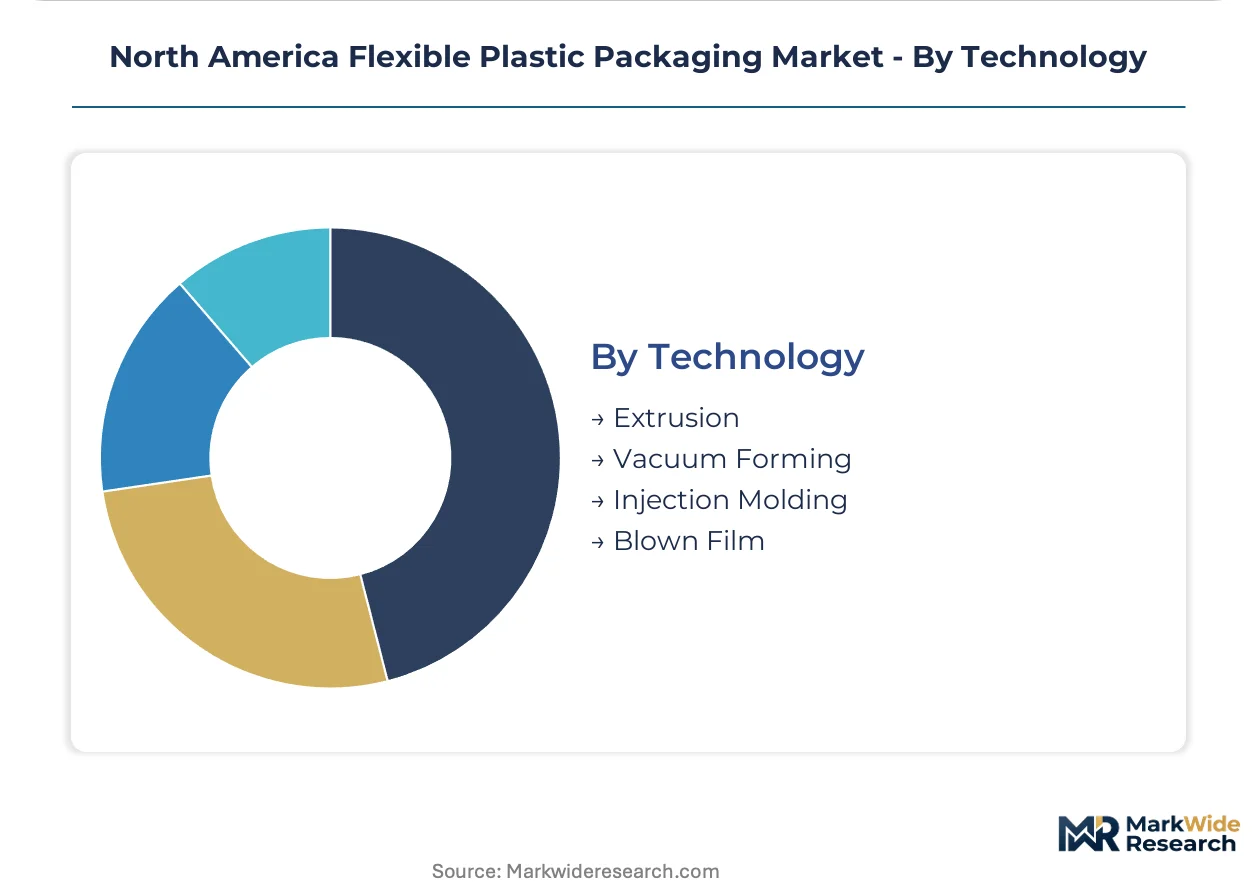
Technology:
Capital equipment compatibility with mono-material specifications determines converter positioning under EPR-driven material transitions.
- Blown Film:Multi-layer coextrusion lines produce the bulk of food-grade barrier films, though legacy equipment requires substantial retooling for recyclable mono-material constructions. Illinois and Ohio facilities leverage resin supply proximity to serve regional food processors.
- Extrusion:Cast film and sheet extrusion lines deliver gauge consistency and optical clarity for lidding and label applications. Water-quenched processes enable high-speed production of transparent polyethylene terephthalate structures.
- Vacuum Forming:Thermoformed trays and blisters serve medical device and consumer goods containment with formed rigidity.
- Injection Molding:Rigid-fitment production for spouts, caps, and closures integrates with flexible pouch assembly operations.
Blown Film dominates installed capacity; Extrusion is gaining share fastest as cast film clarity requirements spread across premium applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the US Midwest manufacturing corridor where resin supply proximity reduces freight-in costs, while Canadian converters absorb higher logistics premiums serving dispersed agricultural export markets across Ontario and Quebec.
United States
Food processors in Illinois and Ohio drive demand for modified atmosphere pouches serving extended shelf-life proteins. EPA recycling infrastructure mandates and California's SB 54 extended producer responsibility law impose 30% recycled content thresholds by 2032. The Midwest manufacturing corridor anchors blown film extrusion capacity within 200 miles of major polyethylene resin production.
Canada
Agricultural exporters in Ontario and Quebec require bulk agricultural films with cold-weather flexibility specifications for grain and fertilizer logistics. Health Canada and PMRA regulate food-contact migration limits that determine acceptable additive packages for domestic converters. Toronto-Windsor industrial packaging cluster serves cross-border supply chains with specialized capacity for temperature-resistant formulations.
Mexico
Processed food manufacturers in Nuevo León and Jalisco expand pouch-based packaging for ready-to-eat meals targeting US export channels. Mexican environmental regulations under SEMARNAT are aligning with California-style recyclability standards for cross-border brand compliance. Monterrey manufacturing hub attracts converter investment seeking duty-advantaged access to US Southwest markets.
North America Flexible Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding upstream pricing power while specialized converters compete on formulation agility and customer proximity. The vendor base separates into three tiers: multinational integrated packaging conglomerates with captive polymer supply, regional scale converters serving food processor clusters, and niche specialists in medical-grade barrier systems. Consolidation pressure intensifies as California's EPR timelines force smaller converters toward acquisition or equipment obsolescence. Dominant competitive moves include backward integration into resin distribution partnerships and geographic expansion toward underpenetrated Canadian agricultural export corridors.
Among North American packaging conglomerates, Amcor plc and Sealed Air Corporation exemplify contrasting strategic positions. Amcor's blown film extrusion network leverages vertical integration across polyethylene supply chains to manage resin cost volatility. Sealed Air occupies a premium-tier position through engineered protective packaging technologies that command pricing power in sterile barrier and vacuum-seal applications. Berry Global represents the scale-driven archetype, sustaining multi-platform manufacturing capacity that serves high-volume food processor procurement consolidation.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Sonoco Products Company |
| Berry Global |
| Mondi Group |
| ProAmpac |
| Transcontinental Inc. |
| Huhtamaki Oyj |
| Novolex Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term resin offtake contracts between polyethylene producers and Midwest converters lock in feedstock access while insulating regional players from ethylene spot volatility that compresses margins for unhedged competitors serving California's recycled-content mandates.
Pricing Analysis
The customization-premium spread separates standard blown-film polyethylene from configured-to-order multi-layer barrier structures with modified atmosphere properties. Three-tier pricing structure across premium, standard, and economy levels reflects FDA food-contact certification grade and volume scale commitments from national food processors. Pricing pressure stems from California SB 54 compliance costs as converters absorb retooling investments without immediate pass-through to brands. Mid-volume regional food processors show highest price sensitivity, while national meal-kit services with EPR exposure accept premium positioning for mass-balance certified supply.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast resin production to Ontario agricultural exporters run 15-20% above Midwest corridor baselines due to cross-border documentation and dispersed delivery points across Quebec grain terminals. Raw material supply concentrates in Texas and Louisiana pyrolysis corridors, with Illinois and Ohio extrusion capacity feeding regional food processor demand. The chain draws from ethylene feedstock tethered to crude oil volatility, creating margin compression risk during upstream cost spikes. Distribution runs through direct-to-retailer procurement contracts that displace traditional regional distributors for mid-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for extrusion line optimization and FDA compliance consulting expand faster than commodity film supply, converting capital equipment vendors into recurring-revenue partners as converters face mono-material retooling mandates.
For Market Incumbents: Shield market position through backward integration into chemical recycling partnerships that secure circular feedstock claims for California compliance, while consolidating regional scale converters stranded by incompatible multi-layer equipment. The priority lever sits with captive resin distribution agreements that reduce ethylene cost volatility exposure. For New Entrants and Emerging Players: FDA food-contact notification fast-tracks for novel mono-material barrier additives open procurement channels with national brands seeking compliant supply alternatives to legacy multi-layer incumbents. White space concentrates in Ontario's cold-weather agricultural film specifications and Texas pyrolysis feedstock verification services. Go-to-market leverage rests on mass-balance certification partnerships with mechanical recycling operators. For Investors and Strategic Acquirers: Capital is best deployed toward specialized mono-material converters with validated California SB 54 compliance pathways and established food-brand supplier relationships, viewed through a viability window where EPR enforcement escalates equipment obsolescence risk for multi-layer specialists. The inflection signal to monitor is state-by-state EPR adoption timelines beyond California and Maine.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Conversion | Retooling multi-layer coextrusion capacity for recyclable polyethylene specifications satisfies California SB 54 mandates. |
| Chemical Recycling Partnership | Pyrolysis feedstock agreements with Texas facilities enable circular content claims for national brand procurement. |
| Direct-to-Retailer Contracting | Bypassing regional distributors secures multi-year volume commitments from consolidated grocery chains. |
| FDA Fast-Track Certification | Accelerated food-contact notifications for novel barrier additives compress product launch timelines versus competitors. |
| Cold-Weather Formulation Development | Temperature-resistant polyethylene variants capture Ontario agricultural export demand with premium positioning. |
Research Methodology
The analysis maps blown-film extrusion, cast film, and thermoforming sub-sectors, each validated through procurement directors at food processors, extrusion line operators, resin supply managers, and FDA regulatory consultants. Primary interview insights triangulate against secondary sources including EPA recycling infrastructure filings, California SB 54 implementation documents, SEC 10-K disclosures from packaging conglomerates, and Health Canada food-contact substance databases. Bottom-up capacity estimates from regional manufacturing clusters reconcile with top-down demand projections from end-use consumption patterns.
Consistency checks validate volume and value outputs against external benchmarks including resin production disclosures, trade flow data, and food processor packaging spend patterns. Segmentation models incorporate product type, end-use industry, material formulation, and manufacturing technology dimensions across the projection horizon. CAGRs derive from trend extrapolation of historical capacity utilization, regulatory compliance cost trajectories, and substitution elasticity between mono-material and multi-layer barrier formats.
Decision-makers should treat outputs as directional under assumptions of California SB 54 enforcement continuity and ethylene feedstock price correlation with crude oil benchmarks; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Europe Flexible Packaging Market