
 Indonesia Flexible Packaging Market | 2026-2036
Indonesia Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Flexible Packaging Market Foresight
Buyer concentration among Indonesian fast-moving consumer goods conglomerates is rebalancing as regional snack and instant food brands multiply order volumes. PT Indopoly Swakarsa Industry Tbk leverages its blown film extrusion scale to serve multinational food accounts. PT Trias Sentosa Tbk anchors the value chain through metallized film capabilities that extend shelf life for tropical distribution. PT Indonesia Toppan Group competes via gravure printing precision for premium personal care labels.
Indonesia flexible packaging comprises multi-layer polymer structures, typically combining polyethylene and polypropylene with barrier coatings, produced through blown film extrusion or cast film processes for product containment and shelf-life extension. Films dominate material throughput due to their adaptability across form-fill-seal lines in humid processing environments. Pouches capture expanding share as beverage and sauce brands shift from rigid containers to stand-up formats with spout fitments. Polyethylene sustains volume leadership while nylon barrier layers penetrate healthcare and retort applications demanding oxygen and moisture resistance.
BIS-equivalent national standards and Indonesia's halal certification mandate under the National Halal Agency shape material sourcing, adhesive selection, and supplier audit protocols for converters. The Ministry of Environment and Forestry advances extended producer responsibility frameworks that pressure film recyclability and mono-material design transitions. Stakeholders must monitor regulatory alignment between provincial waste management ordinances and national circular economy targets to anticipate compliance cost trajectories and recycling infrastructure investments.
Market Dynamics
Indonesia's mandatory halal certification framework under the National Halal Agency is restructuring material sourcing protocols and supplier qualification timelines across the flexible packaging value chain. This regulatory force is compressing procurement cycles and elevating traceability investments.
Growth Catalysts
- Halal Certification Mandate:The National Halal Agency's phased implementation is accelerating investments in segregated production lines and certified adhesive systems. Food and beverage brands are prioritizing compliant converters to secure distribution access.
- Instant Noodle and Snack Expansion:Pouch-based formats are multiplying across Java and Sumatra as regional manufacturers scale production. Form-fill-seal automation investments are rising to match volume throughput.
- Metallized Film Shelf-Life Extension:Barrier-coated polyester and aluminum-laminated structures are penetrating tropical distribution networks. Exporters to ASEAN markets are specifying oxygen transmission rate thresholds below 0.1 cc/m²/day.
Market Restraints
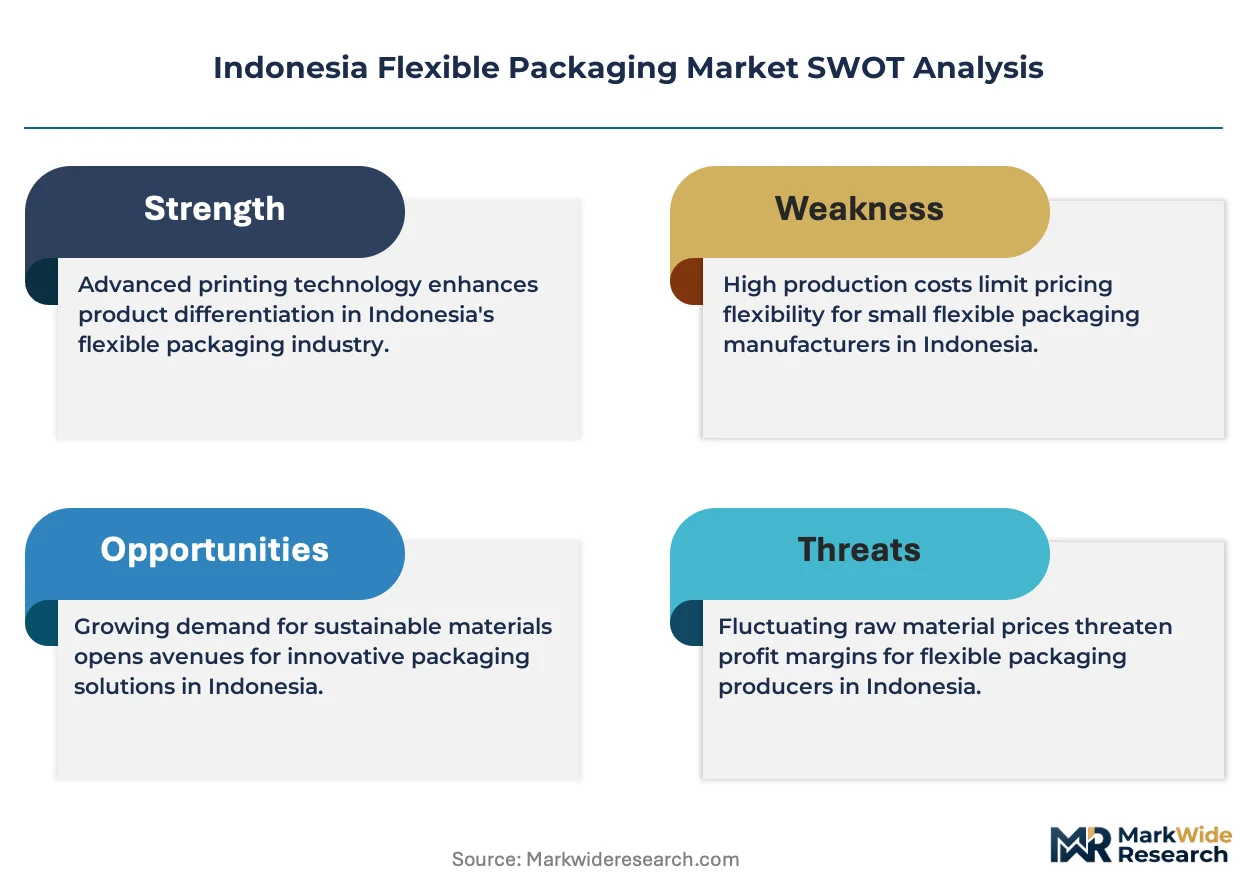
- Polymer Feedstock Volatility:Naphtha-derived polyethylene and polypropylene resin costs fluctuate with regional refinery output. Indonesian converters lack captive cracker capacity to hedge input exposure.
- Barrier Technology Import Dependence:Metallization chambers and vacuum deposition equipment concentrate among Japanese and European suppliers. Domestic equipment fabrication capabilities remain underdeveloped for precision coating applications.
- Extended Producer Responsibility Compliance Costs:The Ministry of Environment and Forestry's circular economy roadmap is mandating recyclability design standards ahead of infrastructure readiness. Mono-material transition investments strain mid-tier converter margins.
Strategic Opportunities
- Eastern Indonesia Underpenetration:Sulawesi and Papua present whitespace for pouch converting capacity serving processed seafood exports. Cold chain logistics gaps currently limit format adoption.
- Healthcare Barrier Film Migration:Pharmaceutical blister packs and medical device pouches are transitioning from rigid trays to high-barrier laminates. Nylon and EVOH coextrusion demand is rising for moisture-sensitive APIs.
- Digital Printing Convergence:Gravure cylinder costs and minimum order quantities are compressing as inkjet and electrophotographic systems achieve food-contact compliance. Short-run customization for seasonal SKUs is becoming economically viable.
Industry Challenges
- Halal Auditor Certification Bottleneck:Qualified personnel to validate material traceability and production segregation are scarce relative to application volume. Training program expansion lags regulatory deadline acceleration.
- Recycling Infrastructure Misalignment:Multi-layer film collection and sorting systems are absent in provincial waste management networks. Design-for-recycling investments lack offtake certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Flexible Packaging Market |
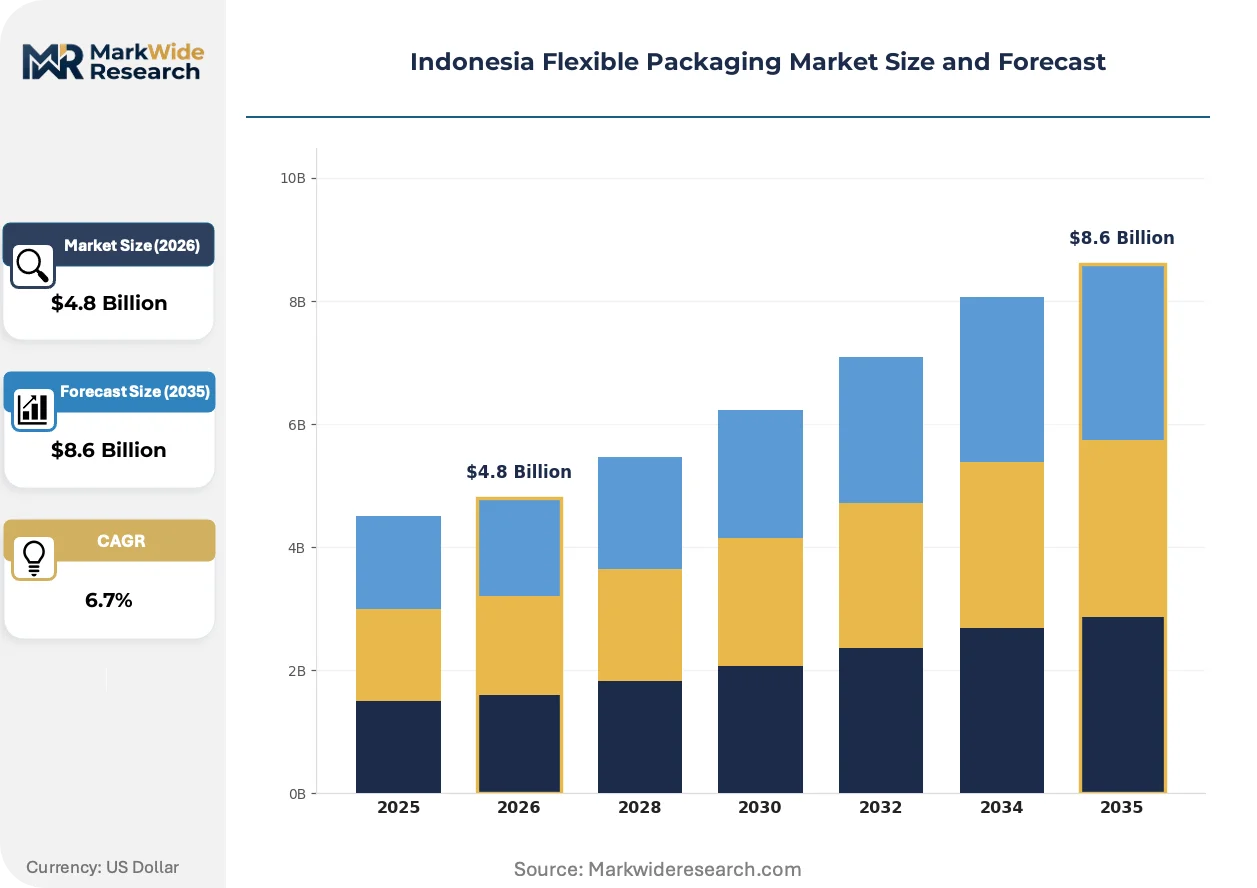
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps Material: Polyethylene, Polypropylene, Nylon, Others End User: Food, Beverage, Personal Care, Healthcare Printing Technology: Flexographic, Gravure, Digital, Rotogravure |
| Companies Covered | PT Artec Package Indonesia, PT Supernova Flexible Packaging, PT ePac Flexibles Indonesia, PT Indopoly Swakarsa Industry Tbk, PT Trias Sentosa Tbk, PT Indonesia Toppan Group, PT Primajaya Eratama, PT Argha Karya Prima Industry Tbk, PT Dinakara Putra, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Flexible Packaging Market Shifts & Advancements
Digital printing and mono-material barrier structures are actively restructuring Indonesia's flexible packaging technical base. Converter investment patterns are pivoting toward equipment that accommodates shorter runs and simplified polymer compositions.
Water-based inkjet printing systems with food-contact compliance are overtaking gravure for medium-run flexible packaging applications. Seasonal sauce and condiment brands in Greater Jakarta are adopting 5,000-20,000 unit production lots. This technology is compressing cylinder engraving lead times from weeks to hours while enabling variable data integration for traceability codes.
Indonesia's National Halal Agency certification timeline is hardening material segregation requirements across adhesive and coating selection. Converters must now document supply chain provenance for every lamination layer. Personal care and pharmaceutical pouch segments are absorbing the highest compliance costs as they retrofit cleanroom-adjacent production zones.
Buyer consolidation among fast-moving consumer goods conglomerates is fragmenting as regional snack brands multiply order frequencies. Direct procurement relationships with mid-tier converters are displacing distributor-mediated purchasing in Surabaya and Bandung industrial corridors. Instant noodle manufacturers in West Java are piloting vendor-managed inventory programs to secure capacity allocation during peak seasons.
Indonesia Flexible Packaging Market Segmentation
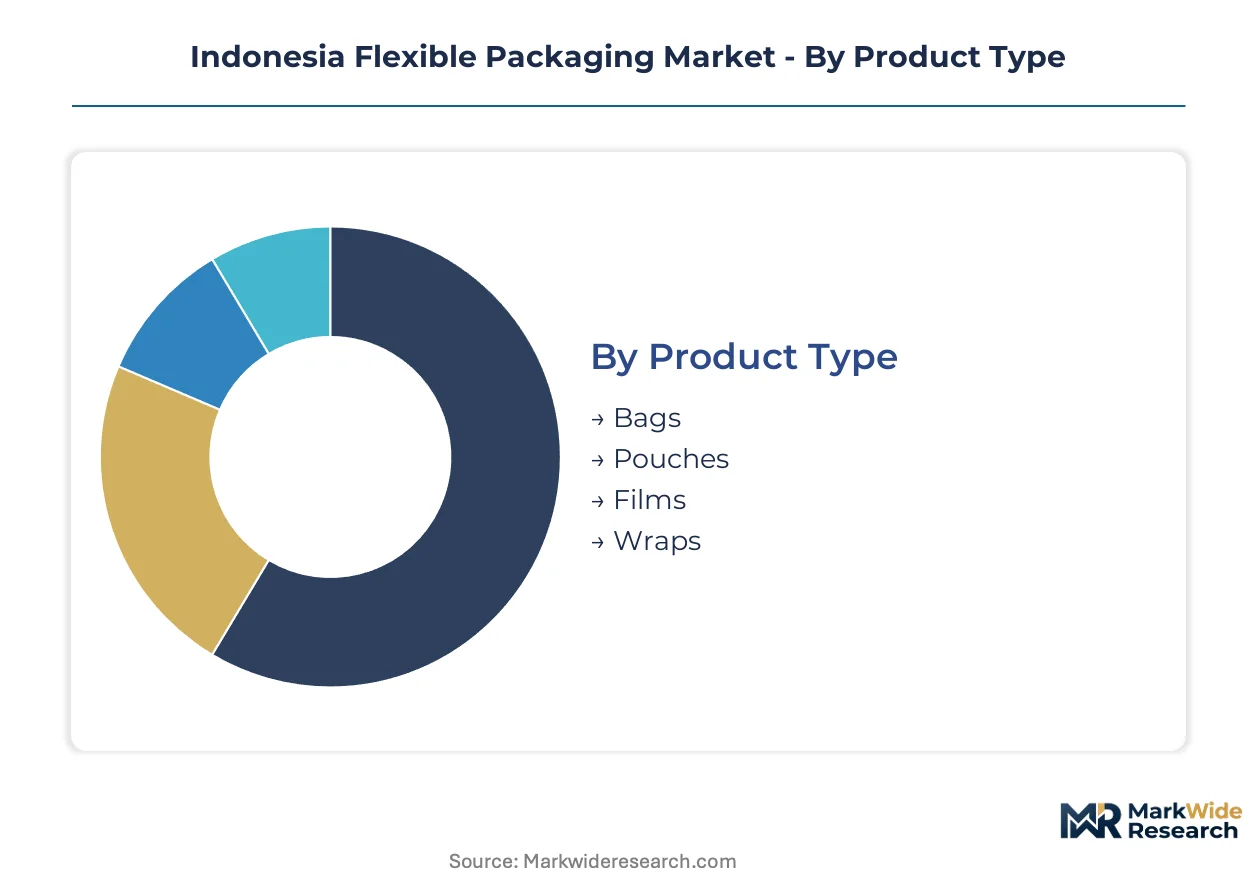
Segmentation in Indonesia's flexible packaging market reveals how halal certification requirements, tropical distribution challenges, and converter capability gaps create divergent competitive dynamics across product formats and material specifications.
Product Type:
Halal certification under Indonesia's National Halal Agency imposes distinct segregation protocols on each format—pouches and bags require certified adhesive systems, while films and wraps face simpler compliance pathways for food-contact applications.
- Pouches:Stand-up formats with spout fitments combine multi-layer barrier structures of polyethylene, nylon, and metallized films. Instant noodle and sauce brands in Greater Jakarta's industrial corridor are migrating rigid containers to pouch-based alternatives, though retort-capable specifications demand oxygen transmission rates below 0.1 cc/m²/day for tropical shelf stability.
- Films:Blown and cast extrusion outputs dominate throughput volume, with polyethylene and polypropylene coextrusions serving form-fill-seal automation across humid processing environments. Java-based converters cluster capacity around metallized and barrier-coated variants for snack food exporters targeting ASEAN distribution networks.
- Bags:Three-side-seal and gusseted configurations serve bulk agricultural commodities and industrial intermediates with lower barrier requirements than pouches.
- Wraps:Stretch and shrink formats concentrate in palletized logistics and fresh produce bundling, with limited halal compliance burden relative to direct food-contact segments.
Leading the category by volume: Films. Growing fastest: Pouches.
Material:
Cost tiers stratify sharply—commodity polyolefins anchor mass-market applications while engineered barrier resins command premium positioning in pharmaceutical and retort food segments.
- Polyethylene:Low-density and linear low-density grades sustain volume leadership across blown film extrusion lines. Indonesian converters rely on naphtha-derived resin imports, exposing margins to regional refinery output volatility without captive cracker capacity for hedge.
- Polypropylene:Cast film biaxially oriented variants serve snack lamination and label faces with clarity and stiffness advantages. BOPP demand clusters with metallization chambers for barrier extension, though vacuum deposition equipment concentrates among Japanese and European suppliers.
- Nylon:Polyamide coextrusions penetrate healthcare blister packs and medical device pouches requiring moisture and oxygen resistance for API stability.
- Others:EVOH and specialty adhesives occupy niche positions in high-barrier retort and pharmaceutical applications with stringent National Halal Agency documentation requirements.
Dominating procurement spend: Polyethylene. Expanding most quickly: Nylon.
End User:
Application-specific performance requirements drive material selection divergence—food and beverage segments prioritize moisture barriers for tropical distribution, while healthcare demands oxygen transmission precision.
- Food:Instant noodle, snack, and processed seafood manufacturers across Java and Sumatra multiply pouch-based format orders. Halal certification mandates from the National Halal Agency compress procurement cycles and elevate traceability investments for adhesive and coating provenance.
- Beverage:Stand-up pouches with spout fitments displace rigid bottles in juice and condiment segments, though cold chain logistics gaps in Eastern Indonesia limit format penetration for dairy and probiotic applications.
- Personal Care:Premium labels and sachet formats gravitate toward gravure printing precision for brand differentiation, with the highest compliance costs for cleanroom-adjacent production zone retrofits.
- Healthcare:Pharmaceutical blister packs and medical device pouches transition from rigid trays to high-barrier laminates, with nylon and EVOH coextrusion demand climbing for moisture-sensitive API protection.
Commanding the largest share: Food. Climbing the fastest: Healthcare.
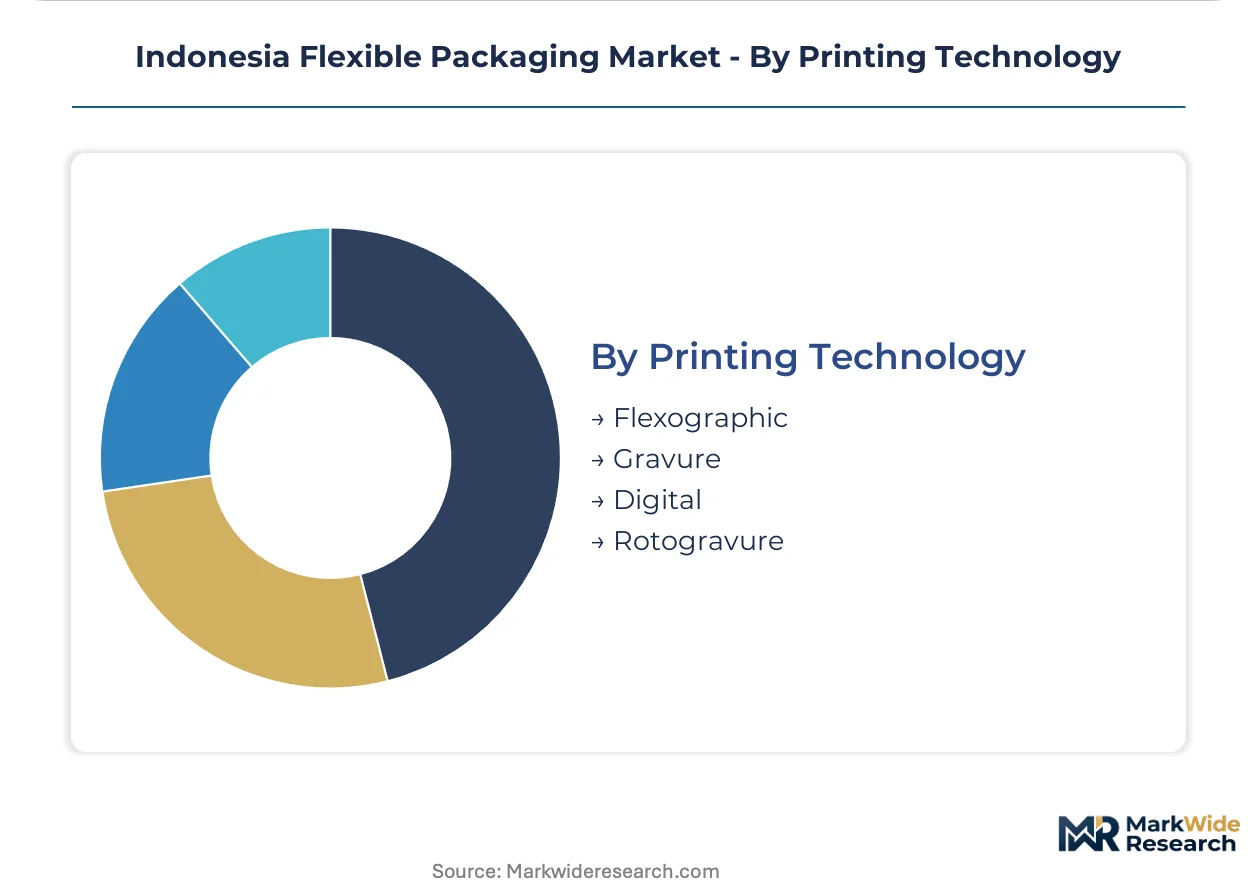
Printing Technology:
Customer type splits the technology base—multinational FMCG conglomerates gravitate toward gravure cylinder investments for long-run economies, while regional snack brands fragment toward digital systems for short-run flexibility.
- Gravure:Cylinder-based systems deliver precision for premium personal care labels and high-volume food packaging with consistent color reproduction. PT Indonesia Toppan Group anchors this segment through metallized film gravure capabilities.
- Digital:Inkjet and electrophotographic systems achieve food-contact compliance, enabling 5,000-20,000 unit production lots for seasonal sauce and condiment brands. Variable data integration supports traceability code requirements under halal certification protocols.
- Flexographic:Central impression drum configurations serve medium-run flexible packaging with water-based ink systems, bridging cost efficiency between gravure and digital.
- Rotogravure:Publication-grade cylinder engraving extends to decorative laminates with extended gamut capabilities for export-oriented cosmetic packaging.
Holding volume leadership: Gravure. Gaining share fastest: Digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian flexible packaging demand concentrates in Greater Jakarta's industrial corridor, where converting capacity clusters serve instant noodle and snack food manufacturers expanding pouch-based formats across Java and Sumatra.
Java
Instant noodle and sauce brands in Greater Jakarta and Bandung are migrating rigid containers to stand-up pouches with spout fitments. The National Halal Agency's certification mandate compresses procurement cycles for adhesive and coating provenance documentation. West Java's industrial zones host the densest concentration of form-fill-seal automation investments.
Sumatra
Processed seafood exporters in Medan and Palembang specify oxygen transmission rate thresholds below 0.1 cc/m²/day for tropical shelf stability. The Ministry of Environment and Forestry's extended producer responsibility frameworks pressure mono-material design transitions ahead of recycling infrastructure readiness. North Sumatra's converting capacity serves ASEAN distribution networks.
Sulawesi
Processed seafood pouch demand from Makassar and Manado faces cold chain logistics gaps that limit format adoption for dairy applications. Provincial waste management ordinances lack alignment with national circular economy targets, creating compliance uncertainty for recyclability investments. South Sulawesi's industrial corridor remains underpenetrated relative to Java-based capacity.
Papua
Remote geography and infrastructure constraints suppress flexible packaging adoption for food and beverage applications. The National Halal Agency's auditor certification bottleneck intensifies in frontier regions where qualified personnel are scarce relative to application volume. Jayapura's limited converting presence relies on Java-based supply chains.
Bali and Nusa Tenggara
Tourism-driven personal care and premium food segments in Denpasar gravitate toward gravure-printed labels with shorter run requirements. Digital printing systems achieve food-contact compliance for seasonal SKU customization. The island's isolation from Java's industrial corridor elevates logistics costs for barrier film procurement.
Indonesia Flexible Packaging Market Competitive Landscape
Java-based producers anchor one tier; Sumatra and Sulawesi specialists hold regional distribution positions. The vendor base fragments across blown film extrusion scale players, metallized film capability holders, and gravure printing precision specialists. Three archetypes dominate: multinational-anchored converters with halal-certified production lines, mid-tier regional suppliers serving snack brand proliferation, and digital printing adopters targeting short-run customization. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters secure raw material allocation during peak seasons.
Within the scale-driven tier, PT Indopoly Swakarsa Industry Tbk and PT Trias Sentosa Tbk occupy positions reflecting blown film extrusion and metallized film capabilities respectively. PT Indonesia Toppan Group represents the precision-printing archetype for premium personal care and label applications. These entities exemplify how technical specialization aligns with distinct customer segments across Indonesia's halal-certification-compliant value chain.
| Leading Market Players |
|---|
| PT Artec Package Indonesia |
| PT Supernova Flexible Packaging |
| PT ePac Flexibles Indonesia |
| PT Indopoly Swakarsa Industry Tbk |
| PT Trias Sentosa Tbk |
| PT Indonesia Toppan Group |
| PT Primajaya Eratama |
| PT Argha Karya Prima Industry Tbk |
| PT Dinakara Putra |
| Others |
Supply & Pricing Matrix
Blown film extrusion operator concentration in West Java's industrial corridor compresses labor-cost differentials into pricing-tier spreads across halal-certified and standard production lines. National Halal Agency compliance investments widen the premium between segregated and conventional converting capacity.
Pricing Analysis
Volume throughput separates from margin capture across Indonesia's flexible packaging tiers. Three-tier pricing structure across premium, standard, and economy levels reflects National Halal Agency certification grade and metallized film barrier performance. Cost compression in commodity polyethylene films is intensifying because naphtha-derived resin imports expose margins to regional refinery volatility. Regional snack brands exhibit highest price sensitivity; pharmaceutical and personal care segments absorb premium positioning for cleanroom-adjacent production zones.
Supply Chain Analysis
Metallization chamber supply rests on Japanese and European equipment fabricators with limited domestic alternatives. Polyethylene and polypropylene resin feedstock draws from Singapore, South Korea, and Thailand refinery outputs. Single-source vulnerability concentrates in vacuum deposition systems for barrier coating applications. Distribution runs through Java-based converter clusters serving Greater Jakarta's industrial corridor with provincial extension to Sumatra and Sulawesi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's flexible packaging market reads as a cost-of-compliance story where National Halal Agency certification mandates erect barrier-to-entry moats for converters with segregated production infrastructure. Compliant players capture pricing power as audit-qualified personnel scarcity extends qualification timelines.
For Market Incumbents: Anticipate digital printing technology displacement of gravure cylinder investments by retrofitting medium-run flexibility into existing metallized film lines. National Halal Agency auditor certification bottlenecks threaten capacity utilization during peak seasoning cycles. Prioritize backward integration into adhesive compounding to secure certified material provenance documentation. For New Entrants and Emerging Players: Launch via digital printing systems targeting 5,000-20,000 unit seasonal production lots for sauce and condiment brands in Surabaya and Bandung. Eastern Indonesia's Sulawesi and Papua corridors present whitespace for pouch converting capacity serving processed seafood exports with lower incumbent density. Partner with cold chain logistics operators to overcome dairy application barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier converters possessing halal-certified cleanroom infrastructure given National Halal Agency deadline acceleration. Long-term viability favors players with mono-material design capabilities aligned to Ministry of Environment and Forestry circular economy roadmaps. Watch provincial waste management ordinance alignment with national recycling targets as inflection signal for recyclability investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | Segregated production lines from PT Indopoly Swakarsa Industry Tbk secure National Halal Agency compliance ahead of regulatory deadlines. |
| Digital Printing Adoption | Inkjet systems with food-contact compliance enable PT ePac Flexibles Indonesia to capture seasonal SKU customization demand. |
| Mono-Material Transition | Polyethylene-only barrier structures align PT Trias Sentosa Tbk with Ministry of Environment and Forestry recyclability mandates. |
| Eastern Indonesia Expansion | Pouch converting capacity in Sulawesi addresses processed seafood export growth with localized production. |
| Healthcare Barrier Film Migration | Nylon and EVOH coextrusion capabilities serve pharmaceutical blister pack transitions from rigid trays. |
Research Methodology
Independent corroboration across converter operations data, National Halal Agency certification records, and Ministry of Environment and Forestry regulatory filings underwrites the qualitative findings. Primary interviews with blown film extrusion plant managers, procurement leads at instant noodle manufacturers, distribution channel partners, and gravure printing technical directors combined with secondary validation from customs trade data, BIS-equivalent national standards documentation, and industrial zone investment disclosures. Bottom-up capacity assessments and top-down demand triangulation anchored volume estimates.
Comparable-period anchoring tied projection trajectories to historical halal certification implementation phases and metallized film adoption curves across the analysis window. Segmentation dimensions modeled encompass product format, material specification, end-use application, printing technology, and regional production cluster. CAGRs derived from trend extrapolation of form-fill-seal automation investments and pouch format migration rates. Forecast inputs incorporated naphtha price volatility assumptions and auditor certification pipeline constraints.
The model assumes a particular technology adoption path; alternative pathways for water-based inkjet food-contact compliance would alter the outlook. Forecasts reflect assumptions regarding National Halal Agency enforcement consistency and provincial waste management infrastructure development timelines. A small set of triggers—metallization equipment localization, cold chain logistics closure in Eastern Indonesia, and mono-material recycling offtake certainty—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market