
 Intermediate Bulk Container (IBC) Market | 2026-2036
Intermediate Bulk Container (IBC) Market Size, Share, and Industry Trends Forecast 2026-2036
Intermediate Bulk Container (IBC) Market Foresight
Lightweight composite engineering is rewriting IBC design economics across industrial supply chains. Schoeller Allibert leverages its European molding footprint to dominate reusable pooling networks for chemicals and food-grade applications. Thielmann anchors premium stainless-steel IBC production for pharmaceutical and high-purity chemical clients requiring UN-certified transport vessels. Mauser Packaging Solutions sustains one of the broadest geographic service networks through its combined rigid and flexible IBC manufacturing base.
An intermediate bulk container is a standardized vessel designed for the transport and storage of liquids, powders, and granular materials, typically constructed with capacities between 500 and 3,000 liters using rotationally molded high-density polyethylene, welded stainless steel, or multilayer composite walls with galvanized steel tubular frames. Its primary industrial purpose centers on reducing packaging waste, optimizing freight cube utilization, and enabling closed-loop logistics between chemical producers, food processors, and agricultural compounders. Rigid IBCs occupy the largest value share due to their durability in multi-trip chemical service, while flexible IBCs represent the fastest-expanding category as agricultural and mineral powder shippers seek collapsible formats that minimize backhaul volume. Plastic material formulations lead unit volume but face margin compression from resin price volatility, whereas steel IBCs command premium pricing in pharmaceutical end uses where cleanability and UN dangerous-goods certification justify higher unit costs.
The EPA regulates IBC reuse and reconditioning standards under hazardous waste container requirements, while the EU F-Gas Regulation and REACH compliance frameworks shape material selection and barrier-layer specifications for chemical contact applications. FDA food-contact substance notifications govern IBC suitability for food and beverage transport, creating a segmented compliance landscape where single-certification products cannot cross between chemical and food end uses without material reformulation. Stakeholders must monitor evolving extended producer responsibility schemes and carbon-border adjustment mechanisms that will increasingly tie IBC fleet economics to lifecycle emissions accounting rather than per-trip cost alone.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing virgin resin demand while chemical manufacturers accelerate fleet reuse programs to offset rising carbon-border adjustment costs. This regulatory-compression dynamic is restructuring converter economics toward post-consumer resin formulations and closed-loop logistics infrastructure.
Growth Catalysts
- Rhine-Ruhr Chemical Corridor Density:Germany's concentrated bulk logistics infrastructure supports high IBC turnover rates and pooling network efficiency for chemical producers.
- REACH Compliance Framework:Material selection standards for chemical contact applications are standardizing barrier-layer specifications across European supply chains.
- Reusable Fleet Expansion:Chemical manufacturers are scaling pooled container programs to reduce per-trip packaging waste disposal expenditures.
Market Restraints
- Resin Price Volatility:High-density polyethylene feedstock costs fluctuate with crude oil markets, compressing margins for rotationally molded plastic IBC producers.
- Galvanized Steel Supply Concentration:Tubular frame production depends on concentrated European steel mill capacity, exposing converters to input bottlenecks.
- Cross-Contamination Risk:FDA food-contact substance notifications prevent material reformulation shortcuts between chemical and food-grade end uses.
Strategic Opportunities
- Agricultural Powder Applications:Flexible IBC formats for mineral and compound shipping remain underpenetrated in collapsible-format adoption.
- Pharmaceutical UN Certification:Stainless-steel IBC demand for high-purity chemical transport commands premium pricing through cleanability mandates.
- Extended Producer Responsibility Schemes:Lifecycle emissions accounting requirements will tie fleet economics to carbon-border adjustment mechanisms.
Industry Challenges
- Multi-Material Bonding Expertise:Composite wall engineering requires scarce rotational molding technicians capable of multilayer co-extrusion.
- Dual Certification Timelines:UN dangerous-goods and FDA food-contact approvals demand parallel testing tracks that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermediate Bulk Container (IBC) Market |
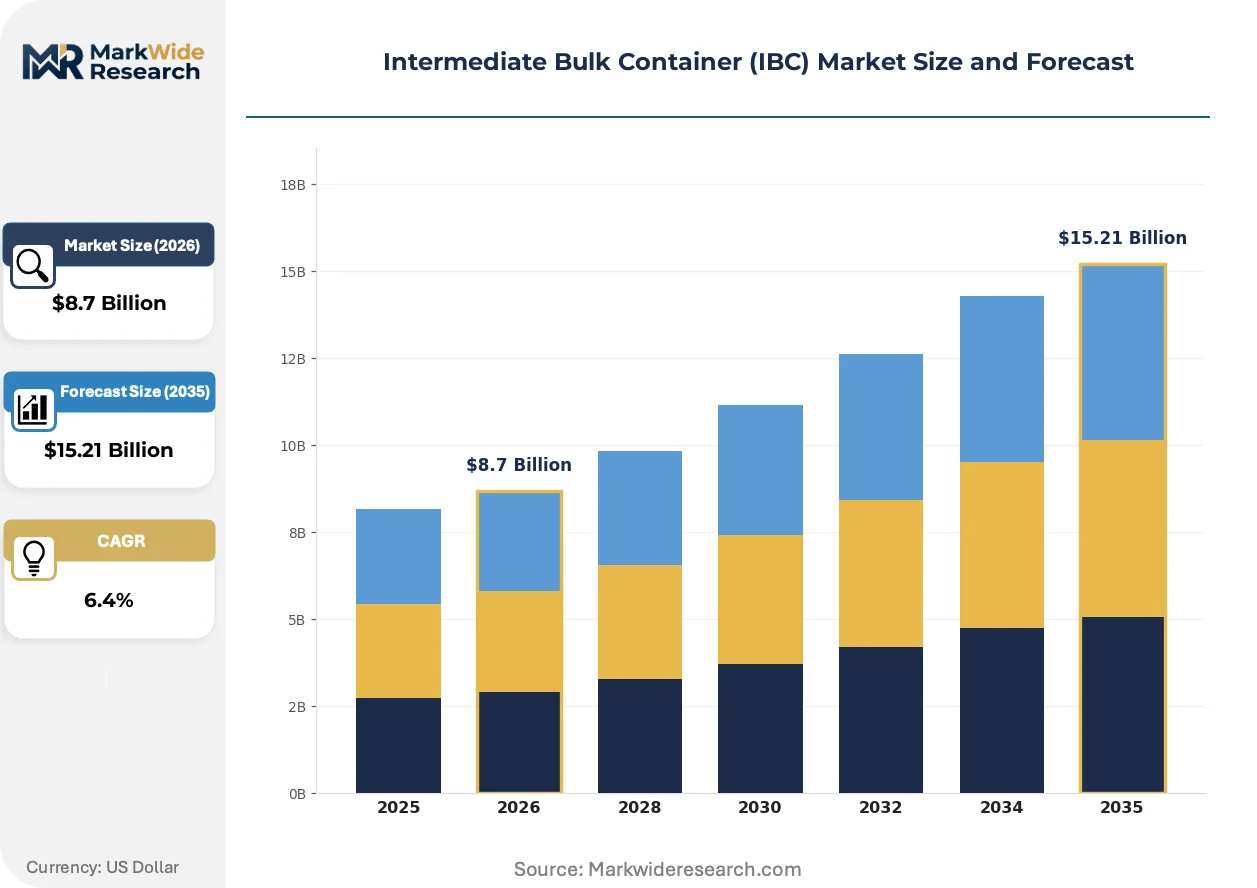
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Rigid IBC, Flexible IBC, Composite IBC, |Metal IBC Material: Plastic, Steel, Aluminum, Glass End Use: Chemicals, Pharmaceuticals, Food & Beverage, Agriculture Capacity: 500 Liters, 1000 Liters, 1500 Liters, 2000 Liters |
| Companies Covered | Snyder Industries, Schoeller Allibert, Greif Inc., Global-Pak, Bulk Lift International, Mauser Packaging Solutions, Berry Global, Thielmann, SCHÜTZ GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermediate Bulk Container (IBC) Market Shifts & Advancements
Sensor-embedded IBC fleets are transforming asset tracking from periodic inspection to continuous condition monitoring. This instrumentation shift is collapsing information asymmetries between lessors and shippers while enabling predictive maintenance protocols.
RFID-tagged composite containers are digitizing custody-chain documentation for chemical and food-grade shipments. Pharmaceutical logistics providers are deploying these tagged fleets fastest, using real-time location data to compress customs clearance timelines. The technology is digitizing compliance audit trails that previously required manual container inspection.
REACH Article 33 substance-of-very-high-concern disclosure requirements are forcing reformulation of barrier-layer adhesives in multilayer IBC walls. Chemical converters must now document full material composition downstream to downstream users. Food-grade IBC segments are responding fastest by segregating production lines to prevent cross-contact with SVHC-containing chemical formats.
Pool-operators are unbundling after-sales reconditioning services from container leases and selling them as standalone maintenance subscriptions. Chemical shippers in the Netherlands and Belgium are adopting these service contracts fastest, outsourcing UN recertification to specialized third-party wash stations. This procurement fragmentation is visible most acutely in the Antwerp-Rotterdam port corridor where high IBC velocity justifies dedicated reconditioning infrastructure.
Intermediate Bulk Container (IBC) Market Segmentation
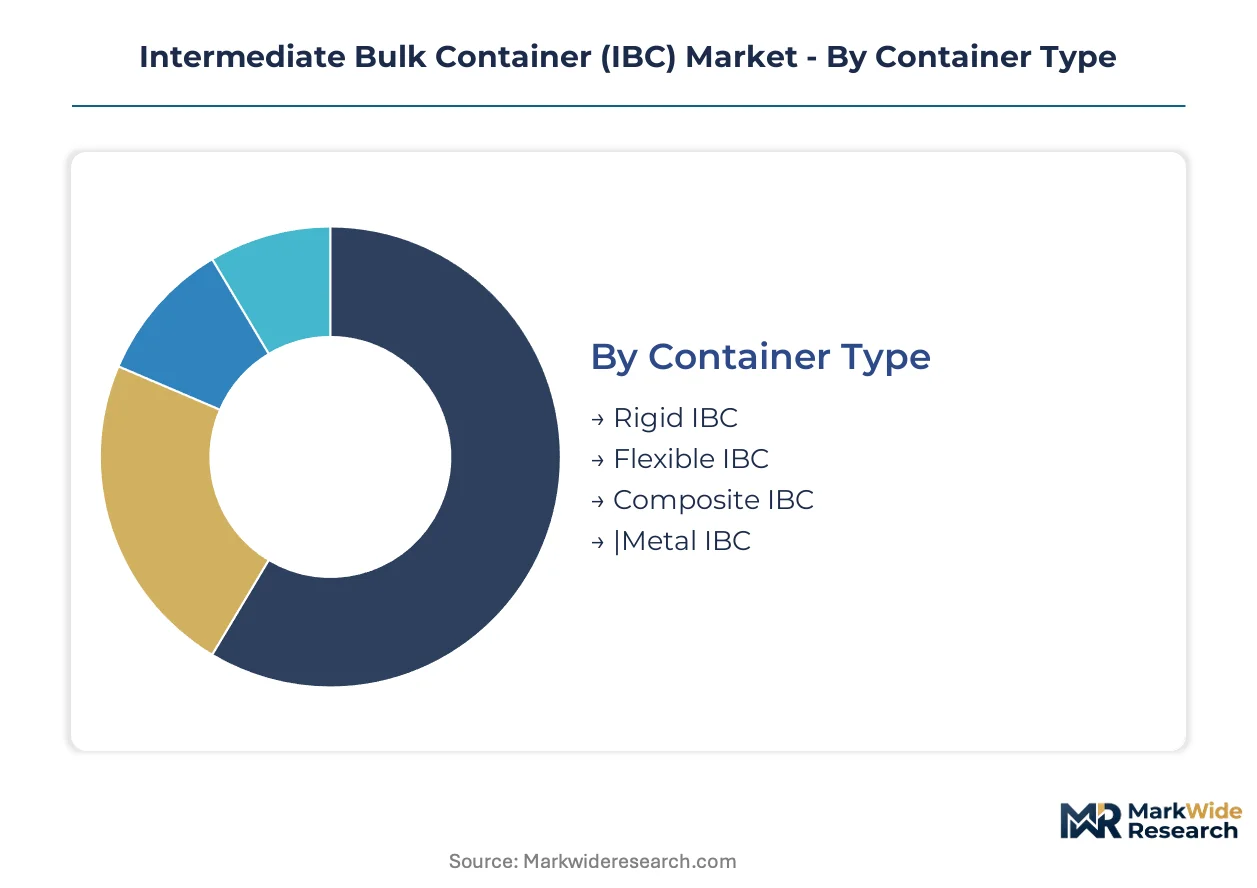
IBC segmentation reveals divergent turnover economics across container formats and material classes. Chemical producers prioritize cycle velocity in fleet procurement decisions. Pharmaceutical and food-grade applications impose slower rotation schedules due to certification complexity.
Container Type:
Rigid formats turn fastest in chemical corridors where pooling networks compress dwell times, while flexible variants minimize backhaul volume for agricultural bulk shippers.
- Rigid IBC:Rotationally molded HDPE or welded stainless-steel vessels with galvanized tubular frames dominate multi-trip chemical logistics. Rhine-Ruhr corridor density supports the highest turnover rates in European bulk transport.
- Flexible IBC:Collapsible woven polypropylene formats with polyethylene liners collapse to 20% of filled volume for return shipment. Agricultural mineral powder shippers in the Netherlands and Belgium are adopting these fastest to eliminate empty truck miles.
- Composite IBC:Multilayer co-extruded walls with barrier-layer adhesives serve REACH-compliant chemical contact applications.
- Metal IBC:UN-certified stainless-steel vessels command premium positioning in pharmaceutical high-purity transport.
Rigid IBC anchors the volume base while flexible IBC gains share at the steepest rate.
Material:
Cost tiers separate commodity resin formulations from certified alloy specifications across end-use applications.
- Plastic:HDPE rotationally molded units lead unit shipments but face margin compression from crude-linked resin volatility. Chemical producers in Germany's bulk logistics clusters specify these for closed-loop pooling programs.
- Steel:Welded 304 and 316 stainless grades dominate pharmaceutical UN dangerous-goods certification where cleanability mandates justify unit price premiums.
- Aluminum:Lightweight alloy vessels serve aerospace and specialty chemical niche applications requiring weight-constrained transport.
- Glass:Borosilicate-lined IBCs address ultra-high-purity chemical and biopharmaceutical segments with zero permeation requirements.
Plastic formulations capture the broadest unit base while steel specifications climb the fastest in value terms.
End Use:
Application-driven certification requirements fragment production lines and prevent cross-segment material reformulation shortcuts.
- Chemicals:REACH Article 33 SVHC disclosure mandates and UN dangerous-goods transport rules dominate material selection. Pooling operators in the Antwerp-Rotterdam corridor maintain dedicated reconditioning stations for this segment's high-velocity turnover.
- Pharmaceuticals:FDA food-contact substance notifications and EMA good distribution practice standards impose the slowest certification cycles. Stainless-steel UN-certified vessels serve this segment exclusively.
- Food & Beverage:FSSAI and FDA parallel compliance requirements segregate production from chemical-contact formats to prevent cross-contamination risk.
- Agriculture:Mineral and compound powder shipping drives flexible IBC adoption for seasonal demand spikes and collapsible return logistics.
Chemical end use anchors the volume base while pharmaceutical specifications gain share at the steepest rate.
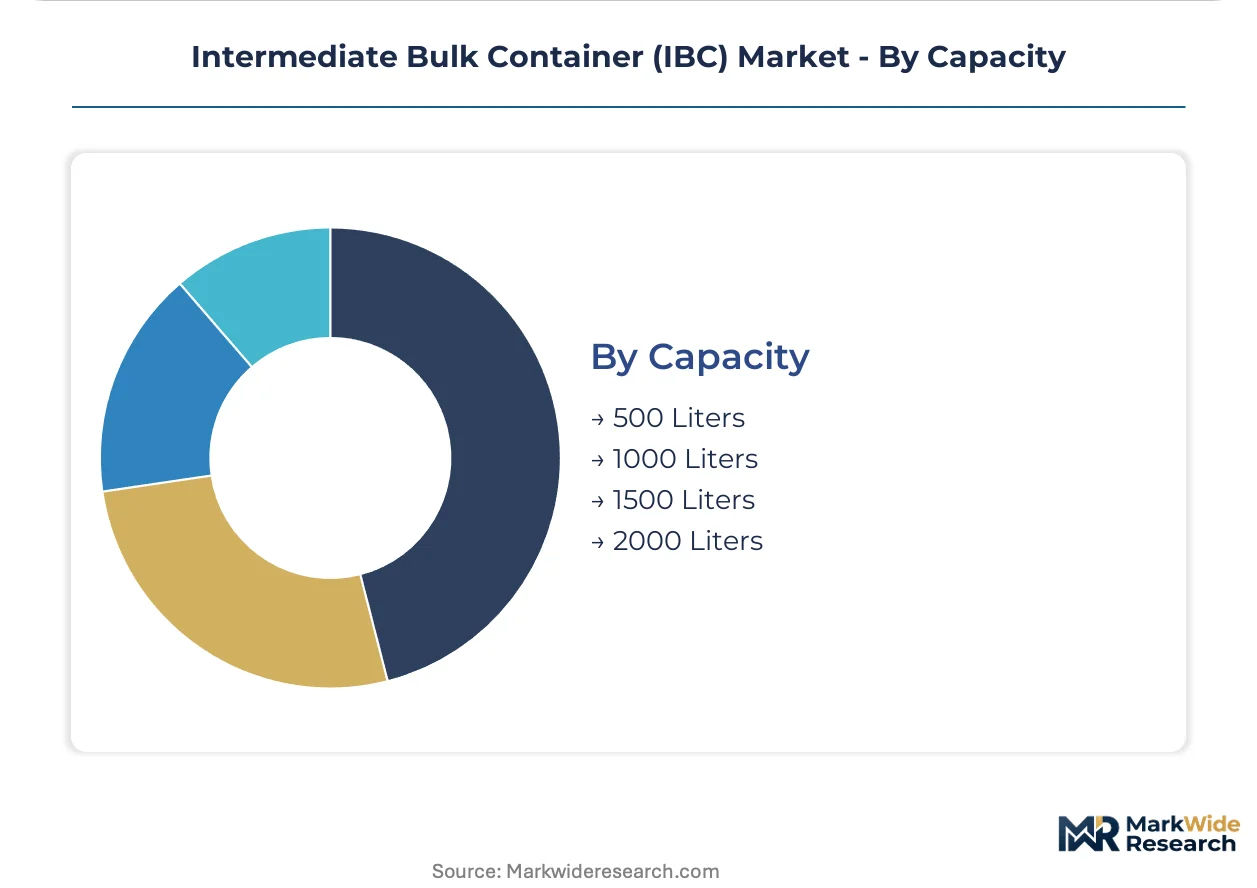
Capacity:
Volume scale determines freight cube optimization and regulatory inspection frequency across logistics networks.
- 1000 Liters:The standardized intermediate volume optimizes truck payload utilization across European chemical transport. This specification dominates pooling fleet composition in Germany and the Netherlands.
- 500 Liters:Reduced-capacity vessels serve specialty chemical and pharmaceutical batch production where smaller lot sizes prevent cross-contamination.
- 1500 Liters:Extended-volume formats address agricultural mineral compound shipping with fewer units per ton-mile.
- 2000 Liters:Maximum-capacity specifications concentrate in bulk liquid chemical transport between integrated production sites.
1000-liter specifications anchor the volume base while 500-liter formats gain share at the steepest rate in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical export surplus generates the highest IBC turnover velocity in Europe, while import-dependent economies in Asia-Pacific and North America drive contrasting fleet utilization patterns. Regional regulatory divergence around carbon-border adjustments and extended producer responsibility schemes is fragmenting procurement standards.
Germany
The Rhine-Ruhr chemical corridor sustains Europe's densest IBC pooling infrastructure, with BASF and Bayer facilities generating multi-trip container demand. REACH Article 33 SVHC disclosure mandates shape barrier-layer specifications for chemical-contact vessels. Ludwigshafen and Leverkusen production clusters anchor closed-loop logistics networks serving EU-wide chemical distribution.
United States
Gulf Coast petrochemical expansion and shale-derived feedstock abundance support rigid HDPE IBC manufacturing scale. EPA hazardous waste container regulations govern reuse and reconditioning standards for chemical transport fleets. Houston-Baytown industrial concentration drives domestic IBC demand for bulk liquid chemical export to Latin American markets.
China
Yangtze River Delta chemical parks and Pearl River Delta manufacturing clusters generate substantial flexible IBC demand for agricultural mineral powders. MIIT industrial packaging standards and dual carbon goals pressure converters toward lightweight composite formulations. Ningbo-Zhoushan port infrastructure supports high-velocity container turnover for chemical export processing.
Netherlands
Rotterdam-Antwerp port corridor density enables dedicated third-party IBC reconditioning infrastructure and UN recertification services. EU Green Deal packaging waste directives accelerate post-consumer resin adoption in rotationally molded vessels. Moerdijk chemical cluster demand concentrates pooling operator investment in automated wash station capacity.
India
Gujarat chemical manufacturing expansion and Maharashtra pharmaceutical production drive stainless-steel IBC demand for UN-certified transport. FSSAI food-contact substance notifications segregate production lines from chemical-contact formats. Dahej and Mundra port zones support import substitution in rigid IBC fabrication for domestic agrochemical distribution.
Intermediate Bulk Container (IBC) Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated pooling operators with continental service networks, specialized fabricators commanding premium certification tiers, and regional converters serving price-sensitive agricultural segments. Strategic archetypes include fleet-based lessors monetizing through trip fees, specification-driven manufacturers capturing pharmaceutical premiums, and resin-integrated molders defending margin through feedstock control. Dominant competitive moves encompass backward integration into reconditioning services and geographic expansion through pooled container network density.
Among European-based specialists, Schoeller Allibert exemplifies the integrated pooling archetype with reusable network infrastructure, while Thielmann occupies a position within premium stainless-steel certification tiers. Mauser Packaging Solutions represents the broad geographic coverage archetype spanning rigid and flexible format manufacturing. These three anchors illustrate how competitive positioning stratifies across service model, material specification, and geographic reach rather than unit cost alone.
| Leading Market Players |
|---|
| Snyder Industries |
| Schoeller Allibert |
| Greif Inc. |
| Global-Pak |
| Bulk Lift International |
| Mauser Packaging Solutions |
| Berry Global |
| Thielmann |
| SCHÜTZ GmbH |
| Others |
Supply & Pricing Matrix
Galvanized steel tube mills in Germany and Belgium concentrate frame production for rotationally molded IBCs, anchoring margin pools with converters who command premium pricing for UN-certified reconditioning services in the Antwerp-Rotterdam corridor.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade stainless-steel vessels with UN dangerous-goods certification command substantial premiums over commodity HDPE formats. Cost compression in standard-grade plastic IBCs is intensifying because resin price volatility erodes converter margins. Agricultural mineral powder shippers exhibit highest price sensitivity, while pharmaceutical logistics providers show lowest sensitivity due to cleanability mandates.
Supply Chain Analysis
Export-control restrictions on advanced rotational molding equipment limit technology transfer to emerging converter bases, preserving European supply dominance. Manufacturing concentrates in Germany, the Netherlands, and China. Production draws from high-density polyethylene resin, galvanized steel tubing, and multilayer barrier adhesives. Single-source vulnerability runs through concentrated European steel mill capacity for tubular frames. Distribution runs through pooling operator networks with dedicated reconditioning infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce multilayer co-extrusion technicians and UN recertification specialists constrain capacity expansion across European converter bases, compressing timelines for new product qualification.
For Market Incumbents: Pre-empt resin price volatility by securing long-term offtake agreements with Gulf Coast petrochemical suppliers and backward integration into captive HDPE compounding. Defend position against flexible IBC displacement by embedding sensor instrumentation into rigid fleet offerings. Prioritize certification investment for dual UN-FDA compliance to lock out cross-segment competitors. For New Entrants and Emerging Players: Build out collapsible-format manufacturing capacity targeting agricultural mineral powder shippers in the Netherlands and Belgium, where empty backhaul elimination drives procurement decisions. Agricultural applications remain the most penetrable segment due to lower certification barriers. Pursue a leasing-plus-reconditioning bundled go-to-market angle to differentiate from established pooling operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pooling operators holding dense Rhine-Ruhr network infrastructure. Long-term viability hinges on carbon-border adjustment mechanism exposure and lifecycle emissions accounting integration. Target acquisition archetypes include regional reconditioning specialists with UN recertification licenses. Monitor EU Green Deal packaging waste directive enforcement intensity as inflection signal for post-consumer resin formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply locks in margin against crude-linked volatility for rotationally molded vessels. |
| Sensor Fleet Instrumentation | Real-time condition monitoring collapses information asymmetries between Schoeller Allibert and chemical shippers. |
| Dual Certification Investment | Parallel UN dangerous-goods and FDA food-contact approval extends product addressable market across chemical and food segments. |
| Reconditioning Infrastructure Expansion | Dedicated wash station capacity in Antwerp-Rotterdam corridor captures high-velocity chemical container turnover. |
| Post-Consumer Resin Formulation | EU Green Deal compliance positions converters ahead of extended producer responsibility scheme implementation. |
Research Methodology
The analysis maps rigid HDPE, flexible woven polypropylene, composite multilayer, and stainless-steel IBC sub-sectors, each validated through plant managers at chemical producers, procurement leads at agricultural compounders, pooling operator fleet directors, and aftermarket reconditioning specialists. Primary interview insights triangulate against customs trade data, Cefic chemical industry reports, SEC 10-K filings from packaging converters, and UN dangerous-goods certification registries. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder feedback.
Assumptions held fixed include REACH Article 33 SVHC disclosure requirements and EPA hazardous waste container regulations, while resin price trajectories and carbon-border adjustment mechanism coverage varied across scenarios. Segmentation dimensions modeled encompass container format, material class, end-use industry, and geographic production hub. CAGRs derive from regression analysis against chemical production indices and agricultural output forecasts. Industry-specific inputs include pooling network turnover velocity data and UN recertification cycle frequency.
Practitioners should monitor EU extended producer responsibility scheme rollout timing and carbon-border adjustment mechanism scope expansion for early signals of demand inflection. Forecasts reflect assumptions about regulatory enforcement continuity and resin supply chain stability. Material shifts in galvanized steel trade policy or REACH substance restriction amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Intermediate Bulk Container Liner Market
Containers
Reconditioned IBC Market
Containers
Wet Wipes Canister Market
Containers
Wooden Crates Market
Containers
Rotomolded Containers Market
Containers
Wooden Barrels Market
Containers
Child-Resistant Containers Market
Containers
Slotted Containers Market
Containers
Thin Wall Plastic Containers Market
Containers
Conipack Pails Market
Containers
EPS Shippers Market
Containers
APAC Container Technology Market
Containers
Belgium Container Glass Market
Containers
Lever Lid Tinplate Containers Market
Containers
Packaging Bins Market
Containers
Vials Market