
 Polymer Dispersed Liquid Crystal (PDLC) Film Market | 2026-2036
Polymer Dispersed Liquid Crystal (PDLC) Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Dispersed Liquid Crystal (PDLC) Film Market Analytics
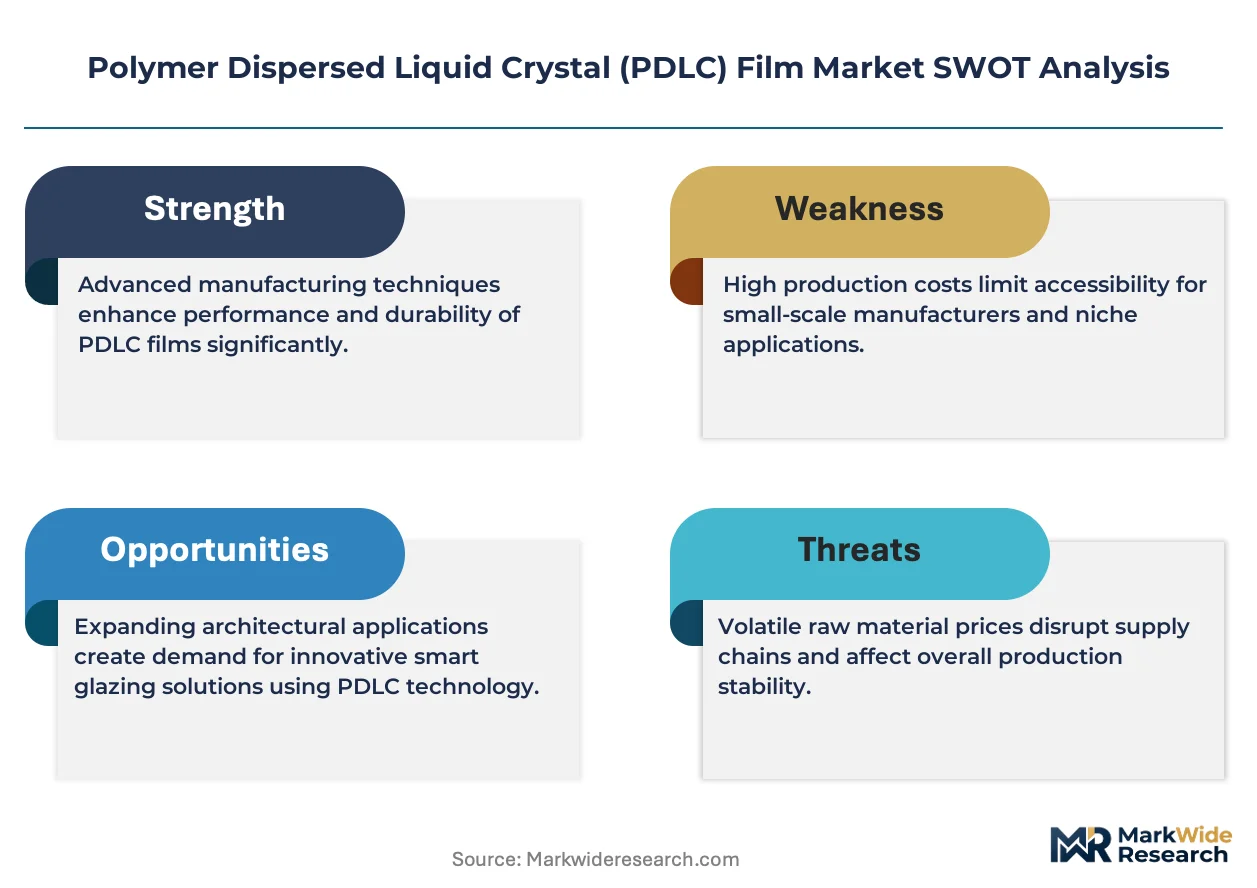
The capital-intensity divergence between roll-to-roll coating specialists and batch-process manufacturers is bifurcating competitive tiers in PDLC film supply. Polytronix, Inc. leverages captive polymer synthesis to sustain margin control across its North American operations. Gauzy Ltd anchors its position through vertical integration into liquid crystal blending, while EB Glass competes on architectural channel density across European project markets.
Polymer dispersed liquid crystal film comprises micron-sized liquid crystal droplets suspended in a polymer matrix, typically achieving optical switching below 50 volts alternating current with haze modulation between opaque and transparent states. This electro-optical architecture serves primarily as an electronically controllable privacy and light-management interface for glazing systems. Switchable films dominate current volume owing to mature building-integration protocols, while privacy films capture expanding specification in healthcare environments where infection-control sightline management matters. Decorative films represent the fastest-growing category as hospitality and retail designers adopt patterned PDLC substrates for dynamic interior branding.
FDA oversight of liquid crystal monomer biocompatibility shapes healthcare adoption pathways, while REACH restricts certain cyanobiphenyl compounds used in legacy formulations and CE marking governs electrical safety for integrated smart window systems. China's GB standards for building-integrated photovoltaics increasingly reference PDLC compatibility testing. Stakeholders must monitor regulatory convergence between electromagnetic emissions standards and material disclosure requirements as jurisdictions tighten performance certification for electrochromic glazing assemblies.
Market Dynamics
Roll-to-roll coating scale economies are concentrating PDLC film supply among capital-intensive specialists, while batch-process manufacturers retreat to niche architectural specifications. This divergence is hardening competitive tiers and reshaping procurement patterns across commercial glazing channels.
Growth Catalysts
- Smart building mandates:China's dual carbon goals accelerate BIPV-integrated PDLC installations in Shanghai and Shenzhen office towers. GB standards compatibility testing streamlines project approvals.
- REACH-driven material upgrades:ECHA restrictions on cyanobiphenyl compounds force legacy formulation retirements, opening specification windows for compliant precursors in European healthcare retrofits.
- Healthcare infection control:Sightline management protocols in US hospital ICUs specify switchable privacy films for patient observation rooms. FDA biocompatibility pathways shape vendor qualification.
Market Restraints
- Liquid crystal precursor concentration:Specialty monomer synthesis concentrates among German and Japanese chemical suppliers, exposing film coaters to input volatility and allocation risk.
- Electrical integration complexity:CE marking requirements for smart window systems extend project timelines and elevate contractor qualification thresholds in European commercial builds.
- Electrochromic substitution:Tungsten-oxide based glazing captures premium architectural projects seeking continuous tint modulation rather than binary switching.
Strategic Opportunities
- India's green building acceleration:CEA energy efficiency codes and BIS performance standards create first-mover advantages for PDLC-integrated facades in Bangalore and Hyderabad IT corridors.
- Automotive sunroof penetration:OEM specification of switchable roof panels merges SPD and PDLC technologies for passenger-controlled transparency in electric vehicle cabins.
- Direct-to-fabricator digital channels:Online specification platforms bypass traditional glazing distributor markups, enabling project-direct sales for mid-size architectural practices.
Industry Challenges
- Electro-optical engineering talent scarcity:Compound expertise in liquid crystal physics and polymer processing remains concentrated among legacy display industry veterans.
- Multi-jurisdiction certification burden:Simultaneous FDA, REACH, and GB standard compliance extends product development cycles and elevates documentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Dispersed Liquid Crystal (PDLC) Film Market |
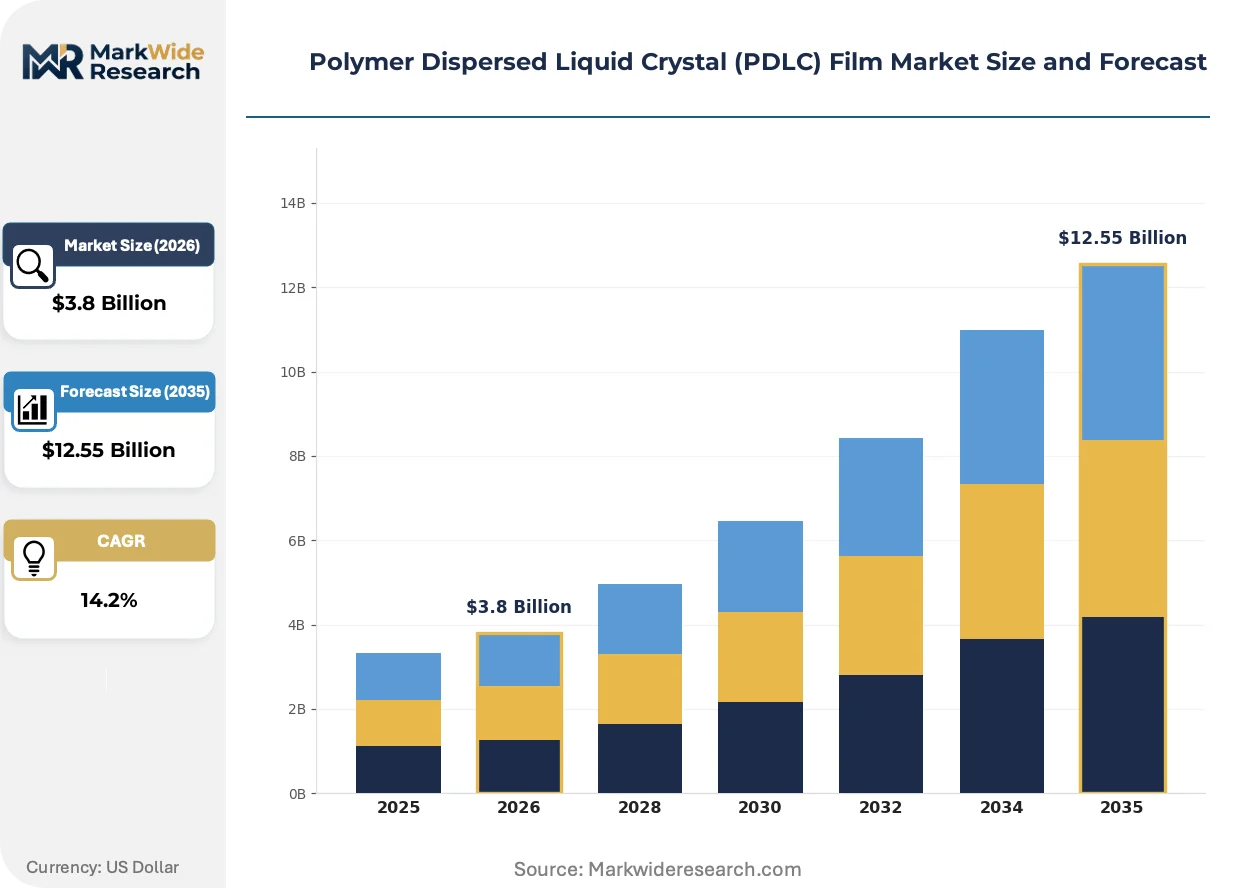
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchable Films, Privacy Films, Decorative Films, Indoor Films End Use: Architectural Applications, Automotive Interiors, Smart Windows, Retail Displays Manufacturing Stage: Raw Material Processing, Film Production, Quality Control, Distribution Application: Commercial Spaces, Residential Use, Healthcare Environments, Industrial Settings |
| Companies Covered | Polytronix, Inc., EB Glass, Gauzy Ltd, Rayno Window Film, Magic Film, Anhui Noyark Technology Co., Ltd., IRISFILM Corp., Uniteglass, DMDisplay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Dispersed Liquid Crystal (PDLC) Film Market Evolving Landscape
UV-curable polymer matrices and nano-encapsulation techniques are compressing manufacturing energy intensity while expanding optical performance envelopes. These process innovations intersect with tightening material regulations to reshape competitive positioning.
Self-adhesive PDLC laminates with dry-peel application protocols are displacing wet-installation switchable films in retrofit glazing projects. Building maintenance contractors across US commercial real estate portfolios adopt these systems to minimize tenant disruption. The shift compresses installation labor costs and accelerates payback calculations for property managers evaluating privacy upgrades.
ECHA's 2023 expansion of SVHC candidate list scrutiny targets halogenated liquid crystal intermediates, forcing reformulation investments among European film coaters. The regulatory pressure elevates compliance costs for smaller batch manufacturers. German and Dutch architectural specifiers increasingly demand full material disclosure documentation, privileging vertically integrated suppliers with captive precursor synthesis.
Architectural procurement teams now unbundle after-sales service from hardware supply, contracting directly with local integrators for electrical commissioning and warranty fulfillment. This fragmentation challenges film manufacturers accustomed to turnkey project relationships. The pattern concentrates in UK and Australian commercial office markets where facilities management outsourcing has matured.
Polymer Dispersed Liquid Crystal (PDLC) Film Market Segmentation
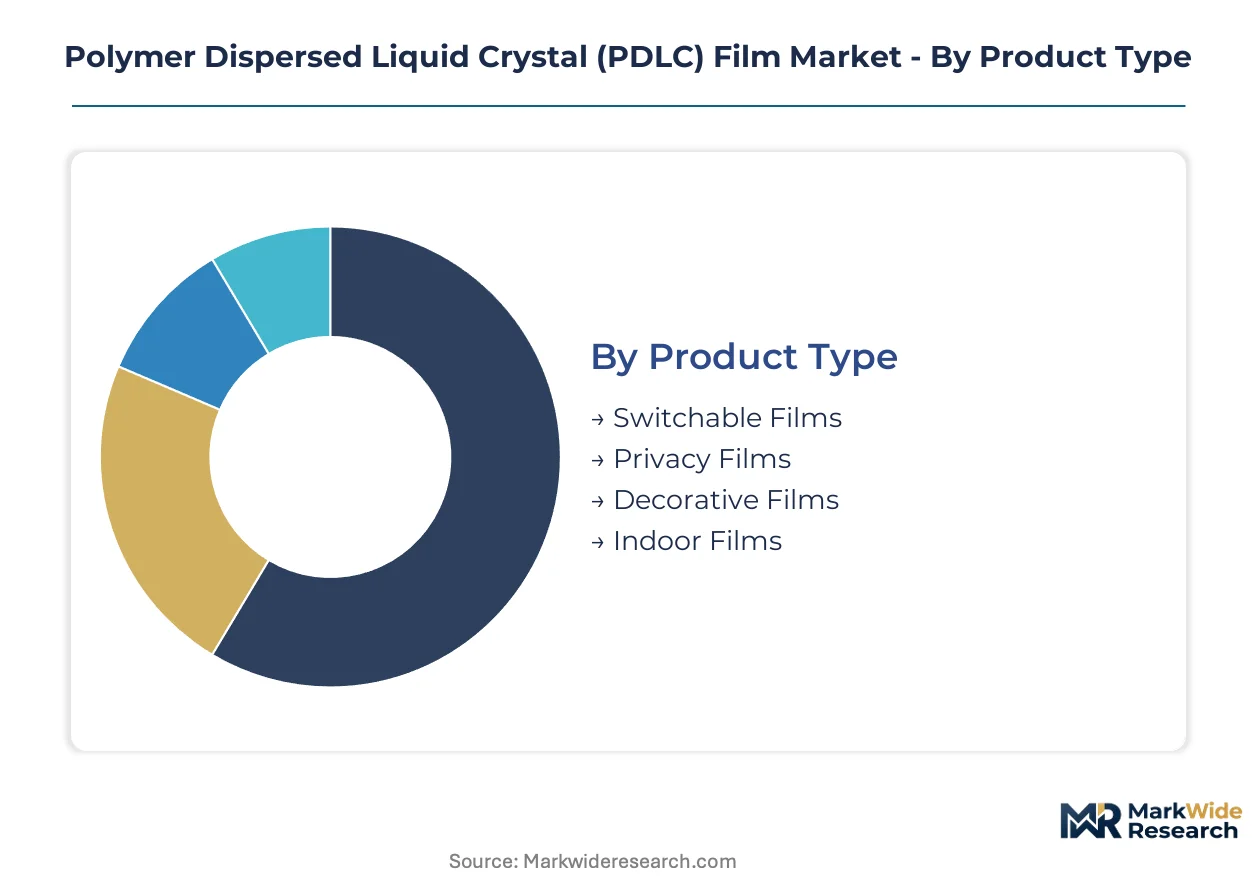
PDLC film segmentation reveals how electro-optical performance requirements diverge across installation environments and procurement workflows. Understanding these category boundaries helps suppliers align formulation investments with margin concentration points.
Product Type:
Margin pools concentrate in high-performance switchable formulations where voltage-response precision commands specification premiums.
- Switchable Films:These films modulate transparency through electrical switching, typically operating below 50 volts AC with haze control between opaque and transparent states. Demand concentrates in Shanghai and Shenzhen office towers where China's dual carbon goals accelerate BIPV-integrated smart window installations.
- Privacy Films:Binary switching architectures serve patient observation rooms in US hospital ICUs where FDA biocompatibility pathways shape vendor qualification and infection-control sightline management protocols dominate specification.
- Decorative Films:Patterned PDLC substrates enable dynamic interior branding in hospitality and retail environments.
- Indoor Films:Lower-voltage formulations target climate-controlled interior glazing with reduced weatherproofing requirements.
The dominant share belongs to Switchable Films, while Decorative Films is closing the gap fastest.
End Use:
Application-specific certification burdens fragment procurement patterns across vertical markets.
- Architectural Applications:Building-integrated glazing systems dominate volume, with European project markets requiring CE marking for electrical safety compliance and extended contractor qualification timelines.
- Automotive Interiors:OEM specification of switchable roof panels merges SPD and PDLC technologies for passenger-controlled transparency in electric vehicle cabins, with NHTSA safety standards governing optical performance in US markets.
- Smart Windows:Electronically controllable privacy and light-management interfaces for glazing systems command premium positioning.
- Retail Displays:Dynamic transparency switching enables merchandise visibility control in high-end storefront applications.
Architectural Applications holds the volume lead, though Automotive Interiors is expanding most quickly as electrification reshapes cabin design priorities.
Manufacturing Stage:
Capital intensity gradients separate competitive tiers across the value chain.
- Raw Material Processing:Specialty liquid crystal monomer synthesis concentrates among German and Japanese chemical suppliers, exposing downstream coaters to input volatility and allocation risk in cyanobiphenyl precursor markets.
- Film Production:Roll-to-roll coating scale economies concentrate supply among capital-intensive specialists, while batch-process manufacturers retreat to niche architectural specifications.
- Quality Control:Electro-optical testing protocols verify switching voltage thresholds and haze modulation consistency.
- Distribution:Direct-to-fabricator digital channels bypass traditional glazing distributor markups in mid-size architectural practices.
Film Production commands the margin concentration, with Raw Material Processing exhibiting the steepest expansion trajectory as REACH compliance tightens precursor specifications.
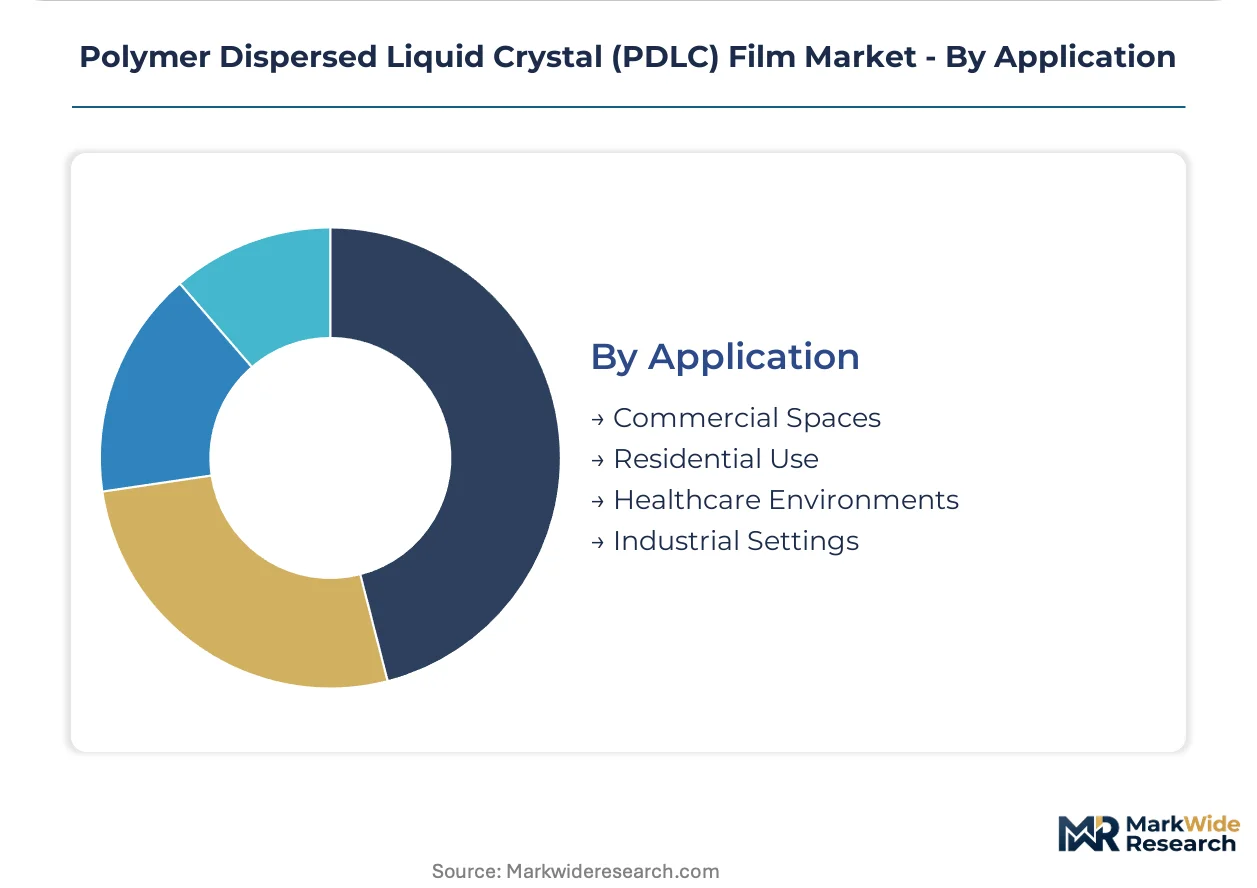
Application:
Environmental exposure requirements dictate formulation durability specifications.
- Commercial Spaces:Self-adhesive PDLC laminates with dry-peel application protocols displace wet-installation films in US commercial real estate retrofit projects, compressing installation labor costs and accelerating payback calculations.
- Residential Use:Smart home integration drives demand for low-voltage switching compatible with home automation systems.
- Healthcare Environments:FDA oversight of liquid crystal monomer biocompatibility shapes adoption pathways in patient care facilities.
- Industrial Settings:Harsh environment durability requirements elevate polymer matrix specifications for temperature and chemical resistance.
Commercial Spaces maintains the dominant position, while Healthcare Environments is gaining share fastest as infection-control protocols expand specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across PDLC film procurement channels. Healthcare and premium hospitality buyers absorb technology premiums with limited volume pushback. Mass-market commercial retrofits in secondary cities exhibit acute cost sensitivity, compressing margins for specification-grade suppliers.
United States
Hospital ICU retrofits and commercial office privacy upgrades drive specification volume. FDA biocompatibility pathways for liquid crystal monomers shape vendor qualification in patient care facilities. Self-adhesive dry-peel systems concentrate deployment across Sun Belt commercial real estate portfolios from Dallas to Phoenix.
China
Dual carbon policy mandates accelerate BIPV-integrated smart window installations in Shanghai and Shenzhen office towers. GB standards compatibility testing streamlines project approvals for facade-integrated systems. Glass construction clusters in Guangdong and Jiangsu provinces absorb the dominant share of switchable film imports.
Germany
ECHA REACH restrictions on cyanobiphenyl compounds force legacy formulation retirements across European healthcare retrofits. CE marking requirements for electrical safety extend contractor qualification timelines in Berlin and Frankfurt commercial builds. Vertically integrated chemical-film operations in the Rhine-Ruhr region capture specification premiums from compliant precursor supply.
United Kingdom
Facilities management outsourcing drives unbundling of after-sales service from hardware supply in London and Manchester office markets. Local integrators now contract directly for electrical commissioning and warranty fulfillment. This procurement fragmentation challenges manufacturers accustomed to turnkey project relationships.
India
CEA energy efficiency codes and BIS performance standards create first-mover positioning for PDLC-integrated facades in Bangalore and Hyderabad IT corridors. Green building acceleration concentrates demand in southern technology hubs. Domestic glass fabricators in Gujarat and Maharashtra pilot switchable film lamination for commercial tower projects.
Polymer Dispersed Liquid Crystal (PDLC) Film Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the PDLC film supply base. Roll-to-roll coating specialists with captive polymer synthesis command specification premiums in North American and European project markets. Batch-process manufacturers retreat to niche architectural segments with customized optical performance requirements. Three archetypes dominate: vertically integrated chemical-film operations, capital-intensive roll-to-roll coaters, and regional glazing channel specialists. Capacity expansion and strategic partnerships with glass fabricators represent the dominant competitive moves reshaping procurement relationships.
Within the vertically integrated tier, Polytronix, Inc. and Gauzy Ltd exemplify archetypes combining captive material control with project-direct specification capabilities. EB Glass occupies a position among European channel specialists leveraging architectural project density. These three anchors illustrate how competitive positioning stratifies between upstream synthesis control and downstream installation relationships.
| Leading Market Players |
|---|
| Polytronix, Inc. |
| EB Glass |
| Gauzy Ltd |
| Rayno Window Film |
| Magic Film |
| Anhui Noyark Technology Co., Ltd. |
| IRISFILM Corp. |
| Uniteglass |
| DMDisplay |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with German and Japanese chemical suppliers lock in liquid crystal precursor access and price visibility for roll-to-roll coating specialists, insulating them from cyanobiphenyl allocation volatility while batch-process competitors absorb spot-market swings. This contracting pattern concentrates margin protection among capital-intensive specialists with balance-sheet depth to commit capacity years forward.
Pricing Analysis
After-sales service revenue from electrical commissioning and warranty fulfillment drives lifetime value capture in European project markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked integrated systems from component-grade films and uncertified retrofit laminates. Cost compression in standard-tier switchable films intensifies as Chinese glass fabricators internalize lamination capabilities. Healthcare specification buyers absorb premium pricing with limited pushback, while secondary-city commercial retrofits exhibit acute cost sensitivity.
Supply Chain Analysis
Inventory cycles extending six to nine months for specialty liquid crystal monomers expose film coaters to demand-supply mismatches during project ramp phases. Production gravity centers on China for film lamination, Germany for precursor synthesis, and the United States for healthcare-grade formulation. Raw material dependencies span cyanobiphenyl compounds, UV-curable acrylate matrices, and indium-tin-oxide coated substrates. Single-source vulnerability concentrates in German and Japanese monomer suppliers. Distribution runs through architectural glazing distributors and direct-to-fabricator digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PDLC film market tracks a cyclical recovery pattern driven by green building code acceleration across Asia-Pacific commercial construction. Capital deployment timing favors positions taken ahead of regulatory enforcement windows.
For Market Incumbents: Secure captive polymer synthesis capacity to defend margin control against electrochromic substitution threats in premium architectural segments. Prioritize REACH-compliant precursor investments to capture specification windows as ECHA restrictions force legacy formulation retirements. Channel control through certified installer networks reinforces pricing power in fragmented European project markets. For New Entrants and Emerging Players: After-sales service unbundling in UK and Australian facilities management markets creates entry pathways for local electrical integrators without manufacturing scale. Target India's green building acceleration in Bangalore and Hyderabad IT corridors where first-mover positioning remains available. Direct-to-fabricator digital specification platforms offer go-to-market efficiency for mid-size architectural practices. For Investors and Strategic Acquirers: Regional glazing channel specialists with dense European project pipelines present consolidation targets as procurement fragmentation intensifies. Long-term viability hinges on backward integration into liquid crystal blending or forward integration into installation services. Watch ECHA SVHC candidate list expansions as inflection indicators for compliance-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive cyanobiphenyl supply secures margin control against REACH-driven material upgrades. |
| CE Marking Pathway Investment | Electrical safety certification accelerates contractor qualification in Berlin and Frankfurt commercial builds. |
| Direct-to-Fabricator Digital Channel Launch | Online specification platforms bypass glazing distributor markups in mid-size architectural practices. |
| Healthcare Biocompatibility Certification | FDA pathway completion unlocks ICU retrofit specification in US hospital systems. |
| Automotive Sunroof Technology Partnership | OEM collaboration merges SPD and PDLC technologies for electric vehicle cabin transparency control. |
Research Methodology
Desk research of regulatory filings from ECHA and FDA, trade flow databases, and glass industry association reports preceded structured interviews with roll-to-roll coating operations managers, architectural glazing procurement directors, liquid crystal R&D chemists, and healthcare facilities engineering heads. Primary fieldwork across Shanghai, Frankfurt, and Dallas markets validated secondary demand indicators. Bottom-up project pipeline analysis triangulated against top-down construction spend forecasts.
Variance decomposition across voltage-response precision tiers, installation protocol categories, and regional regulatory clusters shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level adoption curves and replacement cycle assumptions. Industry-specific inputs included BIPV integration rates in Chinese tier-one cities and infection-control protocol expansion timelines in US healthcare systems.
Underlying assumptions cover REACH enforcement consistency, dual carbon policy continuity, and liquid crystal precursor supply stability, with deviation risk concentrated in ECHA regulatory expansion timing and electrochromic technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Furanoate Films Market
Poly film
Poly Coated Paper Market
Poly film
High Density Polyethylene Film Market
Poly film
PP Laminating Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Global BOPP Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Global PVDC Coated Films Market
Poly film
MOPP Packaging Films Market
Poly film
India BOPP Films Market
Poly film
In-Mould Label Film Market
Poly film
Craft Plastic Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Light Reflective Film Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
PCR Bubble Films Market