
 Germany Flexible Plastic Packaging Market | 2026-2036
Germany Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Flexible Plastic Packaging Market Insights
Private-label food retailers are unwinding legacy rigid container commitments across chilled and ambient categories. Bischof+Klein SE & Co. KG leverages vertical integration in blown film extrusion to serve bakery and meat clients. Constantia Flexibles anchors its position through pharmaceutical-grade barrier film capacity. Amcor plc differentiates via global R&D spillover into recyclable flexible structures for German brand owners.
Germany flexible plastic packaging comprises polymer-based formats—typically polyethylene, polypropylene, or polyester laminates between 20 and 150 microns—manufactured through cast or blown film extrusion, printing, and lamination to deliver moisture, oxygen, and light barrier protection for perishable and industrial goods. Stand-up pouches capture margin pools in premium food and personal care segments where shelf differentiation and material efficiency outweigh format switching costs. Polyethylene dominates volume in rollstock and clear bag applications, though mono-material polypropylene grades gain ground as recycling infrastructure matures under extended producer responsibility frameworks.
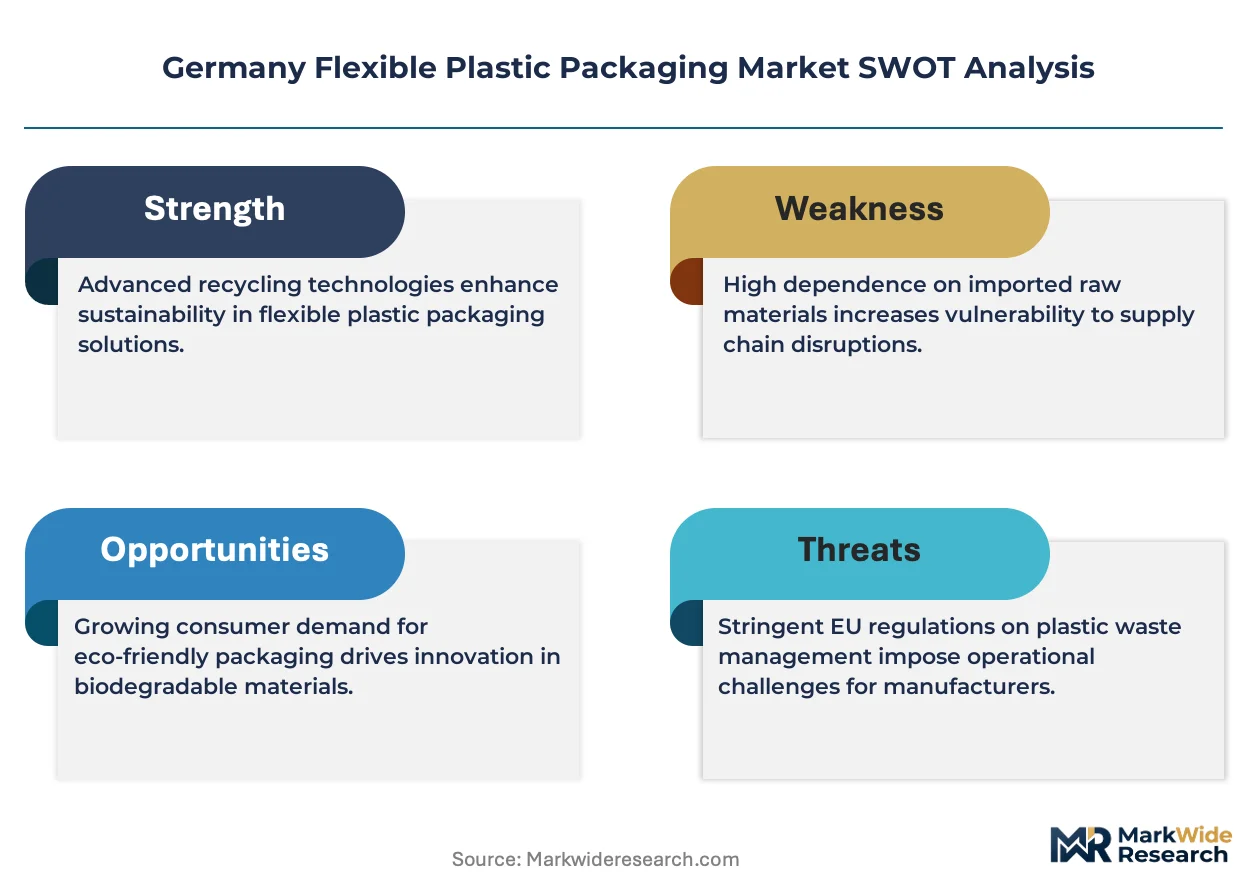
The EU Packaging and Packaging Waste Regulation (PPWR) and Germany's VerpackG packaging law enforce design-for-recycling thresholds and recycled content mandates that reshape material selection and converter investment cycles. REACH compliance on additives and the EU Green Deal's carbon border adjustments further tighten specification windows for imported films. Stakeholders must monitor enforcement timelines for recycled content minimums and assess whether domestic mechanical recycling capacity expands fast enough to offset virgin resin cost volatility.
Market Dynamics
Mono-material design transitions under Germany's VerpackG packaging law are compressing converter investment cycles and forcing rapid extrusion line reconfiguration across Baden-Württemberg and Bavaria.
Growth Catalysts
- EU PPWR recycled content mandates:Mechanical recycling infrastructure expansion in Germany creates captive supply security for converters serving export-oriented food brands.
- Stand-up pouch adoption in fresh produce:Retailers unwind rigid tray commitments as oxygen-scavenging film technologies extend shelf life for pre-cut vegetables.
- Pharmaceutical barrier film demand:Blister packaging specifications tighten for moisture-sensitive APIs, pulling high-performance coextrusion capacity from flexible food applications.
Market Restraints
- Polypropylene feedstock volatility:Naphtha-cracker margins in Rotterdam-Antwerp corridor transmit directly to German converter cost structures.
- Mechanical recycling yield gaps:Multi-layer laminate sorting infrastructure remains concentrated in Northern Italy, creating cross-border logistics exposure.
- Bioplastic performance ceilings:PLA and PHA grades fail to match polyethylene seal integrity at high-speed form-fill-seal lines above 200 units per minute.
Strategic Opportunities
- Chemically recycled content quotas:Pyrolysis partnerships with petrochemical complexes in Ludwigshafen offer compliance pathways ahead of 2030 VerpackG thresholds.
- E-commerce pouch formats:Durable lightweight mailers displace corrugated boxes in Berlin-Brandenburg fulfillment networks.
- Digital watermark integration:HolyGrail 2.0 sorting markers enable post-consumer film traceability for closed-loop brand commitments.
Industry Challenges
- Extrusion technician scarcity:Blown film line operators with multi-layer die experience command 40% wage premiums in Stuttgart industrial corridor.
- Extended producer responsibility fee volatility:VerpackG license cost recalculation every 18 months complicates five-year contract pricing with FMCG clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Flexible Plastic Packaging Market |
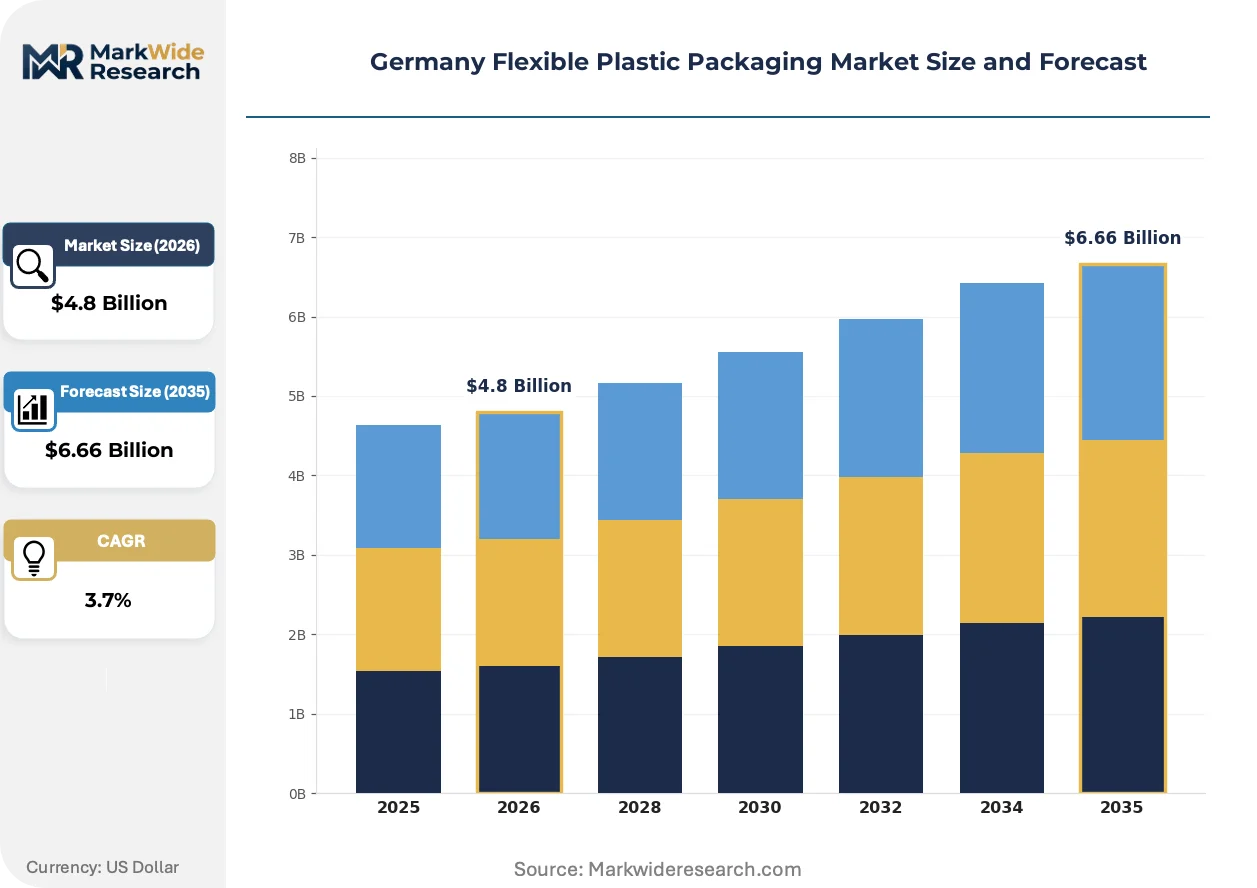
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Shrink Films, Layflat Tubing, Clear Bags Material: Polyethylene, Polypropylene, Polyester, Nylon End Use Industry: Food & Beverages, Healthcare, Personal Care, Household Packaging Type: Flexible Bags, Pouches, Rollstock, Blisters |
| Companies Covered | Bischof+Klein SE & Co. KG, Constantia Flexibles, Amcor plc, Mondi plc, Empac GmbH, Coveris, Berry Global Group Inc, SÜDPACK, Dsmart GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Flexible Plastic Packaging Market Trends and Innovations
Digital printing and mono-material barrier engineering are collapsing traditional format-moisture specifications, enabling mass customization while satisfying mechanical recycling purity thresholds.
High-barrier ethylene vinyl alcohol copolymer replacement is bifurcating between metallized biaxially oriented polypropylene for premium shelf appeal and silicon oxide-coated polyethylene for microwaveable applications. Bakery and ready-meal processors in North Rhine-Westphalia are piloting both grades at 10,000-unit test volumes. The technology is bifurcating converter R&D budgets away from conventional lamination toward direct barrier deposition.
Germany's VerpackG amendment tightens design-for-recycling criteria effective January 2025, requiring mono-material share above 90% by weight for household collection eligibility. Converters must requalify legacy adhesive formulations and ink systems. Pharmaceutical blister lines face 18-month recertification timelines with the national packaging regulator.
Brand-owner sustainability scorecards now weight packaging circularity at 25% of supplier evaluation, displacing unit cost as the primary award criterion. Discounters Aldi and Lidl are consolidating flexible film purchasing through central sustainability desks in Essen and Neckarsulm. Bavarian dairy cooperatives report 30% faster supplier switching as annual tender cycles compress to quarterly reviews.
Germany Flexible Plastic Packaging Market Segmentation
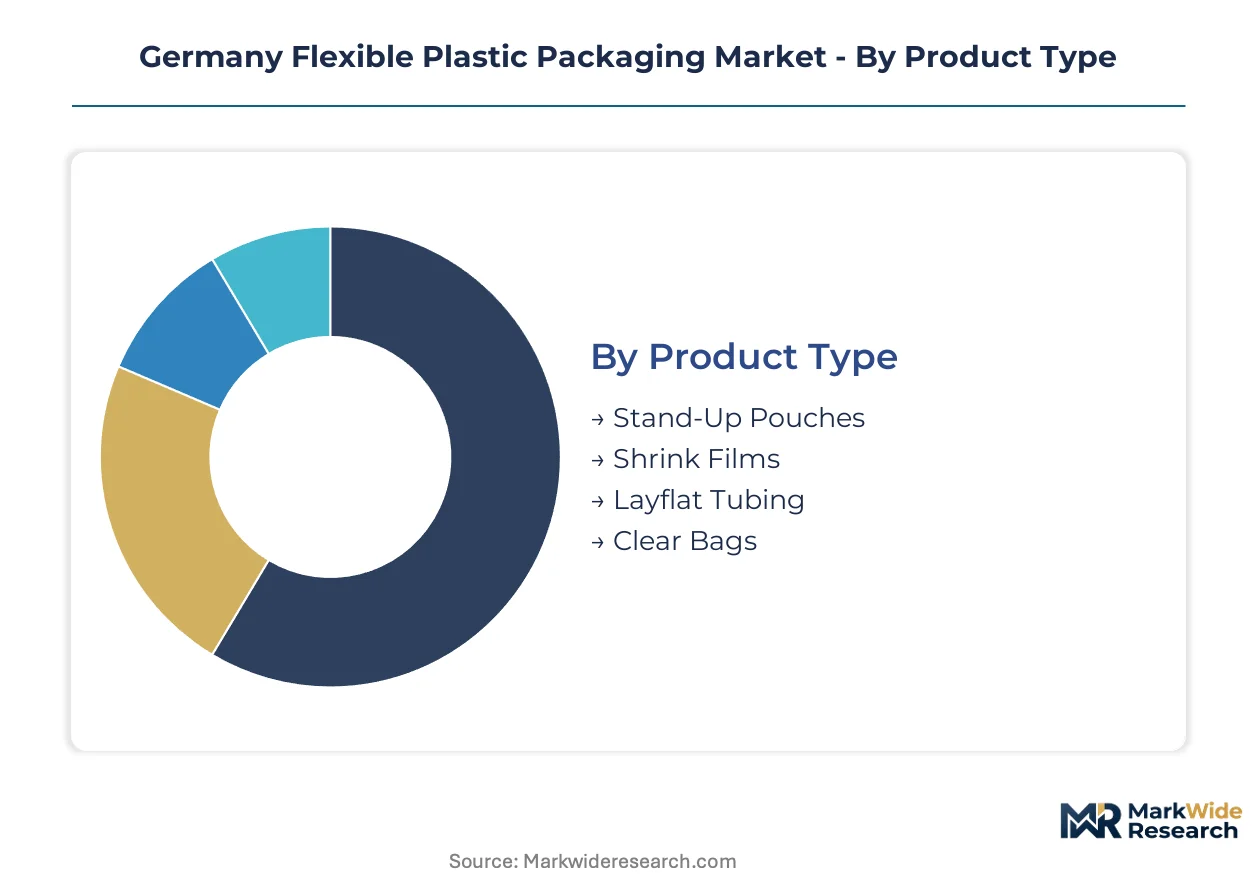
Converters in Baden-Württemberg and Bavaria configure extrusion lines around specific format-material pairings to capture margin pools in export-oriented food brands and pharmaceutical-grade barrier specifications. Segment selection determines compliance pathways under VerpackG recycling thresholds and EPR fee structures.
Product Type:
Margin pools concentrate in formats that displace rigid containers while satisfying high-speed form-fill-seal throughput requirements.
- Stand-Up Pouches:Multi-layer laminates with resealable zipper profiles command premium positioning in ready-to-eat meals and fresh produce. Baden-Württemberg converters serve Aldi and Lidl central purchasing desks with oxygen-scavenging variants that extend shelf life for pre-cut vegetables.
- Shrink Films:Biaxially oriented polypropylene grades dominate beverage multipacks and industrial bundling. Bavarian meat processors are unwinding corrugated tray commitments as collation speeds exceed 400 units per minute on modern flow wrappers.
- Layflat Tubing:Continuous seamless extrusion serves high-volume bakery and frozen vegetable applications with customized width specifications.
- Clear Bags:Single-ply polyethylene formats capture commodity produce and industrial liner demand through rollstock efficiency.
The dominant share belongs to Stand-Up Pouches, while Shrink Films is closing the gap fastest.
Material:
Cost tiers stratify around feedstock volatility exposure and mechanical recycling compatibility under EU PPWR mandates.
- Polyethylene:Low-density and linear low-density grades dominate volume in clear bags and stretch film. North Rhine-Westphalia converters leverage Rotterdam-Antwerp naphtha supply corridors for cost-competitive rollstock serving discount retail.
- Polypropylene:Cast and biaxially oriented variants gain share in mono-material pouch specifications. Mechanical recycling infrastructure in Southern Germany creates captive supply security for export-oriented food brands facing VerpackG content thresholds.
- Polyester:Metallized and silicon oxide-coated grades serve high-barrier pharmaceutical blister and microwaveable ready-meal segments.
- Nylon:Coextruded barrier layers target vacuum-packaged meat and cheese applications requiring puncture resistance.
Polyethylene holds the volume base, though Polypropylene is expanding most quickly as design-for-recycling criteria tighten.
End Use Industry:
Application requirements dictate barrier specification intensity and regulatory compliance burden.
- Food & Beverages:Oxygen and moisture barrier laminates for bakery, meat, dairy, and fresh produce. Retailers in Essen and Neckarsulm consolidate purchasing through sustainability scorecards weighting circularity at 25% of supplier evaluation.
- Healthcare:Moisture-sensitive API blister packaging pulls high-performance coextrusion capacity from flexible food applications. Pharmaceutical-grade specifications require 18-month recertification timelines with national packaging regulators.
- Personal Care:Stand-up pouch formats for premium shampoo and lotion segments where shelf differentiation outweighs format switching costs.
- Household:Durable lightweight mailers displace corrugated boxes in Berlin-Brandenburg e-commerce fulfillment networks.
Food & Beverages commands the installed base, while Healthcare is climbing the fastest on barrier film demand.
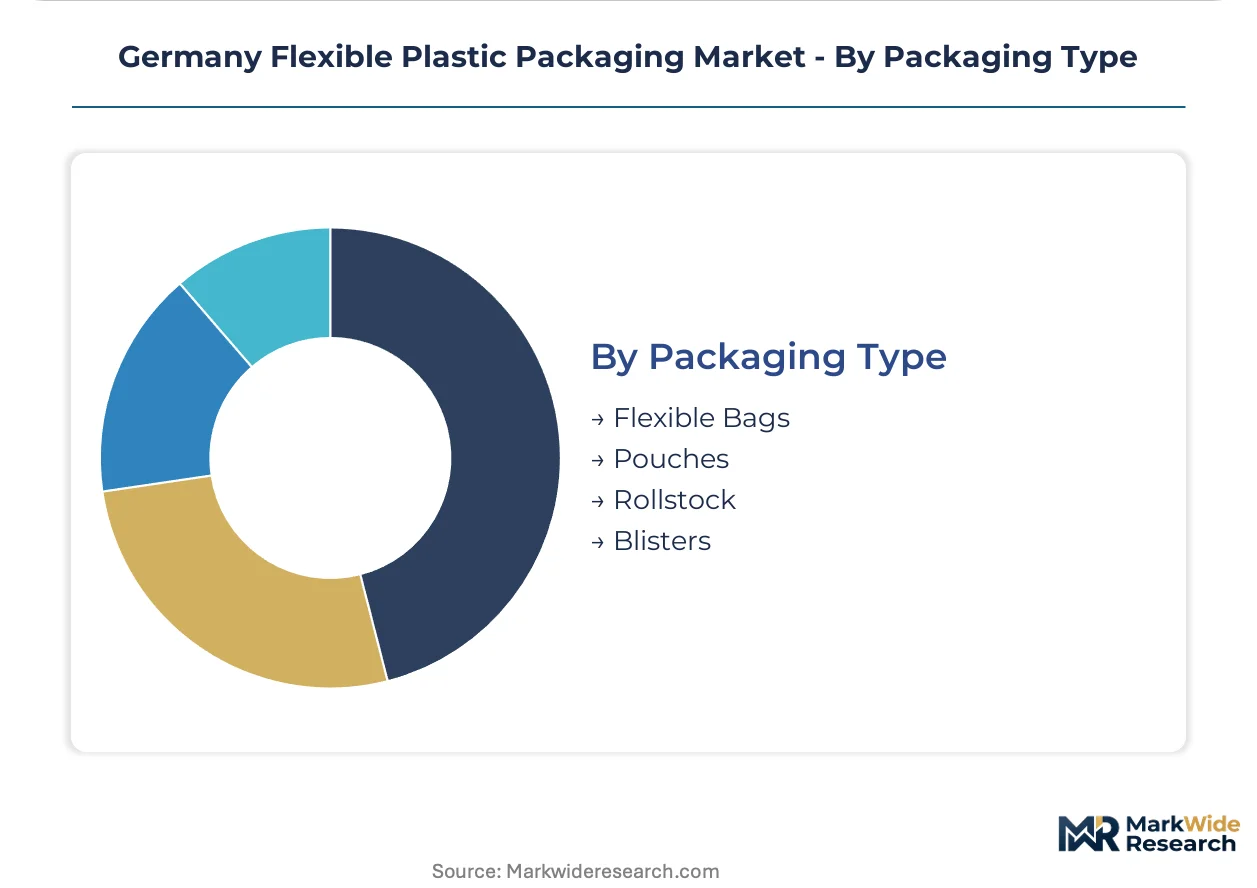
Packaging Type:
Customer type separates brand owners seeking shelf differentiation from industrial buyers prioritizing throughput economics.
- Flexible Bags:Wicketed and loose-fill formats for bakery, produce, and frozen applications. High-speed lines above 200 units per minute reject bioplastic alternatives failing polyethylene seal integrity.
- Pouches:Pre-made and form-fill-seal variants capture premium food and personal care margin pools. Digital printing enables mass customization while satisfying mechanical recycling purity thresholds.
- Rollstock:Continuous web supply for in-house forming operations at meat and dairy processors. Bavarian cooperatives report 30% faster supplier switching as tender cycles compress to quarterly reviews.
- Blisters:Thermoformed pharmaceutical specifications with aluminum lidding or high-barrier film alternatives.
Rollstock maintains the volume edge, while Pouches is gaining share fastest on retail format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway network connects Bavarian converter clusters to Rotterdam-Antwerp chemical corridors, anchoring Germany's flexible packaging distribution topology. This inland freight infrastructure underwrites raw material access for extrusion operations across Southern Germany's industrial belt.
Baden-Württemberg
Stuttgart's automotive supplier ecosystem spills over into precision film extrusion for high-barrier food applications. VerpackG enforcement timelines from Germany's national packaging regulator compress converter recertification cycles to 18-month windows. The Neckar Valley corridor hosts blown film specialists serving Aldi and Lidl central purchasing desks with oxygen-scavenging pouch formats.
Bavaria
Munich's pharmaceutical packaging demand pulls coextrusion capacity from flexible food segments toward moisture-sensitive API blister specifications. REACH compliance on additives tightens specification windows for imported barrier films. The Ingolstadt industrial zone anchors meat processor clusters unwinding rigid tray commitments in favor of shrink film collation systems.
North Rhine-Westphalia
Düsseldorf's chemicals headquarters proximity enables direct naphtha feedstock contracting with Rotterdam-Antwerp crackers for polyethylene rollstock production. The EU Green Deal's carbon border adjustments elevate landed costs for Asian film imports. Cologne-Bonn logistics hubs distribute wicketed bags to discount retail consolidation centers.
Berlin-Brandenburg
E-commerce fulfillment networks in the capital region drive demand for durable lightweight mailers displacing corrugated secondary packaging. Germany's VerpackG packaging law mandates mono-material share above 90% for household collection eligibility. Spreewald converter operations pilot digital watermark integration for HolyGrail 2.0 sorting traceability.
Lower Saxony
Hanover's machinery manufacturing base supplies high-speed form-fill-seal lines rejecting bioplastic alternatives below 200 units per minute throughput. Extended producer responsibility fee recalculation every 18 months complicates FMCG contract pricing. The Wolfsburg automotive corridor feeds industrial liner demand for just-in-time component supply chains.
Germany Flexible Plastic Packaging Market Competitive Landscape
Concentration sits with integrated film extruders and multinational converters with captive R&D infrastructure. The vendor base stratifies across three tiers: global packaging conglomerates with German manufacturing footprints, mid-cap specialists with backward integration into blown film production, and regional converters serving private-label retailers. M&A activity targets mono-material barrier technology assets, while capacity expansion concentrates in pharmaceutical-grade coextrusion lines.
Among Germany-based integrated producers, Bischof+Klein SE & Co. KG and SÜDPACK exemplify the mid-cap specialist archetype with captive extrusion capabilities. Amcor plc and Constantia Flexibles represent multinational converters leveraging global R&D spillover into recyclable flexible structures. These four entities anchor the competitive topology, with the German GmbH and KG structures signaling family-owned or limited partnership governance distinct from the Anglo-American plc format.
| Leading Market Players |
|---|
| Bischof+Klein SE & Co. KG |
| Constantia Flexibles |
| Amcor plc |
| Mondi plc |
| Empac GmbH |
| Coveris |
| Berry Global Group Inc |
| SÜDPACK |
| Dsmart GmbH |
| Others |
Pricing and Supply Chain Analysis
Germany's VerpackG packaging law gates supply qualification and price differentiation simultaneously, as converters must achieve mono-material share above 90% by weight to access household collection eligibility and secure favorable extended producer responsibility fee tiers. Buyers in discount retail channels demand certified recyclable formats while premium export-oriented brands absorb cost premiums for pharmaceutical-grade barrier specifications.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels, with pharmaceutical-grade coextrusion commanding the highest tier and commodity polyethylene rollstock anchoring the base. Price differentiation rests on certification grade under VerpackG thresholds and volume scale in annual versus quarterly tender cycles. Cost compression in standard-tier food packaging is intensifying because Baden-Württemberg converter clusters compete for Aldi and Lidl central purchasing desk contracts. Discount retailers exhibit the sharpest price sensitivity, while pharmaceutical brand owners prioritize barrier performance over unit economics.
Supply Chain Analysis
Belgium and the Netherlands anchor naphtha feedstock supply through the Rotterdam-Antwerp chemical corridor, while Italy concentrates multi-layer laminate sorting infrastructure. Raw material flows draw from Rotterdam-Antwerp crackers for polyethylene, Ludwigshafen petrochemical complexes for polypropylene, and Southern German mechanical recycling facilities for post-consumer content. Single-source vulnerability runs through cross-border logistics exposure to Italian sorting infrastructure. Distribution feeds from Rhine-Main-Danube waterway networks into Bavarian meat processor clusters and North Rhine-Westphalia retail consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's flexible plastic packaging market represents an early-cycle expansion story, as VerpackG enforcement timelines accelerate mono-material design transitions ahead of mechanical recycling infrastructure maturation.
For Market Incumbents: Compound barrier technology leadership through captive R&D spillover into recyclable flexible structures, defending against emerging chemical recycling entrants. Prioritize backward integration into blown film extrusion to secure supply security for pharmaceutical-grade specifications. Lock in five-year offtake agreements with FMCG clients before VerpackG license cost recalculation cycles disrupt contract pricing.
For New Entrants and Emerging Players: Lead with digital watermark integration for HolyGrail 2.0 sorting traceability, targeting Berlin-Brandenburg e-commerce fulfillment networks where durable lightweight mailers displace corrugated secondary packaging. The most penetrable white-space sits in quarterly tender cycles for Bavarian dairy cooperatives reporting accelerated supplier switching. Pursue pyrolysis partnerships with Ludwigshafen petrochemical complexes as a compliance-first go-to-market angle.
For Investors and Strategic Acquirers: VerpackG recycled content mandates reshape the acquisition landscape toward mono-material barrier technology assets with captive extrusion capabilities. Long-term viability over a multi-year horizon hinges on converters' ability to serve both food and pharmaceutical segments through shared coextrusion infrastructure. Watch for mechanical recycling yield gaps in multi-layer laminate sorting as the critical inflection signal for cross-border logistics exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Engineering | VerpackG compliance thresholds force 18-month recertification cycles for adhesive and ink systems. |
| Chemical Recycling Partnership | Pyrolysis alliances with Ludwigshafen complexes secure feedstock ahead of content mandates. |
| Digital Watermark Integration | HolyGrail 2.0 markers enable closed-loop traceability for Aldi and Lidl sustainability scorecards. |
| Pharmaceutical Coextrusion Capacity | Moisture-sensitive API blister demand pulls capacity from flexible food applications. |
| Extrusion Technician Training Programs | Blown film operators with multi-layer die experience command 40% wage premiums in Stuttgart corridor. |
Research Methodology
Operator-level perspectives from extrusion line managers, procurement leads at meat and dairy processors, sustainability directors at discount retailers, and regulatory affairs specialists at national packaging authorities anchored the qualitative base. Secondary validation drew from German Environment Agency circular economy reports, EU PPWR implementation timelines, VerpackG fee structure documentation, and mechanical recycling infrastructure databases. Bottom-up volume estimates triangulated with top-down market sizing across converter capacity utilization rates.
Sensitivity analysis tested forecast outputs against variable adoption rates for mono-material pouch formats and mechanical recycling yield assumptions. Segmentation dimensions modeled include product type, material grade tier, end-use industry, and regional production cluster across the projection horizon. CAGRs derived from historical growth pattern analysis and policy-driven inflection point assessment, with feedstock volatility in Rotterdam-Antwerp naphtha corridors and pharmaceutical barrier film demand intensity as key industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside VerpackG enforcement timelines or EU PPWR recycled content mandate trajectories would require recalibration. Forecasts reflect documented assumptions regarding mechanical recycling infrastructure expansion rates and chemical recycling commercialization pathways. Recalibration cycles align with material shifts in extended producer responsibility fee structures and national packaging regulator enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Mexico Flexible Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market