
 Canada Multilayer Flexible Packaging Market | 2026-2036
Canada Multilayer Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Multilayer Flexible Packaging Market Intelligence
Canadian film extrusion capacity is expanding across the Ontario-Quebec corridor to serve protein and dairy packaging demand. Amcor plc leverages its integrated film and converting footprint to supply major Canadian food processors with high-barrier structures. Winpak Ltd. anchors its competitive position through captive resin compounding and specialized thermoforming operations in Manitoba and Quebec. Transcontinental Inc. competes via its flexible packaging division's focus on sustainable material transitions and regional brand partnerships.
Multilayer flexible packaging consists of laminated polymer films, aluminum foil, and adhesive layers engineered to provide oxygen, moisture, and light barrier protection in a single collapsible structure, typically produced through coextrusion or adhesive lamination processes. Stand-up pouches and roll stock dominate volume flows into Canadian food manufacturing, where retort-capable and high-barrier specifications command premium positioning. Polyethylene and barrier film combinations are gaining formulation share as packagers balance seal integrity against recyclability targets under evolving provincial extended producer responsibility frameworks.
Health Canada sets food-contact compliance standards that directly shape resin selection and adhesive chemistry across Canadian converting operations. Environment and Climate Change Canada administers the Chemicals Management Plan, which restricts certain perfluorinated substances formerly used in grease-resistant barrier coatings. Provincial extended producer responsibility regulations in British Columbia, Ontario, and Quebec are forcing converters to redesign multilayer structures for mechanical recycling compatibility or certified compostability. Stakeholders must monitor regulatory divergence between provinces while building flexible extrusion platforms capable of rapid material transitions.
Market Dynamics
Health Canada's evolving food-contact material regulations and provincial extended producer responsibility frameworks are forcing converters to redesign multilayer structures for mechanical recycling compatibility, compressing formulation flexibility and reshaping competitive positioning across the Ontario-Quebec corridor.
Growth Catalysts
- Provincial EPR mandates:British Columbia, Ontario, and Quebec extended producer responsibility regulations accelerate demand for redesign services and certified compostable alternatives.
- Protein processing concentration:Major beef, pork, and poultry clusters in Ontario and Quebec require high-barrier retort-capable packaging for export-grade shelf-life extension.
- Barrier film innovation:Polyethylene and ethylene vinyl alcohol coextrusions are displacing aluminum foil in select applications while maintaining oxygen transmission rate performance.
Market Restraints
- Resin supply concentration:Polyethylene and polypropylene feedstock dependence on US Gulf Coast petrochemical complexes exposes converters to cross-border logistics friction and currency volatility.
- Perfluorinated substance restrictions:Environment and Climate Change Canada's Chemicals Management Plan eliminates grease-resistant barrier coatings, forcing adhesive and coating reformulation with uncertain performance windows.
- Mechanical recycling incompatibility:Legacy multilayer structures combining polyethylene, nylon, and aluminum foil lack viable mechanical recycling pathways under current provincial facility capabilities.
Strategic Opportunities
- Manitoba dairy expansion:Specialized thermoforming operations serving ice cream and cheese processors face limited regional competition and rising export demand to US Midwest markets.
- Store drop-off collection infrastructure:How2Recycle label adoption creates channel differentiation for converters delivering polyethylene-only structures compatible with existing retail collection programs.
- Digital printing convergence:Flexographic and inkjet hybrid systems enable short-run customization for regional brand partnerships without plate changeover costs.
Industry Challenges
- Adhesive chemistry expertise gap:Solvent-free and water-based lamination systems require retraining of press operators accustomed to solvent-based processes, extending commissioning timelines.
- Compostability certification delays:BPI and TUV Austria industrial compostable verification timelines stretch 12-18 months, blocking market entry for reformulated structures.
- Legacy equipment retrofit costs:Coextrusion lines engineered for conventional barrier constructions demand substantial capital outlay to process bio-based or chemically recycled feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Multilayer Flexible Packaging Market |
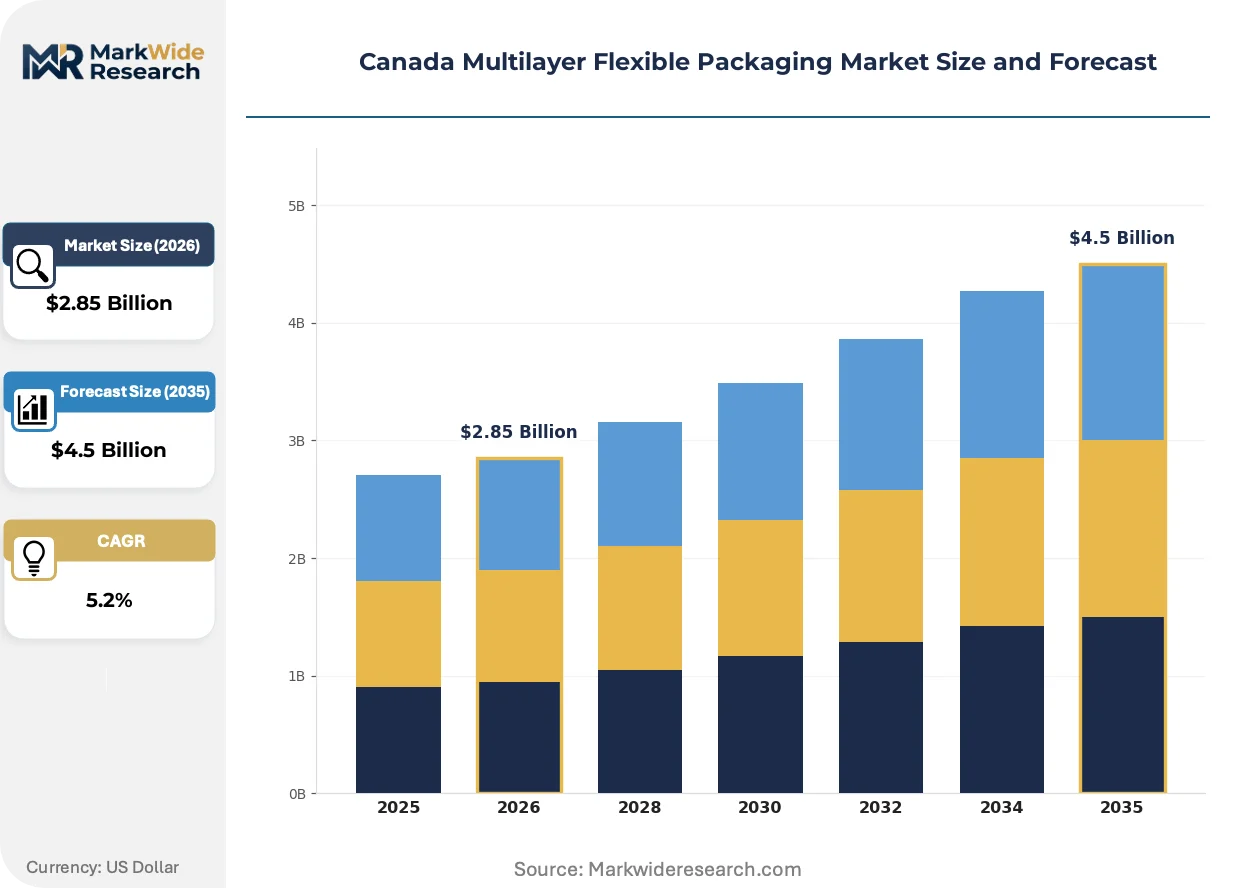
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.5 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Lay-Flat Pouches, Roll Stock, Bags Material: Polyethylene, Polypropylene, Barrier Films, Aluminum Foil Application: Food, Beverage, Personal Care, Pharmaceutical Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Amcor plc, Winpak Ltd., Transcontinental Inc., Berry Global Inc., Sonoco Products Company, Sealed Air, Mondi Group, Glenroy Inc., Westrock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Multilayer Flexible Packaging Market Strategic Shifts & Innovations
Digitalization of converting operations and material traceability systems is compressing lead times while regulatory pressure on perfluorinated substances accelerates adhesive chemistry substitution across the Canadian flexible packaging value chain.
Mono-material polyethylene structures are integrating high-barrier coatings and sealant layers to achieve oxygen and moisture protection previously requiring aluminum foil or nylon interlayers. Major dairy and protein processors in Quebec are piloting these structures for frozen and refrigerated applications. This convergence is integrating mechanical recyclability into performance specifications that previously prioritized barrier metrics alone.
Health Canada's updated food-contact notification requirements for new adhesive chemistries are extending regulatory review timelines from 90 to 180 days for novel barrier coatings. Converters are pre-submission testing to avoid production delays. Small and mid-size Ontario converters without dedicated regulatory affairs staff are outsourcing compliance documentation to specialized consultancies.
Brand procurement teams are consolidating flexible packaging suppliers to reduce audit burdens and secure volume commitments for sustainability reporting. This concentration is displacing fragmented regional converter relationships that dominated the 2015-2020 period. Major Canadian grocery retailers are driving this consolidation through preferred supplier programs tied to EPR compliance verification.
Canada Multilayer Flexible Packaging Market Segmentation
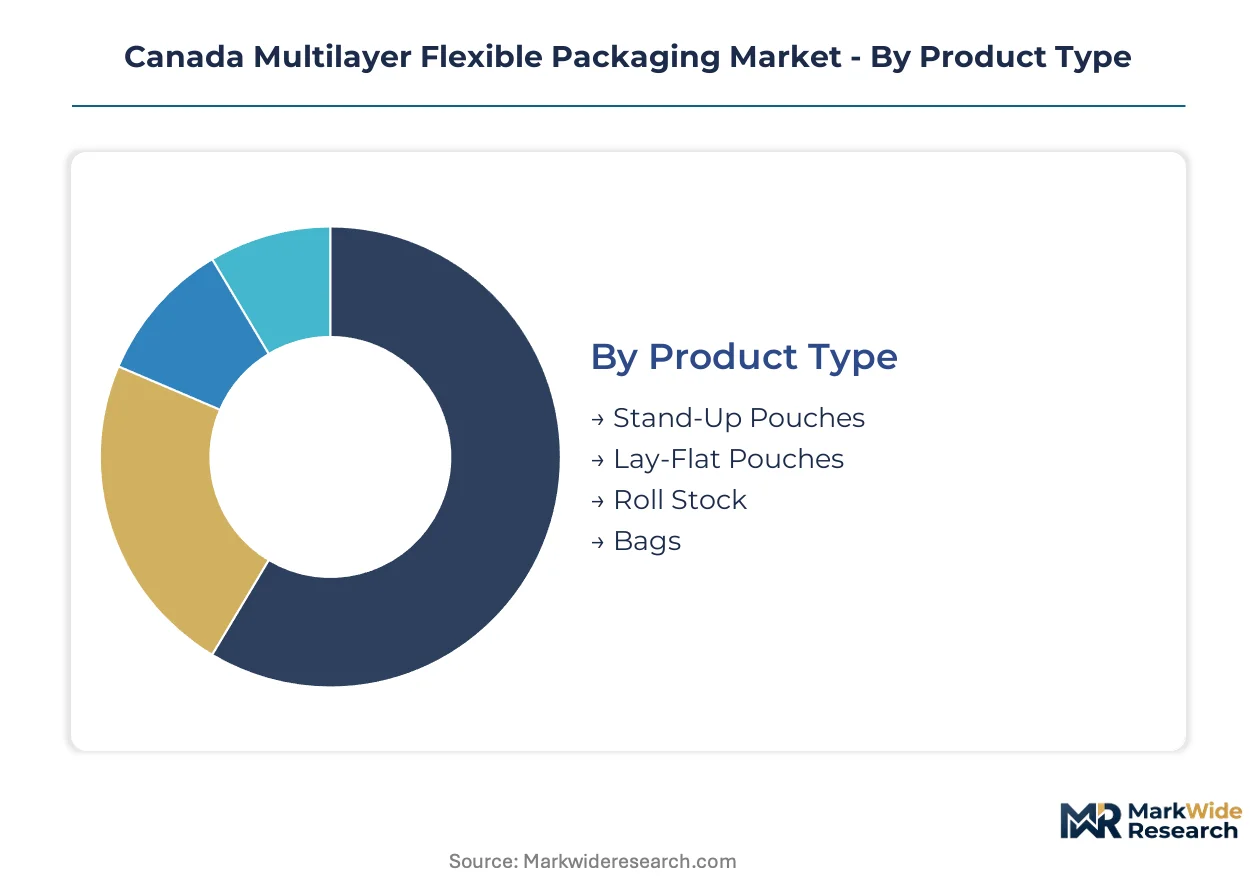
Multilayer flexible packaging segmentation in Canada reflects the tension between performance specifications demanded by protein processors and recyclability mandates from provincial regulators. Understanding how converters align product portfolios across these dimensions determines competitive positioning in the Ontario-Quebec corridor.
Product Type:
Supply concentration among major Canadian converters favors high-volume formats with dedicated production lines and established customer lock-in.
- Stand-Up Pouches:These structures incorporate bottom gussets and resealable zipper closures, typically combining polyethylene sealant layers with ethylene vinyl oxygen barrier films. Demand concentrates in Quebec dairy and Ontario frozen protein applications where retail shelf presence and consumer convenience drive specification. Provincial EPR frameworks are accelerating redesign toward mono-material polyethylene constructions compatible with store drop-off collection infrastructure.
- Roll Stock:Continuous web formats supplied to downstream form-fill-seal operations dominate volume flows into Canadian food manufacturing, particularly retort-capable specifications for export-grade beef and pork processing in Alberta and Ontario. Health Canada's food-contact notification requirements for new adhesive chemistries extend regulatory review timelines, compressing formulation flexibility for converters serving this segment.
- Lay-Flat Pouches:Three-side-seal configurations serve portion-controlled protein and cheese applications with lower capital equipment requirements for converters.
- Bags:Side-gusseted and pillow formats address bulk commodity packaging with thinner gauge specifications and reduced barrier complexity.
Today's leader: Roll Stock. Tomorrow's challenger: Stand-Up Pouches.
Material:
Cost tier stratification separates premium barrier specifications from economy grades, with resin selection directly determining recyclability credentials under evolving provincial frameworks.
- Barrier Films:Ethylene vinyl alcohol and polyamide coextrusions provide oxygen transmission rates below 1 cc/m²/day, enabling extended shelf-life for Canadian protein exports to Asian markets. Ontario and Quebec converters are expanding coextrusion capacity specifically for these specifications. Environment and Climate Change Canada's Chemicals Management Plan restrictions on perfluorinated grease-resistant coatings are forcing adhesive reformulation with uncertain performance windows.
- Polyethylene:Linear low-density and metallocene sealant grades dominate volume due to mechanical recycling compatibility and How2Recycle label qualification. Manitoba and Quebec dairy processors are piloting all-polyethylene structures for frozen applications previously requiring aluminum foil interlayers.
- Polypropylene:Cast and oriented films provide stiffness and clarity for premium retail presentations in personal care and specialty food segments.
- Aluminum Foil:Ultra-high barrier specifications for retort and long-life applications face displacement pressure as polyethylene barrier coatings improve.
Barrier Films command premium positioning. Polyethylene is climbing the fastest.
Application:
Volume concentration in food processing creates margin pressure, while pharmaceutical and personal care segments offer differentiation through compliance documentation and shorter production runs.
- Food:Protein, dairy, and processed food applications account for the dominant share of Canadian multilayer flexible packaging demand, with retort-capable specifications for export-grade beef and pork processing in Alberta and Ontario requiring the highest barrier performance. Health Canada's food-contact material regulations directly shape resin selection and adhesive chemistry across converting operations serving this segment.
- Beverage:Aseptic and hot-fill pouch formats for juice and dairy alternatives are gaining formulation share as packagers migrate from rigid containers.
- Personal Care:Stand-up pouches for liquid soap, shampoo, and conditioner require different sealant chemistries and fragrance barrier properties.
- Pharmaceutical:Blister lidding and sachet formats demand validated manufacturing processes and dedicated regulatory affairs documentation.
Food anchors volume throughput. Pharmaceutical offers margin expansion.
Distribution Channel:
Customer type fragmentation between national retail chains and regional processors determines converter scale requirements and sustainability verification burdens.
- Supermarkets:Major Canadian grocery retailers drive supplier consolidation through preferred vendor programs tied to EPR compliance verification and How2Recycle label adoption. This concentration is displacing fragmented regional converter relationships.
- Wholesalers:Foodservice and industrial supply channels service protein processors and dairy cooperatives with roll stock and bulk bag formats.
- Convenience Stores:Single-serve and portion-controlled formats for on-the-go consumption require shorter production runs and faster changeover capabilities.
- Online Retail:Direct-to-consumer fulfillment demands durable puncture-resistant structures and right-sized packaging to minimize dimensional weight shipping penalties.
Supermarkets dictate compliance standards. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are migrating capacity toward provinces with favorable extended producer responsibility cost structures and established protein processing corridors. British Columbia's early EPR implementation created compliance cost premiums that pushed some volume toward Ontario and Quebec. Alberta's export-grade beef operations continue demanding high-barrier specifications regardless of provincial regulatory differentials.
Ontario
Major beef, pork, and poultry processing clusters in the Golden Horseshoe drive demand for retort-capable roll stock. Environment and Climate Change Canada's Chemicals Management Plan restrictions on perfluorinated substances force Toronto-area converters toward solvent-free lamination systems. The Windsor-Toronto corridor hosts expanding coextrusion capacity serving cross-border food exporters.
Quebec
Dairy processors and specialty cheese producers in Montreal's South Shore require thermoformed barrier structures with extended shelf-life performance. Health Canada's food-contact notification requirements for new adhesive chemistries extend regulatory review timelines for Laval-based converters. The Drummondville-Sherbrooke axis concentrates pouch converting operations for frozen protein applications.
Alberta
Export-grade beef processing in Calgary and Edmonton corridors sustains demand for ultra-high barrier aluminum foil laminations. Provincial EPR frameworks lag Ontario and Quebec, creating temporary cost-of-compliance advantages for local converters. Red Deer's protein packaging hub is expanding coextrusion capacity for Asian export markets.
British Columbia
Early extended producer responsibility implementation created compliance cost premiums that compressed margins for Vancouver-area converters. Health Canada's evolving food-contact material regulations compound regulatory burdens for smaller operations. The Fraser Valley's specialty food sector pilots certified compostable structures for premium retail channels.
Manitoba
Ice cream and cheese processing in Winnipeg's industrial zone sustains specialized thermoforming demand with limited regional competition. Provincial EPR development remains behind Ontario and Quebec, attracting converter investment from cost-sensitive dairy suppliers. Brandon's emerging protein processing cluster is driving pouch specification demand.
Canada Multilayer Flexible Packaging Market Key Industry Players
Ontario and Quebec producers anchor the integrated tier with captive film extrusion and converting operations; Manitoba and British Columbia specialists hold regional positions through dairy-focused thermoforming and sustainable material transitions. Market structure tilts toward consolidation as national grocery retailers drive supplier rationalization through preferred vendor programs. Three archetypes dominate: integrated multinational converters with resin compounding capabilities, mid-size regional specialists with vertical control over specific formats, and sustainability-focused niche players certifying compostable alternatives. Capacity expansion and portfolio diversification toward mono-material recyclable structures represent the dominant competitive moves.
Among integrated multinational converters, Amcor plc and Winpak Ltd. exemplify the captive supply archetype through in-house resin compounding and specialized thermoforming operations. Transcontinental Inc. occupies a position emphasizing sustainable material transitions and regional brand partnerships. These three entities represent contrasting strategic postures within a market where EPR compliance verification and How2Recycle label qualification increasingly determine procurement decisions.
| Leading Market Players |
|---|
| Amcor plc |
| Winpak Ltd. |
| Transcontinental Inc. |
| Berry Global Inc. |
| Sonoco Products Company |
| Sealed Air |
| Mondi Group |
| Glenroy Inc. |
| Westrock Company |
| Others |
Cost & Logistics Intelligence
Mono-material polyethylene adoption is compressing cost differentials between barrier grades while redistributing margin pools toward converters with in-house coextrusion capabilities. This formulation shift simultaneously lowers resin complexity costs and concentrates supply leverage among Ontario-Quebec integrated producers.
Pricing Analysis
Distributor margins on roll stock formats absorb the steepest compression as national grocery retailers consolidate procurement through direct converter relationships. Three-tier pricing structure across premium barrier, standard multi-layer, and economy mono-material levels stratifies by oxygen transmission performance and EPR compliance certification. Pricing pressure stems from provincial extended producer responsibility fees layered onto legacy aluminum-foil constructions. Regional dairy processors exhibit highest price sensitivity due to thin margins on commodity cheese and ice cream, while export-grade protein packers prioritize shelf-life performance over unit cost.
Supply Chain Analysis
Cross-border freight costs from US Gulf Coast petrochemical complexes to Ontario converting plants have amplified working capital requirements for polyethylene and polypropylene feedstock. Raw material supply draws from Texas-Louisiana resin production, Quebec aluminum smelting, and domestic ethylene vinyl alcohol compounding. Single-source vulnerability concentrates in barrier film coextrusion equipment where European and Japanese OEMs dominate installed base. Distribution runs through direct mill-to-plant delivery for high-volume roll stock, with regional warehousing supporting just-in-time pouch converting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
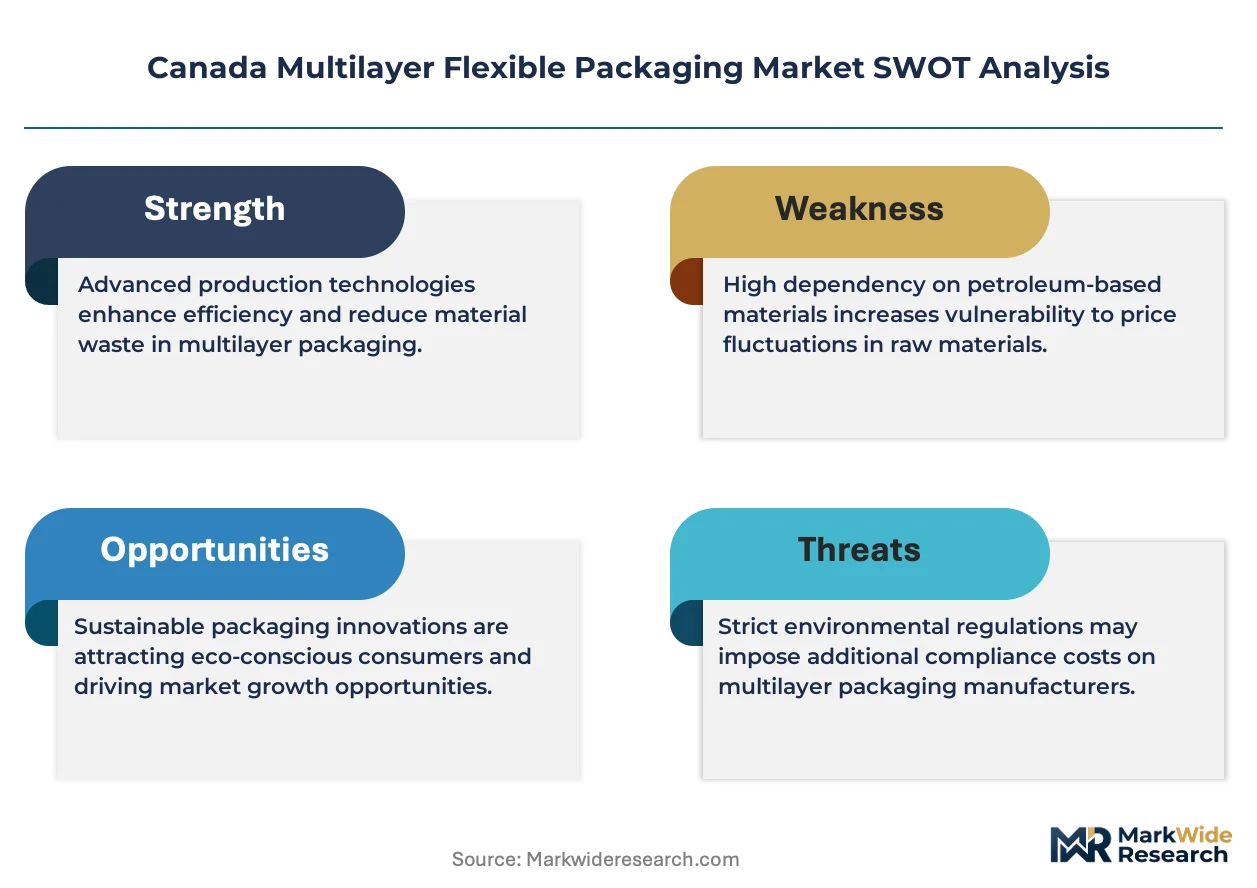
Margin expansion in Canadian multilayer flexible packaging rests on mono-material premiumization and solvent-free lamination cost-downs that offset EPR compliance investments.
For Market Incumbents: Cement market position through captive resin compounding in the Windsor-Toronto corridor and accelerated How2Recycle certification for polyethylene-only structures. Threat from Alberta-based converters exploiting lagging provincial EPR timelines demands preemptive capacity expansion in Manitoba dairy corridors. Vertical control over sealant film extrusion preserves margin against resin price volatility. For New Entrants and Emerging Players: Launch via certified compostable pilot programs targeting British Columbia's premium specialty food sector where EPR cost premiums have displaced incumbent volume. White-space concentrates in thermoformed barrier structures for Winnipeg ice cream processors facing limited regional supply alternatives. Digital printing partnerships with Quebec artisan cheese brands offer low-capital entry with short-run differentiation. For Investors and Strategic Acquirers: Roll-up economics work for mid-size Ontario converters with stranded solvent-based lamination assets because Health Canada's extended adhesive review timelines block greenfield competition. Five-to-ten-year viability hinges on mechanical recycling infrastructure buildout across provincial EPR schemes. Acquisition targets should demonstrate existing BPI or TUV Austria certification pipelines. The signal to watch is Alberta's EPR implementation timeline, which would eliminate the province's temporary cost advantage and trigger cross-border capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Migration | Health Canada's food-contact notification timelines favor early movers with validated polyethylene barrier structures. |
| Solvent-Free Lamination Retrofit | Environment and Climate Change Canada's Chemicals Management Plan eliminates legacy coating chemistry from compliant supply chains. |
| Manitoba Thermoforming Expansion | Winnipeg's ice cream and cheese processing cluster offers limited competition for specialized barrier structures. |
| How2Recycle Label Adoption | National grocery retailer preferred vendor programs require store drop-off compatibility verification for procurement eligibility. |
| Digital Printing Convergence | Flexographic-inkjet hybrid systems enable Quebec artisan brand partnerships without plate inventory costs. |
Research Approach
Direct dialogue with extrusion plant managers, grocery retail category buyers, dairy procurement leads, and regulatory affairs consultants at Health Canada grounded qualitative findings in operational reality. Secondary validation drew from Environment and Climate Change Canada Chemicals Management Plan filings, provincial EPR implementation schedules, How2Recycle label qualification databases, and Canadian plastics trade association capacity surveys. Bottom-up resin demand modeling and top-down food packaging value chain analysis were cross-triangulated against converter capacity announcements.
Bottom-up segment sizing by product type, material grade, and end-use application was reconciled against top-down food processing output data across the analysis window. Segmentation dimensions modeled include barrier performance tier, recyclability certification status, and provincial regulatory framework cluster. CAGRs were derived from elasticity-adjusted demand projections for protein and dairy packaging volumes. Industry-specific inputs incorporated Health Canada food-contact notification approval timelines and provincial EPR fee schedule differentials.
Several conditions sit outside the modeled scope, including potential US-Canada trade friction affecting resin feedstock costs and breakthrough barrier coating technologies that bypass current adhesive chemistries entirely. Forecasts reflect assumptions about mechanical recycling infrastructure buildout pacing and Health Canada review timeline stability. A model refresh is warranted upon material change in Alberta's EPR implementation schedule or major grocery retailer supplier consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Europe Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
China Flexible Plastic Packaging Market
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market