
 North America Flexible Packaging Market | 2026-2036
North America Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flexible Packaging Market Intelligence
A capital-intensity divergence between integrated resin producers and specialized converters is redrawing competitive boundaries across the North American flexible packaging sector. Amcor plc leverages its blown film extrusion network to sustain margin control across multiple substrate categories. Berry Global anchors its position through geographic dominance in the U.S. Southeast, where it operates large-scale polyethylene converting facilities. Sealed Air differentiates through technology leadership in barrier film coextrusion, competing primarily in protein and medical packaging segments.
Flexible packaging comprises polymer-based or multilayer substrates engineered into pouches, bags, and roll stock formats with thicknesses typically ranging from 50 to 200 microns, designed to protect contents from moisture, oxygen, and mechanical damage during distribution and shelf life. Stand-up pouches and flat pouches command the largest share of product type demand, driven by shelf-ready merchandising requirements in retail grocery. Plastic substrates, particularly polyethylene and polypropylene composites, lead material consumption by volume, though paper-based alternatives are gaining structural traction in e-commerce shipping applications where curbside recyclability influences procurement decisions.
The U.S. Food and Drug Administration governs food contact notifications for multilayer structures, while the Environmental Protection Agency regulates volatile organic compound emissions from solvent-based printing operations, collectively elevating capital requirements for compliant manufacturing. Health Canada and the Canadian Food Inspection Agency enforce parallel standards that create cross-border harmonization pressure for North American converters. Stakeholders must monitor emerging extended producer responsibility frameworks at the U.S. state level, where California and New York are advancing distinct recycling infrastructure mandates that will reshape substrate selection criteria and collection economics.
Market Dynamics
Converters across the United States and Canada face mounting pressure from the FDA's evolving food contact substance notification requirements, which are forcing multilayer structure redesigns and elevating compliance capital burdens for mid-tier producers.
Growth Catalysts
- Pouch-based ready-to-eat meal adoption:Food and beverage manufacturers in the U.S. Great Lakes corridor are expanding stand-up pouch formats for single-serve meals, driving substrate demand from Midwestern food processing hubs.
- Extended producer responsibility frameworks:California and New York are advancing distinct recycling infrastructure mandates that create regulatory pull for recyclable multilayer structures.
- Barrier film coextrusion advances:Protein and medical packaging segments are absorbing high-performance coextruded films with enhanced oxygen and moisture protection.
Market Restraints
- Resin supply concentration:Polyethylene and polypropylene feedstock supply clusters along the U.S. Gulf Coast, exposing converters to hurricane-related disruption risk and freight cost volatility.
- Solvent-based printing regulatory friction:EPA volatile organic compound emission controls on rotogravure and flexographic operations are constraining capacity expansion for non-compliant facilities.
- Curbside recyclability technical limitation:Multilayer flexible structures containing incompatible polymer combinations face mechanical recycling rejection at municipal material recovery facilities.
Strategic Opportunities
- E-commerce shipping paper substitution:Paper-based flexible alternatives are penetrating corrugated void fill and mailer applications where Canadian and U.S. retailers face procurement mandates for curbside-recyclable packaging.
- Health Canada harmonization pressure:Parallel food contact standards with the FDA create cross-border substrate standardization opportunities for converters serving both markets.
- Digital printing convergence with short-run production:Inkjet and electrophotographic technologies are enabling economic production of versioned packaging for regional food brands and private label programs.
Industry Challenges
- Multilayer structure redesign talent scarcity:Food contact notification compliance requires specialized polymer science and regulatory affairs expertise that converters struggle to recruit in the U.S. Midwest manufacturing corridor.
- Legacy solvent-to-water-based ink conversion capex burden:Press modification and drying system upgrades demand capital commitments that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flexible Packaging Market |
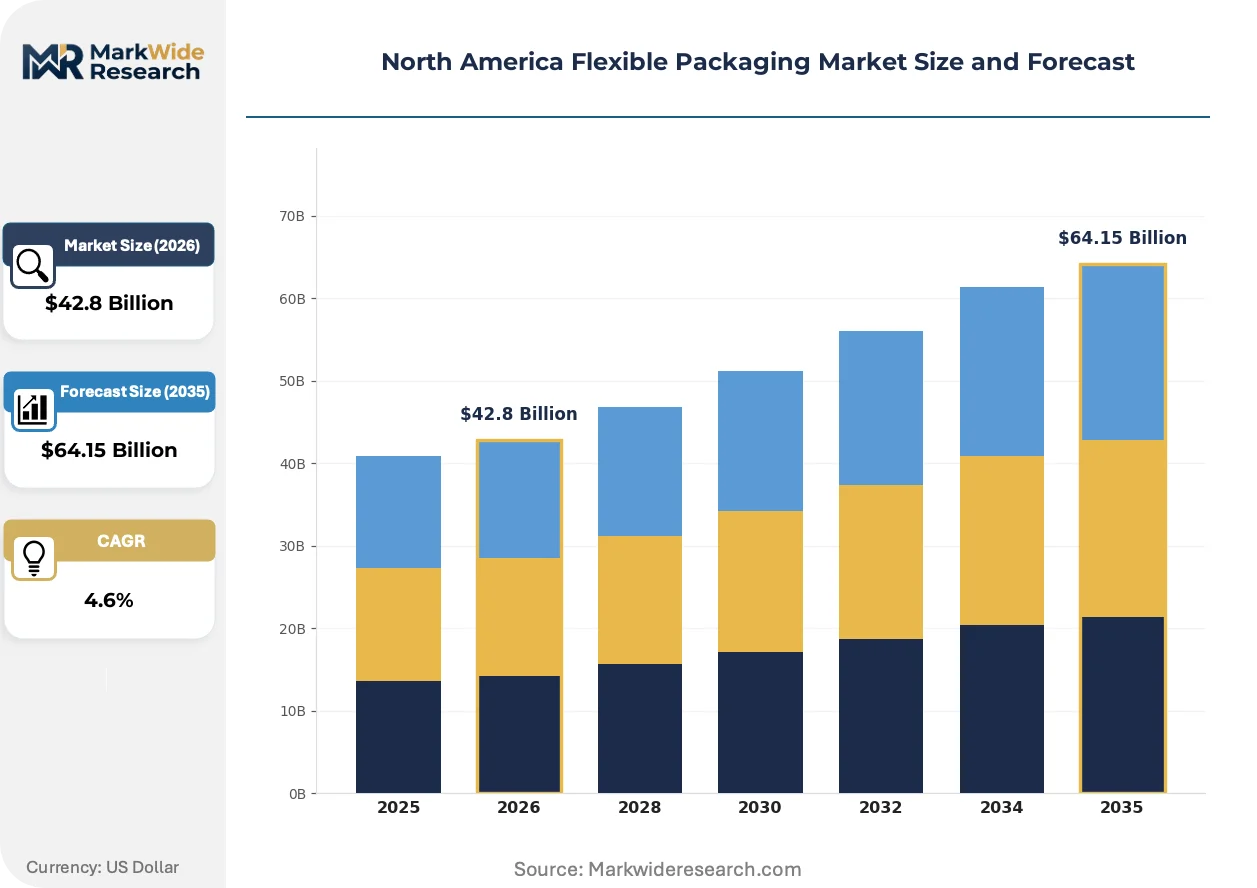
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Roll Stock, Bags Material: Plastic, Paper, Aluminum, Composites Application: Food & Beverage, Pharmaceuticals, Personal Care, Household Products End User: Manufacturers, Retailers, Distributors, E-commerce Platforms |
| Companies Covered | Amcor plc, Berry Global, Sealed Air, Mondi Group, Sonoco Products Company, Huhtamaki, Constantia Flexibles, Transcontinental Inc., American Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flexible Packaging Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compression are converging to reshape substrate selection criteria across protein, medical, and e-commerce packaging end-uses. Three developments dominate strategic planning.
Mono-material polyethylene structures with enhanced barrier properties are supplanting conventional multilayer constructions incompatible with existing mechanical recycling infrastructure. Major U.S. retail grocery chains are accelerating specification of these substrates for private label shelf-ready pouches. The shift is compressing demand for ethylene vinyl alcohol and polyamide barrier layers while expanding metallocene polyethylene resin consumption.
The EPA's tightened volatile organic compound emission standards for packaging printing operations are compelling solvent-based rotogravure facilities toward water-based ink system retrofits or digital press replacement. Compliance timelines vary by facility age and location, with older U.S. Southeast converting plants facing the steepest capital burden. The regulatory pressure is fragmenting competitive capacity between compliant and non-compliant producers.
Direct sourcing relationships between food processors and specialized converters are displacing traditional distributor-mediated procurement for high-volume pouch programs. This channel compression concentrates volume with vertically integrated producers capable of in-house extrusion, printing, and bag-making. The pattern is most pronounced in the U.S. Great Lakes protein packaging corridor, where turkey and ready-to-eat meat processors are consolidating supplier bases.
North America Flexible Packaging Market Segmentation
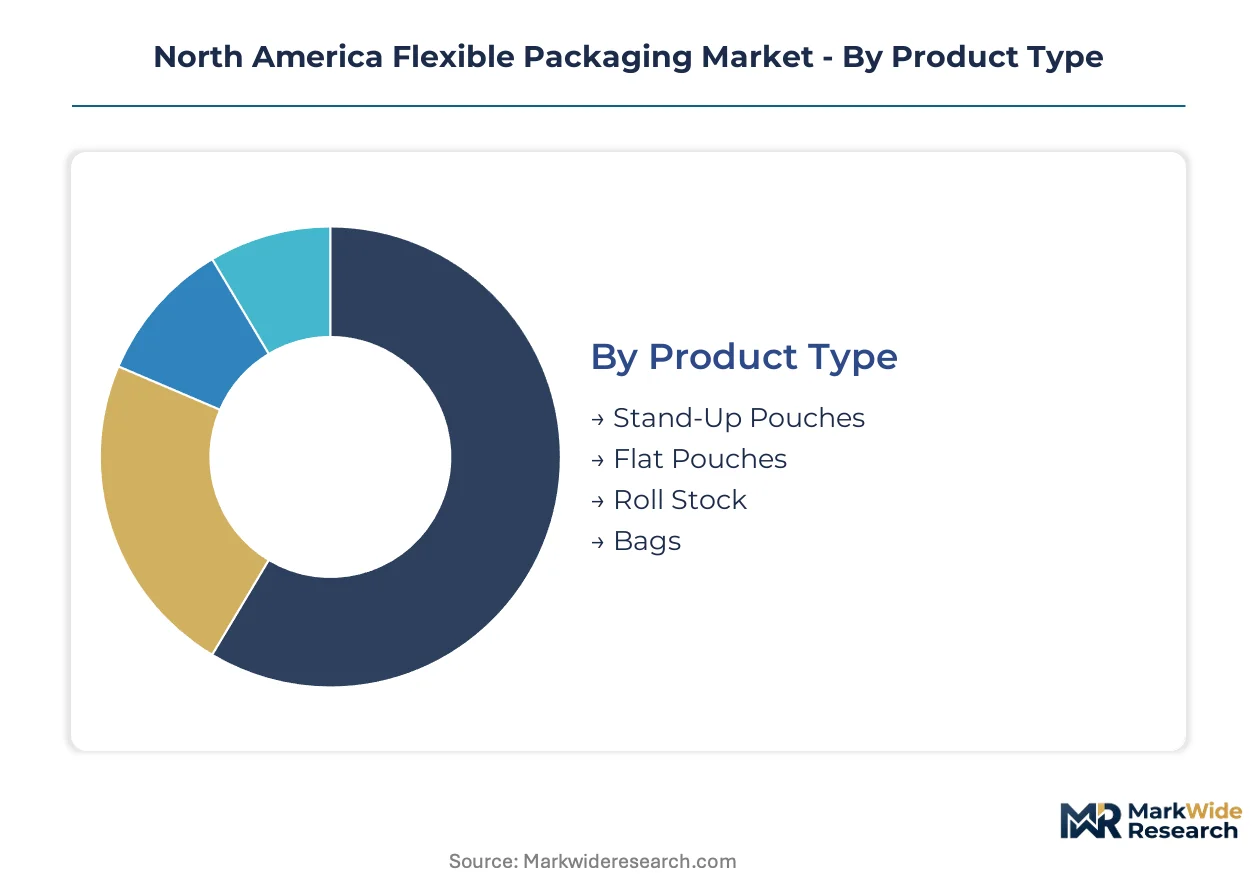
Flexible packaging segmentation in North America tracks how substrate selection and format engineering align with FDA food contact compliance and regional recycling mandates. Distinct margin pools form around barrier performance requirements and end-use regulatory intensity.
Product Type:
Margin concentration follows shelf-ready merchandising functionality and barrier complexity rather than raw material tonnage.
- Stand-Up Pouches:Multilayer constructions with bottom gussets and resealable closures dominate protein and ready-to-eat meal applications. Demand concentrates in the U.S. Great Lakes corridor where turkey processors and meal kit brands specify high-oxygen-barrier specifications for extended shelf life.
- Flat Pouches:Three-side-seal and four-side-seal formats serve single-serve snack and confectionery segments with lower barrier requirements. California and New York retailers are driving specification shifts toward mono-material polyethylene versions compatible with emerging extended producer responsibility collection streams.
- Roll Stock:Unformed substrate supplied to downstream form-fill-seal operations, capturing volume in high-speed vertical packaging lines for frozen vegetables and shredded cheese.
- Bags:Gusseted and pillow formats retain share in bulk dry goods and produce, though growth lags pre-formed pouch alternatives.
Stand-Up Pouches holds installed capacity. Flat Pouches is rotating up the share rankings.
Material:
Cost tier stratification separates commodity resin volumes from specialized barrier and fiber-based alternatives.
- Plastic:Polyethylene and polypropylene composites constitute the volume foundation, with metallocene grades displacing conventional multilayer structures. EPA volatile organic compound regulations on solvent-based printing are accelerating water-based ink compatibility requirements for plastic substrates.
- Paper:Fiber-based flexible formats with polymer barrier coatings are penetrating e-commerce mailer and void-fill applications where Amazon and Canadian retailers enforce curbside recyclability procurement mandates.
- Aluminum:Foil laminations retain defensive positions in retort pouches and pharmaceutical blister foils despite weight and formability limitations.
- Composites:Engineered multilayer structures combining plastic, foil, and paper face mechanical recycling rejection at municipal material recovery facilities.
Plastic dominates volume throughput. Paper is climbing the fastest as retail procurement mandates harden.
Application:
Volume concentration maps to end-use regulatory intensity and shelf-life extension requirements.
- Food & Beverage:The largest application segment spanning fresh produce, processed proteins, dairy, and ready-to-eat meals. FDA food contact substance notification requirements force continuous multilayer redesigns for compliant adhesive and coating systems.
- Pharmaceuticals:High-barrier blister packs, sachets, and strip packaging for unit-dose medications demand validated manufacturing environments and traceable supply chains under Health Canada and FDA current good manufacturing practice standards.
- Personal Care:Stand-up pouches for shampoo, lotion, and cosmetic samples prioritize consumer convenience and shelf differentiation over barrier performance.
- Household Products:Refill pouches for cleaning chemicals and laundry detergents specify chemical resistance and child-resistant closure compatibility.
Food & Beverage commands converter capacity allocation. Pharmaceuticals is gaining share fastest on regulatory pull-through.
End User:
Customer type determines order scale, specification control, and channel compression dynamics.
- Manufacturers:Food processors and consumer goods companies with direct converter relationships specify custom substrate structures and print designs. The U.S. Great Lakes protein packaging corridor shows concentrated manufacturer-direct procurement for high-volume pouch programs.
- Retailers:Private label specification power concentrates with Walmart, Kroger, and Canadian grocery chains demanding mono-material recyclability and versioned regional graphics.
- Distributors:Independent packaging distributors serve mid-tier converters and smaller brands with standard stock formats, facing margin compression from direct sourcing trends.
- E-commerce Platforms:Amazon, Shopify merchants, and third-party logistics providers specify paper-based mailers and protective flexible formats optimized for dimensional weight shipping economics.
Manufacturers retain specification authority. E-commerce Platforms is expanding most quickly on fulfillment infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America flexible packaging sector maintains a structural trade surplus in converted goods while importing specialty resins and barrier films from European and Asian suppliers. Cross-border regulatory harmonization between the United States and Canada reduces compliance friction, though Mexico's distinct standards create segmentation opportunities for regional converters.
United States
Stand-up pouch demand from turkey processors and ready-to-eat meal brands drives substrate consumption across the Great Lakes manufacturing corridor. The FDA's food contact substance notification requirements force continuous multilayer redesigns for adhesive and coating compliance. Chicago and Milwaukee anchor the highest concentration of converting capacity, where resin compounding operations cluster near Midwestern food processing hubs.
Canada
Health Canada and the Canadian Food Inspection Agency enforce parallel food contact standards that create cross-border standardization pull for converters serving both markets. The country's extended producer responsibility frameworks in British Columbia and Ontario advance distinct recycling infrastructure mandates. Toronto and Montreal concentrate flexible packaging demand from protein processors and pharmaceutical manufacturers seeking validated supply chains.
Mexico
Export-oriented food processors in Jalisco and Nuevo León specify pouch formats for North American retail distribution, driving converting investment near Mexico City and Guadalajara. Mexico's federal consumer protection agency enforces labeling standards that diverge from U.S. FDA requirements. The Bajío Region attracts foreign converter investment targeting duty-advantaged supply to the United States under USMCA provisions.
California
State-level extended producer responsibility legislation mandates recyclable packaging procurement by retailers operating in the nation's largest consumer market. The California Department of Resources Recycling and Recovery enforces rigid post-consumer content requirements that reshape substrate selection criteria. Los Angeles and the Central Valley concentrate demand from produce packers and private label food brands.
New York Metro
Financial services and pharmaceutical headquarters in Manhattan and northern New Jersey drive high-barrier sachet and blister pack demand with traceability requirements. New York State's emerging packaging reduction and recycling infrastructure act creates regulatory pull for mono-material structures. The Port of Newark handles substantial European barrier film imports for regional converting operations.
North America Flexible Packaging Market Key Industry Players
Concentration sits with integrated resin-to-converter operators and specialized barrier film specialists rather than mid-tier independent converters. Three to five multinational corporations control the majority of blown film extrusion capacity across polyethylene and polypropylene substrate categories. Strategic archetypes include integrated polymer producers with captive converting networks, specialized coextrusion technology leaders, and regional scale players anchored in specific manufacturing corridors. Competitive dynamics revolve around M&A consolidation of independent converters and capacity expansion in FDA-compliant multilayer structures.
Within the integrated multinational tier, Amcor plc, Berry Global, and Sealed Air exemplify contrasting strategic positions. Amcor plc represents the globally diversified converter archetype with extrusion networks spanning multiple substrate categories. Berry Global anchors a geographic concentration model with large-scale polyethylene operations in the U.S. Southeast. Sealed Air occupies a technology leadership position in barrier film coextrusion, competing primarily in protein and medical packaging segments where oxygen and moisture protection commands premium positioning.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Sealed Air |
| Mondi Group |
| Sonoco Products Company |
| Huhtamaki |
| Constantia Flexibles |
| Transcontinental Inc. |
| American Packaging Corporation |
| Others |
Cost & Logistics Intelligence
Long-term resin offtake contracts with Gulf Coast petrochemical producers lock in polyethylene and polypropylene supply access while providing converters with 12-18 month price visibility against volatile spot markets. These arrangements concentrate procurement power with integrated operators capable of volume commitments, leaving mid-tier converters exposed to margin compression during feedstock price spikes.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing structures across the North American flexible packaging sector. Three-tier pricing stratification separates FDA-validated medical barrier films from standard food-grade pouches and commodity shipping sacks, with certification tier and volume scale driving spreads. Cost compression in commodity polyethylene substrates is intensifying because resin producers are passing through natural gas feedstock volatility. Small regional converters exhibit highest price sensitivity due to limited backward integration, while multinational integrated players absorb fluctuations through captive resin production.
Supply Chain Analysis
Strategic stockpiling of specialty barrier resins and adhesive raw materials characterizes converter inventory management, contrasting with just-in-time polyethylene procurement. Feedstock supply concentrates in the United States, Canada, and Mexico, with the U.S. Gulf Coast hosting the majority of ethylene cracker capacity. Raw material dependencies include metallocene polyethylene, ethylene vinyl alcohol copolymers, and solvent-based printing inks. Hurricane-related disruption risk constitutes the primary structural vulnerability for North American converters. Distribution runs through direct manufacturer relationships for high-volume pouch programs, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American flexible packaging market is entering a cyclical recovery phase supported by protein processor capacity expansion in the U.S. Great Lakes corridor. Inventory restocking and FDA compliance-driven substrate redesigns are accelerating order flow across converter networks.
For Market Incumbents: Consolidate independent converter assets in the U.S. Midwest manufacturing corridor to secure FDA-compliant multilayer capacity and capture direct-sourcing volume from turkey and ready-to-eat meal processors. Acquire specialized barrier film coextrusion technology to defend margin position against emerging mono-material competitors. Prioritize backward integration into metallocene polyethylene resin compounding to reduce Gulf Coast supply disruption exposure.
For New Entrants and Emerging Players: Digital printing service gaps in short-run versioned packaging for regional private label brands offer immediate white-space opportunity. Target California and New York retailers demanding mono-material recyclable structures with water-based ink compatibility, where incumbent rotogravure assets face EPA compliance retrofit burdens. Pursue partnership-based go-to-market models with e-commerce fulfillment platforms specifying paper-based mailer formats.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized barrier film converters with validated FDA food contact notification portfolios and Health Canada dual-market exposure. Long-term viability over the coming decade rests on substrate recyclability positioning ahead of extended producer responsibility mandate expansion. Monitor California Department of Resources Recycling and Recovery enforcement actions as the critical inflection signal for substrate specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Blown film extrusion additions in the U.S. Great Lakes corridor capture protein processor pouch demand. |
| Backward Integration | In-house metallocene polyethylene compounding reduces Gulf Coast resin supply disruption exposure. |
| Green Manufacturing Transition | Water-based ink system retrofits satisfy EPA volatile organic compound emission standards. |
| Long-term Supply Agreement | Direct sourcing contracts with turkey processors lock in high-barrier multilayer volume commitments. |
| Joint Venture | Partnerships with paper substrate producers address Amazon curbside recyclability procurement mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA food contact notification databases, EPA enforcement records, and trade association resin consumption reports. Primary interviews encompassed flexible packaging plant managers, procurement leads at protein processing OEMs, distribution channel partners, and regulatory affairs directors specializing in multilayer compliance. Secondary validation drew from American Chemistry Council resin production data, SEC 10-K disclosures from integrated converters, and Health Canada food packaging guidance documents. Bottom-up volume estimates triangulated against top-down market sizing across substrate categories.
Segmentation dimensions modeled include product type, material substrate, application end-use, and customer archetype across the analysis window. The analytical framework projected value expansion using demand elasticity parameters derived from food processor capital expenditure cycles and retail private label procurement patterns. CAGRs were computed from historical resin consumption trends and forward-looking capacity utilization assumptions. Industry-specific forecast inputs incorporated EPA regulatory compliance timelines and extended producer responsibility implementation schedules.
Underlying assumptions cover resin price stability, hurricane frequency patterns, and FDA notification processing timelines, with deviation risk concentrated in feedstock volatility and state-level recycling mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market