
 Silica for S-SBR Market | 2026-2036
Silica for S-SBR Market Size, Share, and Industry Trends Forecast 2026-2036
Silica for S-SBR Market Analytics
Capital-intensity divergence between integrated precipitated silica producers and regional compounders is redrawing competitive boundaries in the Silica for S-SBR supply base. Evonik Industries AG leverages its backward integration into sodium silicate and sulfuric acid to sustain margin capture across tire maker contracts. Solvay S.A. anchors its position through specialized surface-treated grades that dominate European premium tire formulations. PPG Industries competes on manufacturing scale at its North American precipitated silica complexes.
Silica for S-SBR comprises synthetic amorphous silicon dioxide engineered as a reinforcing filler in solution-polymerized styrene-butadiene rubber compounds, typically surface-treated with silane coupling agents to enable covalent bonding with the rubber matrix and deliver reduced hysteresis loss. Precipitated silica leads product type volumes due to mature supply chains and proven dispersion economics in tire tread applications, while fumed silica occupies higher-margin niches in specialty footwear and industrial rubber goods requiring extreme thermal stability. Reinforcement functionality commands the largest share within functionality segmentation as tire OEMs prioritize tensile strength and tear resistance in fuel-efficient tread designs.
REACH registration requirements in Europe and EPA emissions standards in the United States constrain silica manufacturing processes and elevate compliance costs for producers serving automotive supply chains. China's GB standards on tire fuel consumption and rolling resistance are tightening specifications for silica-reinforced S-SBR compounds exported to domestic vehicle manufacturers. Stakeholders must monitor evolving coupling agent chemistries and regional carbon border adjustments that will determine cost-competitive sourcing strategies across tire industry procurement networks.
Market Dynamics
Tire OEMs in Germany, China, and the United States are mandating silica-reinforced S-SBR formulations to satisfy rolling resistance thresholds, compressing compounder margins while rewarding integrated precipitated silica producers with backward control over sodium silicate supply.
Growth Catalysts
- EU tire labeling mandates:Fuel efficiency grades now require low-hysteresis tread compounds, pulling precipitated silica into OE tire specifications across European vehicle assembly plants.
- China's GB standards on tire fuel consumption:Domestic tire exports to Chinese OEMs must meet tightening rolling resistance coefficients, accelerating silica-loaded S-SBR adoption in Shandong and Jiangsu manufacturing clusters.
- Silane coupling agent advances:Bifunctional organosilane chemistry improves silica-rubber interfacial bonding, enabling higher filler loadings without sacrificing processability in extrusion lines.
Market Restraints
- Sulfuric acid and sodium silicate cost volatility:Integrated producers with captive acid supply maintain margin buffers that regional compounders cannot replicate, concentrating viable production in coastal chemical corridors.
- REACH registration compliance burden:ECHA documentation requirements for surface-treated silica grades elevate fixed costs for European manufacturers serving automotive supply chains.
- Carbon black substitution economics:High-structure furnace blacks retain cost advantages in non-fuel-efficient tire segments, limiting silica penetration in emerging-market commercial vehicle tires.
Strategic Opportunities
- Underpenetrated Indian tire manufacturing:Domestic OEMs in Chennai and Pune are adopting EU-equivalent rolling resistance specifications, creating first-mover openings for precipitated silica suppliers with local technical service capabilities.
- Retread and tire-derived material recovery:Silica-reinforced S-SBR compounds demonstrate superior grindability for rubber reclaiming, aligning with circular economy mandates in European waste frameworks.
- Non-tire industrial rubber goods:Conveyor belting and vibration isolation mounts in German automotive supplier parks are specifying surface-treated silica for dynamic fatigue resistance beyond traditional carbon black performance.
Industry Challenges
- Silane handling and hydrolysis control:Tire compounders lack in-house organosilane expertise, forcing reliance on pre-treated silica deliveries that extend lead times and inflate working capital requirements.
- Batch-to-batch dispersion consistency:In-mix silica distribution variability generates scrap rates in high-speed extrusion lines, demanding real-time rheology monitoring investments that mid-scale compounders defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica for S-SBR Market |
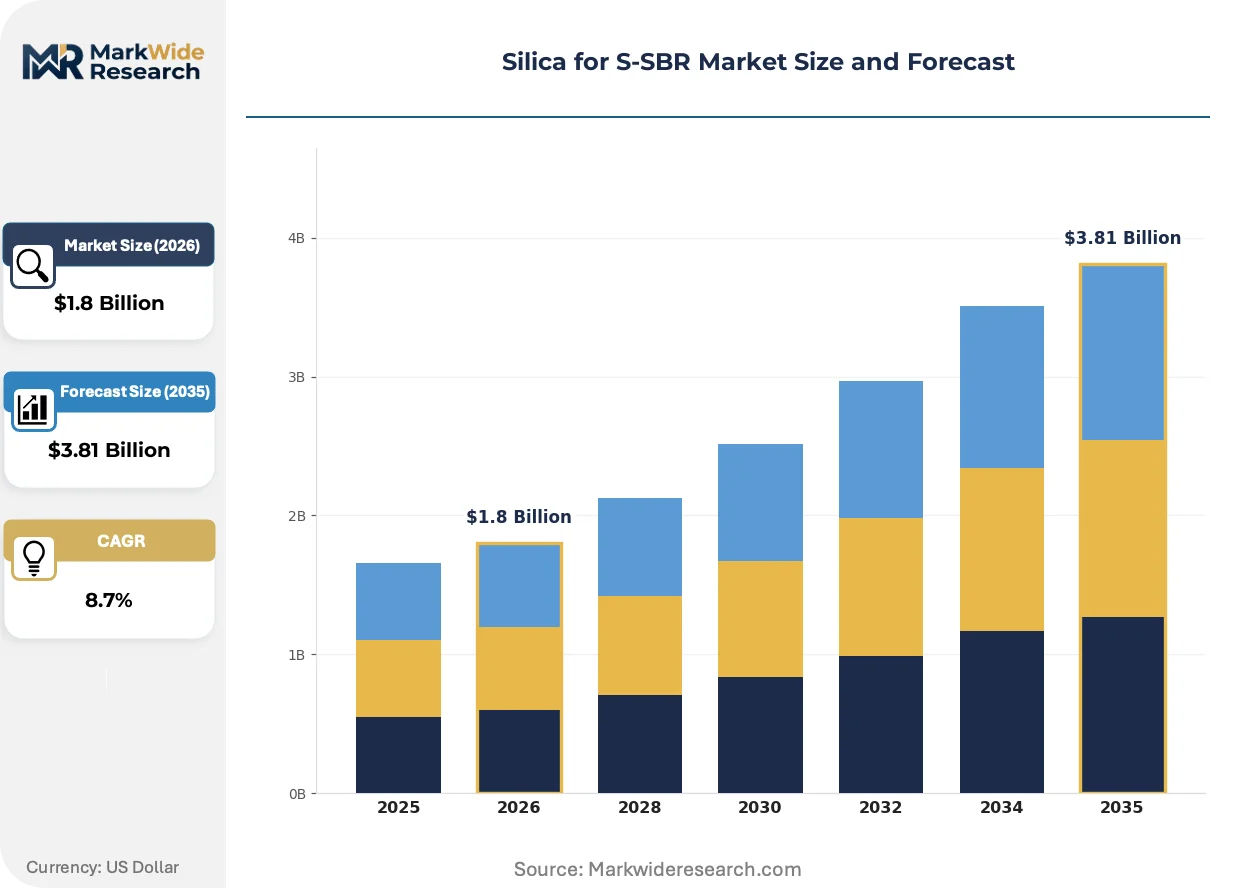
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precipitated Silica, Fumed Silica, Silica Gel, Micro Silica End Use Industry: Automotive, Tires, Footwear, Coatings Functionality: Reinforcement, Abrasion Resistance, Thermal Stability, Modulus Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Evonik Industries AG, Solvay S.A., PPG Industries, Inc., Wacker Chemie AG, Cabot Corporation, Tosoh Silica Corporation, Oriental Silicas Corporation, Quechen Silicon Chemical Co., Ltd., Madhu Silica Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica for S-SBR Market Evolving Landscape
Surface chemistry engineering and coupling agent formulation are compressing the performance gap between precipitated and fumed silica grades, while regulatory pressure on tire lifecycle emissions accelerates material specification changes across OEM procurement offices.
Advanced silane pre-treatment systems for precipitated silica are decomposing the traditional trade-off between filler loading levels and compound viscosity in tire tread formulations. Major tire manufacturers in Germany and Japan are adopting these systems for 2026 OE platform launches. The technology is decomposing historical volume premiums for fumed silica in high-performance tire segments by delivering equivalent dynamic mechanical properties at precipitated-grade cost structures.
REACH authorization timelines for novel organosilane chemistries are extending qualification cycles for new silica grades in European tire supply chains. ECHA's substance evaluation protocols now require extended environmental fate data that delays market entry by 18-24 months. Premium tire manufacturers are responding by locking in multi-year supply agreements with incumbent silica producers holding valid dossiers, freezing out newer entrants.
Specification-driven procurement is consolidating tire compounder supplier lists around silica producers with integrated analytical laboratories and compound development partnerships. Tier-1 tire manufacturers now require collaborative tread formulation support rather than commodity filler transactions. This shift is most pronounced in German and US Midwest automotive corridors where OEMs audit supplier technical service capabilities alongside material certificates.
Silica for S-SBR Market Segmentation
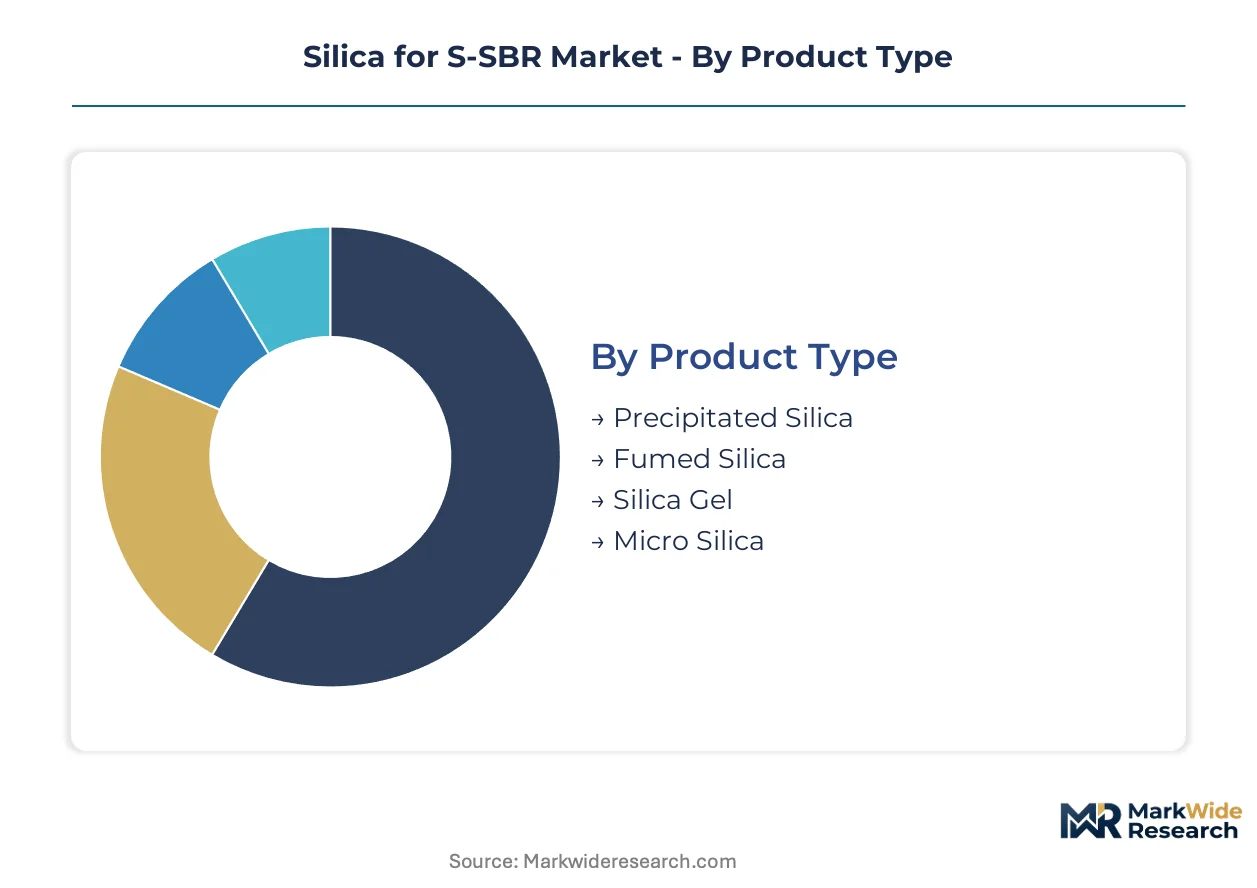
Silica for S-SBR segmentation reveals divergent supply chain economics across product grades and end-use specifications. Tire OEM procurement patterns favor integrated producers capable of delivering surface-treated precipitated silica with consistent dispersion properties, while specialty applications sustain premium positioning for fumed and gel variants.
Product Type:
Domestic production of precipitated silica concentrates in coastal chemical corridors with captive sodium silicate supply, whereas fumed silica and specialty grades depend heavily on import flows from German and Japanese manufacturing complexes.
- Precipitated Silica:Synthetic amorphous silicon dioxide produced via acid precipitation of sodium silicate, engineered with controlled particle size distribution for rubber reinforcement. Demand clusters in German tire manufacturing corridors and Shandong province processing facilities serving domestic OEMs, driven by EU tire labeling mandates requiring low-hysteresis tread compounds.
- Fumed Silica:High-purity silicon dioxide synthesized through flame hydrolysis of silicon tetrachloride, delivering extreme surface area and thermal stability for specialty applications. Premium footwear manufacturers in Italy and industrial rubber goods producers in Japan specify fumed grades for dynamic fatigue resistance beyond precipitated performance thresholds.
- Silica Gel:Mesoporous silica with high adsorption capacity, finding niche application in moisture-sensitive rubber compounding and specialty coating formulations.
- Micro Silica:Ultrafine silica fume byproduct from ferrosilicon production, utilized in high-performance concrete and limited rubber reinforcement applications requiring extreme fineness.
Precipitated Silica holds the largest share; momentum sits with Fumed Silica in premium non-tire segments.
End Use Industry:
Cost-tier stratification separates commodity tire formulations from premium automotive and footwear specifications, with coating applications commanding intermediate pricing based on dispersion technology requirements.
- Automotive:Vibration isolation mounts, seals, and hoses in vehicle assembly supply chains specify surface-treated silica for dynamic mechanical performance under thermal cycling.
- Tires:Tread and sidewall compounds incorporating precipitated silica with silane coupling agents achieve rolling resistance coefficients mandated by EU tire labeling and China's GB standards on fuel consumption.
- Footwear:High-performance athletic and industrial boot manufacturers in Italy and Vietnam specify fumed silica for abrasion resistance and flex fatigue durability in soling compounds.
- Coatings:Industrial and automotive coating formulators utilize colloidal silica for scratch resistance and matting efficiency in waterborne systems.
Tires dominate volume absorption; Footwear delivers the steepest expansion trajectory in value terms.
Functionality:
Application maturity varies sharply across functional roles, with reinforcement representing the most developed specification framework while thermal stability commands premium pricing in aerospace and defense rubber goods.
- Reinforcement:Primary filler function enabling tensile strength, tear resistance, and modulus development in S-SBR compounds through silica-rubber interfacial bonding.
- Abrasion Resistance:Critical for tire tread longevity and footwear soling durability, particularly in high-wear commercial vehicle and industrial safety applications.
- Thermal Stability:Fumed silica grades maintain compound integrity under sustained elevated temperatures in under-hood automotive components and conveyor belting.
- Modulus:Stiffness control in dynamic applications requiring precise deformation characteristics, including engine mounts and suspension bushings.
Reinforcement captures the greatest volume; Thermal Stability is climbing fastest in specialty specification growth.
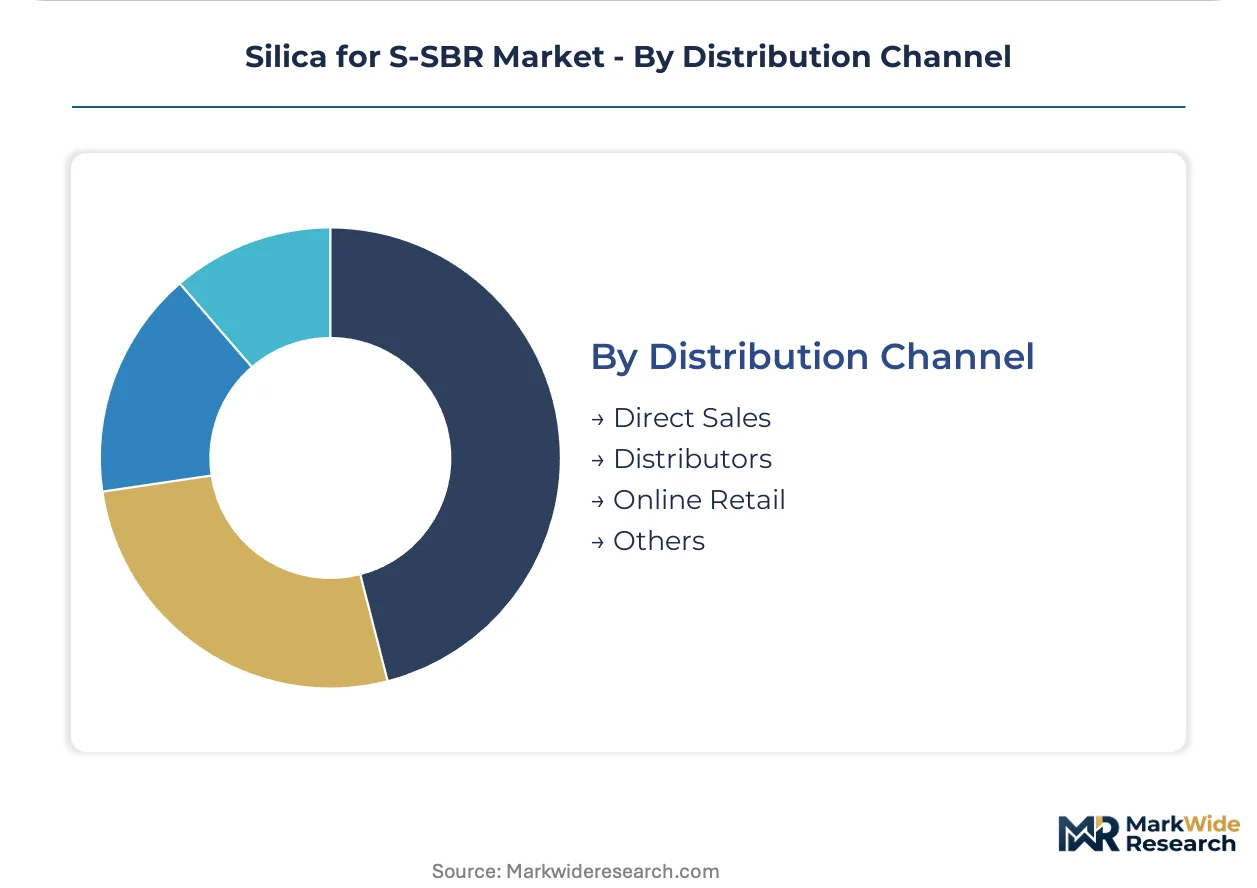
Distribution Channel:
Customer-type concentration drives channel selection, with multinational tire manufacturers favoring direct procurement while regional compounders and specialty formulators rely on distributor technical service capabilities.
- Direct Sales:Long-term supply agreements between integrated silica producers and Tier-1 tire manufacturers, incorporating collaborative tread formulation support and compound development partnerships.
- Distributors:Regional chemical distributors with in-house silane handling expertise and mixing technical service, serving mid-scale compounders lacking organosilane processing capabilities.
- Online Retail:Limited to standardized precipitated silica grades for small-batch industrial rubber goods producers and research compounders.
- Others:Agent-based procurement in emerging manufacturing clusters and consignment arrangements for high-volume tire retread operations.
Direct Sales maintains dominant share; Distributors are gaining share fastest among regional compounder networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and coastal China diverges sharply from fragmented supply in India and Southeast Asia, where compounders absorb margin compression from silane coupling agent imports and inconsistent batch quality.
Germany
EU tire labeling mandates and KBA vehicle certification protocols drive precipitated silica specifications for OE tire platforms. REACH authorization timelines from ECHA extend qualification cycles for novel organosilane chemistries by 18-24 months. Manufacturing clusters in North Rhine-Westphalia and Lower Saxony host integrated silica-tire supply chains serving premium automotive OEMs.
China
GB standards on tire fuel consumption and rolling resistance tighten specifications for silica-reinforced S-SBR compounds bound for domestic vehicle manufacturers. MIIT enforcement of dual carbon goals pressures coastal chemical corridors to upgrade emissions controls. Shandong and Jiangsu province processing facilities dominate precipitated silica output with captive sodium silicate supply.
United States
EPA emissions standards constrain silica manufacturing processes while NHTSA fuel economy regulations pull low-hysteresis tread compounds into light truck and passenger tire specifications. Southeast chemical corridors from Louisiana to South Carolina concentrate precipitated silica capacity with backward integration into sulfuric acid production.
India
Domestic OEMs in Chennai and Pune adopt EU-equivalent rolling resistance specifications, creating demand openings for precipitated silica suppliers with local technical service capabilities. BIS tire safety standards are converging with international fuel efficiency benchmarks. Western Maharashtra and Tamil Nadu manufacturing clusters lack integrated silane handling infrastructure, forcing reliance on pre-treated silica imports.
Japan
METI energy efficiency directives and JIS tire performance standards sustain premium positioning for surface-treated silica grades in high-performance tire segments. Kansai and Chubu industrial corridors host compound development partnerships between silica producers and tire manufacturers for 2026 OE platform launches.
Silica for S-SBR Market Competitive Landscape
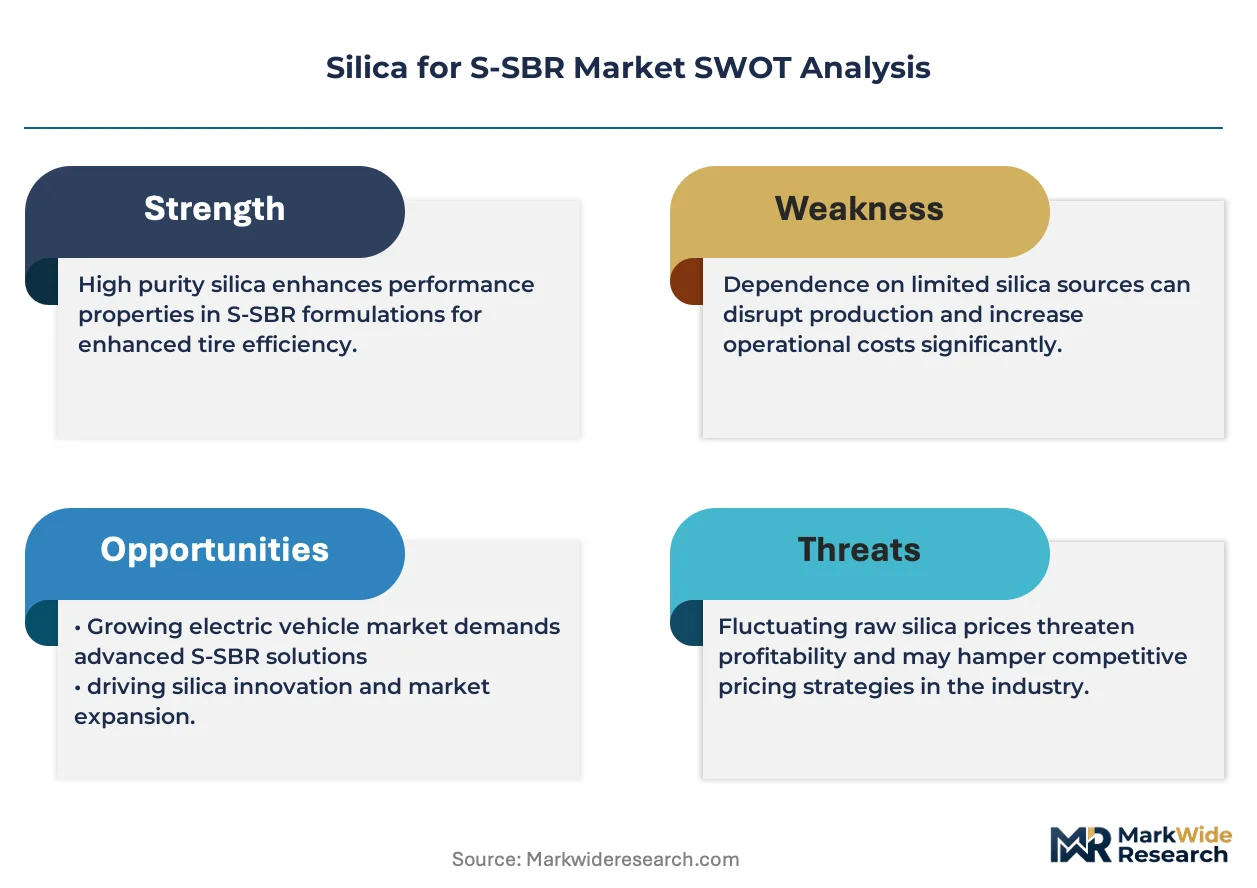
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates commanding formulation partnerships while regional compounders compete on logistics proximity. The supply base exhibits tiered concentration: three to four backward-integrated producers capture premium tire contracts, mid-scale specialists serve industrial rubber goods, and commodity traders fill spot demand in emerging clusters. Dominant archetypes include sodium silicate-integrated precipitated silica manufacturers, silane chemistry specialists, and distributor-anchored regional compounders. Competitive moves center on multi-year supply agreements with collaborative tread formulation support and captive acid supply investments that freeze out non-integrated entrants.
Among German chemical conglomerates, Evonik Industries AG and Wacker Chemie AG exemplify the integrated archetype with in-house control over sodium silicate and sulfuric acid supply chains. Solvay S.A. occupies a distinct positioning as a Belgium-based specialist in surface-treated grades. These three entities anchor the premium tier where tire OEMs audit technical service capabilities alongside material certificates, representing the competitive boundary that regional compounders struggle to cross without silane handling expertise.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Solvay S.A. |
| PPG Industries, Inc. |
| Wacker Chemie AG |
| Cabot Corporation |
| Tosoh Silica Corporation |
| Oriental Silicas Corporation |
| Quechen Silicon Chemical Co., Ltd. |
| Madhu Silica Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between integrated precipitated silica producers and Tier-1 tire manufacturers lock in supply access while anchoring price visibility across volatile sodium silicate and sulfuric acid input markets. These agreements compress working capital risk for buyers with captive silane handling infrastructure while freezing out regional compounders dependent on spot procurement.
Pricing Analysis
Configured-to-order pricing for surface-treated precipitated silica with silane pre-treatment commands spreads over standard commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects silane coupling agent sophistication, REACH dossier validity, and collaborative formulation support bundled into contracts. Pricing pressure stems from carbon black substitution economics in commercial vehicle segments where fuel efficiency mandates carry less weight. Regional compounders in India and Southeast Asia exhibit highest price sensitivity due to import-dependent silane logistics and working capital constraints.
Supply Chain Analysis
Sulfuric acid supply corridors from Louisiana to South Carolina and North Rhine-Westphalia chemical clusters constitute chokepoints that filter viable precipitated silica production to backward-integrated operators. Manufacturing gravity centers on Germany, China, and the United States where captive sodium silicate supply feeds coastal chemical complexes. Raw material dependencies span sulfuric acid, sodium silicate, and organosilane coupling agents sourced from specialty chemical manufacturers. Single-source vulnerability concentrates in silane chemistry supply where ECHA authorization timelines extend qualification cycles. Distribution runs through direct sales channels for multinational tire OEMs and distributor networks for regional compounders lacking in-house technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silica for S-SBR procurement is shifting toward platform-economics logic where tire OEMs specify interoperable surface-treated grades across multiple supplier qualified parts lists, decommodifying filler transactions into collaborative formulation partnerships.
For Market Incumbents: Compound backward integration into sodium silicate with silane chemistry R&D partnerships to defend margin capture against fumed silica displacement in premium tire segments. Lock in multi-year supply agreements with collaborative tread formulation support before ECHA authorization timelines freeze supplier lists. Prioritize capacity additions in Shandong and Jiangsu corridors to capture China's tightening GB standard enforcement. For New Entrants and Emerging Players: Lead with technical service capabilities in Chennai and Pune where domestic OEMs adopt EU-equivalent rolling resistance specifications but local silane handling infrastructure remains underdeveloped. Target pre-treated silica deliveries to mid-scale compounders deferring real-time rheology monitoring investments. Anchor go-to-market through distributor partnerships with existing organosilane expertise rather than direct tire OEM penetration. For Investors and Strategic Acquirers: Silane chemistry specialists with valid REACH dossiers and established tire manufacturer compound development partnerships represent the most defensible acquisition profile. Five-to-ten-year viability hinges on coupling agent innovation pipelines and regional carbon border adjustment positioning. Monitor ECHA substance evaluation protocol extensions as the signal for supplier list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive sulfuric acid supply insulates margin buffers against coastal chemical corridor cost volatility. |
| Silane Pre-Treatment Capacity | Advanced surface chemistry systems decompose the filler loading-viscosity trade-off for 2026 OE platforms. |
| REACH Dossier Investment | Valid ECHA documentation extends qualification cycles and freezes incumbent positions against new entrants. |
| Regional Technical Service Expansion | Localized compound development partnerships satisfy Tier-1 OEM audit requirements beyond material certificates. |
| Long-term Supply Agreements | Collaborative tread formulation support locks in procurement relationships ahead of specification-driven consolidation. |
Research Methodology
A spread of perspectives from tire manufacturer procurement directors, precipitated silica plant managers, silane chemistry R&D leads, and regional chemical distributors converged on the working assumptions driving segmentation forecasts. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings from integrated chemical conglomerates, and industry association reports from ACC and Cefic. Bottom-up volume modeling across product grades and end-use industries triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled span product type, end-use industry, functionality, and distribution channel across the projection horizon. CAGRs derived from elasticity analysis against tire OEM production schedules, fuel efficiency regulation enforcement trajectories, and substitution dynamics between precipitated and fumed silica grades. Forecast inputs incorporated rolling resistance coefficient mandates from EU tire labeling and China's GB standards, silane coupling agent innovation pipelines, and regional carbon border adjustment mechanisms.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of fuel efficiency mandates or accelerated carbon black substitution economics would require recalibration. Forecasts reflect documented assumptions regarding ECHA authorization timelines, MIIT dual carbon goal implementation, and tire manufacturer platform standardization decisions. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and coupling agent chemistry evolution reshape supplier qualification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Vulcanization Market
Rubber
FKM Elastomers Market
Rubber
Rubber Plated Hose Market
Rubber
Synthetic Rubber Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Gum Rosin Market
Rubber
EPDM Rubber Market
Rubber
Rubber Coatings Market
Rubber
Global Rubber Market
Rubber
Rubber Sand Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Global Cast Elastomers Market
Rubber
Cellular Rubber Market
Rubber
Polyacrylate Rubber Market
Rubber
US Nitrile Gloves Market
Rubber
Polyisoprene Market