
 Glass Alternative Materials Market | 2026-2036
Glass Alternative Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Alternative Materials Market Analysis
Aftermarket service revenue for polymer sheet refurbishment and optical coating reapplication is reshaping margin distribution across the value chain. Evonik Industries AG leverages its methacrylate chemistry platform to sustain premium positioning in high-performance acrylic systems. Covestro AG anchors polycarbonate supply for automotive glazing through backward integration into bisphenol-A feedstocks. Trinseo S.A. competes on cost-optimized extrusion grades targeting construction and signage applications.
Glass alternative materials encompass engineered polymers, mineral composites, and hybrid substrates that replicate or exceed silica-based transparency while reducing weight by 40-60 percent. Polycarbonate dominates structural glazing for its impact resistance and thermal formability, though acrylic leads optical clarity applications where UV stability and scratch resistance prove critical. PET sheet extrusion occupies the packaging segment with barrier-coated variants displacing glass in food and pharmaceutical containers. Composite laminates incorporating aramid or glass-fiber reinforcement are extending into ballistic and aerospace viewing applications where failure tolerance governs specification.
EPA regulations on volatile organic compound emissions from solvent-based coating processes are redirecting formulation investment toward waterborne and UV-curable systems. ECHA REACH restrictions on bisphenol-A migration are forcing polycarbonate suppliers to validate copolymer alternatives or secure authorization for continued use. OEMs and tier-one converters must monitor regulatory divergence between EU chemical hazard classifications and FDA food-contact approvals to avoid specification fragmentation across export markets.
Market Dynamics
Automotive electrification is compressing glazing weight targets, forcing polycarbonate and acrylic substitution at scale previously reserved for glass-only applications. Tier-one suppliers now coordinate directly with OEMs on thermal forming specifications that legacy glass converters cannot meet.
Growth Catalysts
- REACH and RoHS compliance tightening:European chemical hazard classifications are disqualifying conventional silica-based systems from medical device housings and food-contact applications, redirecting specification toward validated polymer alternatives.
- Electric vehicle production concentration:Assembly plants in China, Germany, and the United States are specifying lightweight transparent polymers for panoramic roof systems to offset battery pack mass.
- UV-curable coating chemistry:EPA emission limits on solvent-based processes are accelerating waterborne and radiation-cured formulation adoption across optical sheet finishing operations.
Market Restraints
- Bisphenol-A feedstock concentration:Polycarbonate supply chains depend on petrochemical complexes concentrated in the US Gulf Coast and Northeast Asia, exposing converters to aromatic price volatility and force majeure risk.
- Scratch resistance technical ceiling:Acrylic and polycarbonate surfaces require sacrificial hardcoat layers that degrade faster than glass, limiting replacement cycles in high-contact applications.
- ECHA authorization timelines:REACH restrictions on bisphenol-A migration are forcing suppliers to validate copolymer alternatives or secure continued-use exemptions, fragmenting specification across export markets.
Strategic Opportunities
- Ballistic and aerospace viewing:Composite laminates incorporating aramid reinforcement are penetrating defense and aviation applications where failure tolerance governs procurement, commanding premium pricing over conventional glazing.
- India construction signage:Cost-optimized extrusion grades face underpenetration in Indian commercial building and retail display sectors, presenting volume expansion potential for regional converters.
- EU Green Deal material circularity:Mechanical recycling mandates for post-industrial polymer scrap are incentivizing closed-loop sheet production systems that glass cannot replicate.
Industry Challenges
- Thermal forming technician scarcity:Complex curvature specifications for automotive glazing require skilled operators capable of managing stress distribution across polycarbonate sheets, with training pipelines failing to match OEM demand.
- Dual regulatory compliance:Suppliers must simultaneously satisfy FDA food-contact approvals and EU chemical hazard classifications, creating specification fragmentation that complicates inventory management.
- Hardcoat application capex:Plasma-enhanced chemical vapor deposition systems for scratch-resistant surface treatment require capital commitments that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Alternative Materials Market |
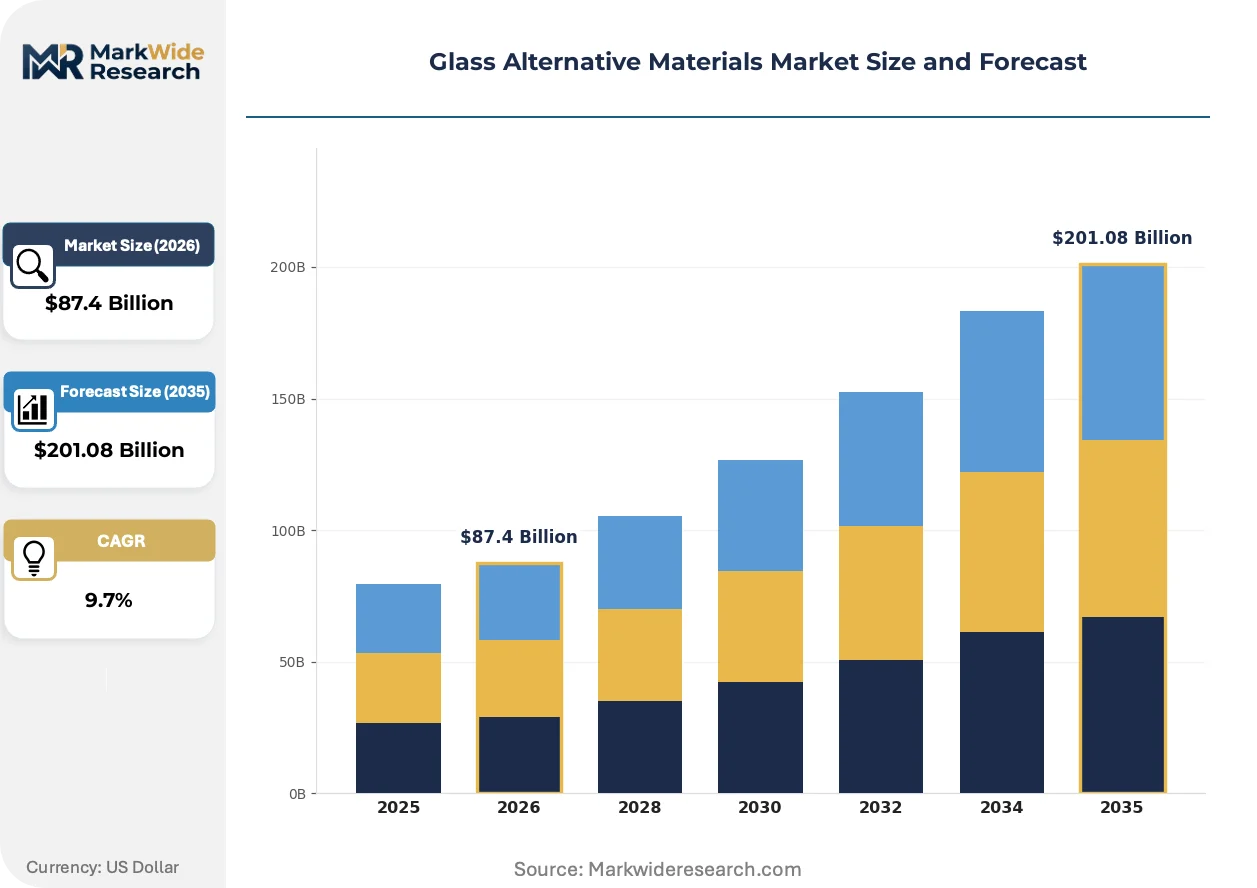
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $201.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Acrylic, PET, Composite Application: Construction, Automotive, Packaging, Electronics End User: OEMs, Retailers, Manufacturers, Distributors Technology: Extrusion, Injection Molding, Blow Molding, 3D Printing |
| Companies Covered | Evonik Industries AG, Lucite International, Covestro AG, Aristech Surfaces LLC, Arkema Group, Trinseo S.A., 3A Composites GmbH, Elastin International Corp, Mitsubishi Gas Chemical Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Alternative Materials Market Emerging Trajectories
Material science advances are collapsing the performance gap between engineered polymers and mineral glass, while regulatory pressure and procurement model evolution are rewriting how transparent substrates are specified, financed, and serviced across end-use verticals.
Multi-layer optical coating stacks are migrating from decorative automotive trim into functional head-up display combiners and LiDAR sensor windows. Tier-one electronics suppliers in South Korea and Japan are adopting these systems at compressed development cycles. The technology is migrating from aesthetic enhancement toward mission-critical photonics applications where refractive index precision determines system performance.
EPA volatile organic compound emission rules are redirecting formulation investment toward waterborne and UV-curable coating processes across North American sheet finishing operations. Industrial consequence includes accelerated capital deployment into electron beam curing lines and compressed solvent recovery infrastructure. Automotive glazing subcontractors in Michigan and Ohio are most affected, responding through consortium purchasing of shared curing capacity.
Fleet operators and leasing companies are unbundling polymer sheet refurbishment from original equipment procurement, treating optical clarity maintenance as a discrete service line. This behavior disrupts traditional distributor models that bundled material supply with installation warranty. The shift is most visible in German commercial vehicle glazing, where aftermarket service contracts now specify coating reapplication intervals independent of substrate replacement cycles.
Glass Alternative Materials Market Segmentation
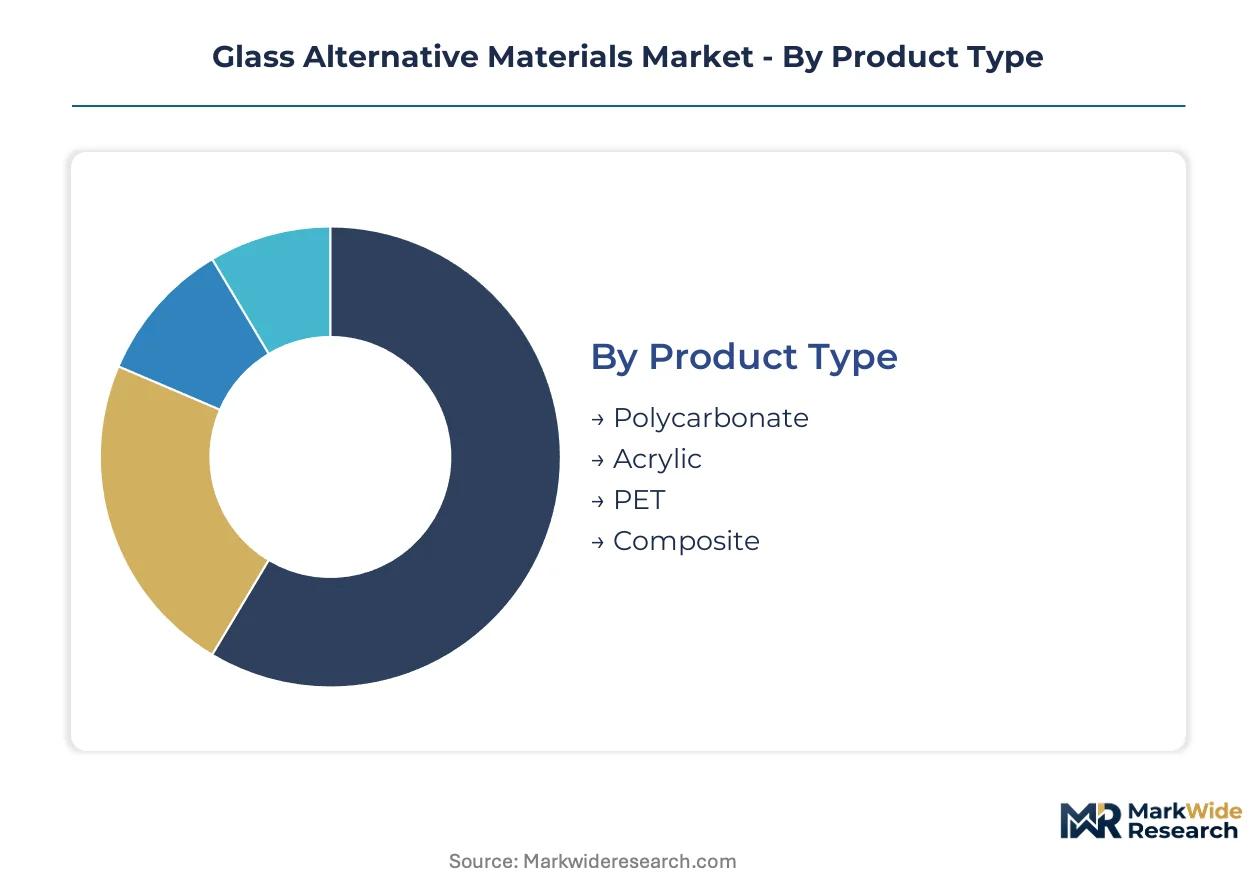
Segmentation in glass alternative materials exposes divergent service intensity across substrate types. Polycarbonate automotive glazing demands scheduled hardcoat refurbishment cycles that PET packaging never requires. These aftermarket dependencies reshape margin capture and customer lifetime value calculations for converters and distributors alike.
Product Type:
After-sales service intensity varies dramatically across polymer chemistries, with optical clarity maintenance contracts concentrating in acrylic and polycarbonate while PET operates on disposable replacement economics.
- Polycarbonate:High-impact thermoplastic with thermal formability enabling complex automotive glazing geometries. Demand concentrates in German and Chinese electric vehicle assembly plants where panoramic roof specifications offset battery pack mass. REACH authorization pressures on bisphenol-A feedstocks are forcing suppliers toward copolymer validation or exemption documentation.
- Acrylic:Methacrylate-based polymer delivering superior optical clarity and UV stability for premium applications. Demand clusters in South Korean and Japanese electronics suppliers adopting multi-layer optical coatings for head-up display combiners and LiDAR sensor windows. Sacrificial hardcoat degradation drives recurring refurbishment revenue streams.
- PET:Barrier-coated sheet extrusion displacing glass in food and pharmaceutical containers with single-use replacement economics. FDA food-contact compliance requirements dominate specification alongside EFSA migration limits for European export markets.
- Composite:Aramid or glass-fiber reinforced laminates penetrating ballistic and aerospace viewing applications where failure tolerance governs procurement. Defense procurement cycles in the United States and NATO member states command premium pricing over conventional glazing substrates.
Polycarbonate holds the largest share; momentum sits with composite laminates in defense and aviation verticals.
Application:
Cost tier stratification separates premium specification automotive and aerospace from volume-driven construction and packaging segments with divergent margin profiles.
- Construction:Cost-optimized extrusion grades for commercial building facades and retail signage. Indian commercial building sector presents underpenetration opportunity for regional converters seeking volume expansion.
- Automotive:OEM-specified polycarbonate and acrylic glazing for panoramic roof systems, head-up displays, and sensor windows. Thermal forming technician scarcity in Michigan and Ohio glazing subcontractors compresses capacity expansion timelines.
- Packaging:Barrier-coated PET sheet for food and pharmaceutical containers. EPA volatile organic compound emission rules redirect coating formulation investment toward waterborne and UV-curable systems across North American finishing operations.
- Electronics:Multi-layer optical coating stacks for photonics applications where refractive index precision determines system performance. South Korean and Japanese tier-one suppliers drive compressed development cycles for functional rather than decorative coating adoption.
Automotive commands premium pricing; packaging delivers volume scale with fastest margin compression.
End User:
Procurement authority concentration among OEMs and tier-one converters contrasts with fragmented distributor networks serving retail and construction channels.
- OEMs:Direct specification authority for automotive and electronics applications with coordinated thermal forming development. German commercial vehicle fleet operators now unbundle polymer sheet refurbishment from original equipment procurement.
- Retailers:Specification influence in construction signage and point-of-sale display applications with price-sensitive volume purchasing patterns.
- Manufacturers:Captive polymer processing for in-house glazing integration, particularly in Chinese electric vehicle battery pack enclosure production.
- Distributors:Traditional bundled supply-plus-installation warranty models disrupted by aftermarket service contracts specifying coating reapplication intervals independent of substrate replacement cycles.
OEMs concentrate specification authority; distributors face margin pressure from unbundled service models.
Technology:
Capital intensity and technical capability requirements stratify processing methods from high-volume extrusion to precision additive manufacturing.
- Extrusion:Dominant sheet production method for construction, signage, and packaging applications with continuous throughput economics. EU Green Deal mechanical recycling mandates incentivize closed-loop post-industrial scrap recovery systems.
- Injection Molding:Precision component fabrication for automotive interior glazing and electronics housings with complex geometry capability.
- Blow Molding:Hollow container production for pharmaceutical and food packaging with barrier coating integration requirements.
- 3D Printing:Emerging additive method for prototype and low-volume optical component fabrication with refractive index control limitations constraining functional adoption.
Extrusion anchors volume production; 3D printing offers fastest capability expansion for prototyping workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies: fleet operators in Germany absorb premium refurbishment contracts while Indian construction buyers drive hard on extrusion-grade unit economics. Buyers in China and the United States occupy intermediate positions, trading weight-reduction specifications against total cost of ownership.
China
Electric vehicle assembly plants in Shanghai and Shenzhen specify polycarbonate panoramic roof systems to offset battery pack mass. MIIT dual carbon goals accelerate lightweight material adoption in domestic OEM supply chains. Yangtze River Delta converters coordinate thermal forming specifications directly with BYD and NIO production schedules.
Germany
Commercial vehicle fleet operators in Munich and Stuttgart unbundle polymer sheet refurbishment from original equipment procurement. ECHA REACH restrictions on bisphenol-A migration force polycarbonate suppliers toward copolymer validation or exemption documentation. Baden-Württemberg glazing subcontractors face technician scarcity compressing capacity expansion timelines.
United States
EPA volatile organic compound emission rules redirect coating formulation investment toward waterborne and UV-curable systems across Michigan and Ohio sheet finishing operations. NHTSA glazing safety standards govern polycarbonate adoption for automotive applications. Detroit-area tier-one suppliers coordinate thermal forming development with Ford and GM electrification programs.
Japan
Tier-one electronics suppliers in Osaka and Nagoya adopt multi-layer optical coating stacks for head-up display combiners and LiDAR sensor windows. METI industrial standards govern refractive index precision for photonics applications. Kanto region fabricators compress development cycles under pressure from South Korean competitors.
India
Cost-optimized extrusion grades face underpenetration in Mumbai and Delhi commercial building facades and retail signage sectors. BIS standards for polymer sheet quality create compliance barriers for regional converters. Gujarat-based fabricators seek volume expansion through price-competitive positioning against Chinese imports.
Glass Alternative Materials Market Vendor Landscape
Capability concentration sits with integrated chemical platforms; scale advantage sits with diversified polymer converters. The vendor base stratifies between methacrylate chemistry specialists, polycarbonate resin producers, and extrusion-grade commodity suppliers. Three archetypes dominate: backward-integrated feedstock controllers, hardcoat application technology licensors, and regional extrusion specialists serving construction and signage. Competitive moves center on M&A for coating technology access and consortium purchasing of shared curing capacity among automotive glazing subcontractors.
Within the integrated chemical tier, Evonik Industries AG and Covestro AG exemplify contrasting strategic positions. Evonik leverages its methacrylate platform to sustain premium positioning in high-performance acrylic systems. Covestro anchors polycarbonate supply through captive bisphenol-A production, exposing its cost structure to aromatic feedstock volatility. Trinseo S.A. occupies a distinct position as a diversified polymer converter competing on cost-optimized extrusion grades. These three entities collectively illustrate how feedstock control, application technology, and regional manufacturing scale distribute competitive advantage across substrate types.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Lucite International |
| Covestro AG |
| Aristech Surfaces LLC |
| Arkema Group |
| Trinseo S.A. |
| 3A Composites GmbH |
| Elastin International Corp |
| Mitsubishi Gas Chemical Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion costs feed directly into polycarbonate sheet landed pricing across German automotive glazing contracts, amplifying the margin spread between captive-feedstock suppliers and merchant-market converters while compressing aftermarket refurbishment economics for independent distributors.
Pricing Analysis
Aftermarket refurbishment revenue tiers now command lifetime value premiums exceeding original substrate margins across German commercial vehicle glazing. Three-tier pricing structure across premium optical-grade acrylic, standard automotive polycarbonate, and economy extrusion-grade PET separates specification authority from volume purchasing power. Cost compression in economy extrusion grades is intensifying because Gujarat-based fabricators undercut Chinese import pricing. Fleet operators in Germany absorb premium refurbishment contracts; Indian construction buyers drive hardest on unit economics.
Supply Chain Analysis
Contract manufacturing concentration for optical coating application rests with Michigan and Ohio automotive glazing subcontractors operating shared electron beam curing consortiums. Bisphenol-A feedstock production anchors in the US Gulf Coast and Northeast Asia; methacrylate monomer supply clusters in Germany and Japan. Raw material dependencies include aromatic petrochemicals, UV stabilizer additives, and sacrificial hardcoat resins. Single-source vulnerability concentrates in bisphenol-A authorization timelines under ECHA REACH. Distribution runs through tier-one converter networks coordinating directly with OEM thermal forming specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass alternative materials are approaching a platform-economics inflection where coating-application technology interoperability determines supplier lock-in, with multi-layer optical stack standardization across South Korean and Japanese electronics ecosystems accelerating winner-take-most dynamics.
For Market Incumbents: Pre-empt copolymer validation investments before ECHA REACH bisphenol-A authorization deadlines fragment export market access. Secure captive hardcoat application capacity through plasma-enhanced chemical vapor deposition technology licensing or acquisition. Thermal forming technician training pipelines in Baden-Württemberg and Michigan represent the critical capacity constraint threatening volume commitments to electrifying OEMs.
For New Entrants and Emerging Players: Mumbai and Delhi commercial building facades present the most penetrable white-space for cost-optimized extrusion grades against Chinese import dominance. Indian retail signage sectors remain undersupplied by regional converters capable of BIS quality compliance. A price-competitive positioning through Gujarat-based manufacturing with direct distributor relationships bypasses legacy bundled warranty models.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded methacrylate or polycarbonate assets lacking coating-application integration. Long-term viability favors suppliers controlling both substrate chemistry and surface treatment technology across the analysis window. Monitor ECHA authorization grant rates for bisphenol-A copolymer alternatives as the inflection signal for incumbent restructuring urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A Feedstocks | Covestro's captive aromatic supply insulates polycarbonate margin from petrochemical volatility. |
| Hardcoat Application Technology Licensing | Plasma-enhanced CVD system access differentiates premium automotive glazing specifications. |
| Shared Curing Capacity Consortium | Michigan and Ohio subcontractors pool electron beam investment to meet EPA emission rules. |
| Copolymer Validation Investment | ECHA REACH authorization pressures force alternative chemistry development ahead of deadlines. |
| Closed-Loop Mechanical Recycling Systems | EU Green Deal mandates incentivize post-industrial scrap recovery that glass cannot replicate. |
Methodological Framework
Desk research of customs and trade flow databases, SEC 10-K chemical segment disclosures, and ECHA REACH authorization documentation preceded structured interviews with polycarbonate plant managers, automotive OEM procurement leads, thermal forming technicians, and aftermarket glazing distributors. Bottom-up modeling of substrate demand by end-use application triangulated against top-down chemical industry production capacity assessments. Primary fieldwork concentrated in German automotive supply clusters, Yangtze River Delta converter operations, and US Great Lakes finishing subcontractors.
Forecast assumptions held regulatory authorization timelines and electrification penetration curves within observed patterns across the projection horizon. Segmentation dimensions modeled include polymer chemistry tier, end-use application vertical, regional production hub concentration, and coating technology integration level. CAGRs derived from volume-demand buildups by segment cross-referenced against supplier capacity expansion announcements and feedstock investment cycles. Automotive glazing weight-reduction targets and electronics photonics adoption curves served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical platforms or accelerated ECHA bisphenol-A restrictions would shift outcomes beyond modeled ranges. Quarterly review of REACH authorization grant rates, Yangtze River Delta logistics indices, and German fleet operator refurbishment contract volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Pharmaceutical Glass Tubing Market
Glass
North America Industrial Silica Sand Market
Glass
Glazing Gel Market
Glass
Middle East and Africa Glassware Market
Glass
Screen-Printing Glass Market
Glass
Glass Insulator Market
Glass
East Africa Flat Glass Market
Glass
Metallic Glass Market
Glass
Shatterproof Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
China Flat Glass Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Glass Balustrade Lamination Market
Glass
Silica Market
Glass
North America and Australia Silica Market
Glass
Global Anti-Reflective Glass Market