
 Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market | 2026-2036
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market Insights
Specialized polymer chemists fluent in fluorosilicone synthesis is reorganizing how additive suppliers allocate technical talent across R&D centers. Dow leverages its integrated silicone backbone capabilities to dominate high-purity automotive grades. BASF competes through backward integration into fluoropolymer intermediates, sustaining cost advantages in optical lens applications. Evonik differentiates via proprietary emulsion technologies that anchor its position in electronic screen treatments.
Anti-smudge and anti-streak additives for glass cleaners comprise surface-active chemistries—typically organosiloxanes, perfluorinated polymers, or amphiphilic surfactants at 0.1–5.0 wt% loading—that reduce surface energy below 20 mN/m to prevent fingerprint adhesion and water spotting on transparent substrates. Their primary commercial purpose is extending visual clarity intervals between cleanings on high-touch or exposed glass surfaces. Silicone-based formulations occupy the largest volume share due to cost-performance balance in architectural glass maintenance, while fluoropolymer-based grades command premium positioning in automotive and optical applications where durability thresholds exceed ten thousand wipe cycles. Surfactant-based systems lead in ready-to-use consumer products where formulators prioritize water solubility and biodegradability compliance.
EPA VOC regulations under the Clean Air Act constrain solvent-borne delivery forms in the United States, compelling shifts toward water-based emulsions and low-VOC liquid concentrates. REACH registration requirements and the EU Green Deal chemical sustainability targets in Europe mandate full substance dossiers for fluorinated chemistries, elevating compliance costs for importers. FDA indirect food contact standards influence additive selection for glassware used in commercial food service. Stakeholders must monitor pending restrictions on per- and polyfluoroalkyl substances, as regulatory reclassification would force rapid reformulation across automotive and electronics supply chains.
Market Dynamics
REACH compliance deadlines and EPA VOC enforcement are compressing formulation timelines across automotive and electronics supply chains, forcing additive suppliers to accelerate silicone-fluoropolymer hybrid development cycles.
Growth Catalysts
- Automotive OEM Specifications:Electric vehicle manufacturers in Germany mandate premium glass treatment chemistries with durability exceeding ten thousand wipe cycles, creating specification-driven demand for fluoropolymer-based grades.
- REACH Registration Mandates:ECHA substance dossier requirements for fluorinated chemistries are consolidating supplier bases toward compliant European producers with established registration portfolios.
- Electronic Screen Treatments:Proprietary emulsion technologies for smartphone and tablet displays anchor demand for amphiphilic surfactant systems in consumer electronics manufacturing clusters.
Market Restraints
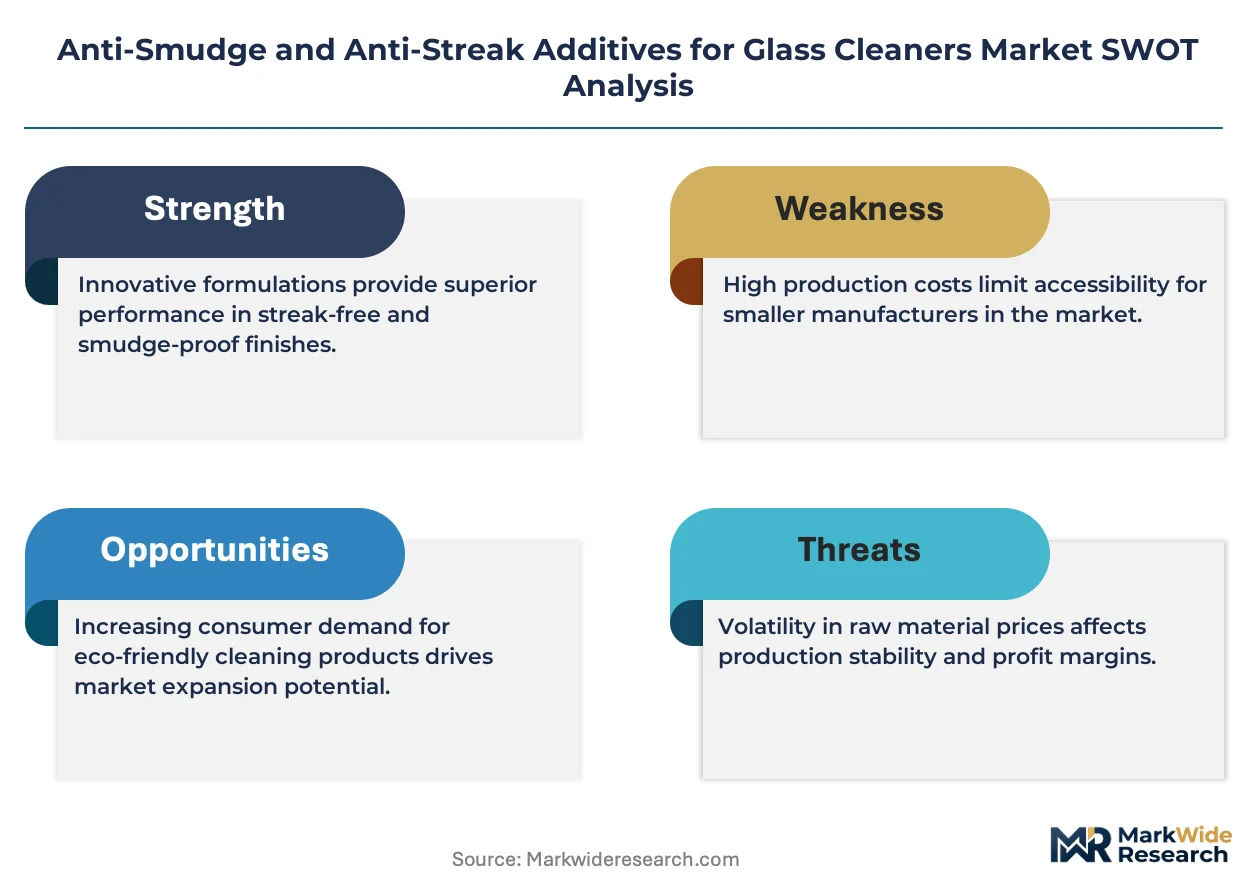
- Fluoropolymer Feedstock Concentration:Backward integration into perfluorinated intermediates concentrates among three chemical conglomerates, creating supply vulnerability for non-integrated formulators.
- PFAS Regulatory Reclassification Risk:Pending restrictions on per- and polyfluoroalkyl substances under EPA and ECHA review threaten rapid obsolescence of automotive-grade additive portfolios.
- Silicone Raw Material Volatility:Organosiloxane precursor costs fluctuate with energy-intensive chlorosilane production economics, compressing margins for architectural glass maintenance formulations.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for display and semiconductor fabrication create untapped demand for electronic screen treatment chemistries in Noida and Chennai clusters.
- Water-Based Emulsion Convergence:Low-VOC liquid concentrate technology married with biodegradable surfactant systems opens food service glassware applications under FDA indirect contact standards.
- Optical Lens Aftermarket Channel:Direct-to-procurement platforms for ophthalmic and photographic lens maintenance bypass traditional chemical distributor markups in Japan and South Korea.
Industry Challenges
- Fluorosilicone Synthesis Talent Scarcity:Specialized polymer chemists command premium compensation across R&D centers, constraining formulation innovation velocity for mid-tier additive suppliers.
- Dual Certification Timeline Compression:Simultaneous EPA Safer Choice and EU Ecolabel approvals require eighteen-to-twenty-four-month validation cycles, delaying product launches in regulated consumer segments.
- Legacy Solvent System Integration:Water-based emulsion retrofitting into existing automotive windshield washer fluid production lines demands capital-intensive equipment reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market |
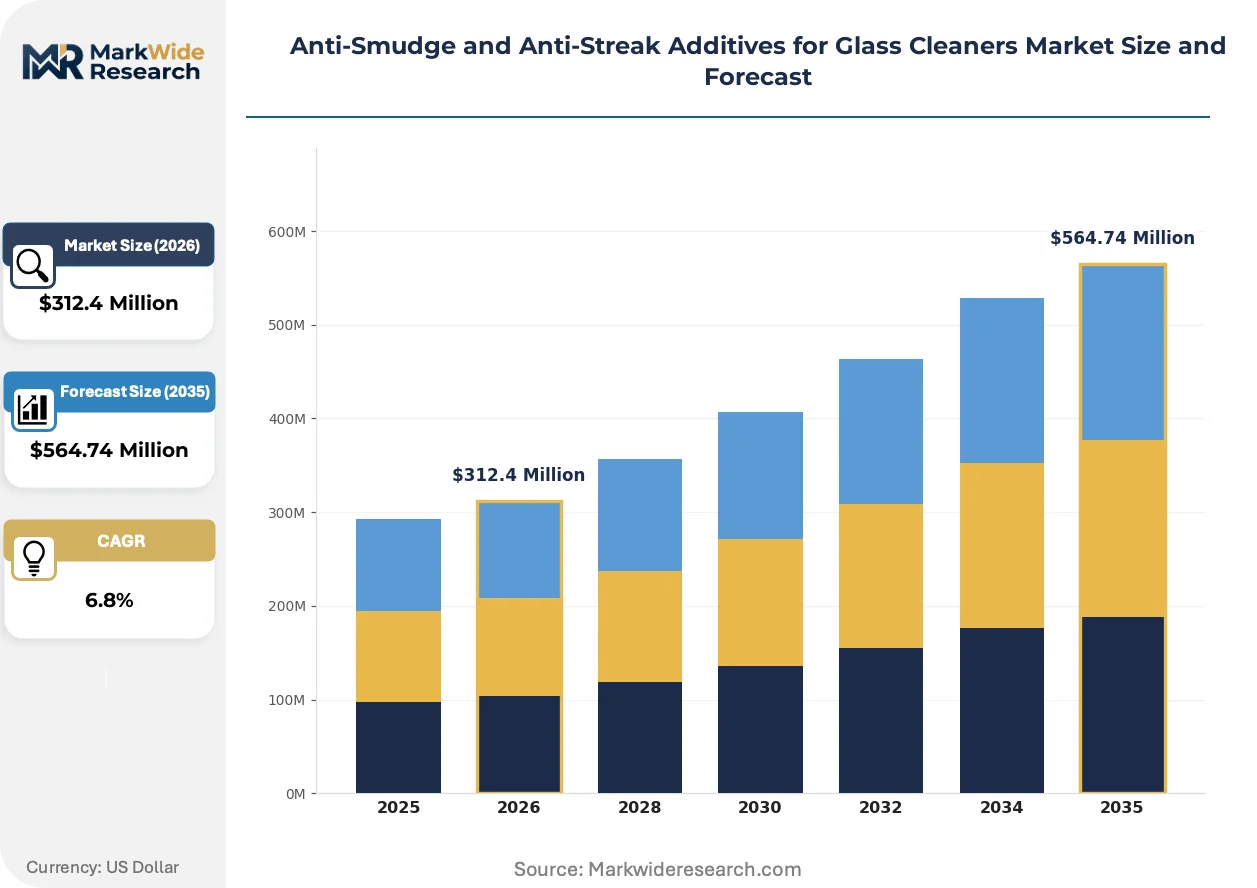
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Fluoropolymer-Based, Polymer-Based, Surfactant-Based, Nonionic, Cationic Application: Automobile Windshields, Optical Lenses, Solar Panels, Electronic Screens, Architectural Glass, Eyewear End User: Vehicle Manufacturers, Electronics Assemblers, Solar Energy Firms, Commercial Construction, Eyewear Producers, Industrial Cleaners Delivery Form: Liquid Concentrate, Powder, Emulsion, Aerosol Spray, Gel, Ready-to-Use |
| Companies Covered | Dow, BASF, Nouryon, Evonik, Clariant, Huntsman, Stepan Company, Kao Chemicals, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market Trends and Innovations
Formulation chemistry is pivoting toward hybrid silicone-fluoropolymer architectures that balance cost-performance with regulatory survivability. Three convergent developments are compressing traditional technology adoption curves.
Fluorosilicone copolymer additives are miniaturizing molecular weight distributions to achieve sub-20 mN/m surface energy at reduced loading rates. Automotive OEMs in Germany and Japan specify these grades for electric vehicle windshields. The technology is miniaturizing equipment footprint requirements for in-line glass treatment application systems.
EPA VOC regulations under the Clean Air Act now mandate maximum 3% solvent content for consumer glass cleaning products. Formulators respond with water-based emulsion concentrates that sacrifice shelf stability for compliance. Automotive aftermarket channels in California and Texas face the steepest product line transition costs.
Certification-driven procurement now dominates commercial food service glassware purchasing. Buyers prioritize EPA Safer Choice and EU Ecolabel credentials over unit cost in contract negotiations. This preference shift concentrates demand among additive suppliers with established sustainability certification portfolios in North American and European institutional channels.
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market Segmentation
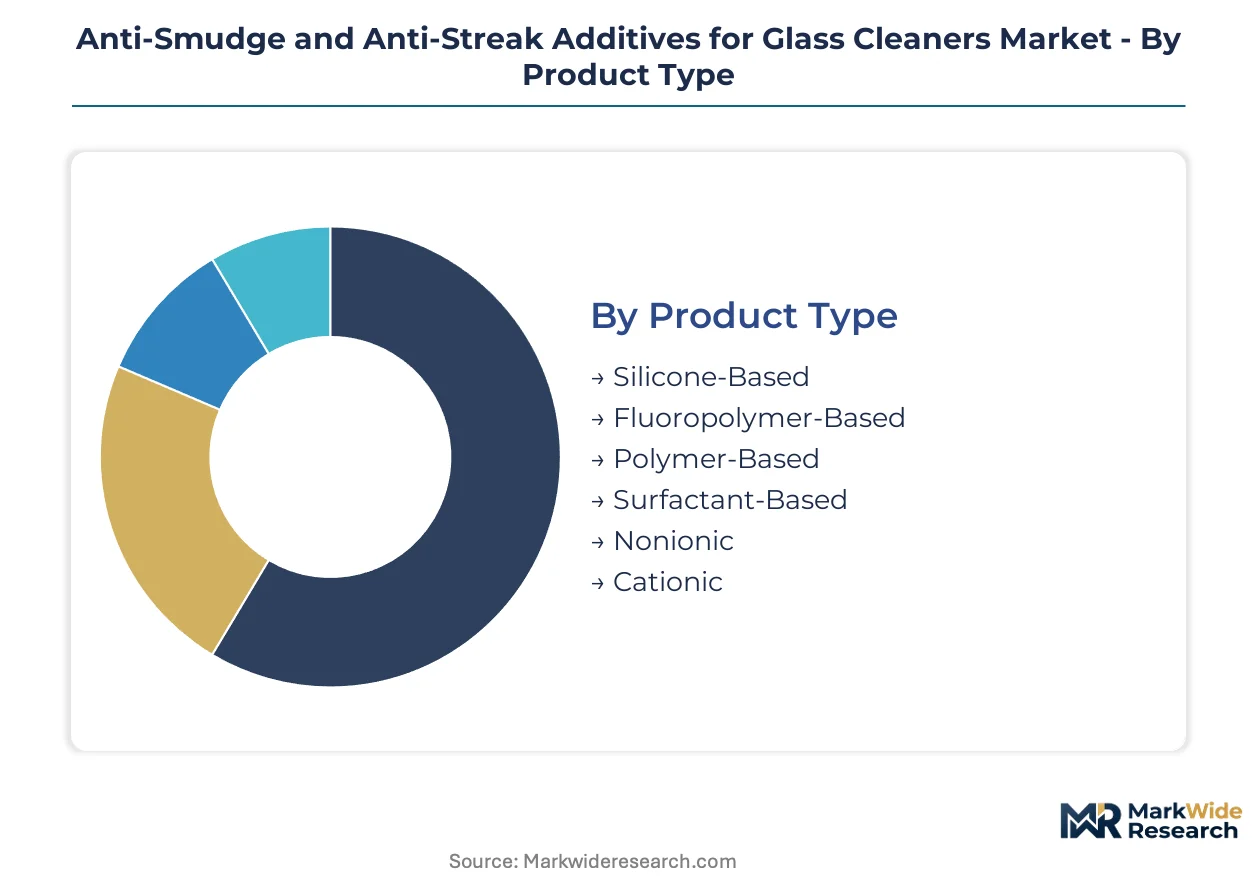
Formulation chemistries diverge sharply across end-use durability requirements and regulatory compliance thresholds. Each segment category reflects distinct supply chain configurations, from captive automotive supply to distributed consumer channels.
Product Type:
Geographic demand patterns split between domestic formulation in regulated markets and export-led supply from integrated chemical hubs.
- Silicone-Based:Organosiloxane backbone chemistries dominate architectural glass maintenance through cost-performance balance. Demand concentrates in Germany and Japan where building maintenance contractors specify water-based emulsion formats under REACH and local VOC limits. Silicone raw material volatility with chlorosilane production economics compresses margins for non-integrated suppliers.
- Fluoropolymer-Based:Perfluorinated polymer architectures achieve sub-20 mN/m surface energy with durability exceeding ten thousand wipe cycles. German electric vehicle OEMs mandate these grades for windshield specifications, creating specification-locked demand. EPA and ECHA reviews of PFAS classification threaten portfolio obsolescence.
- Polymer-Based:Acrylic and polyurethane variants serve mid-tier optical lens applications in Japan and South Korea.
- Surfactant-Based:Amphiphilic systems lead ready-to-use consumer products where biodegradability compliance drives selection in EU and US retail channels.
- Nonionic:Ethoxylated alcohol structures dominate food service glassware under FDA indirect contact standards.
- Cationic:Quaternary ammonium formulations find niche industrial cleaner applications with antimicrobial claims.
Silicone-based grades command the established base. The steepest expansion runs through fluoropolymer-based segments.
Application:
Cost tier stratification separates specification-driven automotive and optical segments from price-sensitive architectural and consumer applications.
- Automobile Windshields:Electric vehicle manufacturers in Germany and Japan specify premium treatment chemistries with durability validation protocols. OEM procurement concentrates among backward-integrated additive suppliers with established automotive certification. California EPA VOC enforcement accelerates water-based emulsion adoption in aftermarket channels.
- Electronic Screens:Smartphone and tablet display manufacturing in Noida and Chennai clusters under India's PLI scheme drives demand for proprietary emulsion technologies. Proprietary emulsion technologies anchor supplier positions in this segment. Touchscreen density specifications exceed ten thousand activation cycles without clarity degradation.
- Optical Lenses:Ophthalmic and photographic lens maintenance in Japan and South Korea favors direct-to-procurement platform distribution.
- Solar Panels:Utility-scale installations in California and Texas specify anti-soiling coatings for efficiency maintenance.
- Architectural Glass:Commercial building maintenance contracts in Germany prioritize EPA Safer Choice and EU Ecolabel credentials.
- Eyewear:Premium sunglass and prescription lens brands in Italy and France specify oleophobic treatments.
Automobile windshields anchor volume concentration. Electronic screens are climbing the fastest.
End User:
Customer type determines procurement modality, from captive supply agreements with vehicle manufacturers to spot purchasing by industrial cleaners.
- Vehicle Manufacturers:German automotive OEMs specify glass treatment chemistries through tiered supplier qualification programs. Electric vehicle production mandates drive fluoropolymer-based grade adoption with durability thresholds exceeding ten thousand wipe cycles. Procurement teams enforce REACH registration documentation and PFAS substance dossier compliance.
- Electronics Assemblers:Display panel manufacturers in Noida and Chennai clusters source electronic screen treatment chemistries under India's PLI scheme incentives. Proprietary emulsion technologies differentiate qualified suppliers. Cleanroom application requirements constrain approved vendor lists.
- Solar Energy Firms:Utility-scale developers in California and Texas specify anti-soiling additive packages for panel efficiency maintenance.
- Commercial Construction:Facility management contractors in Germany prioritize certified sustainable formulations.
- Eyewear Producers:Italian and French luxury brands specify premium oleophobic treatments for lens durability.
- Industrial Cleaners:Contract cleaning operations purchase surfactant-based concentrates through chemical distributor networks.
Vehicle manufacturers dominate specification-driven demand. Electronics assemblers show the steepest procurement acceleration.
Delivery Form:
Supply concentration in water-based emulsion technology reflects regulatory pressure on solvent-borne alternatives.
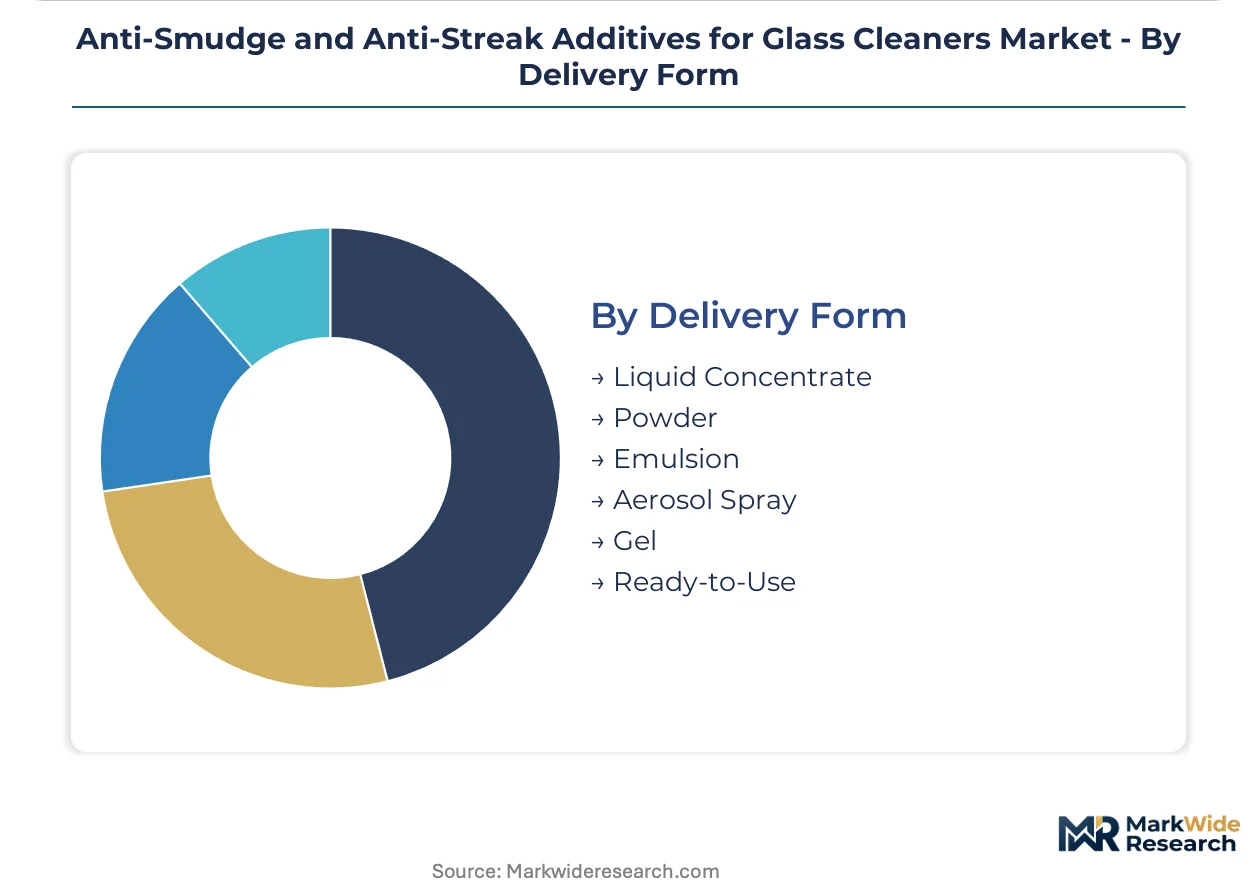
- Liquid Concentrate:Low-VOC formulations serve commercial and industrial dilution systems under EPA Clean Air Act limits. California and Texas aftermarket channels face steepest product line transition costs. Concentrate economics favor high-volume architectural glass maintenance contracts.
- Emulsion:Water-based delivery dominates automotive OEM specifications and electronic screen treatments. Proprietary emulsion technologies anchor supplier competitive positions. Shelf stability trade-offs against VOC compliance compress formulation margins.
- Ready-to-Use:Consumer retail formats prioritize biodegradability certification for EU Ecolabel and EPA Safer Choice positioning.
- Aerosol Spray:Propellant-based formats face regulatory pressure from volatile organic compound restrictions.
- Powder:Solid concentrate formats serve specialized industrial cleaning applications with shipping cost advantages.
- Gel:Viscous formulations target vertical surface applications in architectural maintenance.
Liquid concentrate holds the volume base. Emulsion formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fluoropolymer-based additives at specification-grade purity for automotive OEMs, while India sources surfactant-based systems for electronics manufacturing under cost-optimized procurement models. This consumption-mix differential separates premium durability markets from volume-scale emerging economies.
United States
California and Texas anchor automotive aftermarket demand as EPA VOC enforcement under the Clean Air Act mandates maximum 3% solvent content in consumer glass cleaners. The EPA's Safer Choice program drives procurement shifts toward biodegradable surfactant systems in commercial food service channels. Dallas-Fort Worth industrial clusters concentrate water-based emulsion production for architectural glass maintenance contracts.
Germany
Electric vehicle manufacturers in Stuttgart and Munich specify fluoropolymer-based grades with durability exceeding ten thousand wipe cycles, creating specification-locked demand for premium additives. REACH registration mandates from ECHA consolidate supplier bases toward compliant European producers with established substance dossiers. The Ruhr Valley chemical corridor hosts backward-integrated additive production serving automotive OEM qualification programs.
Japan
Ophthalmic and photographic lens manufacturers in Osaka and Nagoya favor direct-to-procurement platform distribution for optical-grade treatments. METI industrial standards influence additive selection for electronic display manufacturing in the Kanto region. Yokohama-based formulation specialists serve the premium eyewear aftermarket with oleophobic coating systems.
India
Display panel manufacturers in Noida and Chennai clusters source electronic screen treatment chemistries under the PLI scheme incentives for semiconductor fabrication. The country's national chemical regulator enforces import compliance documentation for fluorinated chemistries entering specialty applications. Bangalore electronics assemblers validate touchscreen density specifications exceeding ten thousand activation cycles without clarity degradation.
South Korea
Seoul Capital Area electronics manufacturers procure proprietary emulsion technologies for smartphone and tablet display treatments under cleanroom application requirements. The Korean national standards body certifies surface energy performance thresholds for optical lens coatings. Busan-Ulsan chemical complexes supply mid-tier surfactant concentrates for regional consumer product formulators.
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting raw material access and regulatory compliance capabilities rather than scale alone. The integrated tier commands automotive OEM specifications through captive supply of perfluorinated intermediates and silicone backbone chemistries. Specialist competitors cluster around proprietary emulsion technologies and biodegradable surfactant systems. Dominant competitive moves include backward integration into fluoropolymer feedstocks and acceleration of dual EPA-EU sustainability certification timelines.
Within the integrated chemical conglomerate tier, Dow and BASF exemplify divergent strategic positions. Dow leverages its Midland, Michigan-based silicone backbone capabilities to anchor high-purity automotive grade supply relationships. BASF represents European backward integration into fluoropolymer intermediates, sustaining cost position in specification-driven optical applications. Evonik occupies a specialist position through proprietary emulsion technology development for electronic screen treatment segments. These three entities collectively illustrate how raw material access and application-specific formulation expertise partition competitive advantage across end-use verticals.
| Leading Market Players |
|---|
| Dow |
| BASF |
| Nouryon |
| Evonik |
| Clariant |
| Huntsman |
| Stepan Company |
| Kao Chemicals |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
EPA Safer Choice certification gates both supplier qualification and price differentiation simultaneously, bifurcating additive procurement between certified premium tiers and uncertified commodity alternatives. German automotive OEMs enforce REACH documentation as a non-negotiable entry ticket, concentrating pricing power among compliant European producers while compressing margins for non-registered importers.
Pricing Analysis
Long-term offtake contracts dominate automotive OEM supply relationships, locking fluoropolymer-based grades at specification-grade premiums. Pricing stratifies across premium, standard, and economy tiers based on durability validation cycles and REACH registration status. Cost compression in surfactant-based architectural segments intensifies due to silicone raw material volatility. Spot purchasing industrial cleaners exhibit highest price sensitivity; German electric vehicle manufacturers show lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Chlorosilane precursor production in the Ruhr Valley underwrites European silicone backbone supply for high-purity automotive grades. Backward integration into perfluorinated intermediates centers on Germany, China, and the United States. Tariff exposure on fluoropolymer feedstock imports from China threatens non-integrated formulators. Distribution runs through tiered chemical distributor networks for industrial cleaners; direct-to-procurement platforms serve Japanese optical lens manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between automotive OEM specification systems and electronics cleanroom standards is creating platform-economics dynamics, where additive suppliers qualifying for both ecosystems capture disproportionate procurement volume.
For Market Incumbents: Shield specification-grade positions by accelerating dual EPA-EU certification timelines before PFAS reclassification deadlines. Deepen captive supply of fluorosilicone intermediates through Ruhr Valley capacity expansion to offset feedstock concentration risk from Chinese import dependence. For New Entrants and Emerging Players: Aftermarket water-based emulsion retrofit services for California automotive channels represent underserved white space. Target mid-tier optical lens distributors in South Korea through direct-to-procurement platform partnerships, bypassing established chemical distributor markups. For Investors and Strategic Acquirers: ECHA PFAS substance dossier deadlines reshape the acquisition landscape toward European-registered specialty chemical assets with established automotive OEM relationships. Long-term viability hinges on regulatory survivability across the analysis window. Prioritize targets with proprietary emulsion technology portfolios. Watch EPA Safer Choice approval velocity as inflection indicator for institutional channel penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Intermediates | BASF's Ruhr Valley production secures cost position in specification-driven optical applications. |
| Dual Certification Investment | Simultaneous EPA Safer Choice and EU Ecolabel approvals unlock institutional food service procurement. |
| Proprietary Emulsion Technology Development | Evonik's cleanroom-qualified systems anchor supplier positions in Noida electronics clusters. |
| Long-term Supply Agreement with Automotive OEMs | German electric vehicle manufacturers lock fluoropolymer-grade volumes through tiered qualification programs. |
| Water-Based Emulsion Capacity Expansion | Dow's Midland facilities serve California EPA VOC enforcement with low-solvent concentrate production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance dossiers, EPA enforcement actions, and automotive OEM procurement databases. Technical R&D directors at fluorosilicone synthesis facilities, procurement leads at German electric vehicle manufacturers, distribution channel partners in South Korean optical markets, and regulatory affairs specialists at additive suppliers provided structured input. Customs and trade data, SEC chemical segment disclosures, and REACH registration portfolios furnished secondary validation. Bottom-up segment sizing triangulates against top-down industry expenditure analysis.
Segmentation dimensions modeled include formulation chemistry type, application durability tier, delivery form compliance category, and regional regulatory cluster. Value projections across the analysis window derive from price-volume elasticity functions calibrated to OEM specification adoption curves. CAGRs incorporate fluoropolymer feedstock cost trajectories and certification-driven procurement shift velocities.
Underlying assumptions cover REACH registration maintenance, EPA VOC limit stability, and PFAS classification status, with deviation risk concentrated in regulatory reclassification events. Revision becomes warranted when ECHA substance dossier rejection rates or EPA enforcement intensity cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Solar Reflective Glass Market
Glass
Float Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Latin America Flat Glass Market
Glass
Optical Lens Material Market
Glass
Glass Grade Dolomite Market
Glass
Glass Tableware Market
Glass
Screen-Printing Glass Market
Glass
Fiberglass Window Market
Glass
North America Architectural Flat Glass Market
Glass
United States Flat Glass Market
Glass
Cellular Glass Market
Glass
Solar PV Glass Market
Glass
Low-E Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Alternative Materials Market