
 Shatterproof Glass Market | 2026-2036
Shatterproof Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Shatterproof Glass Market Intelligence
Vehicle manufacturers are unwinding historical reliance on standard tempered solutions in favor of laminated configurations for panoramic roofs and HUD-compatible windshields. Saint Gobain leverages its European float glass network to anchor supply for premium automotive programs. Guardian Glass competes through heat-treatment capacity positioned near Detroit and Stuttgart assembly corridors. Fuyao Glass Industry Group Co., Ltd. dominates replacement windshields in North America while extending chemical strengthening expertise into display cover glass.
Shatterproof glass encompasses laminated, tempered, coated, and annealed variants engineered to retain structural integrity under impact, thermal stress, or blast loading, typically incorporating interlayers of polyvinyl butyral or ion-exchanged surface compression layers exceeding 750 MPa. The primary purpose spans occupant retention in automotive crashes, forced-entry resistance in commercial architecture, and fragmentation control in electronic devices. Laminated glass leads building facade applications where post-breakage adhesion satisfies security and fall-protection requirements, while ion exchange technology claims the fastest expansion in smartphone and tablet cover glass where thickness below one millimeter must survive drop testing. Tempered glass occupies mature volume pools in side-lite automotive and standard architectural glazing where cost sensitivity overrides premium performance specifications.
Automotive safety regulators including NHTSA in the United States and the EU's UNECE R43 framework mandate head-impact and penetration resistance standards that effectively require laminated or tempered constructions for forward and side glazing positions. Construction codes under ICC and national building departments in Germany, Japan, and Australia specify shatterproof performance for overhead glazing and human-impact zones, creating specification pull through architect and contractor channels. Stakeholders must monitor evolving e-mobility platform architectures where battery pack protection and weight minimization create tension between glass thickness reduction and structural duty requirements.
Market Dynamics
Automotive electrification is compressing windshield specifications toward thinner laminates that preserve head-impact performance while reducing curb weight for battery range optimization. This structural pull is reshaping interlayer chemistry and tempering line investments across float glass networks.
Growth Catalysts
- UNECE R43 penetration mandates:European regulators now require laminated constructions for panoramic roof segments, forcing platform redesigns across premium and mass-market vehicle lines.
- HUD-compatible windshields:Head-up display proliferation in electric vehicles demands wedge-shaped interlayers that maintain optical clarity across curved geometries.
- F-Gas Regulation thermal standards:Building envelope performance requirements in the EU are accelerating vacuum-insulated glass adoption for facade retrofits.
Market Restraints
- PVB resin cost volatility:Petrochemical feedstock fluctuations compress margin predictability for laminated glass processors.
- Float glass furnace concentration:Capacity clusters in China's coastal provinces create single-source dependency risks for European automotive programs.
- Ion exchange throughput limits:Chemical strengthening batch processing constrains cover glass supply for tablet and foldable device launches.
Strategic Opportunities
- India's commercial building codes:BIS safety glazing mandates for high-rise construction create specification pull in underpenetrated metropolitan markets.
- Photovoltaic-integrated facades:Building-integrated solar glass convergence opens architectural specification channels beyond traditional glazing contractors.
- Direct OEM contracting:Automotive glass suppliers are bypassing tiered distribution to capture program engineering fees and lifecycle service revenue.
Industry Challenges
- Interlayer optical engineers:Shortage of specialists who can calibrate wedge-angle tolerances for HUD compatibility at production scale.
- UNECE R43 homologation timelines:Extended certification cycles for new windshield geometries delay platform launch windows.
- Float-to-laminate line reconfiguration:Capital intensity of converting tempering capacity to laminated processing strains mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shatterproof Glass Market |
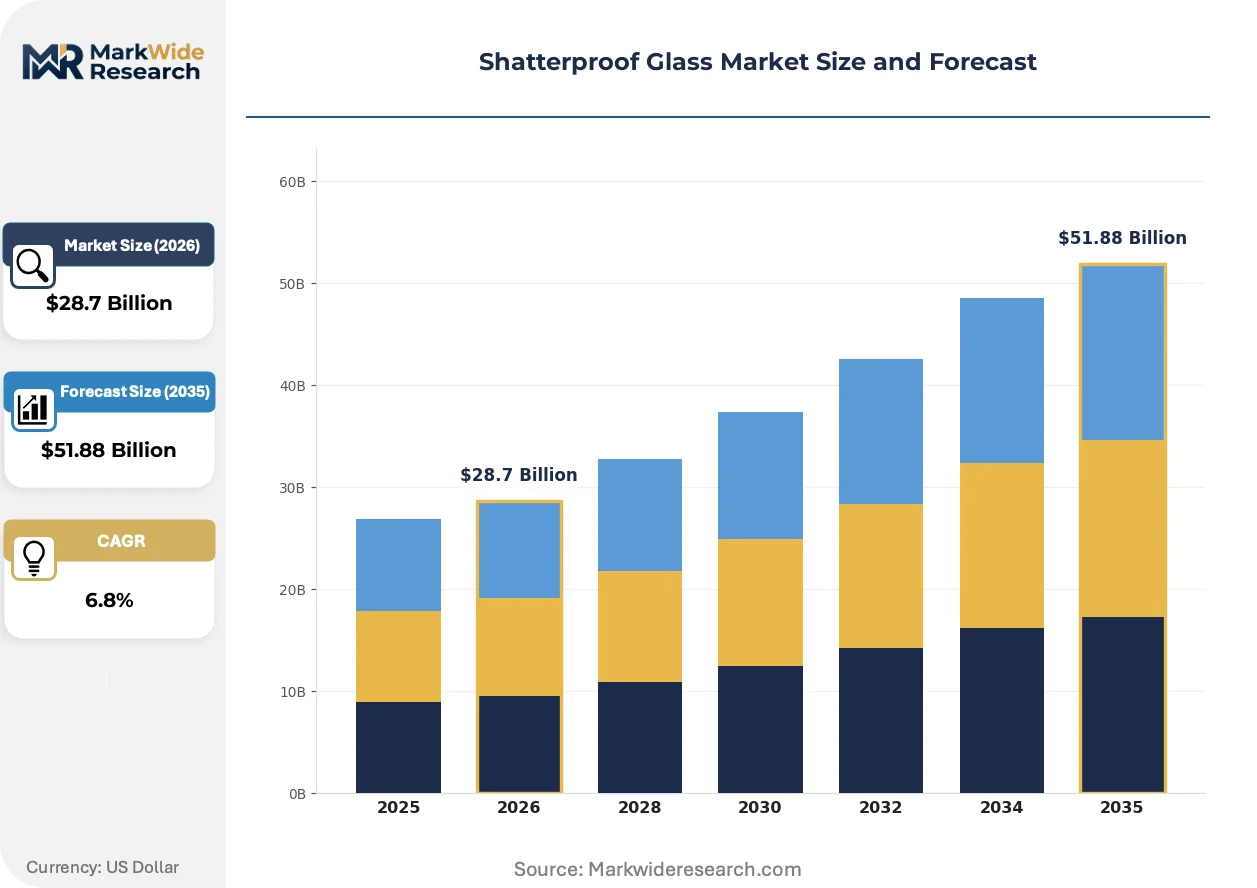
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
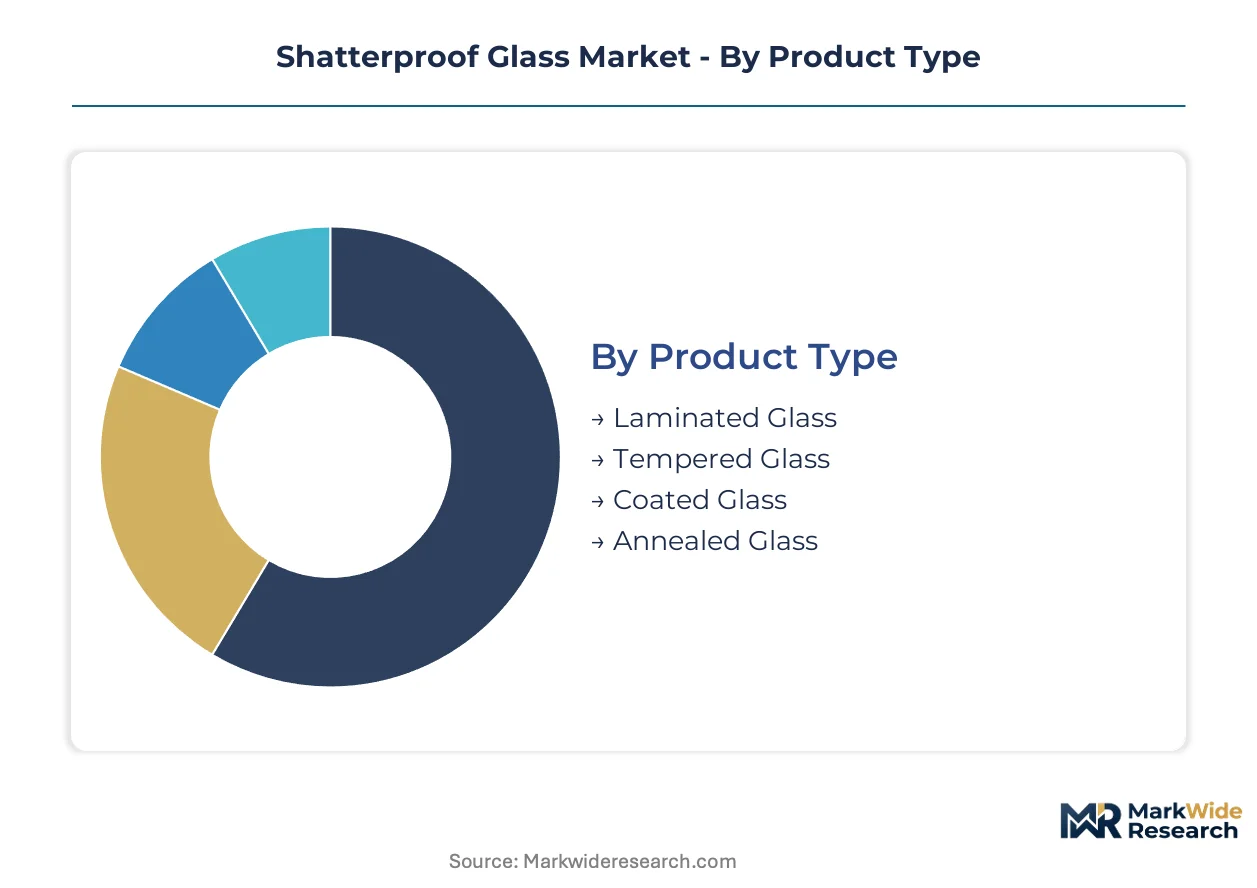
| Segmentation | Product Type: Laminated Glass, Tempered Glass, Coated Glass, Annealed Glass Application: Automotive Windshields, Building Facades, Skylights, Display Screens, Security Barriers End User: Vehicle Manufacturers, Construction Companies, Electronics Producers, Security Firms Technology: Heat Treatment, Chemical Strengthening, Ion Exchange, Coating Technology |
| Companies Covered | Saint Gobain, Cardinal Glass Industries, Guardian Glass, Fuyao Glass Industry Group Co., Ltd., Xinyi Glass, Pilkington Glass, Asahi Glass Co., CSG Holding Co., Ltd., Vitro Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shatterproof Glass Market Strategic Shifts & Innovations
Material science advances are fragmenting traditional glass categories into application-specific hybrids that trade off optical, mechanical, and thermal properties in novel combinations. This recombination is compressing product lifecycles and expanding the addressable perimeter of shatterproof specifications.
SentryGlas ionoplast interlayers are fragmenting the architectural laminated glass market by delivering five times the post-breakage stiffness of conventional PVB. Structural glazing engineers in Frankfurt and Singapore are specifying these interlayers for point-supported facade systems that eliminate mechanical retention hardware. The technology is fragmenting procurement patterns as architects bypass standard glazing contractors to source directly from interlayer compounders.
Europe's F-Gas Regulation is tightening thermal transmittance requirements for commercial building envelopes, forcing facade designers toward triple-pane configurations with suspended low-emissivity films. German building departments are rejecting permit submissions that rely on dual-pane solutions for projects above 50 meters. The regulation is compressing specification timelines as developers rush to lock in designs before 2027 enforcement windows.
Fleet operators are consolidating windshield procurement through national maintenance contracts that bundle replacement scheduling with telematics-based damage detection. Logistics companies in the United States are disintermediating traditional glass distributors to capture volume rebates and reduce vehicle downtime. This concentration is reshaping competitive dynamics as regional installers lose access to high-frequency commercial accounts.
Shatterproof Glass Market Segmentation
Glass processors configure production lines around distinct performance thresholds. Each segment demands specialized interlayer chemistry, thermal profiles, or surface treatments that reshape capital allocation and margin structures across the value chain.
Product Type:
Domestic absorption dominates tempered and annealed categories, while laminated variants serve export-led automotive programs bound for European and North American assembly plants.
- Laminated Glass:Polyvinyl butyral or ionoplast interlayers bond multiple glass plies to retain post-breakage adhesion. Demand concentrates in Germany and the United States where UNECE R43 and NHTSA mandates require laminated windshields for head-impact protection.
- Tempered Glass:Rapid thermal quenching creates surface compression layers exceeding 750 MPa, producing characteristic dice-pattern fragmentation. China's coastal provinces consume the bulk of tempered output for domestic construction and appliance manufacturing.
- Coated Glass:Sputtered low-emissivity or solar-control films modify thermal transmittance for building envelope applications.
- Annealed Glass:Slow-cooled float glass without residual stress serves secondary glazing positions where shatter resistance requirements remain minimal.
Laminated glass commands the established base. The steepest expansion runs through chemically strengthened variants for display cover applications.
Application:
Volume distribution tracks regulatory intensity, with automotive and high-rise construction segments absorbing premium-priced laminated configurations.
- Automotive Windshields:Wedge-shaped interlayers maintain optical clarity for head-up display projection across curved geometries. European electric vehicle platforms are compressing laminate thickness to reduce curb weight for battery range optimization.
- Building Facades:Point-supported structural glazing systems specify ionoplast interlayers that eliminate mechanical retention hardware. German building departments above 50 meters now reject dual-pane solutions under F-Gas Regulation thermal standards.
- Skylights:Overhead glazing positions mandate laminated constructions for fall-protection compliance under ICC and national building codes.
- Display Screens:Ion exchange strengthening enables sub-millimeter thickness for smartphone and tablet cover glass.
- Security Barriers:Multi-ply laminated assemblies resist ballistic and forced-entry threats for government and financial institutions.
Automotive windshields anchor volume commitments. Display screens are climbing the fastest as foldable device launches strain chemical strengthening batch capacity.
End User:
Procurement concentration varies sharply, with vehicle manufacturers consolidating through direct OEM contracts while construction demand fragments across regional glazing contractors.
- Vehicle Manufacturers:Platform engineering teams specify windshield geometries 36-48 months ahead of production, locking in interlayer suppliers early in development cycles.
- Construction Companies:Commercial developers in India's metropolitan markets are pulling specification demand as BIS safety glazing mandates expand for high-rise construction.
- Electronics Producers:Device assemblers in South Korea and Taiwan negotiate multi-year cover glass supply agreements tied to product launch cadences.
- Security Firms:Government procurement channels specify tested ballistic assemblies for embassy and critical infrastructure protection.
Vehicle manufacturers represent the margin-rich core. Electronics producers are expanding most quickly as display diagonal sizes increase strengthening throughput requirements.
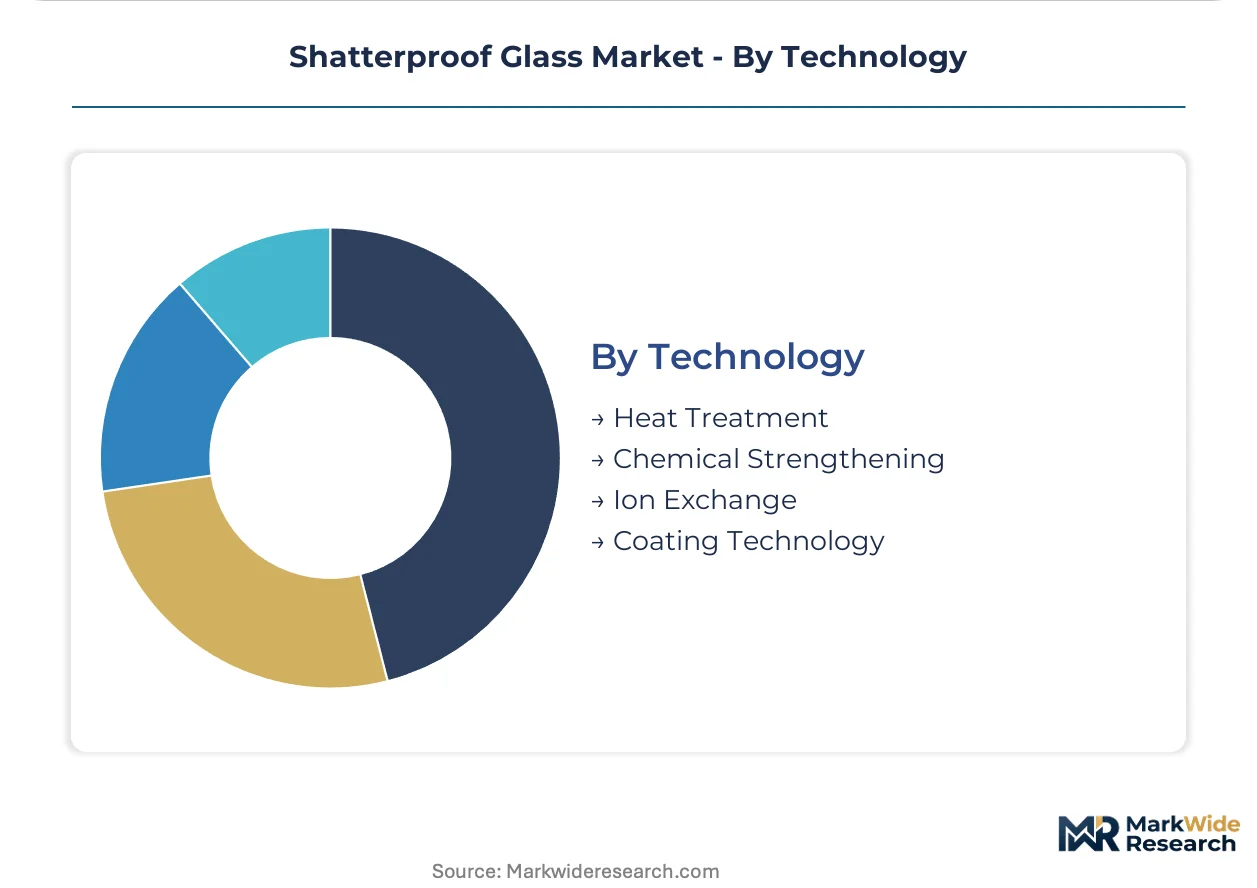
Technology:
Process selection determines capital intensity and throughput scalability, with heat treatment dominating mature volume pools and chemical methods claiming premium applications.
- Heat Treatment:Convection tempering furnaces process architectural and automotive sidelite glass at high throughput rates. Guardian Glass and Saint-Gobain operate heat-treatment capacity positioned near Detroit and Stuttgart assembly corridors.
- Chemical Strengthening:Molten salt ion exchange creates deep compression layers for thin cover glass. Fuyao Glass Industry Group extends this expertise from replacement windshields into display applications.
- Ion Exchange:Potassium-for-sodium substitution generates surface compression exceeding 800 MPa in sub-millimeter substrates.
- Coating Technology:Vacuum deposition and pyrolytic processes apply functional films for solar control, electromagnetic shielding, and anti-reflective properties.
Heat treatment commands the installed capacity base. Ion exchange is gaining share fastest as foldable and rollable display form factors demand extreme bend-radius durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and vehicle manufacturers concentrate procurement in Germany, the United States, and China, while construction demand clusters in India's metropolitan corridors and the UAE's high-rise developments.
United States
NHTSA head-impact mandates and commercial fleet consolidation drive laminated windshield specifications. Logistics operators bypass regional distributors for national maintenance contracts. Detroit-area processing plants serve domestic automotive assembly corridors with heat-treatment capacity positioned near OEM platforms.
Germany
UNECE R43 penetration standards and F-Gas Regulation thermal requirements reshape building envelope specifications. Stuttgart's automotive engineering clusters specify wedge-shaped interlayers for HUD-compatible windshields. Frankfurt facade engineers source ionoplast interlayers directly from compounders for point-supported structural glazing.
China
Coastal manufacturing provinces host float glass furnace clusters serving export automotive programs and domestic construction. MIIT safety standards and dual carbon goals compress laminate thickness for electric vehicle weight optimization. Fuyao Glass anchors chemical strengthening expertise for display cover glass expansion.
India
BIS safety glazing mandates for high-rise construction create specification pull in underpenetrated metropolitan markets. Commercial developers in Mumbai and Delhi-NCR accelerate laminated facade adoption. Regional glazing contractors fragment procurement across project-scale batches.
United Arab Emirates
High-rise construction codes and security glazing requirements for critical infrastructure drive multi-ply laminated assemblies. Dubai's architectural specification channels prioritize ballistic-resistant barriers for financial and government institutions. MOHAP building safety standards enforce fall-protection compliance for overhead glazing positions.
Shatterproof Glass Market Key Industry Players
Player mix skews toward integrated float-to-fabrication specialists with captive interlayer supply and regional heat-treatment networks serving automotive assembly corridors. Mid-tier processors face capital strain converting tempering capacity to laminated processing lines. Three archetypes dominate: European float glass networks with premium automotive anchoring, Chinese coastal clusters with scale-driven export positioning, and chemical strengthening specialists extending into display cover applications. Competitive moves center on direct OEM contracting to capture program engineering fees and geographic repositioning near Stuttgart and Detroit assembly zones.
Among European-integrated fabricators, Saint Gobain exemplifies the premium-tier float network archetype, anchoring supply for automotive programs through continental furnace positioning. Guardian Glass occupies the regional heat-treatment specialist position with capacity clustered near North American and German assembly corridors. Fuyao Glass Industry Group Co., Ltd. represents the chemical strengthening extension archetype, leveraging ion exchange expertise from automotive replacement into display cover glass segments.
| Leading Market Players |
|---|
| Saint Gobain |
| Cardinal Glass Industries |
| Guardian Glass |
| Fuyao Glass Industry Group Co., Ltd. |
| Xinyi Glass |
| Pilkington Glass |
| Asahi Glass Co. |
| CSG Holding Co., Ltd. |
| Vitro Glass |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with petrochemical indexation lock in PVB interlayer supply for European automotive programs while capping margin exposure to resin price swings. These arrangements tie laminated glass processors to named-volume commitments with Saint-Gobain and Guardian Glass, embedding price visibility across the analysis window.
Pricing Analysis
Cost-plus contracts indexed to butyraldehyde and ethylene feedstock benchmarks dominate the laminated glass tier. Price differentiation separates UNECE R43-certified automotive laminates from standard architectural grades, with HUD-compatible wedge-interlayer configurations commanding additional premiums. Cost compression in mass-market tempered sidelite segments is intensifying because Chinese coastal processors are expanding heat-treatment capacity. Fleet operators consolidating through national maintenance contracts demonstrate the lowest price sensitivity, while regional glazing contractors in India's metropolitan markets face acute margin pressure.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on the Asia-Europe trade lane are elevating working capital requirements for float glass importers. Supply concentrates in China's coastal provinces, Germany's Saarland corridor, and the US Midwest, with raw material dependencies spanning soda ash, natural gas for furnace fuel, and petrochemical-derived interlayer resins. Single-source vulnerability from PVB resin concentration among three global compounders creates supply chain risk. Distribution runs through direct OEM contracting for automotive programs and fragmented regional glazing contractor networks for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as vehicle manufacturers consolidate windshield procurement through 36-48 month platform engineering cycles, fragmenting pricing leverage among mid-tier processors.
For Market Incumbents: Consolidate heat-treatment capacity near Stuttgart and Detroit assembly corridors to anchor premium automotive programs against emerging Chinese chemical strengthening specialists. Deepen captive interlayer compounding capabilities to offset PVB resin cost volatility. Secure UNECE R43 homologation engineering contracts early in OEM development cycles to lock out competing bids. For New Entrants and Emerging Players: Post-breakage structural engineering services for point-supported facade systems represent a service-layer gap where Saint-Gobain and Guardian Glass under-serve mid-size commercial developers. Target India's underpenetrated high-rise construction markets as BIS safety glazing mandates expand in Mumbai and Delhi-NCR. Pursue direct architect specification relationships that bypass traditional glazing contractor channels. For Investors and Strategic Acquirers: Capital is best deployed toward ion exchange specialists with existing automotive glass expertise seeking display cover glass expansion, such as Fuyao Glass Industry Group's trajectory. Long-term viability over the next decade hinges on foldable device launch cadences straining chemical strengthening batch capacity. Watch for inflection when South Korean and Taiwanese electronics assemblers announce multi-year cover glass supply agreements exceeding existing processor throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Contracting | Bypasses tiered distribution to capture program engineering fees from NHTSA-mandated windshield platforms. |
| Ionoplast Interlayer Adoption | SentryGlas formulations enable point-supported facades that eliminate mechanical retention hardware in Frankfurt specifications. |
| Chemical Strengthening Capacity Expansion | Molten salt ion exchange lines address foldable display cover glass demand from South Korean device assemblers. |
| Float-to-Laminate Line Reconfiguration | Converts tempering capacity to laminated processing for UNECE R43 panoramic roof mandates in European electric vehicles. |
| Photovoltaic-Integrated Facade Development | Building-integrated solar glass opens architectural channels beyond traditional glazing contractor networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive platform engineers, facade specification architects, glass processing plant managers, and commercial fleet procurement directors. Secondary validation drew from UNECE R43 homologation databases, NHTSA FMVSS compliance filings, BIS safety glazing standards, and EU F-Gas Regulation implementation guidance. Bottom-up volume modeling from individual processor capacity and top-down demand estimation from vehicle production and construction permit data were triangulated to anchor projections.
Across the projection horizon, the analytical framework segmented volume and value by product type, application, end-user archetype, and regional production cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle platform weight optimization trends and high-rise construction code expansion patterns. Modeled inputs included float glass furnace operating rates, interlayer resin price indices, and homologation timeline distributions for new windshield geometries.
Material uncertainties — including petrochemical feedstock volatility, UNECE R43 certification delays, and ion exchange throughput constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement timelines and OEM platform launch cadences. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Europe Sapphire Glass Market
Glass
Glass Tableware Market
Glass
Global Vitrification Market
Glass
Asia-Pacific Flat Glass Market
Glass
Heat Resistant Glass Market
Glass
Glazing Gel Market
Glass
Middle East and Africa Glassware Market
Glass
Global Self-Cleaning Glass Market
Glass
Glass Lens Market
Glass
Silica Sol Market
Glass
Low Temperature Laminated Glass Market
Glass
Latin America Flat Glass Market
Glass
Flexible Glass Market
Glass
Fiberglass Window Market
Glass
Coated Solar Control Glass Market
Glass
Dynamic Glazing Market