
 UAE Silica Sand Market | 2026-2036
UAE Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Silica Sand Market Analytics
Multi-source procurement among glass and construction buyers is consolidating around vertically integrated suppliers with captive quarry access. Silica International (RAK) anchors its position through direct control of Ras Al Khaimah mining leases. Gulf Minerals & Chemicals LLC leverages long-haul logistics networks to serve foundry customers across the northern Emirates. Majd Al Muayad specializes in wet-processing capabilities that yield lower-iron product for premium glass applications.
UAE silica sand comprises high-purity quartz grains with SiO₂ content typically exceeding 95%, processed through washing, drying, and magnetic separation to meet foundry and glass specifications. Industrial grade silica sand dominates volume flows into concrete batching plants serving Dubai and Abu Dhabi megaprojects. Wet silica sand commands premium positioning among float glass producers like Emirates Float Glass LLC due to superior particle consistency. Water filtration applications represent the fastest-growing demand channel as desalination capacity expands across the Emirates.
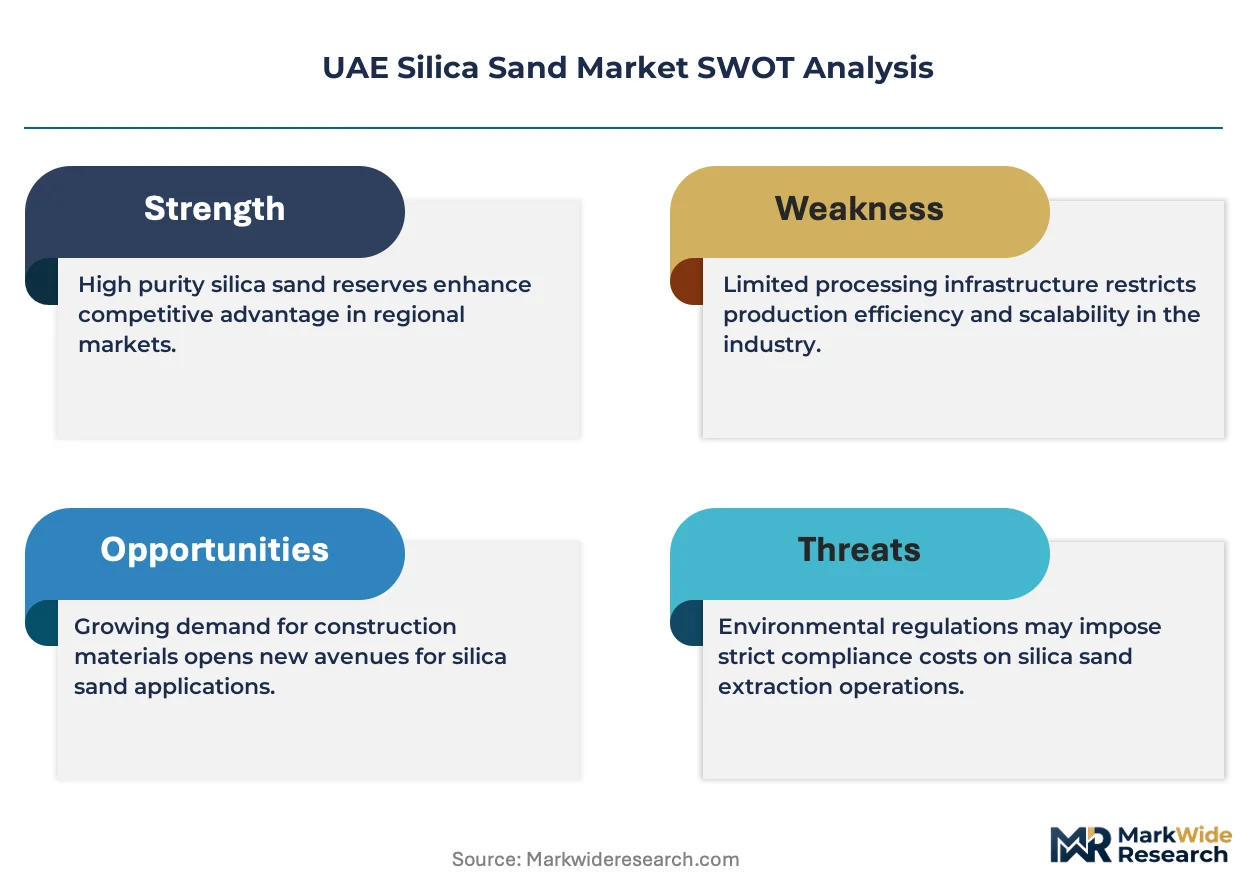
MOHAP workplace silica exposure limits and Emirates Authority for Standardization and Metrology (ESMA) product quality mandates shape extraction licensing and end-use certification requirements. Federal environmental assessments now require dust suppression systems at all new quarry developments. Stakeholders must monitor how Abu Dhabi industrial zone expansion timelines affect bulk logistics infrastructure for silica delivery.
Market Dynamics
Glass manufacturers across the Emirates are consolidating feedstock procurement around suppliers with direct quarry control, compressing spot-market liquidity and elevating long-term contract premiums for high-purity grades.
Growth Catalysts
- Float glass capacity expansion:Emirates Float Glass LLC and adjacent producers are commissioning new furnaces that require wet-processed silica with sub-0.1% iron content, pulling premium feedstock volumes through dedicated offtake agreements.
- MOHAP silica exposure limits:Workplace safety mandates are accelerating capital deployment in dust suppression and enclosed processing systems, filtering out informal operators and tightening supply to certified handlers.
- Desalination infrastructure buildout:Water filtration-grade silica demand is climbing as Abu Dhabi and Dubai utilities expand reverse osmosis pre-treatment capacity, creating a specialized high-margin outlet for processed sand.
Market Restraints
- Captive quarry concentration:Ras Al Khaimah holds the majority of mineable high-purity reserves, creating geographic supply risk and transport cost penalties for southern Emirates buyers.
- Energy input volatility:Wet processing and kiln drying are natural-gas intensive, exposing margins to UAE domestic tariff adjustments and global LNG price swings.
- Alternative ceramic feedstocks:Recycled glass cullet and synthetic silica precursors are gaining traction in container glass applications, capping volume growth in traditional sand markets.
Strategic Opportunities
- Abu Dhabi industrial zone clustering:KIZAD and adjacent heavy manufacturing corridors lack proximate silica processing, creating first-mover advantage for integrated quarry-to-plant logistics investments.
- ESMA quality certification premium:Federal standardization mandates for construction materials are opening margin expansion for pre-certified suppliers versus uncertified bulk traders.
- Solar glass demand emergence:Photovoltaic panel manufacturing investments in the Emirates are specifying ultra-low-iron silica for tempered cover glass, converging semiconductor-grade purity requirements with traditional industrial supply chains.
Industry Challenges
- Specialized processing engineering scarcity:Wet beneficiation and magnetic separation expertise is concentrated among a handful of technical consultants, constraining capacity expansion timelines for new entrants.
- Multi-agency permitting complexity:Quarry licenses require sequential approvals from Ras Al Khaimah Natural Resources Authority, federal environmental assessments, and MOHAP workplace safety inspections, extending project gestation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Silica Sand Market |
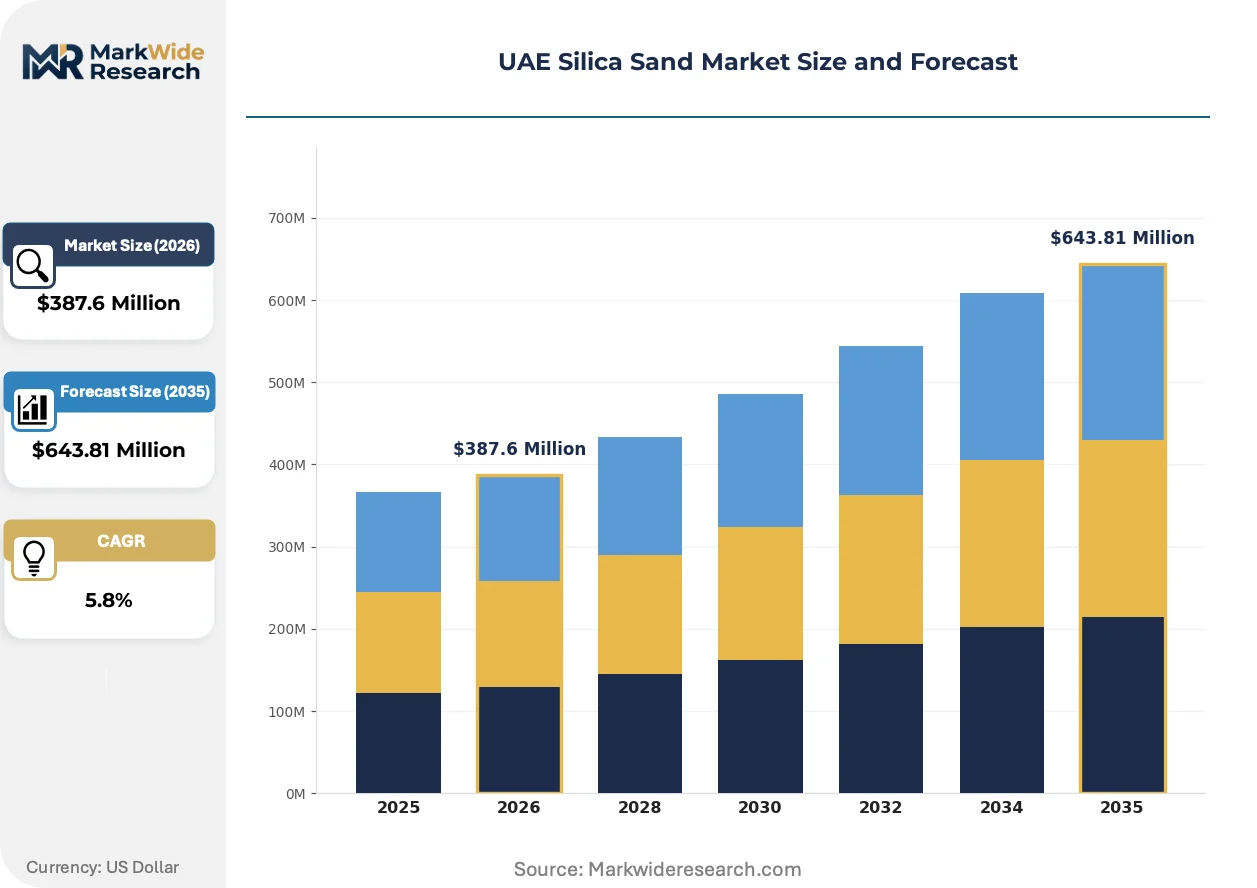
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Silica Sand, Wet Silica Sand, Coated Silica Sand, Industrial Grade Silica Sand End User: Construction, Oil & Gas, Glass Manufacturing, Foundries Application: Concrete Production, Water Filtration, Abrasives, Coatings Packaging Type: Bulk Packaging, Bags, Containers, Loose Delivery |
| Companies Covered | National Ready Mix Concrete Co. LLC, Silica International (RAK), Gulf Minerals & Chemicals LLC, Majd Al Muayad, Emirates Mining Company LLC, Delmon Co. Ltd., Mitsubishi Corporation, Emirates Float Glass LLC, Adwan Chemical Industries Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Silica Sand Market Evolving Landscape
Processing technology and regulatory compliance are converging to reshape competitive advantage, with automation and environmental controls displacing labor-intensive extraction methods across the Emirates.
Advanced sensor-based sorting is integrating real-time near-infrared and X-ray fluorescence analysis into wet processing lines. Float glass producers are adopting these systems to guarantee iron content consistency batch-to-batch. The technology is integrating quality assurance directly into extraction workflows, reducing downstream rejection rates and compressing supplier qualification cycles for premium applications.
MOHAP respirable crystalline silica exposure limits are tightening enforcement protocols across all quarry operations. Federal inspectors are mandating continuous personal monitoring and engineered ventilation retrofits at existing sites. Wet processing operators face lower compliance burdens than dry extraction competitors, tilting investment toward slurry-based beneficiation methods in new project designs.
Long-term offtake contracting is displacing spot procurement among major glass and foundry buyers. Procurement teams at Emirates Float Glass and northern Emirates metalcasters are locking in five-year supply agreements with fixed-grade specifications. Abu Dhabi megaproject concrete batching plants remain the exception, maintaining spot-market flexibility for industrial-grade material.
UAE Silica Sand Market Segmentation
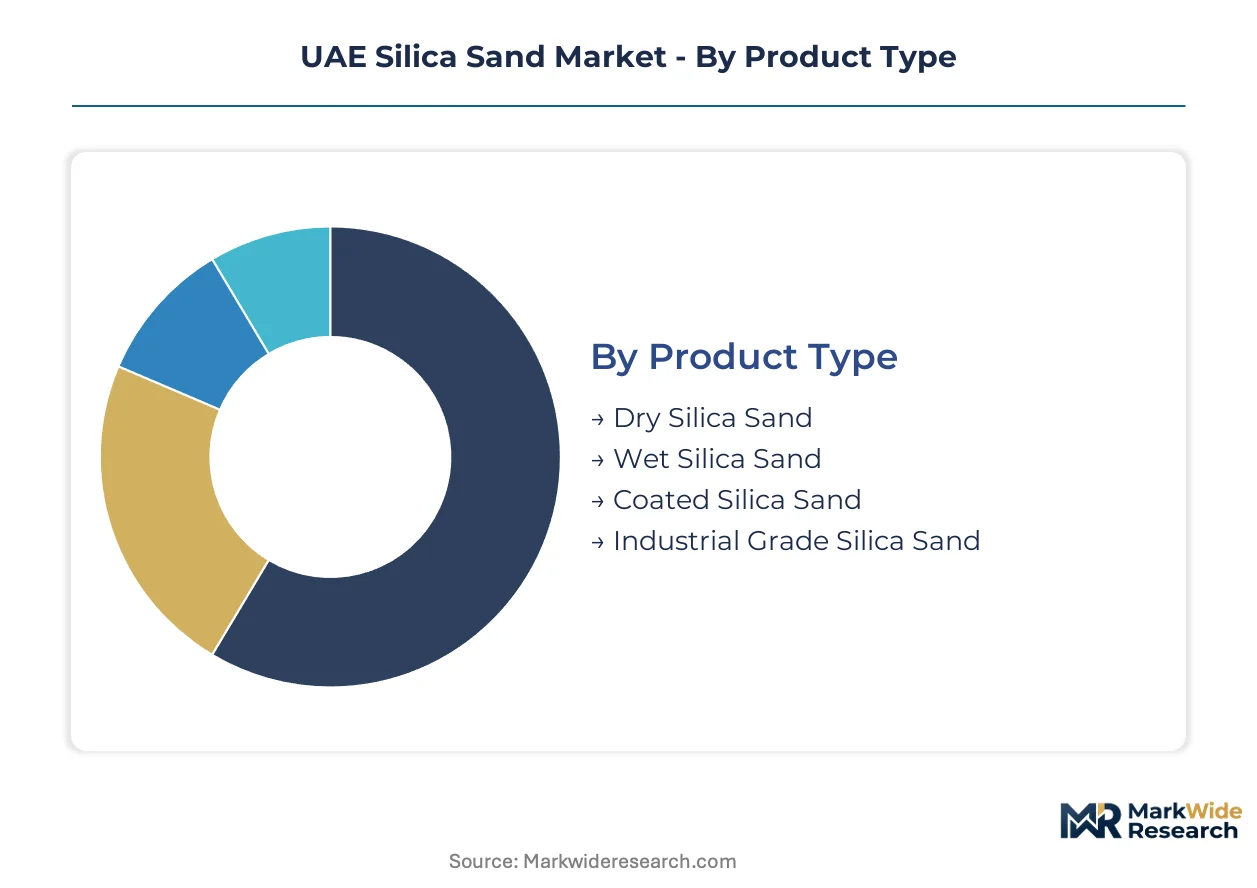
Segmentation in the UAE silica sand market reveals how product specifications, end-use requirements, and logistics configurations create distinct profit pools. Buyers optimize procurement across these dimensions to balance purity premiums against transport and handling economics.
Product Type:
Wet-processed material commands premium positioning while dry grades dominate volume flows into mass construction applications.
- Wet Silica Sand:Slurry-based beneficiation yields sub-0.1% iron content essential for float glass furnace feedstock. Emirates Float Glass LLC and adjacent producers lock in dedicated offtake agreements for this grade, pulling supply through Ras Al Khaimah processing corridors. MOHAP dust exposure regulations favor wet operations over dry extraction, reinforcing supply concentration among slurry-capable handlers.
- Industrial Grade Silica Sand:Lower-purity material with SiO₂ content between 85-95% serves concrete batching plants across Dubai and Abu Dhabi megaprojects. Volume demand concentrates in bulk delivery contracts with flexible spot-market pricing, though ESMA certification requirements are tightening quality thresholds for federal infrastructure eligibility.
- Dry Silica Sand:Kiln-dried material with controlled moisture content below 0.5% supplies foundry mold-making operations across the northern Emirates.
- Coated Silica Sand:Resin-bonded formulations serve specialized foundry applications requiring reduced thermal expansion characteristics.
Today's leader: Industrial Grade Silica Sand. Tomorrow's challenger: Wet Silica Sand.
End User:
Glass manufacturers consolidate procurement around captive quarry relationships while construction maintains spot-market flexibility.
- Glass Manufacturing:Float glass and container glass producers specify ultra-low-iron feedstock with batch-to-batch consistency guarantees. Sensor-based sorting integration at Ras Al Khaimah processing facilities enables real-time quality assurance that reduces downstream rejection rates. Solar glass investments in the Emirates are extending purity requirements toward semiconductor-grade specifications.
- Construction:Concrete batching plants and precast manufacturers absorb the largest volume share, prioritizing cost efficiency over chemical purity. Abu Dhabi industrial zone expansion is creating logistics bottlenecks for southern Emirates projects, compressing delivered margins for bulk suppliers without integrated transport assets.
- Foundries:Metalcasting operations in the northern Emirates require consistent grain size distribution for mold permeability control.
- Oil & Gas:Hydraulic fracturing and well completion applications specify rounded grain morphology with crush resistance above 5,000 psi.
Glass Manufacturing captures the steepest margin expansion. Construction retains volume dominance.
Application:
Water filtration is climbing the fastest as desalination capacity expands, while concrete production anchors baseline demand.
- Water Filtration:Reverse osmosis pre-treatment systems across Abu Dhabi and Dubai utilities specify angular grain morphology with uniform effective size. Desalination infrastructure buildout is creating a specialized high-margin outlet that commands premium positioning over industrial-grade alternatives. Federal water security investments are accelerating procurement timelines for certified filtration media.
- Concrete Production:Aggregate blending and cementitious matrix applications consume the largest tonnage, with specifications emphasizing gradation consistency and alkali-silica reactivity compliance. KIZAD and adjacent heavy manufacturing corridors lack proximate silica processing, inflating delivered costs for megaproject batching plants.
- Abrasives:Sandblasting and surface preparation applications require hardness above 6.5 Mohs with controlled fines generation.
- Coatings:Architectural and industrial paint formulations utilize micronized silica for rheology control and matting effects.
Concrete Production holds current volume leadership. Water Filtration is gaining share fastest.
Packaging Type:
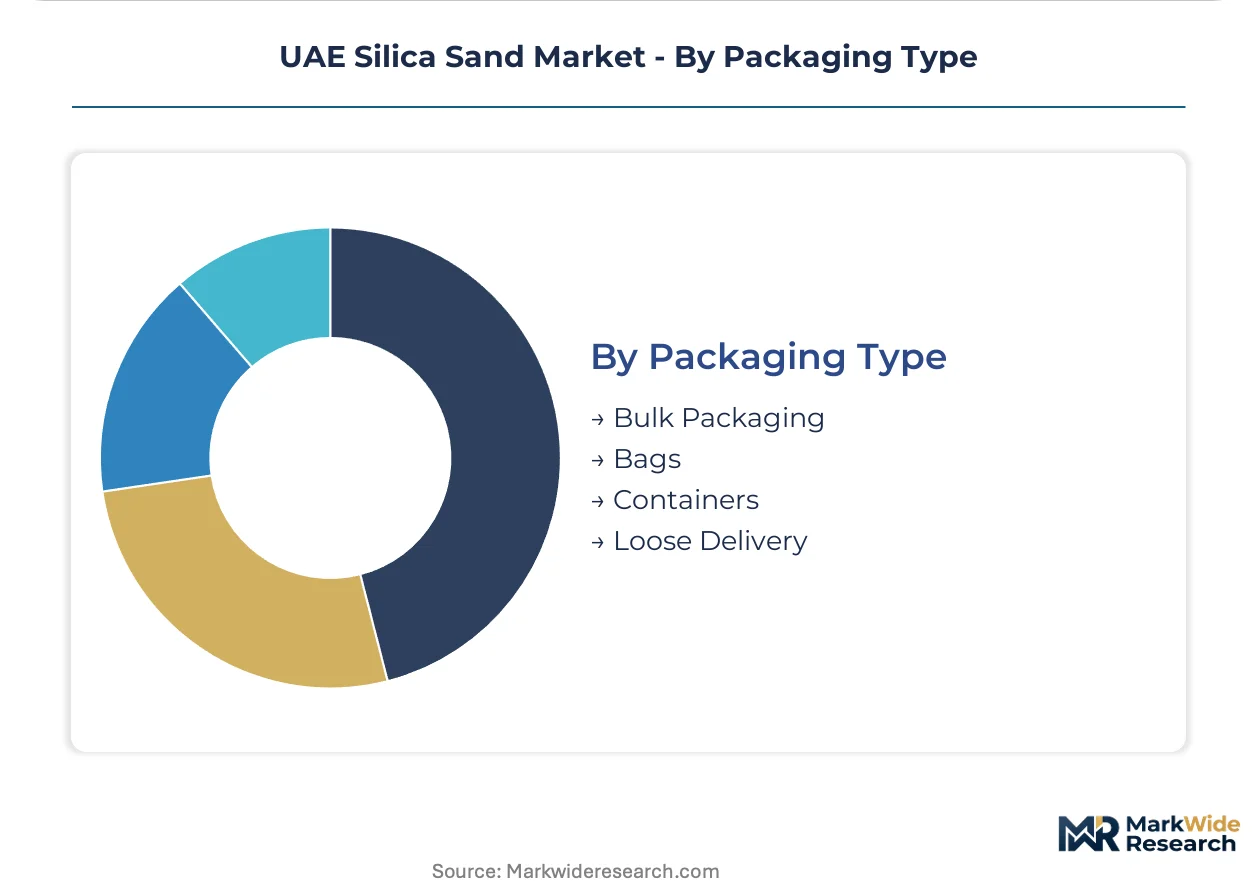
Bulk configurations dominate industrial flows while bagged formats serve remote sites and specialty applications.
- Bulk Packaging:Pneumatic tanker and pneumatic trailer delivery minimizes handling costs for high-volume glass and construction customers. Long-haul logistics networks from Ras Al Khaimah quarries to Abu Dhabi industrial zones favor bulk configurations that maximize payload efficiency and reduce per-ton transport penalties.
- Bags:25kg and 50kg woven polypropylene formats serve foundry customers and remote construction sites lacking pneumatic unloading infrastructure.
- Containers:ISO tank and flexitank configurations support export-oriented foundry and filtration-grade shipments.
- Loose Delivery:Direct dump truck discharge serves proximal concrete batching plants with dedicated receiving hoppers.
Bulk Packaging defines operational scale. Bags retain niche premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ras Al Khaimah industrial corridors anchor UAE silica sand extraction, with processing infrastructure clustering around captive quarry leases and bulk logistics terminals serving downstream glass and construction demand.
Dubai
Concrete batching plants across Dubai South and Jebel Ali absorb industrial-grade silica for megaproject construction, with procurement teams prioritizing spot-market flexibility over long-term contracts. ESMA certification mandates are tightening quality thresholds for federal infrastructure eligibility. Bulk pneumatic delivery networks from northern Emirates quarries face congestion at Dubai industrial zone entry points.
Abu Dhabi
KIZAD and adjacent heavy manufacturing corridors generate concentrated demand for water filtration-grade silica as desalination capacity expands. MOHAP workplace safety inspections enforce dust suppression protocols at all receiving facilities. The absence of proximate processing infrastructure inflates delivered costs for glass manufacturers seeking high-purity feedstock.
Ras Al Khaimah
Captive mining leases controlled by vertically integrated processors supply wet-processed silica with sub-0.1% iron content to float glass producers. Federal environmental assessments mandate continuous personal monitoring and engineered ventilation at extraction sites. Sensor-based sorting facilities enable real-time quality assurance that reduces downstream rejection rates for premium applications.
Sharjah
Foundry operations in Sharjah industrial zones require consistent grain size distribution for mold permeability control, sourcing dry-processed material through long-haul logistics networks. Emirates Authority for Standardization and Metrology product quality mandates shape end-use certification requirements. Bulk packaging configurations dominate flows to metalcasting customers lacking pneumatic unloading infrastructure.
Northern Emirates
Remote construction sites across Fujairah and Umm Al Quwain rely on bagged silica formats due to limited pneumatic receiving infrastructure. Multi-agency permitting complexity from Ras Al Khaimah Natural Resources Authority extends project gestation periods for new quarry developments. Specialized wet beneficiation expertise concentrates among established technical consultants, constraining capacity expansion timelines.
UAE Silica Sand Market Competitive Landscape
Global trading houses compete with regional quarry operators across procurement consolidation and captive reserve access. Market structure tilts toward supply concentration, with Ras Al Khaimah leaseholders commanding premium positioning through direct mining control. Three archetypes dominate: vertically integrated processors with captive reserves, trading intermediaries with long-haul logistics networks, and specialized wet-beneficiation operators. Competitive moves center on five-year offtake contracting and dust suppression technology deployment.
Among UAE-based leaseholders, Silica International (RAK) and Emirates Mining Company LLC occupy positions anchored to Ras Al Khaimah reserve bases. Gulf Minerals & Chemicals LLC exemplifies the logistics-intensive trading archetype serving foundry demand across northern Emirates corridors. Majd Al Muayad represents wet-processing specialization yielding lower-iron product streams.
| Leading Market Players |
|---|
| National Ready Mix Concrete Co. LLC |
| Silica International (RAK) |
| Gulf Minerals & Chemicals LLC |
| Majd Al Muayad |
| Emirates Mining Company LLC |
| Delmon Co. Ltd. |
| Mitsubishi Corporation |
| Emirates Float Glass LLC |
| Adwan Chemical Industries Co. |
| Others |
Value Network & Pricing Analysis
Natural gas tariff indices cascade through UAE silica sand processing economics, compressing margins at wet-beneficiation operators while amplifying price premiums for low-iron grades. Ras Al Khaimah quarry holders translate captive reserve access into contract pricing power over southern Emirates buyers lacking proximate supply.
Pricing Analysis
Input-cost pass-through from energy tariffs and long-haul logistics compresses margins for non-integrated handlers. Pricing stratifies across wet-processed premium grades, ESMA-certified industrial tiers, and spot-market bulk material. Cost compression in industrial-grade supply is intensifying because concrete batching plants maintain spot flexibility. Glass manufacturers show least price sensitivity due to purity-locked furnace specifications; construction buyers exhibit highest sensitivity with volume-driven procurement.
Supply Chain Analysis
ESMA certification and MOHAP workplace safety inspections gate supplier qualification before contract eligibility. Supply concentrates in Ras Al Khaimah, with secondary processing in Sharjah and consumption centered in Dubai and Abu Dhabi. The chain draws from captive mining leases, natural gas inputs, and specialized magnetic separation equipment. Single-source vulnerability runs through Ras Al Khaimah reserve concentration. Distribution runs through pneumatic bulk tankers for glass and construction customers, with bagged formats serving remote foundry sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP silica exposure limits compound regulatory-driven demand for certified processing infrastructure, elevating capital requirements that filter marginal operators from contract eligibility.
For Market Incumbents: Hedge geographic concentration risk by securing secondary processing capacity in Abu Dhabi industrial corridors before KIZAD demand peaks. Deepen backward integration into dust suppression technology to sustain MOHAP compliance advantages over dry-extraction competitors facing retrofit burdens.
For New Entrants and Emerging Players: Abu Dhabi water filtration buyers lacking proximate supply represent the most penetrable white-space target. Solar glass manufacturers specifying ultra-low-iron feedstock offer second entry path. Lead with wet-processing certification to bypass ESMA qualification barriers blocking bulk traders from premium contracts.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-agency permitting complexity extends project gestation beyond capital patience. Five-to-ten year viability favors quarry-to-plant integrated operators with locked reserve bases. Target acquisition archetype: wet-beneficiation specialists with MOHAP-compliant facilities and uncontracted expansion permits. Watch Abu Dhabi desalination procurement timelines as inflection signal for filtration-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Quarry Lease Expansion | Secures Ras Al Khaimah reserve access ahead of federal environmental assessment tightening. |
| Wet-Processing Capacity Buildout | Captures MOHAP compliance advantage over dry extraction while serving float glass purity requirements. |
| Long-Term Offtake Agreements | Locks in Emirates Float Glass and solar glass producers before alternative ceramic feedstocks mature. |
| ESMA Certification Investment | Qualifies industrial-grade supply for federal infrastructure eligibility excluding uncertified bulk traders. |
| Abu Dhabi Logistics Integration | Reduces delivered cost penalties for KIZAD and Dubai South megaproject batching plants. |
Research Methodology
Direct dialogue with quarry operations managers, glass manufacturer procurement leads, foundry technical directors, and federal environmental assessors grounded qualitative findings in operational reality. Secondary validation drew from MOHAP regulatory filings, ESMA standards documentation, Ras Al Khaimah Natural Resources Authority licensing records, and customs trade data. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators.
Segment-level volume and value trajectories emerged from integrating product-grade specifications, purity-tier pricing differentials, and regional logistics cost structures across the projection horizon. Modeled dimensions spanned wet versus dry processing routes, glass manufacturing versus construction versus foundry end-uses, and bulk versus bagged packaging configurations. CAGRs derived from time-series analysis of furnace capacity expansion, desalination infrastructure procurement, and megaproject concrete demand. Industry-specific inputs included natural gas tariff schedules and MOHAP enforcement protocol evolution.
Underlying measurement precision varies by segment; water filtration and solar glass applications carry tighter precision than speculative construction spot markets. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and alternative ceramic feedstock substitution rates. A model refresh is warranted upon material change in Abu Dhabi industrial zone commissioning timelines or MOHAP silica exposure limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Shatterproof Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Glass Mat Market
Glass
Glass Mason Jars Market
Glass
Global Anti-Reflective Glass Market
Glass
Europe Glassware Market
Glass
Mirrored Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
Solar Reflective Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Glass Forming Machine Market
Glass
Solar PV Glass Market
Glass
Mexico Flat Glass Market
Glass
Europe Sapphire Glass Market
Glass
Glass Polishing Powder Market
Glass
Global Self-Cleaning Glass Market