
 Asia Pacific Flexible Glass Market | 2026-2036
Asia Pacific Flexible Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Flexible Glass Market Outlook
China's GB standards for display panel energy efficiency is broadening the cost-of-entry calculus for flexible glass suppliers seeking domestic certification. SCHOTT AG leverages its specialty glass expertise to sustain premium positioning in high-barrier substrate segments. Corning Incorporated anchors its regional presence through deep R&D partnerships with Korean display manufacturers. Samsung Electronics dominates foldable device integration, navigating the transition from pilot-scale to mass-production volumes.
Asia Pacific flexible glass refers to alkali-free borosilicate or aluminosilicate glass substrates manufactured to thicknesses below 0.1 millimeters, capable of bending radii under 5 millimeters without fracture, primarily serving as protective and functional layers in bendable electronic devices. Chemical vapor deposition yields the highest-performance barrier films for organic electronics, though roll-to-roll processing is gaining traction as manufacturers scale throughput for mid-tier wearable applications. Ultra-thin glass commands the strongest margin pools in premium smartphone foldable displays, while coated glass variants expand fastest in automotive curved-console segments where anti-reflective and anti-fingerprint specifications determine supplier selection.
Japan's METI enforces stringent JIS standards for electronic material reliability, while South Korea's MFDS oversees chemical safety in manufacturing processes, and China's SAMR administers national standard compliance for imported substrate materials. These frameworks collectively elevate testing burdens but simultaneously filter out low-quality entrants, preserving pricing power for certified suppliers. Stakeholders must monitor evolving substrate thickness requirements in next-generation foldable form factors and assess captive supply investments before capacity commitments lock in.
Market Dynamics
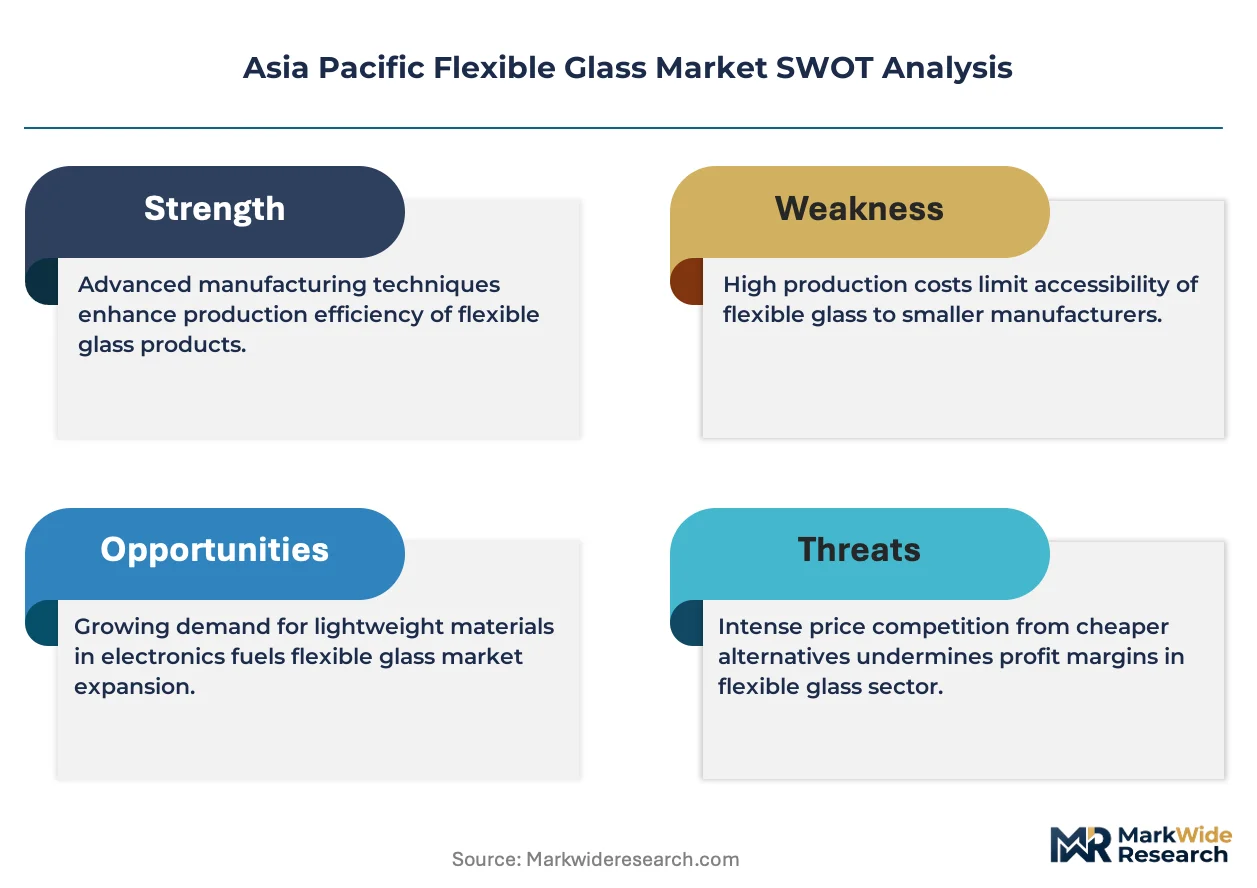
Foldable display manufacturing in South Korea and Japan is concentrating procurement power among three dominant panel makers, compressing supplier margins while elevating technical certification requirements for substrate entrants.
Growth Catalysts
- MIIT dual carbon goals:China's energy-efficiency mandates accelerate capital flows into low-temperature glass processing, expanding addressable capacity for domestic substrate producers.
- Automotive curved consoles:Anti-reflective coated glass specifications in premium vehicle cabins are displacing polycarbonate alternatives across Japanese and Korean OEM supply chains.
- Guangdong cluster procurement:Display panel concentration in China's southern manufacturing belt generates localized demand pull for ultra-thin substrate certification.
Market Restraints
- High-purity alumina supply:Input cost volatility from Australian and Vietnamese bauxite processors constrains margin predictability for aluminosilicate glass manufacturers.
- Captive Korean supply chains:Samsung Display and LG Display maintain backward-integrated substrate operations, limiting third-party penetration in premium foldable segments.
- JIS reliability testing:METI-mandated 100,000-cycle bend endurance protocols extend certification timelines and exclude uncertified Chinese suppliers from Japanese electronics procurement.
Strategic Opportunities
- India's electronics PLI scheme:Smartphone assembly incentives in Uttar Pradesh and Tamil Nadu create first-mover positioning for glass substrate suppliers establishing local finishing operations.
- Roll-to-roll barrier deposition:Convergence of atomic layer deposition with continuous web processing enables mid-tier wearable entry at sub-premium price points.
- Vietnam display assembly:Samsung and BOE panel backend migration to Bac Ninh province opens procurement channels outside Chinese tariff exposure.
Industry Challenges
- Thin-film transistor integration:Bonding ultra-thin glass to polyimide backplanes without thermal stress fractures requires specialized process engineering talent concentrated in Korean and Taiwanese facilities.
- Cross-border GB standard recognition:Chinese SAMR certification does not automatically transfer to MFDS chemical safety approvals, forcing redundant testing for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Flexible Glass Market |
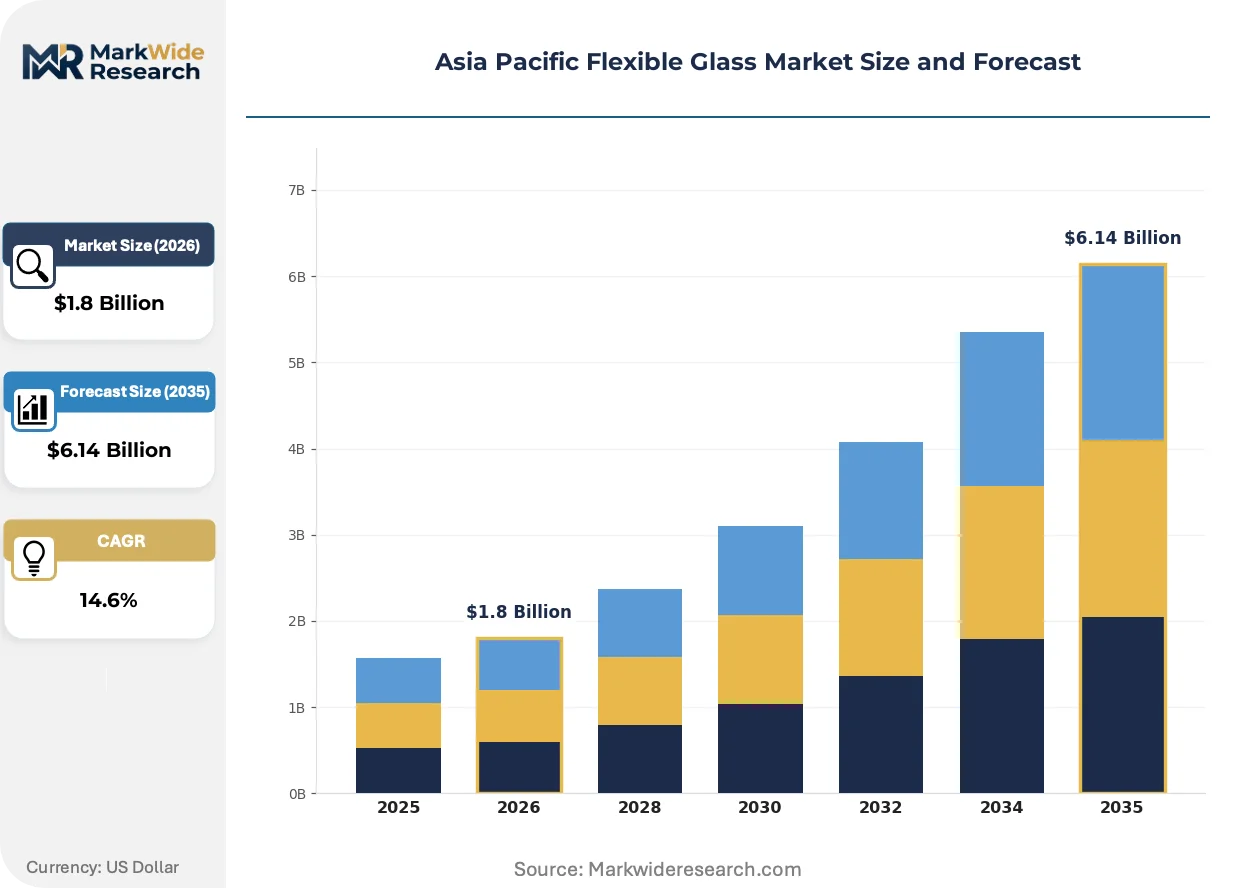
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Glass, Thin Film Glass, Coated Glass, Ultra-Thin Glass End User: Consumer Electronics, Automotive Displays, Wearable Devices, Building and Construction Application: Touch Panels, Flexible Displays, Solar Cells, Lighting Solutions Technology: Chemical Vapor Deposition, Roll-to-Roll Processing, Laser Processing, Nanoimprinting |
| Companies Covered | Samsung Electronics, Nippon Electric Glass Co., Ltd., Corning Incorporated, SCHOTT AG, Taiwan Glass Industry Corporation, AGC Inc., LG Electronics, Asahi India Glass Limited, Xinyi Glass Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Flexible Glass Market Strategic Shifts
Chemical strengthening protocols and barrier film architectures are rewriting the technical foundation for flexible substrate performance, compressing development cycles while fragmenting competitive positioning across application tiers.
Roll-to-roll atomic layer deposition is rewriting the economics of high-barrier encapsulation for organic electronics. Mid-tier wearable manufacturers in Taiwan and Vietnam are adopting continuous web processing to bypass batch-scale vacuum chamber bottlenecks. The technology is rewriting supplier selection criteria by decoupling barrier performance from capital-intensive flat-panel equipment.
METI's 2024 revision to JIS C 60068 environmental testing standards imposes stricter thermal shock parameters on foldable display substrates. Japanese electronics OEMs now require documented compliance for supply chain qualification, filtering out uncertified entrants. Korean panel makers are accelerating in-house testing infrastructure to preempt third-party laboratory bottlenecks.
Consolidated procurement through designated panel supplier programs is compressing vendor diversity in China's display ecosystem. BOE, TCL CSOT, and Tianma now coordinate substrate specifications through shared technical committees, displacing fragmented buyer-seller negotiations. The shift is most visible in Guangdong province, where centralized purchasing has reduced qualified glass supplier rosters by half.
Asia Pacific Flexible Glass Market Segmentation
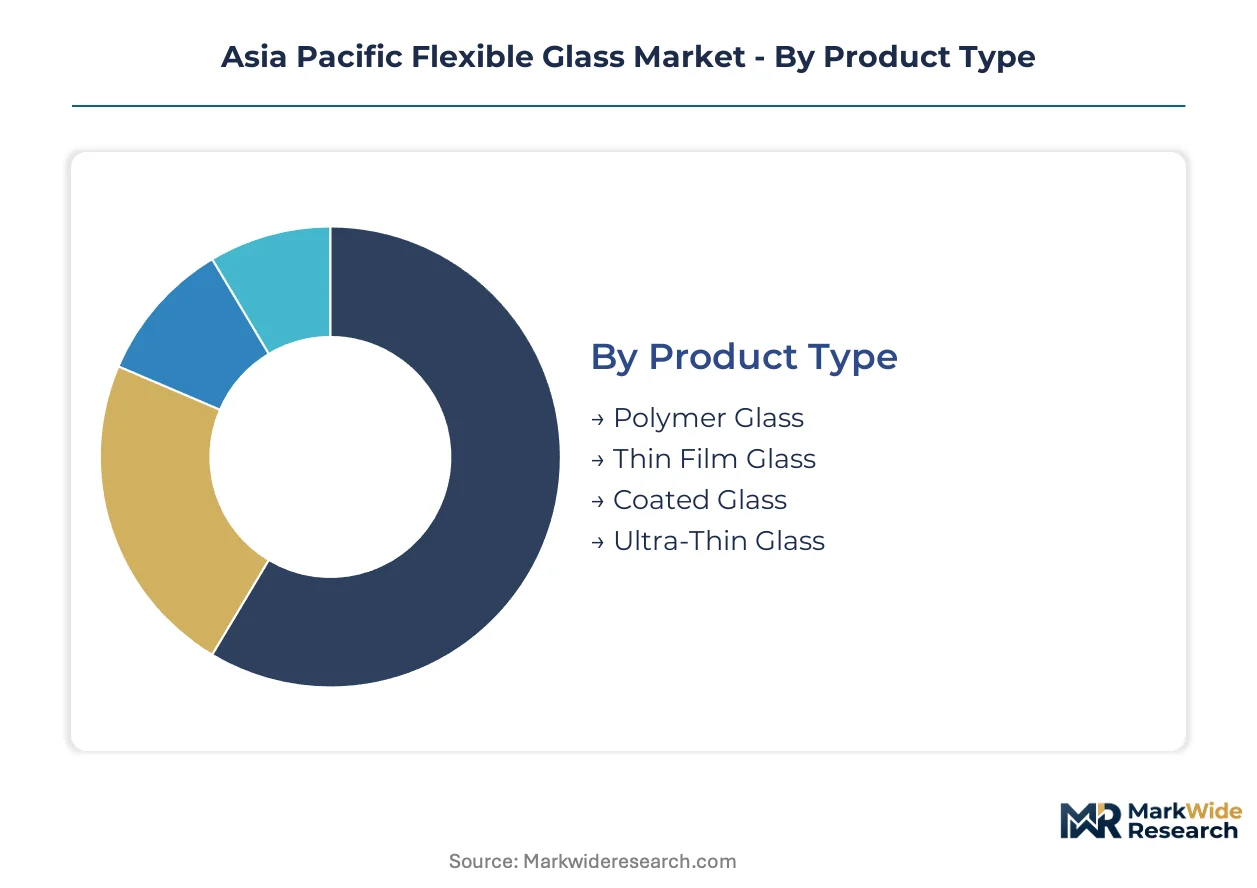
Flexible glass procurement in Asia Pacific fractures across performance tiers and manufacturing methods. Suppliers must calibrate product portfolios against distinct margin pools and certification burdens that vary sharply by segment.
Product Type:
Ultra-thin glass commands premium positioning through thickness tolerances below 0.1 millimeters, while polymer glass and coated variants compete on cost-adjusted performance for mid-tier applications.
- Ultra-Thin Glass:Alkali-free borosilicate substrates engineered to sub-0.1mm thickness enable bend radii under 5 millimeters without fracture. Samsung Display and BOE in South Korea and China concentrate procurement for foldable smartphone cover windows, with MIIT dual carbon goals accelerating low-temperature processing investments among domestic Chinese suppliers.
- Coated Glass:Anti-reflective and anti-fingerprint surface treatments differentiate automotive console applications from polycarbonate alternatives. Japanese OEMs in Toyota and Honda supply chains specify JIS C 60068 thermal shock compliance, filtering out uncertified Chinese entrants from premium cabin electronics procurement.
- Thin Film Glass:Sputtered or vapor-deposited layers on polymer carriers serve cost-sensitive touch panel applications in Guangdong display clusters.
- Polymer Glass:Hybrid organic-inorganic composites bridge performance gaps for disposable wearable sensors in Vietnam and India assembly operations.
Today's leader: Ultra-Thin Glass. Tomorrow's challenger: Coated Glass.
End User:
Consumer electronics concentrates procurement volume, yet automotive displays and wearables are fragmenting demand specifications across durability and form-factor requirements.
- Consumer Electronics:Foldable smartphones, tablets, and laptops absorb the majority of high-barrier substrate output. Korean panel makers Samsung Display and LG Display maintain backward-integrated supply chains, compressing third-party glass supplier margins while elevating technical certification thresholds for external entrants.
- Wearable Devices:Smartwatches and health monitors prioritize weight reduction over optical clarity. Taiwan-based mid-tier manufacturers adopt roll-to-roll atomic layer deposition to bypass batch-scale vacuum bottlenecks, enabling sub-premium pricing for fitness tracker cover lenses.
- Automotive Displays:Curved instrument panels and center consoles in Japanese and Korean premium vehicles displace polycarbonate with anti-reflective coated glass.
- Building and Construction:Smart window and facade applications remain nascent, constrained by GB standard thermal cycling requirements in Chinese commercial projects.
Consumer Electronics anchors current procurement; Wearable Devices are climbing the fastest as health monitoring form factors proliferate.
Application:
Flexible displays concentrate value capture, while touch panels and solar applications split between premium performance and cost-optimized specifications.
- Flexible Displays:Active-matrix organic light-emitting diode backplanes bonded to ultra-thin glass cover windows constitute the highest-margin application segment. Korean and Chinese panel clusters in Gyeonggi-do and Guangdong provinces drive specification convergence through shared technical committees.
- Touch Panels:Projected capacitive sensors for automotive and industrial interfaces favor coated glass variants with finger-resistant surfaces. Vietnamese assembly migration by Samsung and BOE backend operations is opening procurement channels outside Chinese tariff exposure.
- Solar Cells:Flexible photovoltaic encapsulation demands moisture barrier performance that chemical vapor deposition currently satisfies best.
- Lighting Solutions:Organic light-emitting diode luminaire substrates remain experimental, constrained by thermal management in roll-to-roll processing scale-up.
Flexible Displays dominate margin pools; Touch Panels are expanding most quickly through automotive console penetration.
Technology:
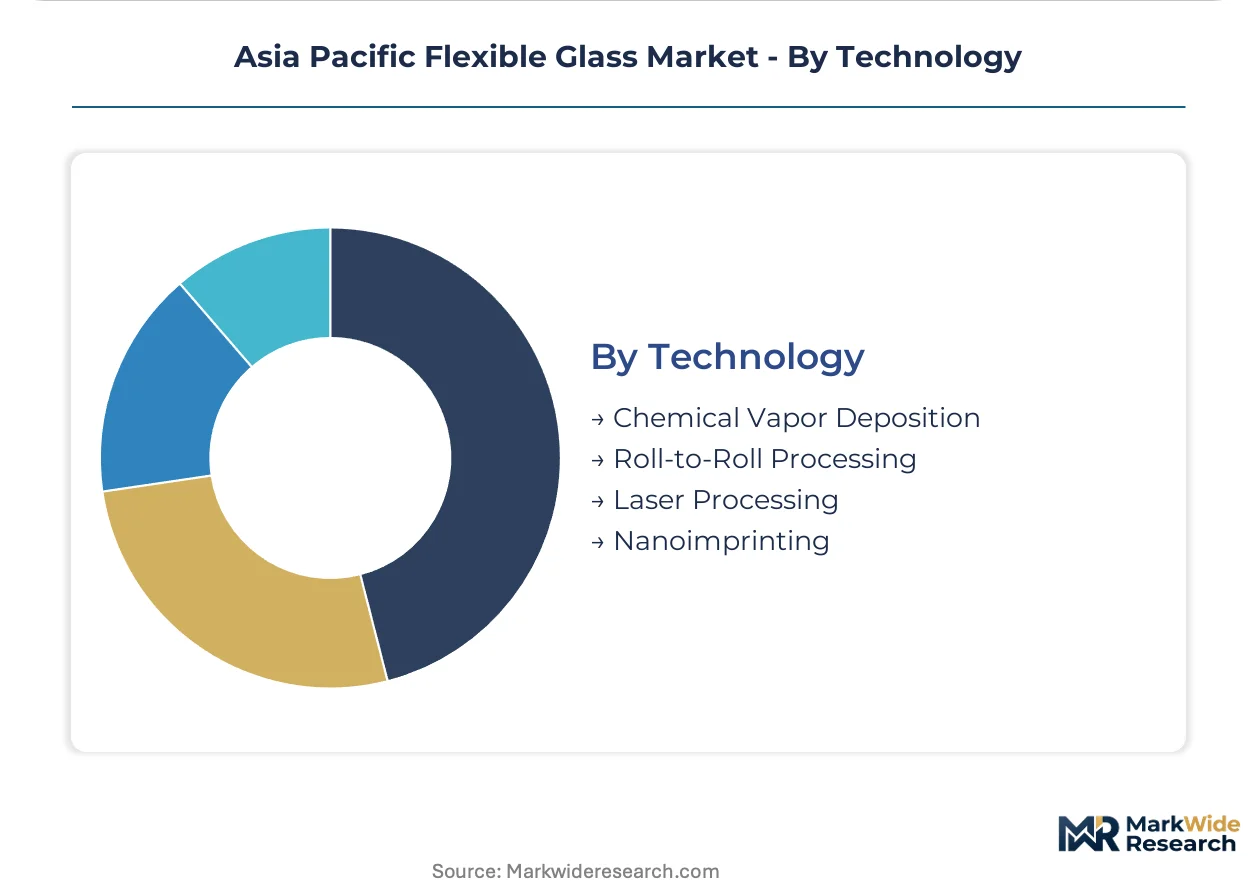
Batch chemical vapor deposition retains performance leadership for barrier films, yet continuous processing methods are rewriting economics for mid-tier volume segments.
- Chemical Vapor Deposition:Plasma-enhanced and low-pressure variants yield the highest-performance moisture and oxygen barriers for organic electronics. Japanese equipment suppliers in Tokyo and Osaka prefectures dominate tool installation, with METI export controls constraining technology transfer to Chinese substrate producers.
- Roll-to-Roll Processing:Continuous web handling of ultra-thin glass enables throughput scaling without flat-panel vacuum chamber bottlenecks. Taiwan and Vietnam wearable manufacturers adopt atomic layer deposition convergence to compress barrier deposition costs for fitness tracker cover lenses.
- Laser Processing:Precision cutting and edge strengthening of chemically tempered glass serves custom form-factor prototyping in Korean display R&D centers.
- Nanoimprinting:Pattern replication for anti-reflective surface structures remains confined to pilot-scale Japanese optical component suppliers.
Chemical Vapor Deposition holds the performance crown; Roll-to-Roll Processing is gaining share fastest through mid-tier wearable cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers and materials scientists cluster in South Korea's Gyeonggi-do corridor and Japan's Kansai region, anchoring the region's flexible glass innovation capacity. Chinese fabrication talent concentrates in Guangdong and Jiangsu provinces, where display panel ecosystems drive substrate specification expertise. Vietnamese assembly technicians in Bac Ninh and Thai process specialists in Rayong represent emerging workforce pools for backend integration.
China
Guangdong province absorbs the majority of ultra-thin glass procurement through BOE and TCL CSOT panel operations. MIIT dual carbon goals mandate low-temperature processing investments, accelerating domestic substrate certification programs. Shenzhen and Dongguan clusters now coordinate centralized purchasing through shared technical committees, compressing qualified supplier rosters by half.
South Korea
Samsung Display and LG Display dominate foldable cover window procurement through backward-integrated substrate operations. MFDS chemical safety protocols govern manufacturing process approvals, elevating testing burdens for external glass entrants. Gyeonggi-do's Suwon and Paju industrial belts concentrate pilot-scale to mass-production transitions for next-generation bendable form factors.
Japan
Nippon Electric Glass and AGC anchor high-barrier substrate development for premium automotive console applications. METI's 2024 JIS C 60068 revision imposes stricter thermal shock parameters, filtering uncertified suppliers from Toyota and Honda procurement channels. Osaka and Nagoya prefectures host specialized equipment suppliers whose plasma-enhanced deposition tools face export control constraints.
Vietnam
Samsung and BOE backend migration to Bac Ninh province opens procurement channels outside Chinese tariff exposure. Vietnamese regulators enforce chemical safety alignment with Korean MFDS standards for panel assembly operations. Ho Chi Minh City logistics corridors now route coated glass substrates for mid-tier wearable finishing operations.
India
Uttar Pradesh and Tamil Nadu smartphone assembly incentives under the electronics PLI scheme attract substrate finishing investments. BIS certification requirements for imported display materials create compliance hurdles for uncertified Chinese suppliers. Delhi-NCR technical institutes supply process engineering talent for emerging glass lamination operations.
Asia Pacific Flexible Glass Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct performance tiers. The vendor base stratifies between premium barrier film suppliers and mid-tier roll-to-roll processors. Three archetypes dominate: integrated panel makers with captive substrate operations, specialty glass manufacturers with chemical strengthening expertise, and coating specialists serving automotive anti-reflective specifications. Competitive moves center on capacity expansion in Vietnam and India, plus technology licensing partnerships to bypass METI export controls.
Among German specialty glass fabricators, SCHOTT AG occupies a position exemplifying high-barrier substrate leadership. Corning Incorporated represents US-based materials science conglomerates with regional R&D anchoring. Samsung Electronics sits within the integrated electronics archetype, leveraging captive supply chains for foldable device integration.
| Leading Market Players |
|---|
| Samsung Electronics |
| Nippon Electric Glass Co., Ltd. |
| Corning Incorporated |
| SCHOTT AG |
| Taiwan Glass Industry Corporation |
| AGC Inc. |
| LG Electronics |
| Asahi India Glass Limited |
| Xinyi Glass Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between JIS-compliant premium substrates and uncertified Chinese alternatives manifests in parallel supply chain configurations, with METI-mandated testing extending procurement lead times for Japanese automotive OEMs while compressing margins for domestic suppliers lacking barrier film expertise.
Pricing Analysis
Bundled chemical strengthening and barrier deposition services command 40-60% premiums over unbundled substrate-only transactions in Korean foldable display procurement. Price differentiation rests on MIIT dual carbon compliance certification and 100,000-cycle bend endurance documentation. Pricing pressure intensifies in mid-tier wearable segments as Taiwanese roll-to-roll processors compress barrier film costs through atomic layer deposition scale-up. Chinese display panel makers exhibit highest price sensitivity, while Japanese automotive OEMs prioritize performance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for chemically tempered glass edge trimming and strengthening salt recovery concentrate in Gyeonggi-do and Guangdong province processing hubs. Primary supply draws from German and Japanese specialty glass fabricators for premium ultra-thin substrates, with Vietnamese bauxite processors feeding aluminosilicate raw material streams. Single-source vulnerability persists in plasma-enhanced deposition equipment where METI export controls constrain technology transfer. Distribution runs through designated panel supplier programs coordinating BOE, TCL CSOT, and Tianma procurement in centralized technical committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where METI's 2024 JIS C 60068 revision tightens thermal shock parameters and accelerates demand for certified substrate suppliers capable of documented compliance.
For Market Incumbents: To counter captive Korean supply chain expansion by Samsung Display and LG Display, SCHOTT AG and Corning should deepen R&D partnerships with emerging Vietnamese panel assembly operations while securing MIIT dual carbon certification for Chinese low-temperature processing investments. Backward integration into high-purity alumina sourcing mitigates Australian and Vietnamese bauxite volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in mid-tier wearable barrier films offers entry positioning through roll-to-roll atomic layer deposition convergence in Taiwan and Vietnam. Target India's Uttar Pradesh and Tamil Nadu smartphone assembly corridors under electronics PLI scheme incentives, emphasizing BIS certification completion ahead of substrate finishing operations deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where JIS certification bottlenecks filter uncertified Chinese suppliers from Japanese automotive procurement channels. Long-term viability favors specialty glass fabricators with chemical strengthening expertise and established METI compliance documentation. Monitor Samsung Display's pilot-to-mass-production volume transitions as inflection indicators for third-party substrate demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Dual Carbon Certification Investment | Low-temperature processing compliance unlocks BOE and TCL CSOT procurement channels in Guangdong clusters. |
| Vietnam Assembly Corridor Expansion | Bac Ninh province backend migration by Samsung and BOE opens tariff-advantaged substrate finishing operations. |
| Roll-to-Roll ALD Technology Licensing | Atomic layer deposition convergence enables mid-tier wearable entry at sub-premium barrier film price points. |
| JIS C 60068 Testing Infrastructure Buildout | In-house thermal shock validation preempts third-party laboratory bottlenecks for Japanese automotive qualification. |
| India PLI Scheme Localization | Uttar Pradesh and Tamil Nadu smartphone assembly incentives attract substrate finishing capacity outside Chinese tariff exposure. |
Study Parameters
Multiple input streams — primary interviews with display panel procurement directors, specialty glass R&D leads, and automotive electronics sourcing managers; secondary validation through MIIT dual carbon policy filings, METI JIS standard revision documents, and Korean MFDS chemical safety registrations; plus customs trade data and SEC 10-K materials science disclosures — were reconciled through bottom-up segment aggregation and top-down macro constraint triangulation.
Historical shipment trajectories were cross-referenced against panel maker capacity expansion announcements to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type performance tiers, end-use durability requirements, application-specific barrier specifications, and regional regulatory cluster variations. CAGRs were derived from iterative convergence between supply-side capacity buildouts and demand-pull indicators from foldable device form factor roadmaps.
Caveats apply where METI export control tightening or MIIT certification timeline acceleration could materially shift the outlook for technology transfer and market access. Practitioners should monitor Samsung Display mass-production ramp schedules and BOE Guangdong cluster procurement committee decisions for early signals of substrate demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Tempered Glass Market
Glass
Glass Insulator Market
Glass
Glass Manufacturing Market
Glass
Recycled Glass Aggregates Market
Glass
Solar Reflective Glass Market
Glass
Europe Glassware Market
Glass
Dynamic Glazing Market
Glass
China Flat Glass Market
Glass
Soda Feldspar Market
Glass
Recycled Glass Market
Glass
Sapphire Glass Market
Glass
Glass Block Market
Glass
Glass Mat Thermoplastic Market
Glass
Glass Mat Market
Glass
Antibacterial Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market