
 US Polycarbonate Market | 2026-2036
US Polycarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
US Polycarbonate Market Insights
Electric vehicle original equipment manufacturers is rotating demand toward lightweight, impact-resistant glazing and battery enclosure materials. Covestro AG leverages its Baytown, Texas production complex to sustain captive resin supply for North American automakers. SABIC anchors its position through backward integration into bisphenol-A feedstock and specialized compounding operations. Trinseo competes on optical-grade purity for LED lighting and display applications.
Polycarbonate denotes a thermoplastic polymer synthesized from bisphenol-A and phosgene, exhibiting glass-like transparency with impact resistance roughly 250 times that of silicate glass and service temperatures up to 147°C. The material serves primarily as a engineering substitute for glass and acrylic in applications demanding dimensional stability under thermal load. Resin commands the dominant volume share as the feedstock base for downstream sheet extrusion and injection molding, while optical-grade material captures disproportionate margin pools in medical device and precision lighting segments. Flame-retardant formulations are gaining fastest traction as UL 94 V-0 compliance becomes mandatory for electronics housings and EV battery components.
EPA tailpipe emission rules and NHTSA corporate average fuel economy standards directly incentivize automotive lightweighting, expanding addressable volume for polycarbonate glazing and structural parts. FDA biocompatibility requirements and USP Class VI testing protocols govern medical device-grade resin qualification, creating barrier-to-entry dynamics for optical-grade suppliers. Stakeholders must monitor California Air Resources Board zero-emission vehicle mandates and pending revisions to OSHA phosgene exposure limits, as both will reshape raw material costs and plant siting decisions.
Market Dynamics
Automotive electrification is compressing material substitution cycles as OEMs race to shed vehicle weight without compromising crash performance or optical clarity. EPA tailpipe emission rules and NHTSA fuel economy standards now treat polycarbonate glazing and battery enclosures as compliance-critical components rather than discretionary upgrades.
Growth Catalysts
- EV Battery Enclosure Demand:Polycarbonate flame-retardant formulations meeting UL 94 V-0 standards are displacing metal in battery housings as thermal runaway protection becomes mandatory.
- NHTSA Lightweighting Mandates:Corporate average fuel economy standards force automakers toward polycarbonate windshields and panoramic roofs that cut mass versus laminated glass.
- Midwest Manufacturing Density:Tier 1 automotive suppliers clustered around Detroit and Chicago create localized resin offtake corridors with just-in-time delivery requirements.
Market Restraints
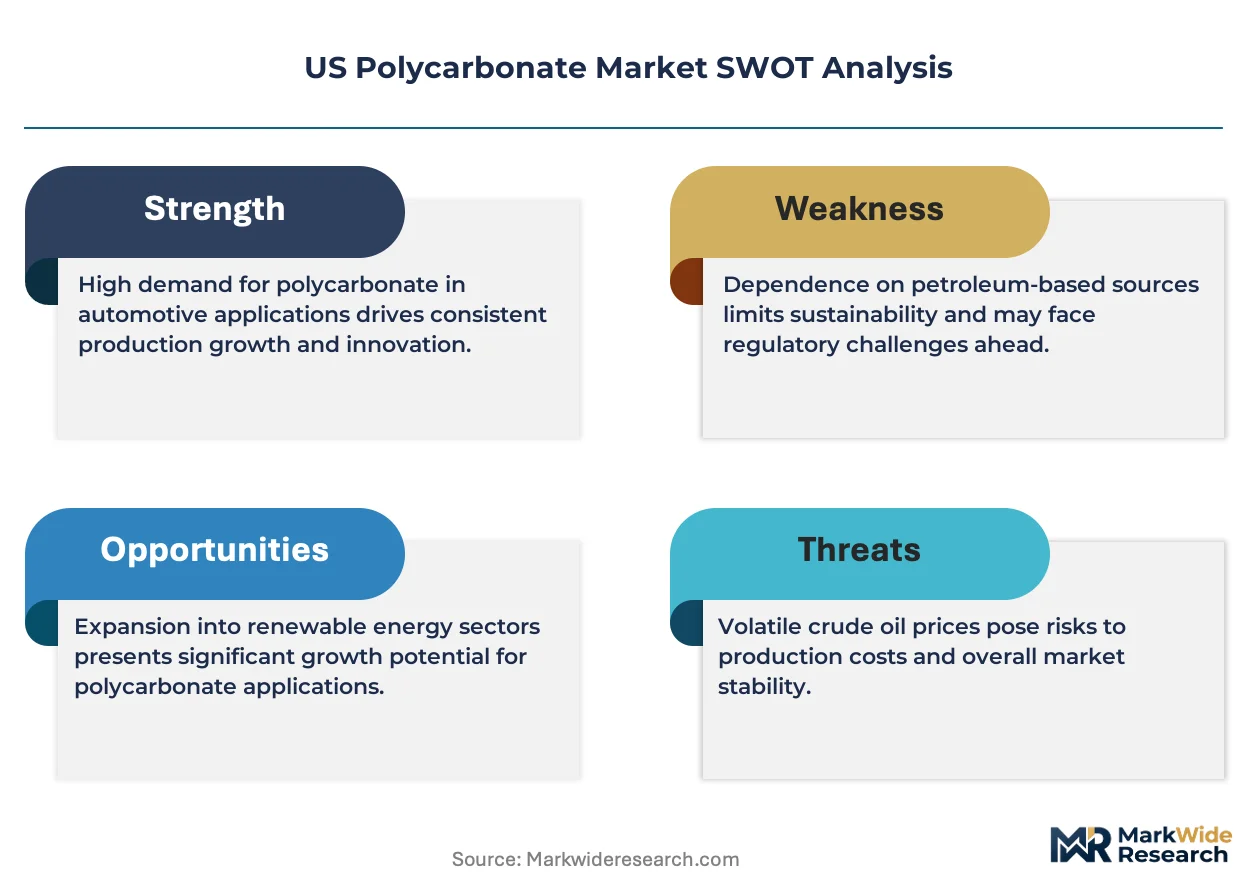
- Bisphenol-A Feedstock Volatility:Crude oil price swings and refinery capacity constraints transmit directly to polycarbonate resin cost structures.
- Phosgene Regulatory Friction:OSHA exposure limit revisions under consideration would force plant retrofits or alternative chemistry investments at Gulf Coast production sites.
- Acrylic Substitution Threat:PMMA advances in optical clarity and scratch resistance challenge polycarbonate dominance in non-impact lighting applications.
Strategic Opportunities
- Medical Device-Grade Resin:FDA biocompatibility and USP Class VI testing protocols create margin pools for suppliers qualifying optical-grade material for surgical instruments and diagnostic housings.
- LED Lighting Convergence:Polycarbonate collimator lenses combining thermal management with light diffusion are penetrating architectural and automotive forward-lighting segments.
- California ZEV Procurement:Air Resources Board zero-emission vehicle mandates accelerate polycarbonate adoption in charging station enclosures and EV interior trim.
Industry Challenges
- Optical-Grade Purification Capex:Medical and lighting applications require capital-intensive melt filtration and contamination control systems that extend payback periods.
- Multi-Regulatory Certification Timelines:Simultaneous FDA, EPA, and NHTSA qualification processes stretch product development cycles and strain technical documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Polycarbonate Market |
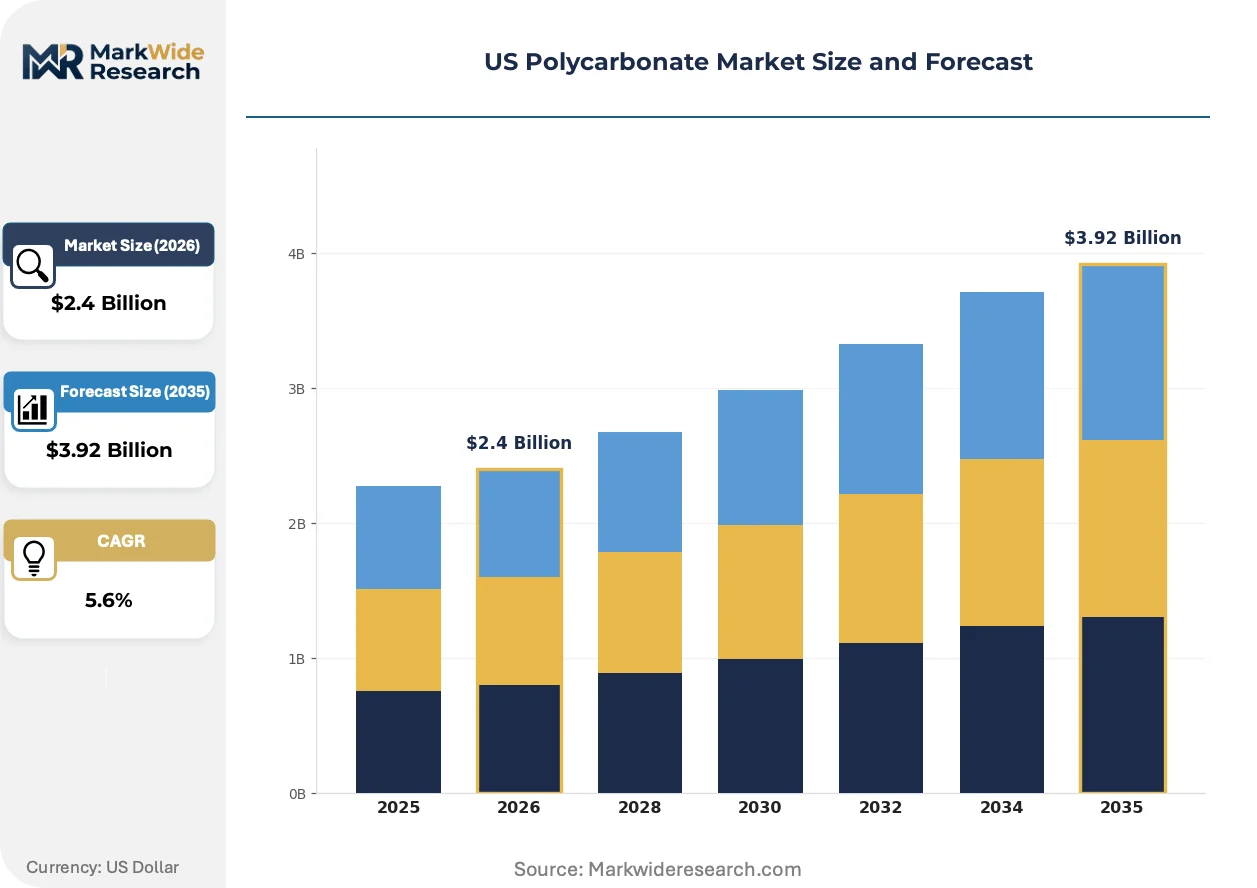
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Films, Resin, Blends End User: Automotive, Electronics, Construction, Aerospace Application: Optical, Safety Equipment, Lighting, Medical Devices Grade: General Purpose, High Impact, Optical Grade, Flame Retardant |
| Companies Covered | Covestro AG, SABIC, Mitsubishi Chemical Group Corporation, Teijin Limited, LG Chem, Trinseo, BASF Corporation, Idemitsu Kosan, Lotte Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Polycarbonate Market Trends and Innovations
Material science advances and regulatory ratcheting are compressing traditional substitution boundaries between polymers, glass, and metal in automotive and electronics applications.
Co-extruded polycarbonate-acrylic laminates are displacing monolithic polycarbonate in automotive glazing as OEMs seek to combine impact resistance with surface hardness without secondary coatings. Ford and General Motors have qualified these hybrids for windshield trials. The technology is displacing conventional hard-coated polycarbonate in premium vehicle segments and compressing the addressable market for standalone optical-grade resin.
EPA vehicle weight standards and NHTSA safety regulations are tightening in tandem, creating overlapping compliance obligations that favor materials satisfying multiple performance thresholds simultaneously. Polycarbonate suppliers must now validate flame retardancy, optical clarity, and impact resistance under single test protocols. Battery enclosure manufacturers face the steepest certification burden as UL 94 V-0 compliance becomes non-negotiable for EV platform approvals.
Automotive OEM procurement departments are consolidating resin suppliers to reduce qualification overhead and secure volume commitments for multi-platform launches. Tier 1 suppliers now face sole-source or dual-source mandates that favor producers with captive bisphenol-A supply and compounding capabilities. The purchasing concentration is most visible in the Midwest manufacturing belt, where Detroit-based buyers are extracting price-volume agreements from Baytown and Illinois production complexes.
US Polycarbonate Market Segmentation
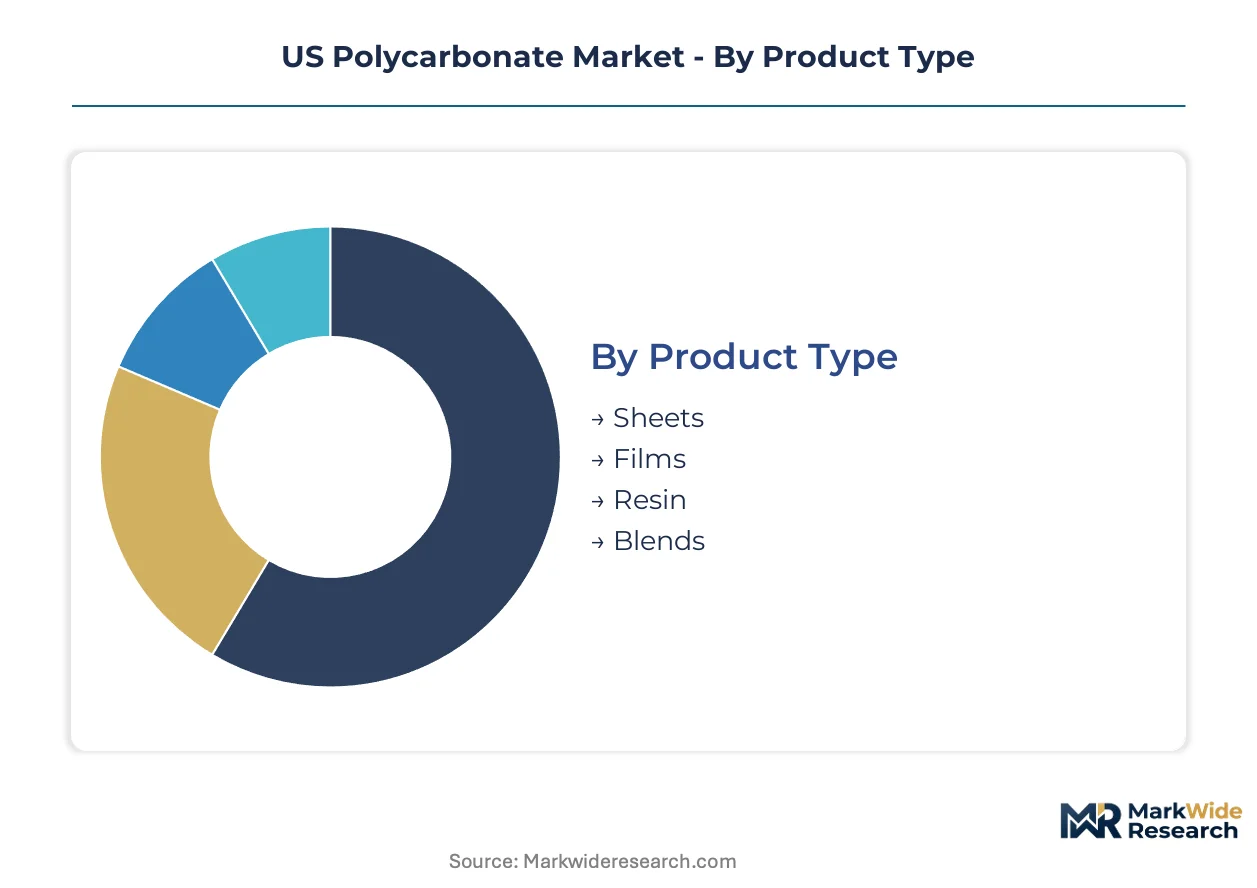
Polycarbonate segmentation in the US market tracks divergent regulatory pathways—automotive lightweighting mandates, FDA biocompatibility protocols, and UL 94 flammability standards each favor distinct material grades and form factors. Suppliers configure production assets around these compliance clusters rather than generic volume tiers.
Product Type:
FDA, EPA, and NHTSA specifications dictate which resin forms qualify for downstream conversion, creating rigid segmentation boundaries between extrudable sheet stock and injection-molding feedstock.
- Sheets:Extruded flat and multiwall configurations serve greenhouse glazing, aircraft windows, and riot shield fabrication. Midwest automotive suppliers around Detroit source co-extruded sheet for panoramic roof trials under NHTSA weight reduction programs.
- Films:Thin-gauge optical and graphic overlay films carry tight thickness tolerances for membrane switch interfaces and display diffusers. Demand concentrates in electronics manufacturing corridors where FCC-compliant device housings require EMI-shielding laminates.
- Resin:Pelletized feedstock dominates volume throughput as the foundational input for injection molding and compounding operations. Captive bisphenol-A integration at Gulf Coast complexes secures supply security for high-volume automotive contracts.
- Blends:Polycarbonate-ABS and polycarbonate-polyester alloys balance processability with thermal resistance for appliance housings and power tool enclosures. Formulators tune rubber content to meet Izod impact specifications without sacrificing Vicat softening points.
Resin handles the majority of throughput; films are gaining share fastest on electronics miniaturization and display layer proliferation.
End User:
Customer procurement patterns split between specification-driven OEMs with captive resin qualification teams and distributor-mediated buyers seeking standardized grades.
- Automotive:OEM engineering groups specify polycarbonate for glazing, interior trim, and battery enclosures under EPA tailpipe and NHTSA fuel economy compliance pressure. Electrification programs at Detroit-area assemblers are accelerating substitution trials for laminated glass.
- Electronics:Device manufacturers source flame-retardant grades for laptop housings, server chassis, and EV charging station enclosures. UL 94 V-0 certification has become a non-negotiable gate for platform approval at major contract manufacturers.
- Construction:Architectural glazing and daylighting systems exploit polycarbonate's thermal insulation versus glass. Building code officials in California and Florida are updating wind-load and fire-resistance tables to accommodate structural polycarbonate panels.
- Aerospace:Cabin interior components and cockpit transparencies demand traceable lot certification and extended supply chain documentation. FAA material qualification timelines stretch 18-36 months for new resin formulations.
Automotive commands the dominant revenue share; electronics represents the steepest expansion trajectory on EV infrastructure buildout.
Application:
Functional performance requirements—optical clarity, impact resistance, or biocompatibility—determine grade selection more than end-use industry affiliation.
- Optical:Lens-grade resin with birefringence control below 10 nm serves LED collimators, camera lenses, and virtual reality headsets. Medical device manufacturers in Massachusetts and Minnesota require USP Class VI and ISO 10993 validation for diagnostic instrument windows.
- Safety Equipment:High-impact grades with notched Izod values exceeding 800 J/m fabricate face shields, ballistic visors, and industrial hard hat components. OSHA personal protective equipment standards mandate optical clarity retention after multiple sterilization cycles.
- Lighting:Diffuser sheets and LED housing materials combine light transmission above 85% with thermal stability to 130°C. Architectural fixture manufacturers specify UV-stabilized grades for outdoor luminaire lenses subject to California Title 24 energy code compliance.
- Medical Devices:Surgical instrument housings, dialysis machine components, and drug delivery systems require gamma-stable, biocompatible formulations. FDA 510(k) submission pathways favor suppliers with established drug master files and dedicated cleanroom compounding lines.
Optical applications anchor margin pools; medical devices are expanding most quickly on diagnostic equipment reshoring.
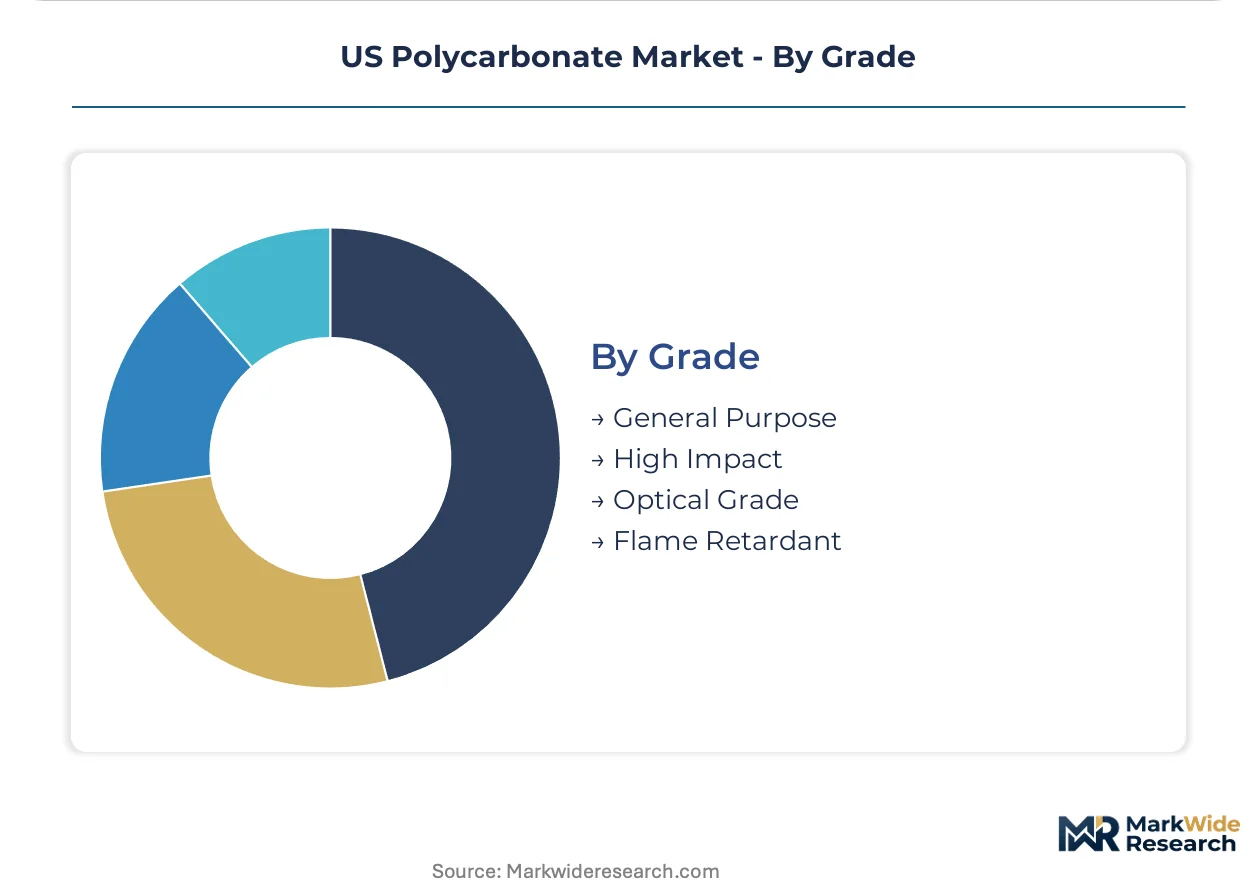
Grade:
Material differentiation follows a clear hierarchy from commodity general-purpose resin to specification-locked optical and flame-retardant variants with extended qualification barriers.
- General Purpose:Standard melt-flow index resins serve undemanding packaging, signage, and consumer goods applications. Price-sensitive buyers in the construction sector specify these grades where impact requirements fall below 200 J/m.
- High Impact:Rubber-modified formulations with Izod values above 600 J/m target automotive bumpers, sporting goods, and industrial machinery guards. Tier 1 suppliers in Ohio and Indiana qualify these grades for pedestrian safety compliance under NHTSA test protocols.
- Optical Grade:Ultra-purified resin with haze below 1% and yellowness index under 3.0 serves precision lighting, medical imaging, and automotive headlamp lenses. Melt filtration to 5-micron levels and contamination-controlled packaging command 40-60% premiums over general-purpose material.
- Flame Retardant:Halogen-free and brominated formulations meeting UL 94 V-0 and 5VA ratings penetrate EV battery enclosures, server farms, and mass transit interiors. California Air Resources Board toxicant restrictions are pushing formulation shifts from halogenated to phosphorus-based systems.
General-purpose resin moves the highest tonnage; flame-retardant grades are climbing the fastest on electrification safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel and Port of Corpus Christi anchor Gulf Coast resin distribution, with barge and rail links feeding Midwest automotive clusters and Eastern electronics corridors.
Texas Gulf Coast
Baytown and Corpus Christi host integrated bisphenol-A and polycarbonate complexes supplying captive resin to automakers. OSHA phosgene exposure rule revisions threaten retrofit costs at these production sites. Covestro's Baytown facility ships resin via the Houston Ship Channel to Detroit-area Tier 1 suppliers under just-in-time contracts.
Midwest Manufacturing Belt
Detroit and Chicago concentrate battery enclosure and glazing demand from electrifying OEM platforms. NHTSA corporate average fuel economy standards force automakers toward polycarbonate windshields and panoramic roofs. Ohio and Indiana injection molders qualify high-impact grades for pedestrian safety compliance.
Southeast Automotive Corridor
BMW's South Carolina assembly plant and Tennessee EV battery factories pull flame-retardant grades for thermal runaway protection. California Air Resources Board zero-emission vehicle mandates indirectly accelerate procurement through Southeastern EV supply chain migration. Georgia and Alabama compounders serve charging station enclosure manufacturers.
Northeast Medical Device Cluster
Massachusetts and Minnesota diagnostic instrument manufacturers demand USP Class VI validated optical-grade resin. FDA biocompatibility protocols create extended qualification barriers for surgical instrument housings. Greater Boston cleanroom compounders process gamma-stable formulations for drug delivery systems.
Pacific Northwest Electronics Hub
Washington and Oregon device manufacturers source UL 94 V-0 certified resin for laptop housings and server chassis. FCC electromagnetic interference standards favor polycarbonate-ABS blends with conductive fillers. Portland-area distributors stock optical films for display diffuser applications.
US Polycarbonate Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates possessing captive bisphenol-A supply and Gulf Coast production assets. The vendor base stratifies between scale-driven resin producers, specialized optical-grade compounders, and regional distribution intermediaries. Three archetypes dominate: backward-integrated chemical majors, medical-grade purification specialists, and automotive-focused compounders. Capacity expansion and qualification-driven customer lock-in represent the primary competitive vectors.
Among German-integrated chemical majors, Covestro AG anchors the scale-driven tier with Baytown production complex access. Saudi Basic Industries Corporation exemplifies feedstock-secured positioning through bisphenol-A integration. Trinseo occupies a position within the specialty-compounder archetype, serving optical purity requirements for LED and medical applications. These three represent distinct strategic postures: captive supply security, upstream raw material control, and downstream formulation specialization.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| Mitsubishi Chemical Group Corporation |
| Teijin Limited |
| LG Chem |
| Trinseo |
| BASF Corporation |
| Idemitsu Kosan |
| Lotte Chemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Automotive glass substitution compresses resin procurement cycles while simultaneously stretching supply geography from Gulf Coast petrochemical complexes to Midwest just-in-time assembly lines. This dual pressure reshapes how polycarbonate producers negotiate contract structures and manage working capital against volatile bisphenol-A feedstock costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by optical-grade certification and captive bisphenol-A integration status. Price differentiation hinges on UL 94 V-0 flame-retardant qualification and volume-scale commitments from Detroit-based OEM procurement desks. Cost compression in general-purpose resin is intensifying because acrylic advances in optical clarity erode polycarbonate's lighting application dominance. Tier 1 automotive suppliers exhibit lowest price sensitivity due to sole-source mandates, while construction distributors remain most elastic to spot-market fluctuations.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive offtake corridors, forcing resin producers to maintain buffer stocks at regional compounding facilities near Detroit and Chicago. Supply concentrates in the United States, Germany, and Saudi Arabia through integrated bisphenol-A complexes. Raw material dependencies center on crude oil derivatives, chlorine feedstock for phosgene synthesis, and specialty additive packages for flame-retardant formulations. Single-source vulnerability threatens Gulf Coast production sites facing OSHA phosgene exposure rule revisions. Distribution runs through barge-rail intermodal networks linking Houston Ship Channel terminals to Midwest manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarbonate incumbents face sustained substitution defense as co-extruded polycarbonate-acrylic laminates displace monolithic resin in premium automotive glazing trials.
For Market Incumbents: Compound optical-grade purification capabilities to defend margin pools against hybrid laminate displacement in NHTSA-compliant windshield programs. Deepen backward integration into bisphenol-A feedstock to offset crude oil volatility transmission. Prioritize UL 94 V-0 certification investments for EV battery enclosure contracts before platform standardization locks in supplier relationships. For New Entrants and Emerging Players: Lead with medical device-grade resin qualification targeting Massachusetts and Minnesota diagnostic instrument manufacturers where USP Class VI validation creates extended barrier-to-entry dynamics. Exploit optical film demand proliferation in Pacific Northwest electronics corridors for display diffuser applications. Pursue toll-compounding partnerships with established Gulf Coast resin producers to bypass capital-intensive melt filtration infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive compounders lacking captive feedstock integration. Long-term viability across the analysis window favors producers with dual-stream revenue from both commodity resin volume and specification-locked optical grades. Monitor California Air Resources Board zero-emission vehicle mandate acceleration as inflection signal for EV infrastructure polycarbonate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A | Covestro's Baytown complex secures feedstock cost stability against crude oil volatility. |
| Optical-Grade Purification Capacity | Medical device qualification in Massachusetts commands 40-60% premiums over general-purpose resin. |
| Flame-Retardant Formulation Development | UL 94 V-0 certification opens EV battery enclosure procurement at Detroit OEMs. |
| Regional Compounding Facility Expansion | Midwest proximity satisfies Tier 1 just-in-time delivery requirements under NHTSA programs. |
| Co-Extruded Laminate Partnership | Ford and General Motors trials signal hybrid technology adoption in premium vehicle segments. |
Research Methodology
Desk research of customs trade databases, American Chemistry Council industry reports, and SEC 10-K filings preceded structured interviews with polycarbonate plant managers, Tier 1 automotive procurement leads, and medical device regulatory affairs directors. Primary fieldwork with distribution channel partners and technical R&D directors at compounding facilities validated secondary data on grade-specific margin structures. Bottom-up resin volume estimates triangulated against top-down automotive lightweighting penetration assumptions.
Variance decomposition across grade tier, end-use industry, and regional production hub segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression against EPA vehicle weight standard stringency indices and NHTSA corporate average fuel economy compliance trajectories. Modeled inputs included EV platform launch schedules and FDA 510(k) submission velocity for diagnostic device housings.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment or OSHA phosgene rule implementation would require recalibration. Forecasts reflect assumptions regarding bisphenol-A cost pass-through elasticity and acrylic substitution velocity in non-impact lighting. Revision becomes warranted when California Air Resources Board zero-emission vehicle procurement thresholds cross material supply adequacy thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Circular Polymers Market