
 Potassium Acetate Market | 2026-2036
Potassium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Acetate Market Analytics
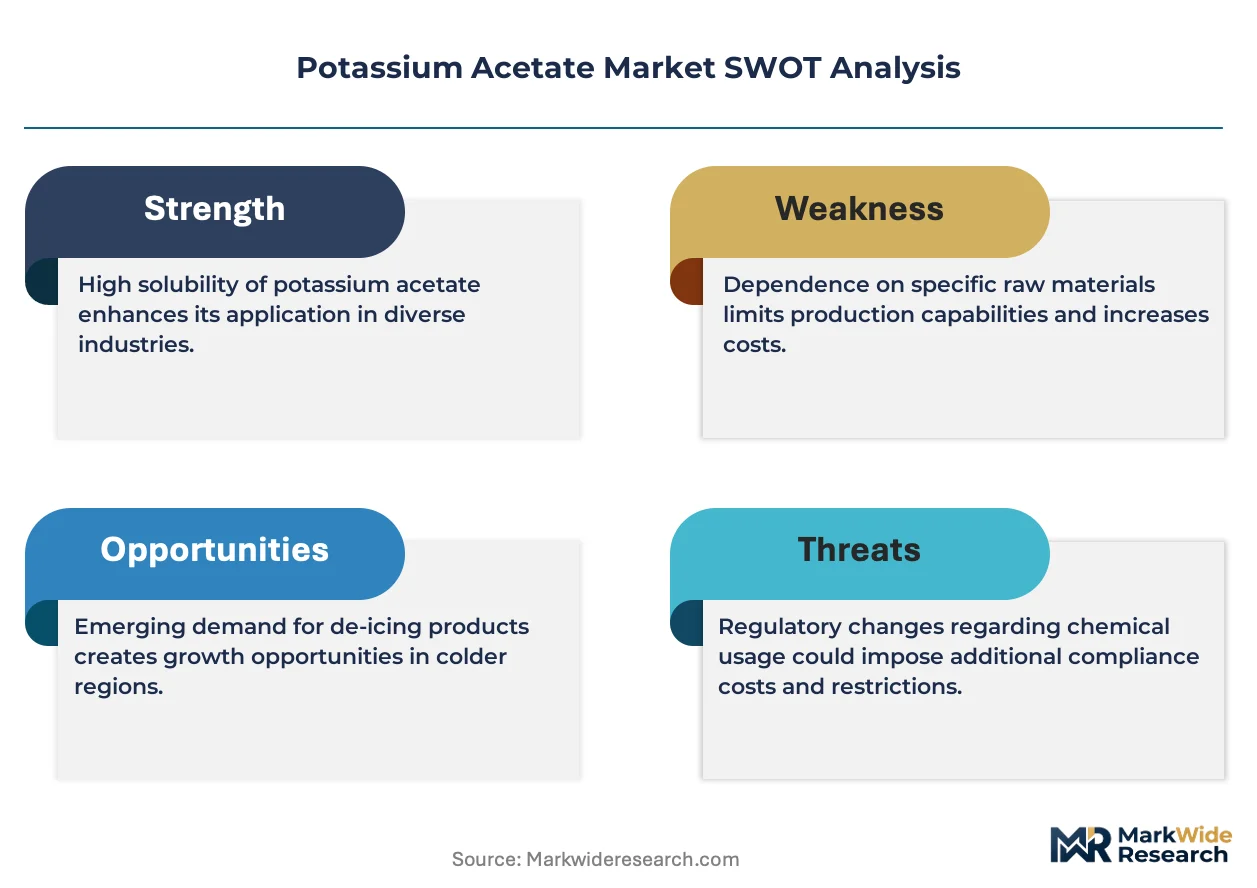
Sodium chloride is consolidating its displacement by potassium acetate in critical infrastructure deicing, as corrosion damage to reinforced concrete and steel accelerates material switching across municipal and aviation buyers. Niacet leverages its integrated acetic acid position to sustain cost-competitive crystalline grades for North American runway operators. BASF SE anchors European supply through its Ludwigshafen chemical complex, competing on specification consistency for pharmaceutical-grade material. Lancashire Chemicals specializes in regional UK distribution, occupying niche buffering-agent contracts with domestic biotech manufacturers.
Potassium acetate is the potassium salt of acetic acid, typically manufactured through neutralization of acetic acid with potassium carbonate or potassium hydroxide, yielding a hygroscopic crystalline solid or aqueous solution with melting point depression properties effective to approximately negative seventy-six degrees Fahrenheit. The compound serves primarily as a non-corrosive deicing agent for airport runways and sensitive concrete infrastructure, alongside pharmaceutical buffering and food-grade preservative functions. Deicing agents dominate volume demand as aviation authorities and highway agencies prioritize chloride-free alternatives, while food additives command premium pricing through stringent FCC and EP certification requirements. Pharmaceutical-grade crystals attract concentrated margin pools due to USP monograph compliance and batch-level documentation overhead.
EPA stormwater regulations and FAA airport certification standards constrain chloride runoff, directly expanding potassium acetate specification in federal and state procurement tenders across the United States. REACH registration and the EU Green Deal chemicals strategy pressure European deicing formulators toward biodegradable, low-toxicity alternatives, reinforcing potassium acetate positioning against urea and glycol blends. Stakeholders must monitor evolving EN 16811 deicing performance standards and state-level salt-reduction mandates to anticipate procurement specification shifts.
Market Dynamics
Chloride-based deicing salts face accelerating displacement as infrastructure corrosion costs mount and environmental regulators tighten runoff standards across transportation authorities.
Growth Catalysts
- EPA Stormwater Regulations:Federal constraints on chloride runoff from highway and airport operations are mandating specification switches to potassium acetate in state procurement contracts across the United States.
- Concrete Infrastructure Preservation:Municipal transportation departments prioritize non-corrosive alternatives to extend reinforced concrete service life on bridges and elevated highways.
- REACH Registration Compliance:European deicing formulators require biodegradable, low-toxicity substitutes as ECHA enforcement intensifies against legacy chloride formulations.
Market Restraints
- Acetic Acid Feedstock Volatility:Potassium acetate production costs track petrochemical-derived acetic acid pricing, exposing margins to energy market swings and refinery output fluctuations.
- Supplier Concentration in Ludwigshafen:European pharmaceutical-grade supply concentrates at BASF SE's German chemical complex, creating single-point vulnerability for specification-critical buyers.
- Performance Ceiling in Extreme Cold:Potassium acetate effectiveness degrades below negative seventy-six degrees Fahrenheit, limiting substitution potential in Arctic aviation and northern mining operations.
Strategic Opportunities
- Pharmaceutical Buffering Expansion:USP-grade crystal demand from biologics manufacturing offers concentrated margin pools as batch documentation requirements deter commodity entrants.
- Food-Grade Preservative Certification:FCC and EP-compliant material commands premium positioning against sodium-based alternatives in clean-label processed food formulations.
- Integrated Acetic Acid Positioning:Producers with captive acetic acid supply can defend crystalline grade competitiveness against merchant market dependent competitors.
Industry Challenges
- Pharmaceutical Compliance Timeline:USP monograph validation and batch-level documentation overhead extends qualification cycles for new manufacturing entrants seeking high-margin segments.
- Aviation Certification Burden:FAA airport certification standards require extensive runway friction testing and environmental impact documentation before potassium acetate specification approval.
- Formulation Integration Complexity:State transportation departments must retrain application crews and recalibrate spreading equipment optimized for granular chloride salts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Acetate Market |
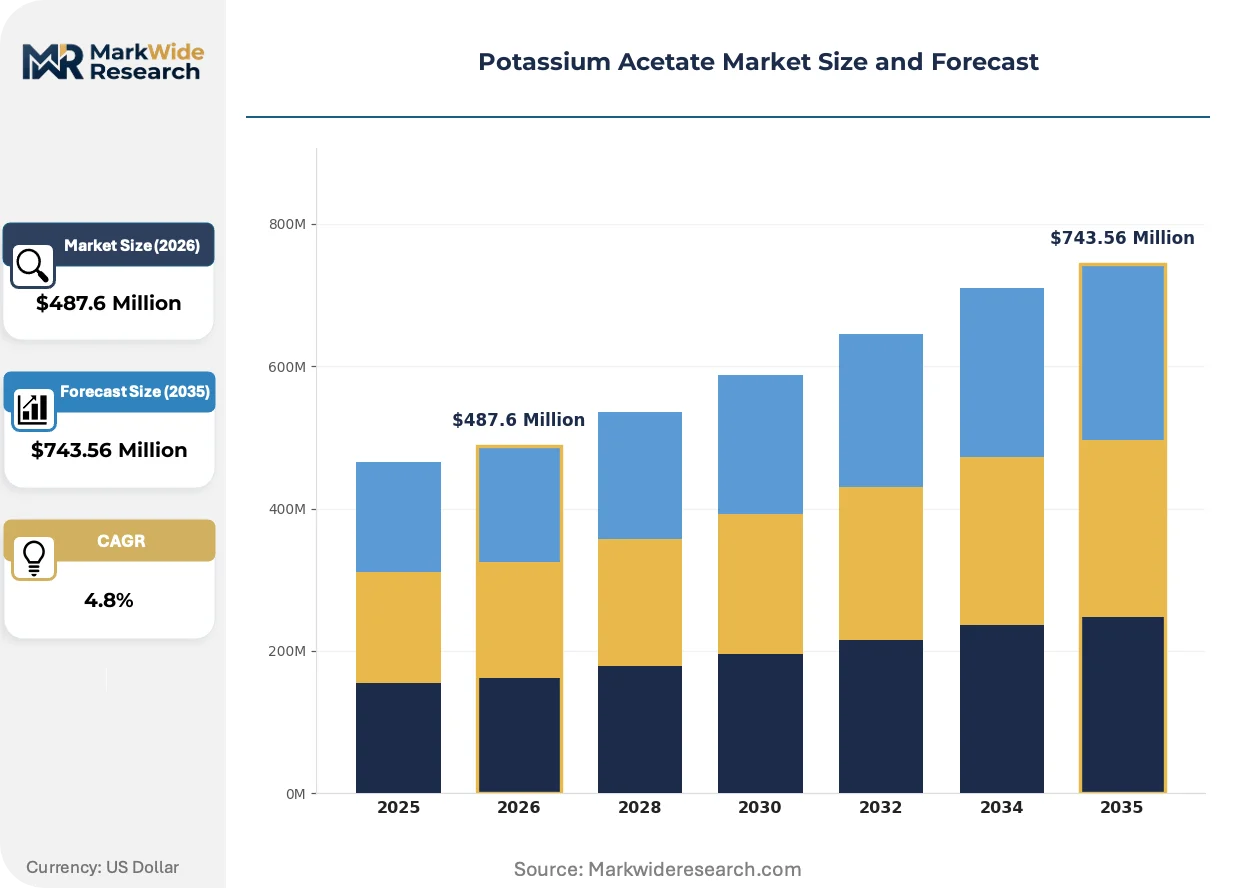
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Potassium Acetate, Potassium Acetate Solution, Potassium Acetate Granules, Potassium Acetate Crystals End Use Industry: Food Industry, Chemical Manufacturing, Pharmaceutical, Agriculture Application: Deicing Agents, Food Additives, Buffering Agents, Fertilizers Packaging Type: Bags, Drums, Bulk Containers, Bottles |
| Companies Covered | Niacet, Hawkins Inc., Lancashire Chemicals, Clariant, BASF SE, Cryotech, Wuxi Yangshan Biochemical, Alkem, Tessenderlo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Acetate Market Evolving Landscape
Automation of deicing application systems is compressing labor intensity and improving precision dosing on aviation runways. Formulation chemistry advances target performance extension into colder temperature bands.
Sensor-integrated spreader technology is automating real-time calibration of potassium acetate brine concentration based on pavement temperature and precipitation rates. Airport authorities in Germany and the United States are deploying these systems to minimize chemical over-application and reduce environmental discharge volumes. The technology is automating documentation compliance for EPA stormwater reporting and FAA certification audits.
REACH authorization timelines are compressing the window for chloride-based deicing re-registration across European member states. ECHA's prioritization of aquatic toxicity endpoints is elevating potassium acetate's biodegradability profile against calcium magnesium acetate and urea blends. Nordic aviation authorities are accelerating specification updates to preempt 2027 authorization cliff effects.
Long-term service contracts are displacing spot procurement for municipal highway deicing in the United States. State departments of transportation in Michigan and New York are consolidating multi-year supply agreements with performance guarantees on corrosion rates and application efficiency. This shift concentrates volume allocation among integrated producers with guaranteed acetic acid supply chains.
Potassium Acetate Market Segmentation
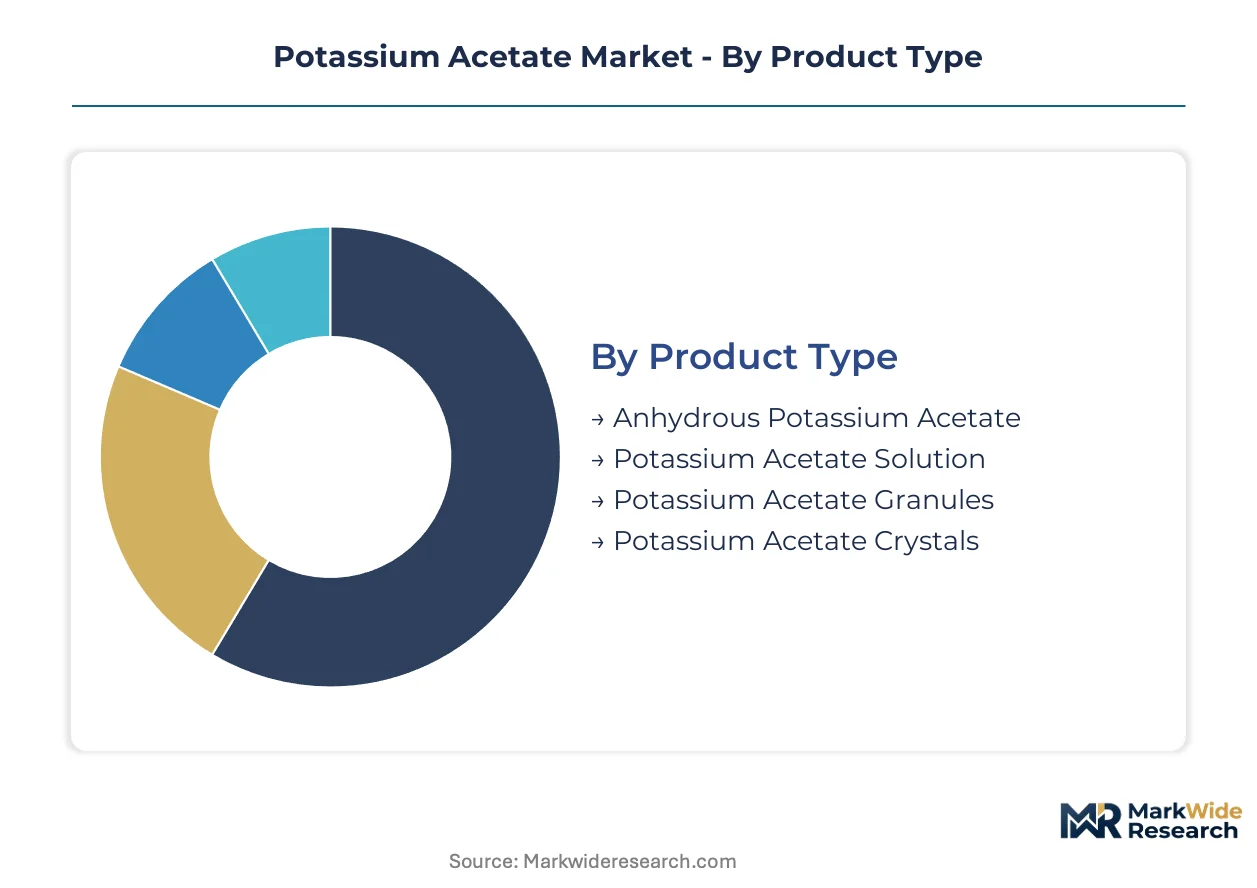
Potassium acetate specifications diverge sharply across buyer categories, with deicing operators prioritizing bulk solution economics while pharmaceutical and food manufacturers enforce monograph-grade crystalline standards. Segmentation reveals how formulation chemistry and certification requirements partition margin pools between commodity volume and premium specialty tiers.
Product Type:
Buyers select physical forms based on dissolution kinetics, storage constraints, and application equipment compatibility, with liquid solutions dominating runway operations and solid grades serving precision-dosing end-uses.
- Anhydrous Potassium Acetate:A moisture-free crystalline solid with hygroscopic properties requiring sealed storage systems. Demand concentrates in pharmaceutical manufacturing where USP monograph compliance mandates exact stoichiometry for intravenous buffer formulations.
- Potassium Acetate Solution:Pre-dissolved aqueous concentrate typically supplied at 50-60% concentration for direct spray application. State transportation departments in the United States specify brine solutions for automated runway deicing systems, prioritizing pump compatibility over dry-handling logistics.
- Potassium Acetate Granules:Free-flowing particulate form engineered for controlled dissolution rates in agricultural and industrial blending operations. The granule geometry suits bulk fertilizer compounding where uniform nutrient distribution is required.
- Potassium Acetate Crystals:High-purity geometric solids produced through controlled evaporation crystallization. FCC and EP certification requirements for food-grade preservatives drive specification rigor in processed meat and bakery applications.
Volume sits with Potassium Acetate Solution; growth tilts toward Anhydrous Potassium Acetate as biologics manufacturing expands buffer demand.
End Use Industry:
Industry verticals impose divergent compliance architectures, with food and pharmaceutical sectors extracting premium pricing through certification overhead that excludes commodity producers.
- Food Industry:Preservation and pH modulation applications in processed foods require FCC-compliant material with documented heavy metal limits and microbial specifications. Clean-label formulation trends in the United States and Europe are elevating potassium acetate against sodium-based alternatives.
- Pharmaceutical:USP-grade crystals serve as buffering excipients in sterile injectables and dialysis solutions. Batch-level documentation and validation protocols create qualification barriers that protect incumbent suppliers.
- Chemical Manufacturing:Intermediate consumption in acetic acid derivative synthesis and catalyst formulations. Demand tracks specialty chemical production cycles with lower certification burden than life-science segments.
- Agriculture:Potassium source in foliar fertilizers and soil amendments, competing with chloride and sulfate salts on nutrient cost-efficiency. Application rates depend on regional soil potassium deficiency mapping.
Revenue concentrates in Pharmaceutical; volume expansion is steepest in Food Industry as preservative substitution accelerates.
Application:
Functional performance requirements determine formulation specifications, with deicing prioritizing eutectic depression and food applications demanding taste neutrality.
- Deicing Agents:Non-corrosive runway and highway ice control leveraging potassium acetate's negative seventy-six degrees Fahrenheit effective temperature limit. FAA certification and EPA stormwater compliance mandate this application across United States aviation infrastructure.
- Buffering Agents:pH stabilization in bioprocessing and diagnostic reagents requiring precise acid-base equilibrium control. Pharmaceutical manufacturing in Germany and Switzerland drives specification-grade demand.
- Food Additives:Acidity regulation and antimicrobial preservation in processed foods. EP and FCC monograph compliance distinguishes premium-grade supply from technical material.
- Fertilizers:Potassium nutrition delivery with reduced chloride phytotoxicity versus muriate of potash. Specialty crop producers in California and Florida specify acetate-based formulations for chloride-sensitive cultivars.
Procurement scale favors Deicing Agents; margin capture is expanding most quickly in Buffering Agents as biologics manufacturing intensifies.
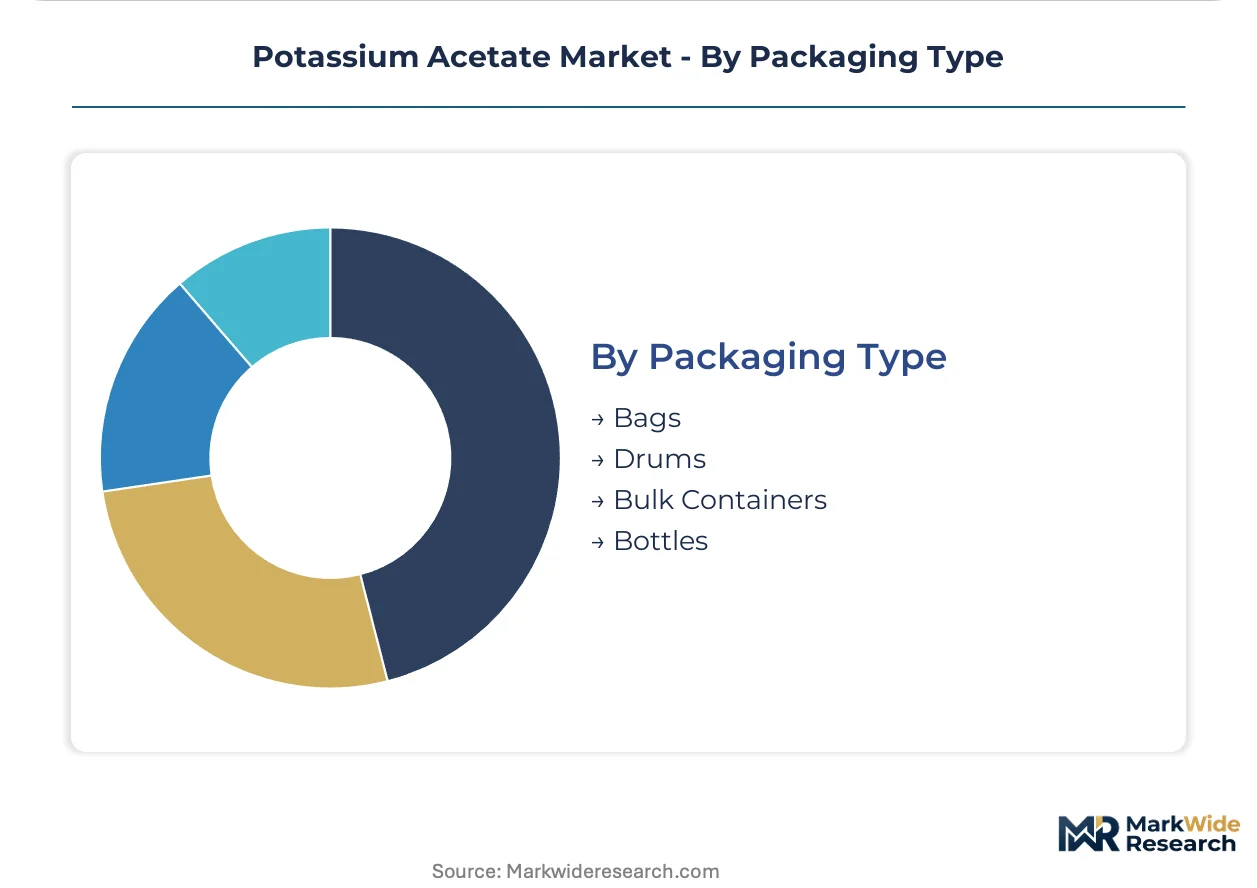
Packaging Type:
Logistics economics and contamination risk govern packaging selection, with bulk systems dominating high-volume deicing and sealed units protecting pharmaceutical integrity.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for deicing brine procurement by municipal and aviation authorities. Just-in-time inventory systems minimize storage degradation of hygroscopic material.
- Drums:Steel and fiber drums for chemical manufacturing and agricultural intermediate handling. UN certification requirements govern hazardous material transport classifications.
- Bags:Multi-layer moisture-barrier sacks for food-grade and technical-grade crystalline product. Palletization standards vary by regional distribution infrastructure.
- Bottles:Sterile and amber-glass configurations for pharmaceutical laboratory and small-batch production. USP packaging integrity testing validates seal performance.
Shipment volume concentrates in Bulk Containers; packaging specification complexity is climbing fastest in Bottles as pharmaceutical batch sizes contract toward personalized medicine formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State transportation departments in the United States command the largest procurement volumes for runway and highway deicing contracts. European aviation authorities are accelerating specification updates ahead of regulatory deadlines. Asian pharmaceutical manufacturers are expanding buffer chemical demand for biologics production.
United States
FAA airport certification standards and EPA stormwater regulations are mandating chloride-free deicing specifications across federal and state tenders. Michigan and New York departments of transportation have consolidated multi-year supply agreements with performance guarantees. The Midwest corridor concentrates aviation infrastructure investment where automated brine application systems are deploying.
Germany
ECHA enforcement of REACH authorization timelines is compressing the window for legacy chloride formulation re-registration. The EU Green Deal chemicals strategy prioritizes biodegradable alternatives in federal procurement guidelines. Ludwigshafen's chemical complex anchors European pharmaceutical-grade supply chains with specification-critical batch documentation.
United Kingdom
Highway England's salt-reduction mandates are elevating potassium acetate specification in bridge and elevated highway maintenance contracts. Domestic biotech manufacturers in the Cambridge-Oxford corridor are expanding buffering-agent procurement for diagnostic reagent production. Lancashire-based distributors occupy niche regional supply positions for food-grade preservative formulations.
China
MIIT industrial standards for airport infrastructure are incorporating non-corrosive deicing specifications in new construction guidelines. Dual carbon goals are pressuring municipal transportation departments toward lower-environmental-impact chemical alternatives. Wuxi-centered biochemical producers are scaling crystalline-grade capacity for export pharmaceutical markets.
Canada
Transport Canada aviation safety directives are aligning with FAA standards on runway friction performance and environmental discharge documentation. Provincial transportation ministries in Ontario and Quebec are piloting potassium acetate blends on critical bridge infrastructure. Prairie region mining operations face performance ceiling constraints in extreme cold applications below negative seventy-six degrees Fahrenheit.
Potassium Acetate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated acetic acid producers defending crystalline grade competitiveness against merchant-dependent rivals. The vendor base organizes around three strategic archetypes: captive feedstock operators, regional distribution specialists, and specification-grade certification holders. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around guaranteed acetic acid supply chains and multi-year service contract consolidation.
Among North American integrated producers, Niacet exemplifies the captive acetic acid archetype with cost-competitive positioning for crystalline grades. Hawkins Inc. occupies a distribution-consolidation role across municipal and aviation procurement channels. BASF SE anchors European pharmaceutical-grade supply through its Ludwigshafen complex, representing specification consistency for USP-monograph compliance. Lancashire Chemicals sits within the regional specialist tier, focusing on UK-centric buffering-agent contracts with domestic biotech manufacturers.
| Leading Market Players |
|---|
| Niacet |
| Hawkins Inc. |
| Lancashire Chemicals |
| Clariant |
| BASF SE |
| Cryotech |
| Wuxi Yangshan Biochemical |
| Alkem |
| Tessenderlo Group |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between USP-monograph pharmaceutical crystals and technical-grade deicing solutions manifests in pricing spreads exceeding three-to-one multiples, with supply chain configurations bifurcating between sealed sterile packaging for life-science buyers and bulk tanker logistics for municipal highway departments. Acetic acid feedstock volatility transmits directly into crystalline grade margins, while long-term offtake contracts insulate deicing operators from spot market swings.
Pricing Analysis
Volume-mass deicing solutions trade at commodity-competitive rates against chloride salts, while pharmaceutical-grade crystals capture concentrated margin pools through batch documentation overhead and USP validation requirements. Price differentiation hinges on certification tier and volume scale, with FCC-compliant food additives commanding mid-tier positioning. Pricing pressure stems from petrochemical feedstock volatility pressuring producers without captive acetic acid supply. Municipal transportation departments exhibit highest price sensitivity through competitive tender processes, while biologics manufacturers prioritize specification consistency over unit cost.
Supply Chain Analysis
Workforce availability constraints in Ludwigshafen, Wuxi, and the US Gulf Coast chemical corridor limit expansion velocity for pharmaceutical-grade crystalline capacity. Production draws from potassium carbonate and petrochemical-derived acetic acid feedstocks, with energy costs anchoring variable cost structures. Single-source vulnerability concentrates at BASF SE's German complex for European USP-grade supply. Distribution runs through regional chemical distributors for technical grades and direct manufacturer relationships for specification-critical pharmaceutical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetic acid supply constraints prop pricing power for integrated producers, with captive feedstock positioning defending margin structures against merchant-dependent competitors facing input volatility.
For Market Incumbents: Deepen backward integration into acetic acid supply to defend crystalline grade competitiveness against Niacet's integrated position. Expand capacity in the US Midwest corridor where Michigan and New York departments of transportation consolidate multi-year contracts. Address substitution risk from calcium magnesium acetate blends through performance documentation in EN 16811 compliance testing. For New Entrants and Emerging Players: Regional distributors in the UK Cambridge-Oxford biotech corridor offer partnership pathways into pharmaceutical buffering contracts with lower qualification barriers than USP-grade manufacturing. Target food-grade preservative formulations where FCC certification overhead excludes commodity entrants but batch scale remains accessible. Pursue private-label supply agreements with established European distributors lacking crystalline production assets. For Investors and Strategic Acquirers: Re-rating potential sits with integrated acetic acid producers given REACH authorization timelines compressing chloride substitution windows. Long-term viability favors producers with guaranteed feedstock supply and multi-year service contract backing from state transportation departments. Monitor ECHA enforcement intensity as inflection indicator for European deicing specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive feedstock supply defends crystalline grade margins against petrochemical volatility. |
| Long-term Supply Agreement | Michigan and New York DOT contracts concentrate volume allocation among guaranteed suppliers. |
| USP Monograph Certification | Batch documentation overhead creates qualification barriers protecting incumbent pharmaceutical suppliers. |
| Automated Brine Application System Deployment | German and US aviation authorities reduce over-application and environmental discharge volumes. |
| Green Manufacturing Transition | EU Green Deal chemicals strategy prioritizes biodegradable alternatives in federal procurement guidelines. |
Research Methodology
Trade databases, ECHA registration filings, and FAA airport certification standards formed the secondary backbone, cross-referenced against primary interviews with plant managers at integrated acetic acid producers, procurement leads at state transportation departments, pharmaceutical regulatory affairs directors, and distribution channel partners. Bottom-up volume triangulation across grade tiers and end-use segments was reconciled with top-down market sizing from customs data and industry association reports.
Historical trendline analysis across production capacity, feedstock pricing, and procurement contract structures informed the projection framework. Segmentation dimensions modeled include product form, certification grade, end-use industry vertical, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA stormwater regulation enforcement trajectories and biologics manufacturing expansion rates.
Caveats apply where acetic acid feedstock volatility, REACH authorization timeline delays, or aviation certification standard revisions could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and infrastructure investment continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Asia-Pacific Bio Transformer Oil Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
FCCL Coating Machine Market