
 Furnace Filters Market | 2026-2036
Furnace Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Furnace Filters Market Analytics
Market Context
Skilled HVAC technician shortages across North America is redrawing how manufacturers secure installer loyalty and specification pull-through. 3M Company leverages its Filtrete brand strength and retail channel control to sustain consumer mindshare in big-box and e-commerce outlets. Honeywell International Inc. anchors its position through backward integration into smart thermostat ecosystems that prompt automated filter replacement alerts. Lennox International Inc. competes by bundling proprietary filter formats with its furnace OEM installed base, creating captive aftermarket demand.
Technical Definition and Segments
Furnace filters are replaceable air-cleaning media installed within forced-air heating and cooling systems, typically rated by MERV values from 1 to 16 that quantify particle capture efficiency at specified airflow velocities. Their primary purpose is protecting heat exchanger and blower components from dust accumulation while reducing indoor airborne contaminants. Pleated synthetic media dominates value generation due to superior surface area and extended service intervals compared to flat fiberglass panels. Electrostatic and HEPA categories command premium positioning in residential and healthcare HVAC retrofits where allergen and pathogen capture justifies higher replacement costs. Activated carbon segments address odor and volatile organic compound removal in commercial kitchen and industrial process ventilation where gas-phase filtration supplements particulate control.
Regulatory Outlook
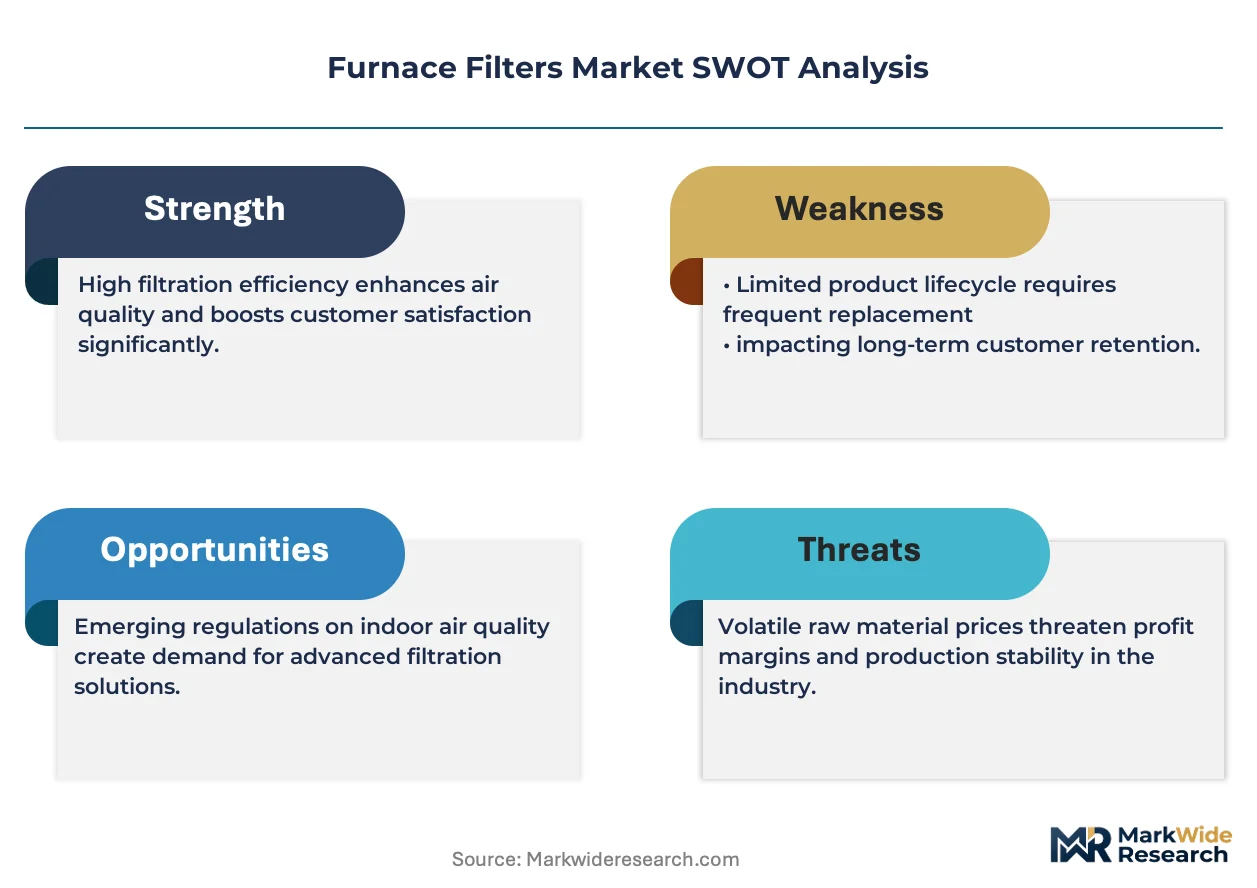
ASHRAE Standard 62.1 ventilation requirements and the U.S. EPA National Ambient Air Quality Standards tighten permissible particulate thresholds, directly elevating minimum MERV specifications in new construction and major renovations. The U.S. Department of Energy furnace efficiency regulations indirectly shape filter demand by mandating tighter duct systems that require more frequent media changes to prevent airflow restriction. Stakeholders must monitor how state-level building electrification mandates alter replacement cycle timing as heat pump conversions accelerate and hybrid heating configurations proliferate.
Market Dynamics
The furnace filters market is being fundamentally reshaped by the collision of tightening EPA particulate standards with chronic HVAC technician shortages, forcing manufacturers to redesign products for longer service intervals while securing specification loyalty through digital channel control.
Growth Catalysts
- ASHRAE 62.1 ventilation mandates:The standard's elevated outdoor air requirements in commercial buildings are accelerating MERV 13+ specification rates in new construction across the American Sun Belt.
- Electrostatic media technology:Synthetic fiber charging processes are capturing sub-micron particles without the airflow penalty of denser pleated alternatives, penetrating residential allergen-control segments.
- Heat pump conversion waves:State-level building electrification mandates in California, New York, and Washington are compressing replacement cycles as hybrid HVAC configurations proliferate.
Market Restraints
- Polypropylene resin volatility:Pleated filter manufacturing depends on petroleum-derived synthetic media whose input costs fluctuate with crude price swings, compressing margin stability for mid-tier producers.
- Skilled installer concentration:North American HVAC technician shortages are concentrating specification power with regional contractor chains, limiting brand access for non-vertically integrated suppliers.
- Flat fiberglass substitution:Price-sensitive rental housing and light commercial segments continue specifying minimum-efficiency disposable panels that undercut pleated upgrade penetration.
Strategic Opportunities
- Smart home ecosystem integration:Filter replacement alerts embedded in connected thermostat platforms are creating automated recurring revenue streams independent of traditional distribution.
- Activated carbon layering:Wildfire smoke events in the Pacific Northwest and Mountain West are driving demand for gas-phase filtration add-ons to standard particulate media.
- Healthcare HVAC retrofit:Hospital outpatient expansion and ambulatory surgery center construction are opening specification channels for HEPA-grade furnace-adapted products.
Industry Challenges
- MERV certification bottlenecks:Third-party testing laboratory capacity constraints are extending new product validation timelines, delaying seasonal product launches.
- Legacy system compatibility:Aging furnace installed bases with restricted blower motor capacity cannot accommodate higher-efficiency media without airflow recalculation and duct modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furnace Filters Market |
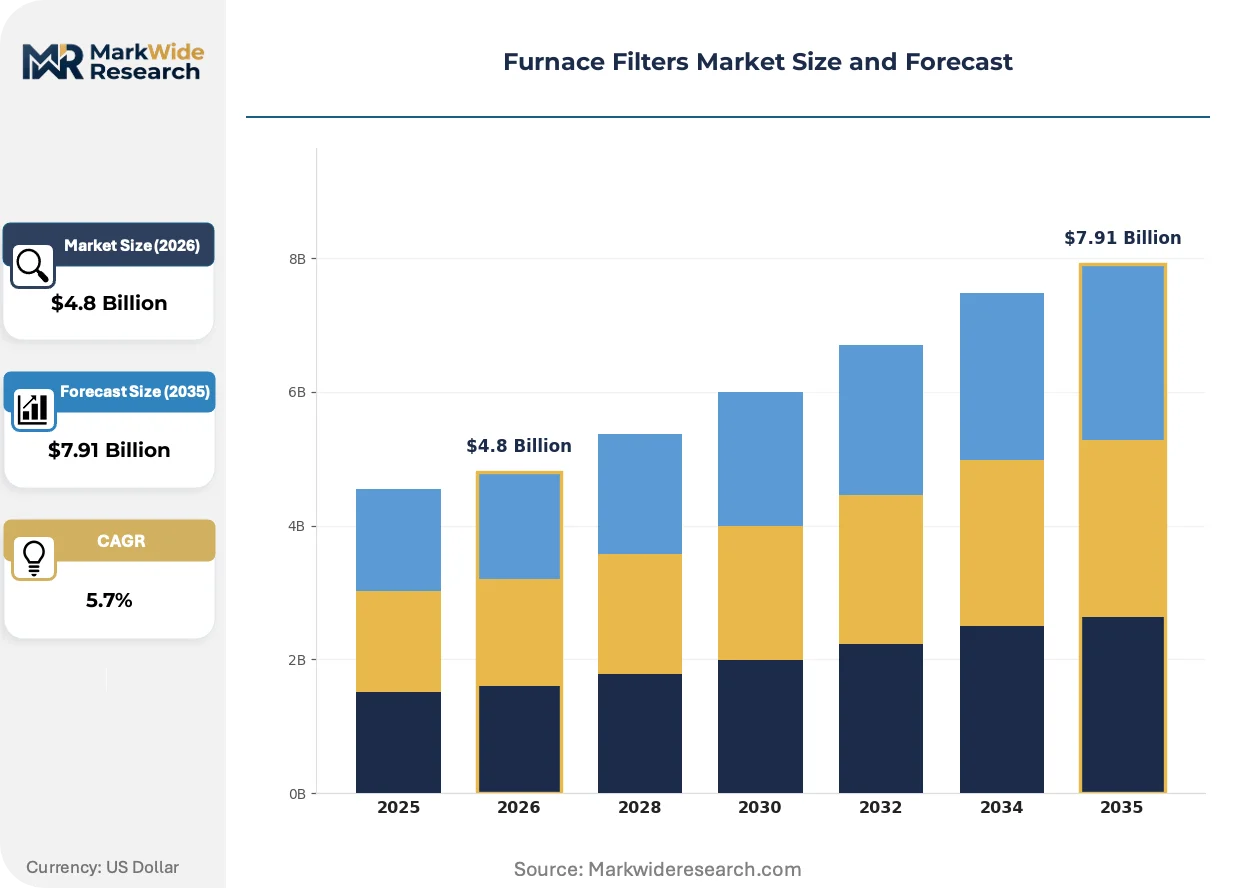
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Pleated, Electrostatic, HEPA, Carbon Material: Fiberglass, Polyester, Foam, Activated Carbon End User: Residential, Commercial, Industrial, HVAC Frame Type: Plastic, Metal, Cardboard, Others |
| Companies Covered | 3M Company, Honeywell International Inc., Lennox International Inc., Camfil AB, AprilAire LLC, Nordic Pure, Inc., AAF International, FilterBuy, Inc., Koch Filter Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furnace Filters Market Evolving Landscape
Filter technology is diverging along performance and convenience axes simultaneously, with material science advances enabling finer capture without pressure drop penalties while IoT connectivity restructures how replacement demand is triggered and fulfilled.
Synthetic nanofiber surface coatings are bifurcating the premium segment by delivering HEPA-level efficiency within pleated formats compatible with standard residential HVAC cabinets. Allergy-sensitive households and home office conversions are adopting these products at accelerated replacement frequencies. The technology is compressing traditional distinctions between residential and commercial filtration tiers.
EPA National Ambient Air Quality Standards revisions are mandating PM2.5 threshold reductions that cascade into state implementation plans and municipal building codes. New construction and major renovation permits now routinely specify minimum MERV 11-13 filtration where MERV 8 previously sufficed. Commercial office and multifamily residential developers in Texas, Florida, and Arizona are front-running compliance with higher-specification designs.
Subscription-based filter delivery models are displacing big-box retail as the dominant replacement channel for owner-occupied single-family homes. Amazon's Subscribe & Save and dedicated HVAC service platforms are capturing recurring purchase automation. This pattern concentrates in suburban Sun Belt markets where housing turnover and new construction overlap with digital-native homeowner demographics.
Furnace Filters Market Segmentation
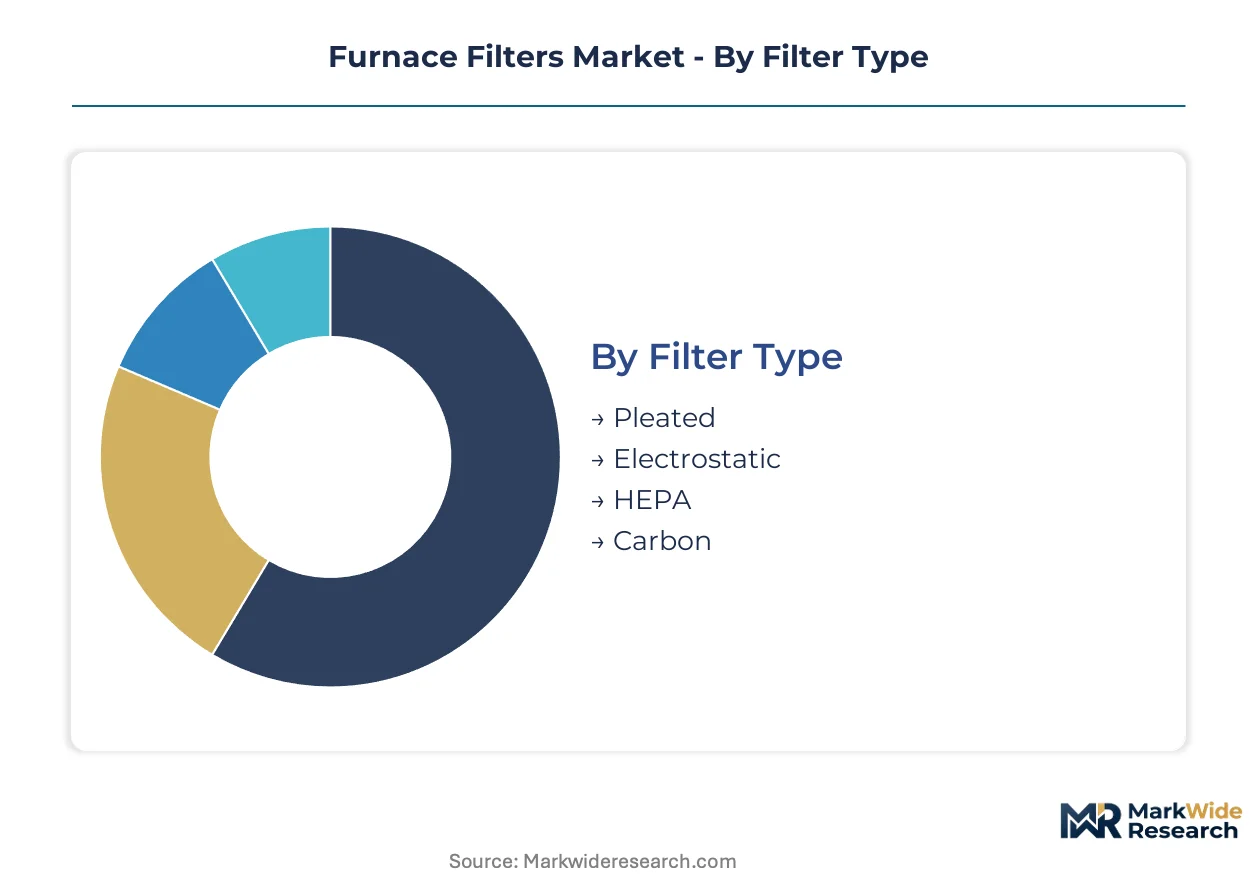
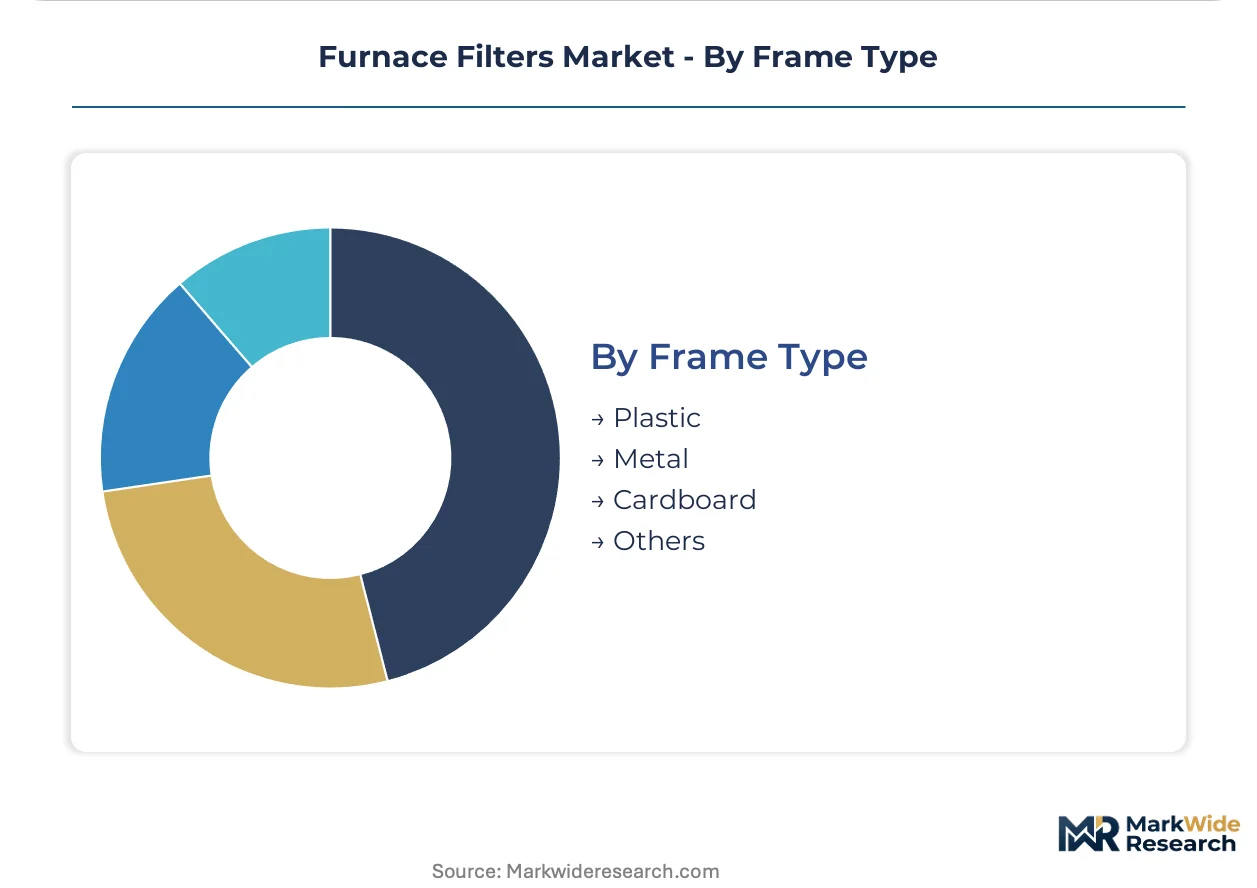
Furnace filter segmentation reveals how margin capture varies dramatically across material technologies and frame constructions. Specification power concentrates where end-use requirements intersect with regulatory pressure on minimum efficiency ratings.
Filter Type:
Premium positioning clusters around media technologies that deliver superior particle capture without airflow penalties.
- Pleated:Synthetic fiber arrays with expanded surface area dominate residential replacement cycles. Demand concentrates in American Sun Belt suburban markets where new construction mandates MERV 11+ specifications and homeowner awareness of indoor air quality has intensified post-pandemic.
- Electrostatic:Permanently charged synthetic fibers attract sub-micron particles through electrostatic attraction rather than mechanical density. California and Pacific Northwest markets specify these for wildfire smoke protection without the pressure drop of denser alternatives.
- HEPA:Medical-grade fiberglass matrices meeting DOE efficiency standards for 0.3-micron particle capture. Healthcare facility HVAC retrofits and home office conversions with immunocompromised occupants.
- Carbon:Activated charcoal impregnation targets gas-phase filtration for volatile organic compounds and odors. Commercial kitchen ventilation and industrial process exhaust applications.
Pleated holds installed capacity. Electrostatic is rotating up the share rankings.
Material:
Raw material selection determines both manufacturing cost structure and performance certification tiers achievable.
- Fiberglass:Spun glass matrices deliver minimum MERV capture at lowest unit cost. Rental housing maintenance contracts and price-sensitive light commercial specify disposable flat panels.
- Polyester:Synthetic polymer fibers enable pleating durability and extended service intervals. Residential owner-occupied upgrades and MERV 8-13 specification bands.
- Foam:Reticulated polyurethane structures for reusable washable applications. Garage workshops and light industrial ambient filtration.
- Activated Carbon:Coconut shell or coal-derived charcoal for adsorption capacity. Odor control in hospitality and food service ventilation.
Polyester commands specification loyalty. Activated Carbon is climbing the fastest.
End User:
Replacement cycle frequency and price elasticity diverge sharply across building types and ownership structures.
- Residential:Single-family and multifamily owner-occupied housing drives subscription delivery model adoption. Sun Belt new construction and HVAC replacement cycles overlap with digitally native homeowner demographics.
- Commercial:Office buildings, retail, and hospitality face ASHRAE 62.1 ventilation mandates. Texas and Florida developers front-run compliance with MERV 13+ designs in new construction.
- Industrial:Manufacturing process ventilation and dust collection systems. Heavy particulate load environments with compressed replacement intervals.
- HVAC:Original equipment manufacturer bundled specifications and contractor-installed replacement demand. Regional contractor chain concentration limits brand access.
Commercial anchors specification volume. Residential is expanding most quickly.
Frame Type:
Structural durability requirements and disposal economics shape frame material selection across end-use tiers.
- Plastic:Injection-molded polymer frames resist moisture corrosion in humid climates. Residential pleated filter standard.
- Metal:Aluminum or galvanized steel for high-velocity commercial systems and reusable media applications. Healthcare and industrial specifications.
- Cardboard:Recyclable paperboard for disposable economy tiers. Minimum-efficiency flat panel construction.
- Others:Rigid wire mesh and specialty composite structures for custom cabinet dimensions.
Plastic holds manufacturing scale. Metal is gaining specification share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The American Sun Belt prioritizes high-MERV filtration for new construction compliance, while European markets emphasize energy-recovery ventilation integration. Asian demand clusters around compact, high-density residential formats with specialized filtration needs.
United States
Texas and Florida developers front-run ASHRAE 62.1 mandates with MERV 13+ specifications in new commercial and multifamily construction. The EPA's tightened National Ambient Air Quality Standards for PM2.5 cascade into state implementation plans across California, New York, and Washington. The Dallas-Fort Worth Metroplex concentrates HVAC contractor chains that control specification pull-through for replacement cycles.
Canada
Wildfire smoke events in British Columbia and Alberta drive demand for electrostatic and activated carbon layering in residential retrofits. Health Canada's PMRA guidelines for indoor air quality influence provincial building code adoptions in Ontario and Quebec. The Greater Toronto Area anchors distribution infrastructure serving the Prairie Provinces' resource-sector ventilation needs.
Germany
The EU Green Deal's building renovation wave accelerates filter efficiency upgrades in existing residential stock. REACH regulations restrict certain synthetic fiber chemistries, pushing manufacturers toward bio-based polyester alternatives. The Rhine-Ruhr industrial corridor maintains specification concentration for commercial HVAC systems in manufacturing and logistics facilities.
China
MIIT energy efficiency standards for heat pumps create compressed replacement cycles in northern heating zones. GB standards for indoor air quality tighten in tier-one cities, elevating minimum filtration specifications in Beijing-Tianjin-Hebei new construction. The Yangtze River Delta concentrates OEM furnace manufacturing that bundles proprietary filter formats.
Japan
METI building energy codes integrate filtration efficiency with heat-recovery ventilation requirements in dense urban housing. JIS standards for HVAC components maintain strict certification protocols that favor established domestic suppliers. The Kanto region around Tokyo anchors specification authority for commercial building retrofits and healthcare facility upgrades.
Furnace Filters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in furnace filter supply. The upper tier commands specification loyalty through captive distribution channels and smart-home ecosystem integration. Mid-scale specialists compete on material innovation and regional contractor relationships. Two competitive moves dominate: backward integration into synthetic media manufacturing, and subscription-based direct-to-consumer delivery platforms that displace traditional wholesale.
Among North American diversified industrials, 3M Company and Honeywell International Inc. exemplify the integrated archetype through retail channel control and connected home platform embedding. Lennox International Inc. occupies a distinct position bundling proprietary formats with OEM furnace installed bases. Camfil AB represents the European specialist model focused on commercial and healthcare specification channels.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Lennox International Inc. |
| Camfil AB |
| AprilAire LLC |
| Nordic Pure, Inc. |
| AAF International |
| FilterBuy, Inc. |
| Koch Filter Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day raw media lead times from Asian polyester fiber suppliers compress margin flexibility for North American pleated filter manufacturers, concentrating pricing power with vertically integrated producers who control synthetic media production in-house. Contract structures and inventory positioning determine how cost volatility transmits through distribution tiers.
Pricing Analysis
Long-term offtake agreements between major retailers and synthetic media suppliers anchor pricing stability for high-volume pleated filter SKUs, while spot-market procurement dominates specialty electrostatic and activated carbon tiers. Three-tier pricing structure across premium, standard, and economy levels separates MERV 13+ certified products from MERV 8-11 mid-tier offerings and flat fiberglass minimum-efficiency panels. Cost compression in the economy tier is intensifying because rental housing maintenance contractors prioritize disposable flat panels over upgrade cycles. Single-family owner-occupiers show lowest price sensitivity, accepting subscription premiums for automated replacement delivery.
Supply Chain Analysis
Inventory cycles stretching across peak HVAC replacement seasons strain working capital for non-integrated distributors who cannot match manufacturer-direct fulfillment velocities. Synthetic fiber production concentrates in China, South Korea, and the United States, with polypropylene resin feedstock drawing from Gulf Coast petrochemical complexes. Backward integration into media manufacturing rests on proprietary fiber charging and pleating equipment that locks in process advantages. Tariff exposure on Chinese-sourced nonwoven substrates threatens margin structures for mid-tier assemblers lacking alternative supplier qualification. Distribution runs through big-box retail, HVAC contractor chains, and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The furnace filters market demands substitution defense against reusable washable foam filters and electrostatic precipitator technologies that threaten disposable media replacement cycles. Incumbents must harden recurring revenue streams before permanent filtration alternatives capture specification share.
For Market Incumbents: Compound smart-home ecosystem penetration by embedding filter replacement alerts in connected thermostat platforms, neutralizing the threat from permanent electrostatic precipitator installations that eliminate disposable media demand. Deepen backward integration into synthetic nanofiber coating capabilities to capture premium HEPA-adjacent positioning without licensing dependencies. Secure specification lock-in through proprietary frame geometries that block third-party filter substitution in OEM furnace installed bases.
For New Entrants and Emerging Players: Subscription fulfillment gaps in multifamily rental housing expose the most penetrable segment, where property managers lack automated inventory management for bulk filter procurement. Target regional HVAC contractor chains in the American Sun Belt with private-label pleated filter programs that undercut national brand premiums while matching MERV certification tiers. Deploy direct-to-building-owner digital platforms that bypass distributor markups and capture recurring replacement automation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized filtration divisions lacking smart-home connectivity and subscription revenue infrastructure. Long-term viability hinges on recurring revenue intensity rather than transactional replacement volume, favoring assets with installed IoT alert systems and captive OEM specification channels. Watch state-level building electrification mandate acceleration as the inflection signal for heat pump conversion-driven replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Embedding filter alerts in Honeywell and ecobee thermostat ecosystems automates replacement demand triggering. |
| Synthetic Media Backward Integration | In-house polypropylene fiber production insulates margin structures from petroleum resin price volatility. |
| Subscription Delivery Infrastructure | Amazon Subscribe & Save and dedicated HVAC platforms displace wholesale distribution with recurring capture. |
| HEPA-Grade Nanofiber Coating | Synthetic surface treatments deliver medical-grade efficiency within standard residential cabinet dimensions. |
| Regional Contractor Chain Partnerships | Specification pull-through concentrates with Sun Belt HVAC service networks controlling replacement access. |
Research Methodology
Operator-level perspectives from HVAC contractor operations managers, facility maintenance directors at commercial property firms, residential builder procurement leads, and big-box retail category buyers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from EPA National Ambient Air Quality Standards documentation, ASHRAE Standard 62.1 technical amendments, U.S. Department of Energy furnace efficiency rulemakings, and customs trade data on synthetic fiber imports. Bottom-up channel volume estimates and top-down construction permit filtration specification rates underwent iterative triangulation to converge on segment-level sizing.
Sensitivity analysis across MERV specification adoption curves, heat pump conversion penetration scenarios, and synthetic resin price volatility bands stress-tested projection robustness throughout the forecast period. Segmentation modeling incorporated filter type, material technology, end-user building category, and frame construction dimensions alongside regional regulatory cluster variations. CAGRs derived from fitted adoption curves reflecting ASHRAE mandate compliance timelines and replacement cycle frequency shifts. Industry-specific inputs included HVAC technician labor availability indices and smart thermostat household penetration rates.
Forecasts assume regulatory continuity in EPA National Ambient Air Quality Standards enforcement and state-level building electrification mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Pleated Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Global Tangential Flow Filtration Market
Filters
Drum Filters Market
Filters
Intake Filter Media Market
Filters
Europe Industrial Air Filtration Market
Filters
North America Gas Filtration Media Market
Filters
Activated Carbon Market
Filters
Fabric Filter System Market
Filters
Liquid Filter Bags Market
Filters
Global Filter Press Market
Filters
Global Industrial Filters Market
Filters
Europe Activated Carbon Market
Filters
Global Liquid Filtration Market
Filters
Nonwoven Filter Media Market
Filters
Zeolite Adsorbents Market