
 Glass Tableware Market | 2026-2036
Glass Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Tableware Market Analysis
ISO 6486-1 certification for ceramic and glass articles in contact with food is reorganizing competitive entry barriers across the glass tableware supply base. Arc International leverages its integrated furnace operations in France to sustain cost discipline across tempered and crystal lines. Libbey Inc. anchors North American foodservice demand through dedicated distribution to restaurant chains and institutional buyers. Villeroy & Boch AG differentiates via heritage positioning in European premium retail channels.
Glass tableware encompasses vessels, plates, and serving articles fabricated from silica-based melts, typically formulated with sodium carbonate and calcium oxide to achieve clarity, thermal stability, and food-contact safety. Primary commercial purpose spans residential dining, hospitality service, and ceremonial presentation, with borosilicate variants tolerating thermal shock gradients exceeding 150°C for oven-to-table applications. Soda-lime glass dominates volume manufacturing due to lower melting energy requirements, while crystal commands margin concentration in gift and luxury hospitality segments. The restaurant end-user channel shows structural momentum as post-pandemic dining-out frequency stabilizes and operators refresh tabletop inventories.
REACH compliance in Europe and FDA food-contact substance notifications in the United States jointly determine material composition permissibility and market access for imported glass tableware. BIS certification under India's Compulsory Registration Scheme for food-contact articles adds a third compliance layer for suppliers targeting Asian retail expansion. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level packaging regulations in California and New York, as these will increasingly dictate acceptable recycling content thresholds and shape supplier qualification criteria.
Market Dynamics
EU Green Deal packaging waste directives are compressing acceptable material weights and recyclability thresholds, forcing reformulation investments across the glass tableware supply base while premium hospitality procurement in the Gulf accelerates simultaneously.
Growth Catalysts
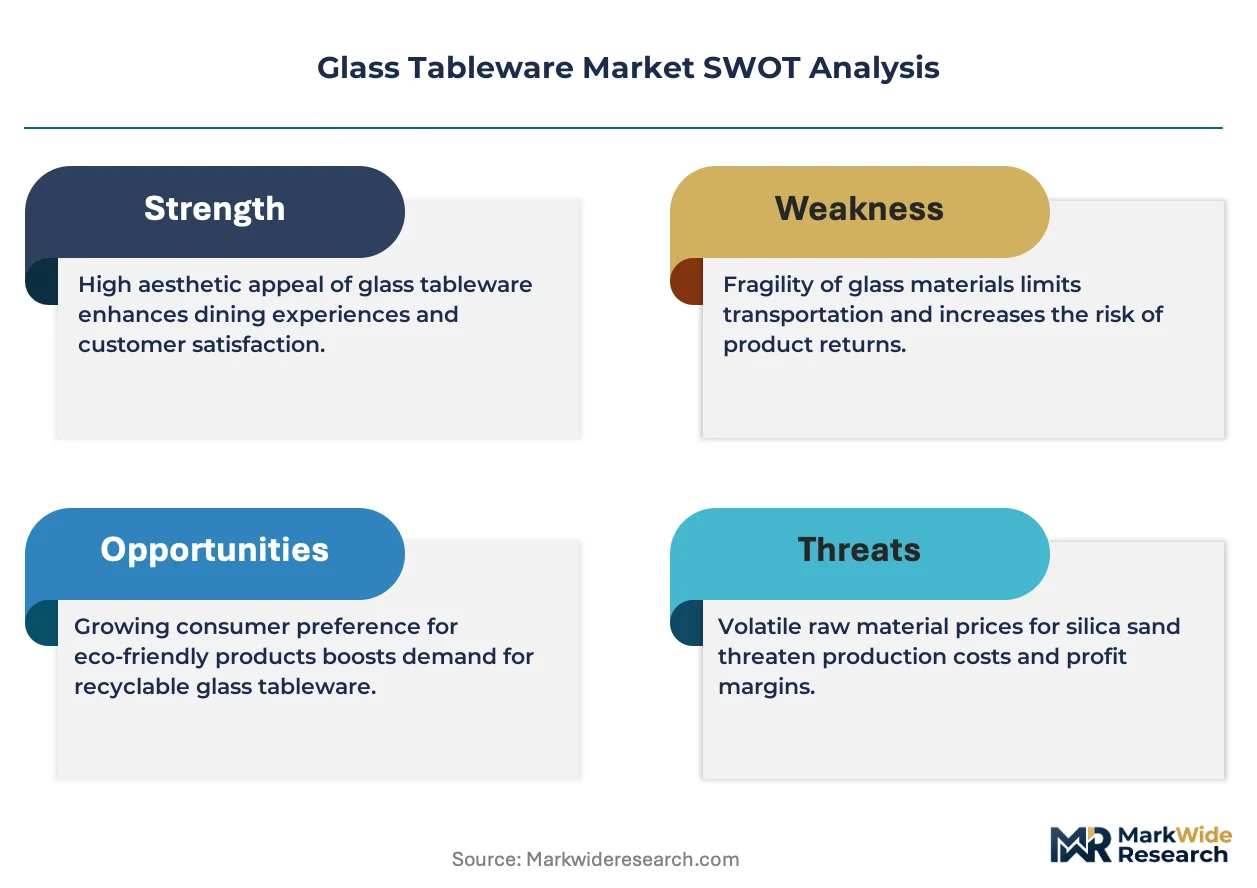
- REACH compliance thresholds:European chemical safety mandates for food-contact substances are filtering out non-compliant imports and consolidating qualified supplier rosters for EU-bound manufacturers.
- Borosilicate thermal shock tolerance:Oven-to-table functionality exceeding 150°C gradients is penetrating residential segments as nuclear households seek multi-purpose serveware.
- Dubai hospitality procurement:Premium venue expansion across the Emirates is generating dedicated artisan glassware collection demand with customized specifications.
Market Restraints
- Natural gas price volatility:Furnace energy inputs represent 35-40% of soda-lime glass production costs, exposing margins to European and Asian feedstock fluctuations.
- ISO 6486-1 certification barriers:Food-contact safety testing timelines and documentation requirements extend market entry cycles for new suppliers targeting institutional buyers.
- Ceramic and melamine substitution:Lightweight alternatives are capturing volume in casual dining and institutional segments where thermal performance requirements are minimal.
Strategic Opportunities
- India Compulsory Registration Scheme:BIS certification mandates for food-contact articles are creating first-mover advantages for compliant suppliers in urban retail expansion.
- Extended producer responsibility frameworks:EU recycling content thresholds will favor domestic remelt capacity and closed-loop collection partnerships.
- Direct-to-hospitality digital platforms:Procurement bypassing traditional distribution layers is enabling customization and reducing lead times for boutique hotel chains.
Industry Challenges
- Artisan furnace operator scarcity:Hand-blown and cut crystal production depends on skilled craftspeople with diminishing apprenticeship pipeline replenishment.
- Dual certification complexity:Simultaneous FDA notification and REACH compliance requires parallel testing protocols and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Tableware Market |
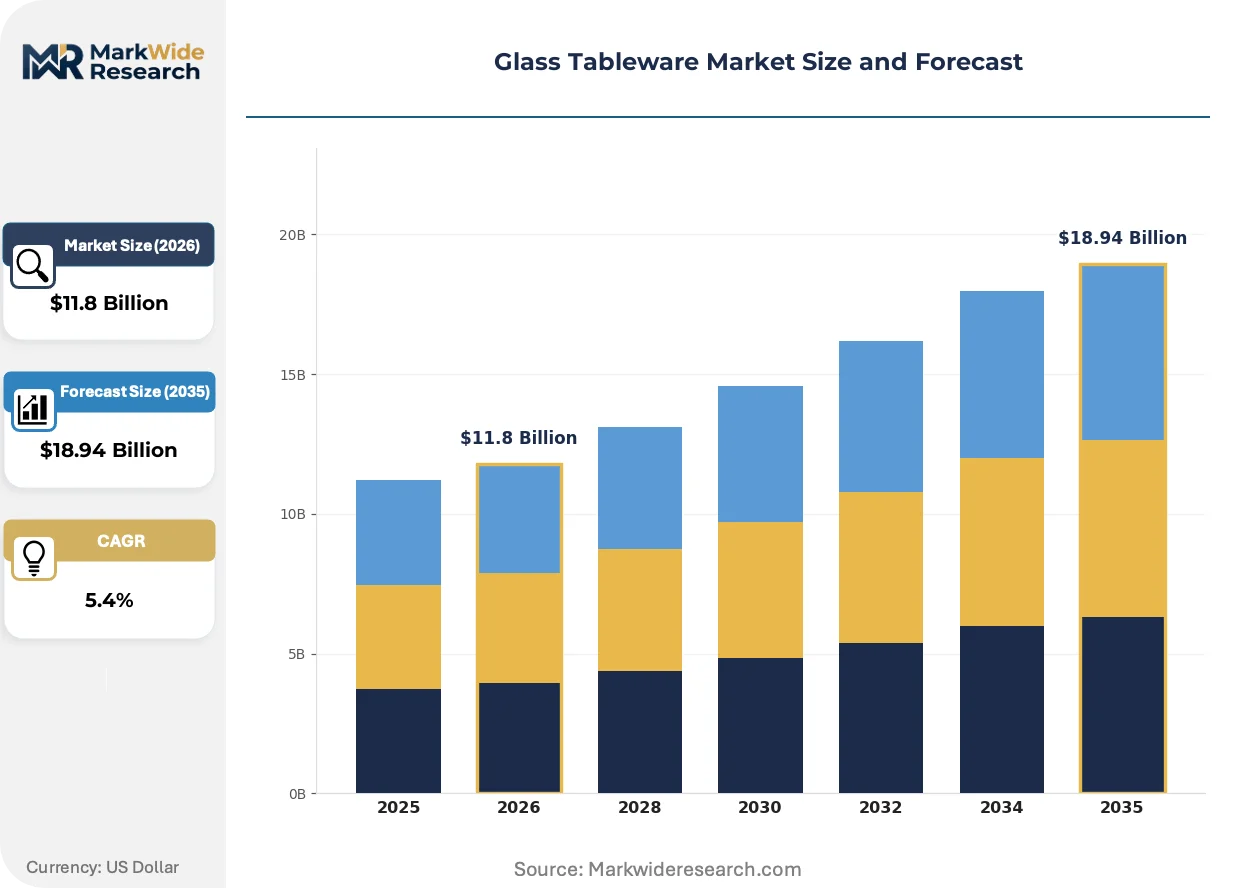
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Glassware, Serving Dishes Material: Tempered Glass, Crystal, Borosilicate Glass, Soda-Lime Glass Design Style: Modern, Traditional, Vintage, Minimalist End User: Residential, Restaurants, Catering Services, Event Management |
| Companies Covered | Arc International, Bormioli Rocco S.p.A, Libbey Inc., Sisecam Glassware, Anchor Hocking LLC, Pasabahce, Duralex International, Lenox Corporation, Villeroy & Boch AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Tableware Market Emerging Trajectories
Active reformulation toward lighter, recyclable glass compositions intersects with digital procurement platform emergence and regulatory pressure on material transparency, compressing traditional competitive advantages rooted in scale alone.
Ultralight soda-lime formulations are achieving 15-20% weight reduction without sacrificing clarity or thermal stability through optimized calcium oxide and alumina ratios. Quick-service restaurant chains in North America are piloting these vessels for reduced shipping costs and breakage rates. The technology is miniaturizing the cost gap between standard and premium lightweight alternatives.
California's state-level packaging regulations are extending producer responsibility requirements beyond EU directive baselines, mandating post-consumer recycled content minimums. Glass tableware importers are restructuring supply chains to incorporate domestic remelt facilities. Foodservice distributors serving California operators face the most immediate compliance recertification burdens.
Centralized procurement by multinational hospitality groups is consolidating supplier rosters and demanding unified global specifications. Traditional regional distributors in Europe and Asia-Pacific are losing volume to direct manufacturer relationships. This concentration is most visible in Riyadh and Jeddah, where luxury hotel development is synchronizing tabletop standards across property portfolios.
Glass Tableware Market Segmentation
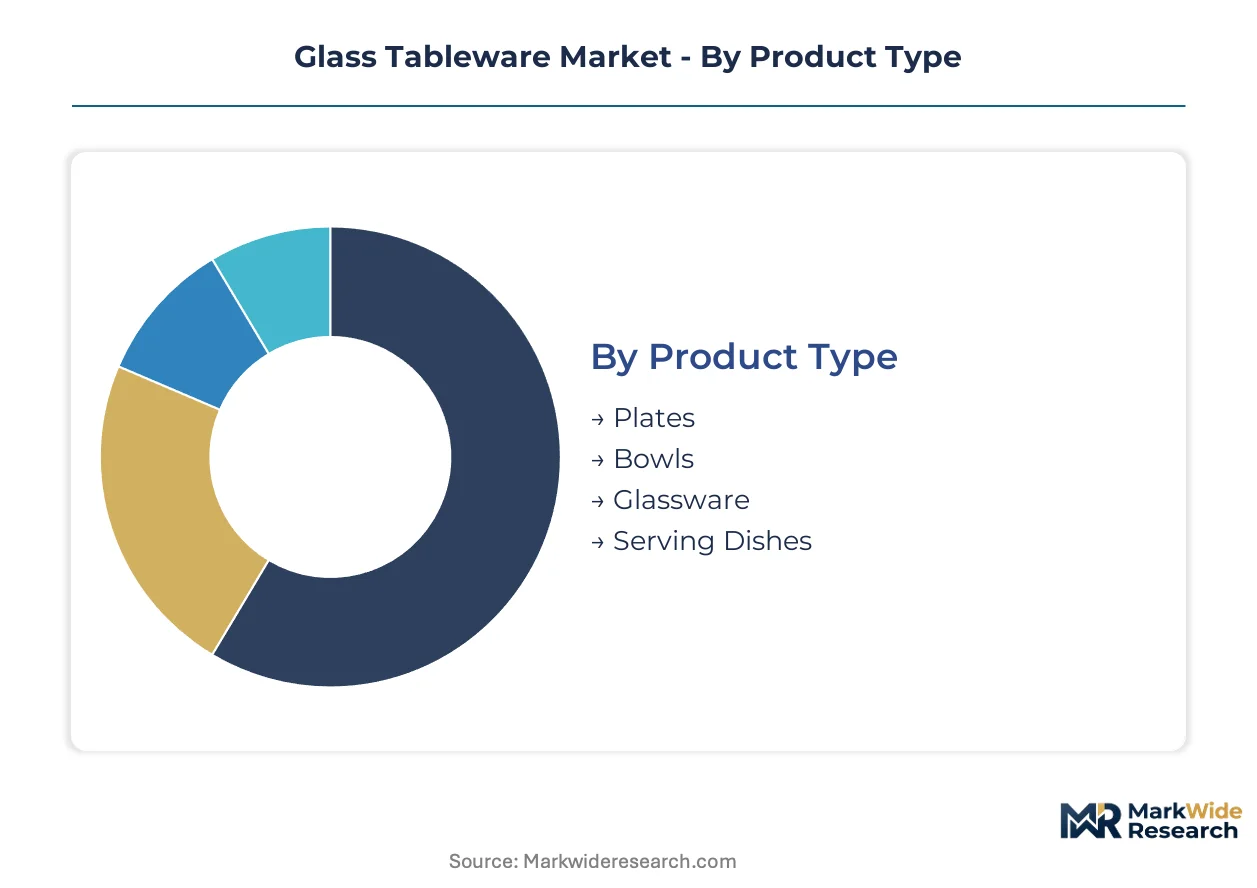
Glass tableware segmentation reveals how material chemistry, functional durability, and aesthetic positioning split margin pools across dramatically different cost structures and procurement channels. Understanding these divisions exposes where formulation investments yield pricing power versus where volume scale dominates.
Product Type:
Margin concentration tracks thermal performance requirements and breakage replacement frequency, with oven-compatible vessels commanding sustained premium pricing over decorative serveware.
- Plates:Flatware fabricated from soda-lime or tempered formulations with diameters typically ranging 15-30cm. Residential nuclear households in India are upgrading from unbranded ceramic to tempered glass dinner sets as disposable incomes rise and branded retail penetration deepens.
- Bowls:Deep vessels engineered for thermal shock resistance in soup and cereal applications. Dubai's premium hospitality venues are specifying customized artisan bowl collections for signature dining concepts, with procurement bypassing traditional distribution layers.
- Glassware:Stemmed and tumbler configurations spanning water, wine, and spirit service. REACH-compliant European imports are consolidating qualified supplier rosters as chemical safety mandates filter out non-compliant competitors.
- Serving Dishes:Platters and casseroles emphasizing presentation scale and oven-to-table functionality. Borosilicate variants tolerating thermal gradients above 150°C are penetrating residential segments seeking multi-purpose serveware.
The dominant share belongs to Glassware, while Bowls is closing the gap fastest.
Material:
Cost structure and energy intensity diverge sharply across melting temperatures and compositional complexity, with furnace economics favoring high-volume soda-lime production while crystal maintains artisan scarcity premiums.
- Tempered Glass:Thermally strengthened through controlled rapid cooling to achieve 4-5x mechanical resistance versus annealed equivalents. Quick-service restaurant chains in North America are piloting ultralight tempered vessels for reduced shipping costs and breakage rates.
- Crystal:Lead oxide or barium-enhanced formulations achieving refractive indices above 1.52 for luxury hospitality and gift applications. Hand-blown production depends on skilled craftspeople with diminishing apprenticeship pipeline replenishment across European heritage manufacturers.
- Borosilicate Glass:Silica-boron oxide matrices delivering thermal shock tolerance exceeding 150°C for oven-to-table and laboratory applications. BIS certification under India's Compulsory Registration Scheme is creating first-mover advantages for compliant suppliers in urban retail expansion.
- Soda-Lime Glass:Sodium carbonate and calcium oxide formulations dominating volume manufacturing due to lower melting energy requirements. Natural gas price volatility exposes margins to European and Asian feedstock fluctuations, with furnace energy representing 35-40% of production costs.
Soda-Lime Glass anchors volume leadership, though Borosilicate Glass is expanding most quickly as functional durability commands residential premiumization.
Design Style:
Aesthetic positioning determines channel access and price elasticity, with heritage European manufacturers leveraging archival patterns against emerging minimalist labels capturing urban professional segments.
- Modern:Clean geometries and neutral palettes aligned with contemporary interior design trends. Riyadh and Jeddah luxury hotel development is synchronizing modern tabletop standards across property portfolios through centralized multinational procurement.
- Traditional:Ornamentation and classical proportions rooted in regional craft traditions. European premium retail channels sustain heritage positioning for established manufacturers with archival pattern libraries.
- Vintage:Reproduction or authentically aged aesthetics targeting gift and collector segments. California's state-level packaging regulations are extending producer responsibility requirements, mandating post-consumer recycled content minimums that reshape importer supply chains.
- Minimalist:Reduced visual mass and monochromatic finishes emphasizing material purity. EU Green Deal packaging waste directives are compressing acceptable material weights, forcing reformulation investments toward lighter compositions without sacrificing clarity.
Traditional styling retains the largest installed base, yet Minimalist is gaining share fastest among urban residential purchasers.
End User:
Procurement scale and specification complexity separate fragmented residential purchasing from consolidated institutional tenders with unified global standards and extended certification requirements.
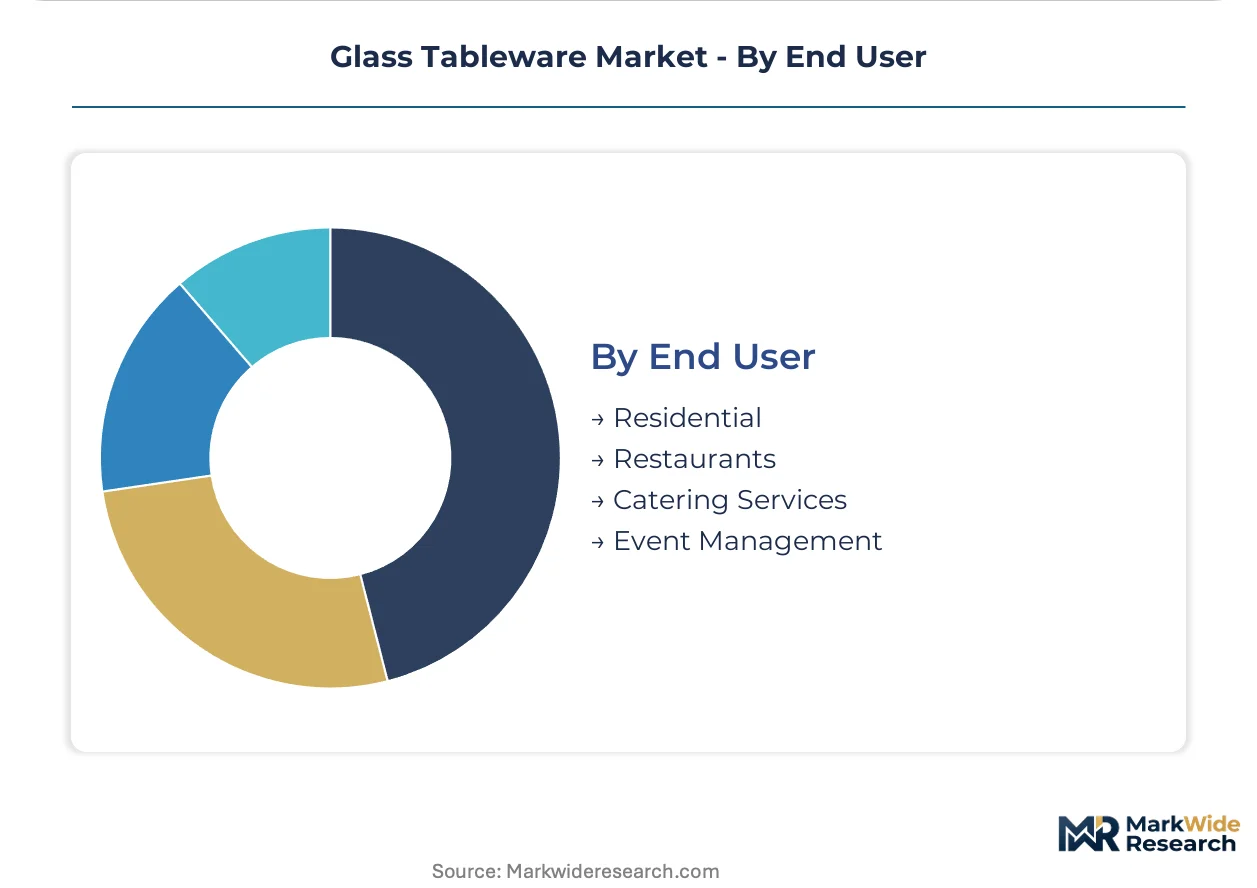
- Residential:Individual and nuclear household acquisition through retail and e-commerce channels. India's urban residential segment is concentrating demand as nuclear households invest in branded dining sets with BIS-certified food-contact safety.
- Restaurants:Foodservice operators refreshing tabletop inventories as post-pandemic dining-out frequency stabilizes. ISO 6486-1 certification timelines and documentation requirements extend market entry cycles for new suppliers targeting institutional buyers.
- Catering Services:High-volume event provisioning prioritizing durability and stackability over thermal performance. Ceramic and melamine substitution is capturing volume where thermal requirements are minimal and weight reduction drives logistics economics.
- Event Management:Temporary and ceremonial deployment with emphasis on presentation impact and rental cycle efficiency. Direct-to-hospitality digital platforms are enabling customization and reducing lead times for boutique hotel chains and exclusive venue operators.
Restaurants command the dominant procurement volume, while Residential is climbing the fastest as branded retail penetration accelerates across emerging urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement clusters in the Gulf and residential upgrade cycles in South Asia are concentrating buyer archetypes into two distinct demand pools with diverging specification requirements.
United States
Quick-service restaurant chains are piloting ultralight tempered vessels to reduce shipping costs and breakage rates. FDA food-contact substance notifications determine material composition permissibility for imported glass tableware. California's state-level packaging regulations mandate post-consumer recycled content minimums that reshape importer supply chains toward domestic remelt facilities.
Germany
Heritage manufacturers with archival pattern libraries sustain premium retail positioning through traditional styling. REACH compliance thresholds filter out non-compliant imports and consolidate qualified supplier rosters for EU-bound manufacturers. The North Rhine-Westphalia industrial corridor hosts integrated furnace operations that sustain cost discipline across tempered and crystal lines.
India
Urban nuclear households are upgrading from unbranded ceramic to tempered glass dinner sets as disposable incomes rise and branded retail penetration deepens. BIS certification under the Compulsory Registration Scheme for food-contact articles creates first-mover advantages for compliant suppliers. The Maharashtra-Gujarat manufacturing belt is expanding production capacity to serve domestic retail expansion.
United Arab Emirates
Premium hospitality venues in Dubai are expanding procurement of artisan glass tableware collections with customized specifications. The country's national packaging regulator enforces extended producer responsibility frameworks that align with EU directive baselines. Centralized multinational procurement by luxury hotel groups is synchronizing tabletop standards across property portfolios in Riyadh and Jeddah.
France
Hand-blown and cut crystal production depends on skilled craftspeople with diminishing apprenticeship pipeline replenishment across heritage manufacturers. EU Green Deal packaging waste directives compress acceptable material weights and recyclability thresholds. The Champagne-Ardenne region maintains specialized furnace operations for luxury hospitality and gift applications.
Glass Tableware Market Vendor Landscape
Player mix skews toward integrated furnace operators with captive energy management and heritage specialists with archival design libraries. The supply base concentrates around three strategic archetypes: scale-driven soda-lime manufacturers, premium crystal houses, and borosilicate functional specialists. Dominant competitive moves include backward integration into raw material sourcing and direct-to-hospitality digital platform deployment.
Among French heritage manufacturers, Arc International and Villeroy & Boch AG occupy positions anchored by integrated production infrastructure and archival pattern libraries. Libbey Inc. exemplifies the North American foodservice anchor archetype, sustaining volume relationships with restaurant chains and institutional buyers through dedicated distribution networks. These three entities represent the tiered structure separating scale-driven commodity supply from premium positioning.
| Leading Market Players |
|---|
| Arc International |
| Bormioli Rocco S.p.A |
| Libbey Inc. |
| Sisecam Glassware |
| Anchor Hocking LLC |
| Pasabahce |
| Duralex International |
| Lenox Corporation |
| Villeroy & Boch AG |
| Others |
Supply Flow & Price Mechanics
Ultralight soda-lime formulations replacing standard-weight vessels in North American quick-service procurement simultaneously shift production gravity toward furnace operators with optimized calcium oxide capabilities and compress per-unit pricing premiums that previously separated lightweight from conventional grades. Natural gas indexation in European cost-plus contracts and container rate volatility on Asia-Europe lanes now jointly determine landed cost structures for importers serving California's recycled-content mandates.
Pricing Analysis
Cost-plus contracts with Henry Hub and TTF natural gas indexation dominate long-term supply agreements for soda-lime furnace operators, anchoring price volatility to feedstock rather than finished-glass benchmarks. Price differentiation rests on thermal performance certification tiers and artisan craftsmanship scarcity, with ISO 6486-1 compliance commanding measurable premiums over uncertified alternatives. Pricing pressure intensifies downward as ceramic and melamine substitution captures casual dining volume where thermal tolerance requirements are minimal. Quick-service restaurant chains exhibit highest price sensitivity due to breakage replacement frequency and shipping cost optimization, while Dubai luxury hospitality venues demonstrate lowest sensitivity through customized artisan procurement with specification premiums.
Supply Chain Analysis
Inbound logistics costs on the Shanghai-Rotterdam and Shenzhen-Los Angeles lanes fluctuate with container availability and port congestion at Long Beach and Hamburg, compressing importer margins during peak hospitality procurement seasons. Manufacturing concentrates in China, France, and Turkey, with furnace operations drawing from silica sand deposits in Belgium and soda ash from Wyoming and Kenya. Supply chain risk centers on single-source dependency for boron oxide in borosilicate formulations, where Turkish and American deposits dominate global availability. Distribution runs through foodservice distributors in North America, heritage retail channels in Germany, and direct-to-hospitality digital platforms consolidating procurement for multinational hotel groups in the Gulf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass tableware market sits in a post-pandemic replacement cycle as hospitality operators refresh tabletop inventories and residential nuclear households upgrade from unbranded ceramic, creating cyclical demand tailwinds through the analysis window.
For Market Incumbents: Compound defensive positioning by securing captive boron oxide supply arrangements with Turkish mining operators and accelerating BIS certification completion ahead of India's urban retail expansion wave. Ceramic substitution in casual dining and natural gas cost volatility represent immediate margin threats requiring furnace energy hedging and thermal performance messaging reinforcement. For New Entrants and Emerging Players: Differentiate on borosilicate thermal shock tolerance for India's nuclear household segment, where BIS compliance creates first-mover advantages against unbranded competitors. Target direct-to-hospitality digital platforms serving boutique hotel chains in Riyadh and Jeddah, bypassing traditional European distributor layers with customized artisan specifications and compressed lead times. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated furnace operators with captive energy management and archival design libraries over pure trading intermediaries. Long-term viability hinges on extended producer responsibility compliance capabilities and closed-loop remelt infrastructure. Monitor California packaging regulation enforcement intensity as the inflection signal for recycled-content threshold acceleration across North American import supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive boron oxide and soda ash supply secures margin stability against Turkish deposit volatility. |
| BIS Certification Investment for India Entry | Compulsory Registration Scheme compliance unlocks urban retail expansion in Maharashtra and Gujarat. |
| Direct-to-Hospitality Digital Platform Deployment | Bypassing European distributors reduces lead times for Dubai and Riyadh luxury hotel procurement. |
| Ultralight Formulation R&D Scale-Up | Quick-service pilot programs in North America validate 15-20% weight reduction without clarity sacrifice. |
| Closed-Loop Remelt Partnership Formation | California's recycled-content mandates require domestic remelt facility integration for importer compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, furnace operator production disclosures, and hospitality procurement databases, validating volume estimates through cross-reference with EU packaging waste directive implementation timelines and BIS registration filings. Primary interviews engaged glass furnace operations managers, foodservice distributor category buyers, luxury hotel procurement directors, and artisan craft apprenticeship coordinators across France, Turkey, India, and the United Arab Emirates. Secondary sources included ECHA REACH substance notifications, FDA food-contact substance inventories, and Maharashtra-Gujarat manufacturing belt capacity announcements. Bottom-up product-type demand modeling triangulated against top-down regional consumption projections.
Segmentation dimensions modeled encompass material chemistry tiers, thermal performance specifications, design style positioning, and end-user channel procurement scale across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporating natural gas price scenarios and hospitality development pipelines in Dubai and Riyadh. Forecast inputs included nuclear household formation rates in Indian urban centers, quick-service restaurant chain expansion schedules, and EU Green Deal packaging waste directive compliance cost assumptions.
The analysis sits within stated boundaries; outcomes outside sustained natural gas price stability, uninterrupted BIS certification processing timelines, or accelerated ceramic substitution rates would require recalibration. Forecasts assume continued enforcement of REACH and FDA food-contact substance thresholds without regulatory rollback, and stable apprenticeship pipeline replenishment for European hand-blown crystal production. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Low Temperature Laminated Glass Market
Glass
Low Iron Glass Market
Glass
Cellular Glass Market
Glass
Coated Solar Control Glass Market
Glass
3D Glass Market
Glass
Pharma Glass Tubing Market
Glass
Glass Insulator Market
Glass
Glass Polishing Powder Market
Glass
Crystalware and Glassware Market
Glass
Advanced Glass Market
Glass
Dynamic Glazing Market
Glass
Europe Silica Sand for Glass Making Market
Glass
China Flat Glass Market
Glass
Shatterproof Glass Market
Glass
Heat Resistant Glass Market
Glass
Glass Like Carbon Market