
 Flavored and Functional Water Market | 2026-2036
Flavored and Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored and Functional Water Market Intelligence
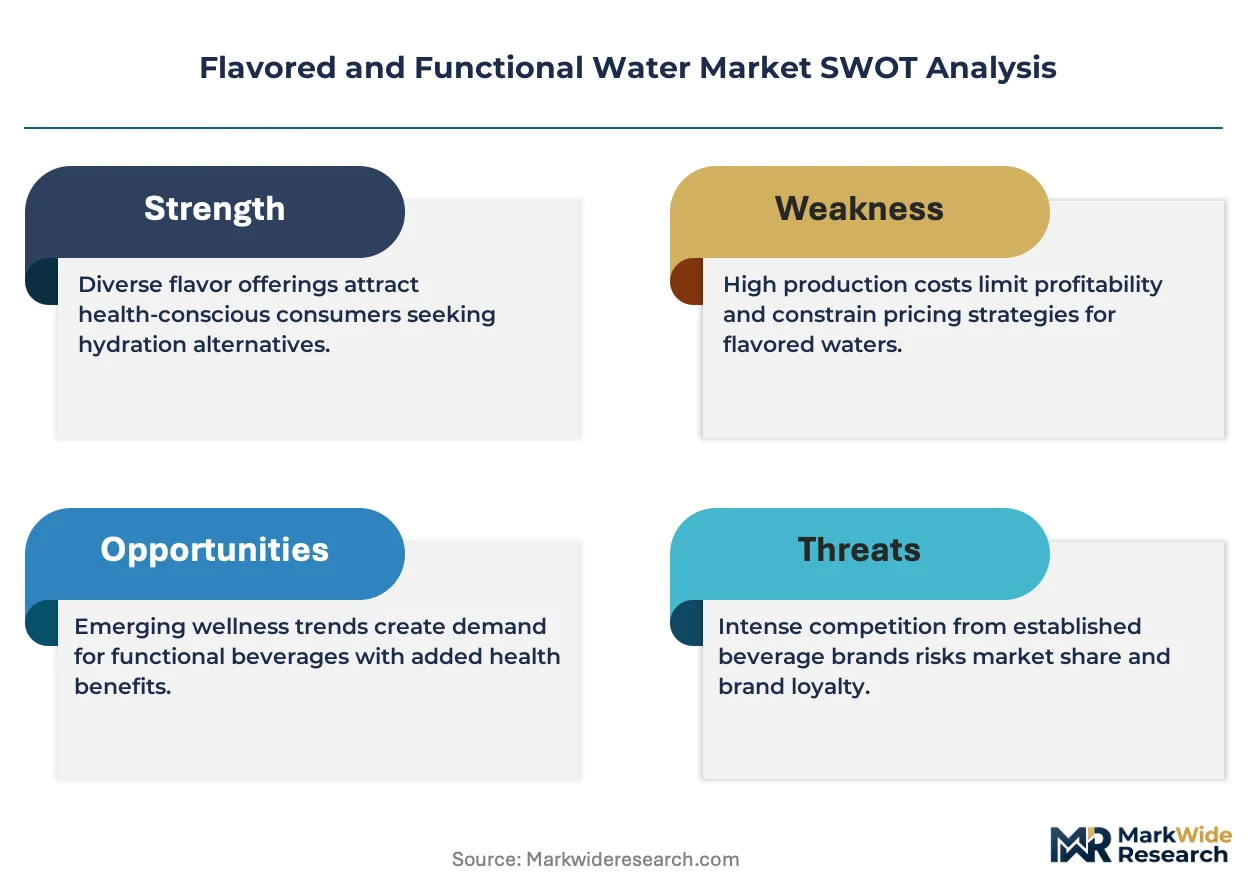
The gap between premium functional waters and commodity flavored offerings is expanding in concrete terms. Danone leverages its mineral water heritage to anchor premium positioning in European markets. The Coca-Cola Company competes through mass-market distribution density and multi-brand portfolio scale. PepsiCo differentiates via sports-linked electrolyte formulations and athlete endorsements.
Flavored and functional water comprises non-alcoholic beverages enhanced with vitamins, minerals, electrolytes, botanical extracts, or other bioactive compounds, typically manufactured through cold aseptic filling or hot-fill processes to preserve nutrient stability and achieve shelf lives of 6-18 months. The category serves industrial and commercial purposes spanning post-exercise recovery, workplace hydration programs, and retail wellness positioning. Electrolyte functionality leads volume contribution among fitness enthusiasts and outdoor workers, while immunity support formulations represent the fastest-growing functionality segment as post-pandemic health vigilance persists. Vitamin-enriched products occupy mature margin pools in conventional retail, whereas herbal infused variants navigate specialty channels with premium price architecture.
The US FDA governs bottled water safety standards and label claims under 21 CFR 165, while the EU's F-Gas Regulation and Single-Use Plastics Directive constrain refrigerant choices and packaging formats across the value chain. Health Canada and Japan's Ministry of Health, Labour and Welfare impose additive approval requirements that shape cross-border formulation strategies. Stakeholders must monitor evolving sugar taxation frameworks and deposit-return scheme expansions as these mechanisms increasingly determine profitable market access and portfolio architecture.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing rapid packaging reconfiguration across European supply chains, while FDA label claim scrutiny under 21 CFR 165 tightens permissible health assertions in the United States. These dual regulatory pressures are compressing formulation timelines and elevating compliance costs simultaneously.
Growth Catalysts
- Post-Pandemic Health Vigilance:Sustained consumer attention to immune function drives repeat purchase behavior for vitamin-fortified and botanical-infused variants in urban United States clusters.
- EU F-Gas Regulation:Refrigerant phase-down mandates accelerate cold-chain infrastructure upgrades that favor aseptic filling investments over conventional hot-fill capacity.
- Workplace Hydration Programs:Corporate wellness budgets in Germany and Japan expand bulk procurement contracts for electrolyte-enhanced SKUs replacing traditional vending machine soda.
Market Restraints
- Packaging Input Cost Volatility:R-PET and aluminum can price swings squeeze margin structures for brands dependent on sustainable material claims.
- Supply Concentration in Mineral Source Territories:Premium spring water sourcing clusters in specific French and Italian alpine regions create geographic vulnerability to climate-induced yield variation.
- Substitution by Tap Filtration Systems:Home-installed reverse osmosis and carbon filtration units capture price-sensitive households in mature North American markets.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Rising disposable incomes in Indonesia and Vietnam create first-mover advantage for functional hydration positioned between bottled water and energy drinks.
- Deposit-Return Scheme Expansion:Germany's DRS infrastructure and pending UK scheme implementation reward brands with reusable or high-recyclability packaging formats.
- Convergence of Biometric Wearables and Personalized Nutrition:Integration of sweat-sensor data with electrolyte replenishment protocols opens subscription-based formulation services for endurance athletes.
Industry Challenges
- Clean-Label Formulation Expertise Gap:Shortage of food scientists skilled in stabilizing bioactive compounds without synthetic preservatives delays product pipeline velocity.
- Multi-Jurisdiction Certification Timelines:Sequential approval processes across Health Canada, Japan's Ministry of Health, Labour and Welfare, and US FDA extend time-to-market for novel botanical extracts by 18-24 months.
- Legacy ERP Integration with Track-and-Trace Mandates:Batch-level serialization requirements under evolving EU regulations strain mid-tier manufacturers with dated enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored and Functional Water Market |
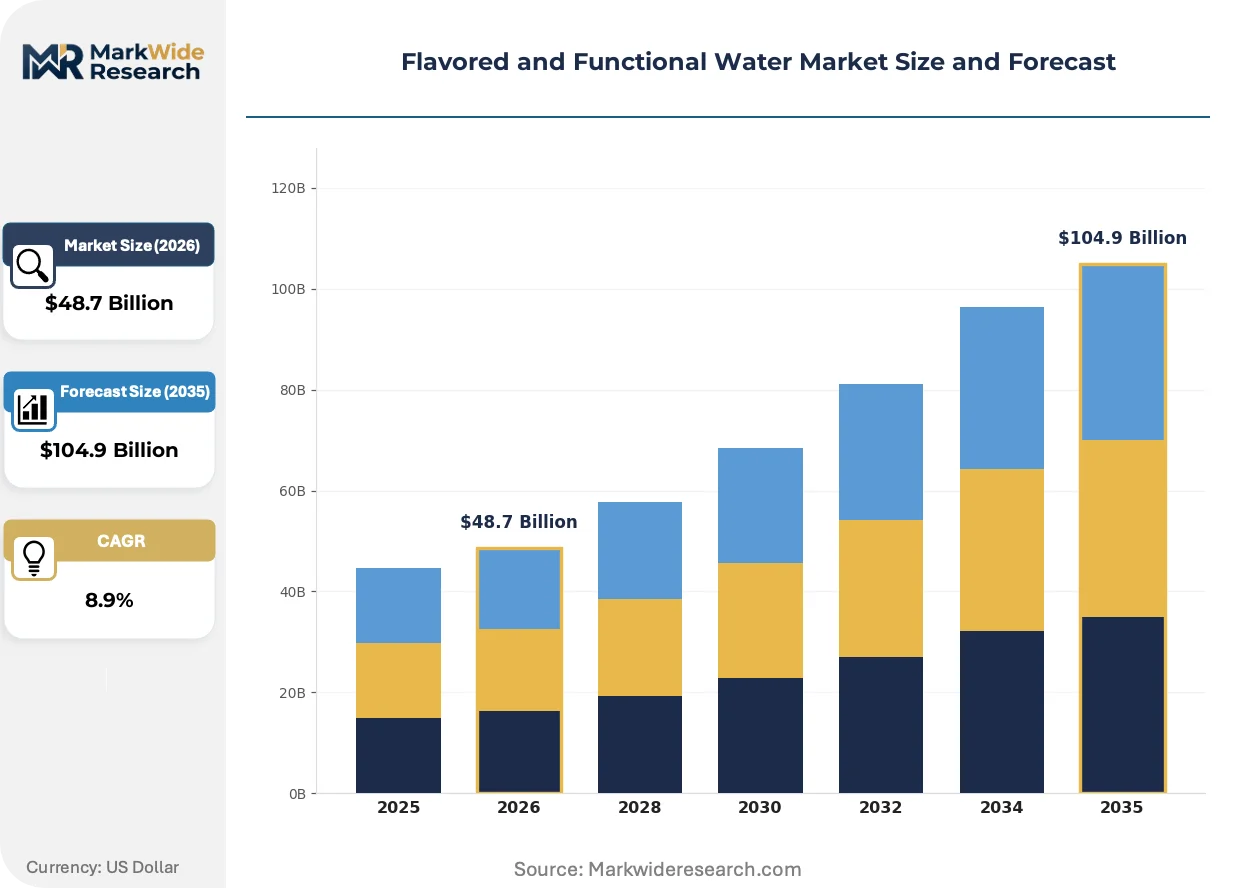
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $104.9 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin-enriched, Electrolyte, Antioxidant, Herbal Infused, Mineral Enhanced Functionality: Hydration, Energy Boost, Detoxification, Weight Management, Immunity Support Packaging Type: Bottle, Can, Pouch, Box, Refillable Container End User: Fitness Enthusiasts, Office Workers, Students, Elderly, Travelers |
| Companies Covered | Danone, Hint Water, Nestlé, Keurig Dr Pepper, Spindrift Beverage Co., The Coca-Cola Company, Talking Rain, National Beverage Corp., PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored and Functional Water Market Strategic Shifts & Innovations
Cold aseptic filling infrastructure is displacing hot-fill capacity across premium functional water lines, while regulatory pressure on packaging recyclability accelerates material science investment. These forces are compressing traditional equipment depreciation cycles and elevating capital intensity for market participation.
High-pressure processing (HPP) technology is electrifying nutrient retention capabilities in vitamin-enriched waters. Sports nutrition brands and specialty retailers are adopting HPP lines at triple-digit annual investment rates. This equipment shift is electrifying shelf-life extension without thermal degradation, compressing the competitive window for conventional hot-fill producers.
The EU's Single-Use Plastics Directive is banning certain single-use formats and mandating recycled content minimums by 2025. Industrial consequence includes accelerated R-PET sourcing competition and reformulation of multi-layer barrier structures. Premium positioned brands with European distribution face the most acute packaging redesign timelines and are responding through vertical partnerships with recycling consortiums.
Direct-to-subscription models are capturing recurring revenue from fitness enthusiasts and corporate wellness managers. Traditional retail slotting fees and distributor markups face displacement by owned-channel relationships with predictable replenishment algorithms. This channel shift is most visible in United States metropolitan corridors where delivery density supports same-day fulfillment economics.
Flavored and Functional Water Market Segmentation
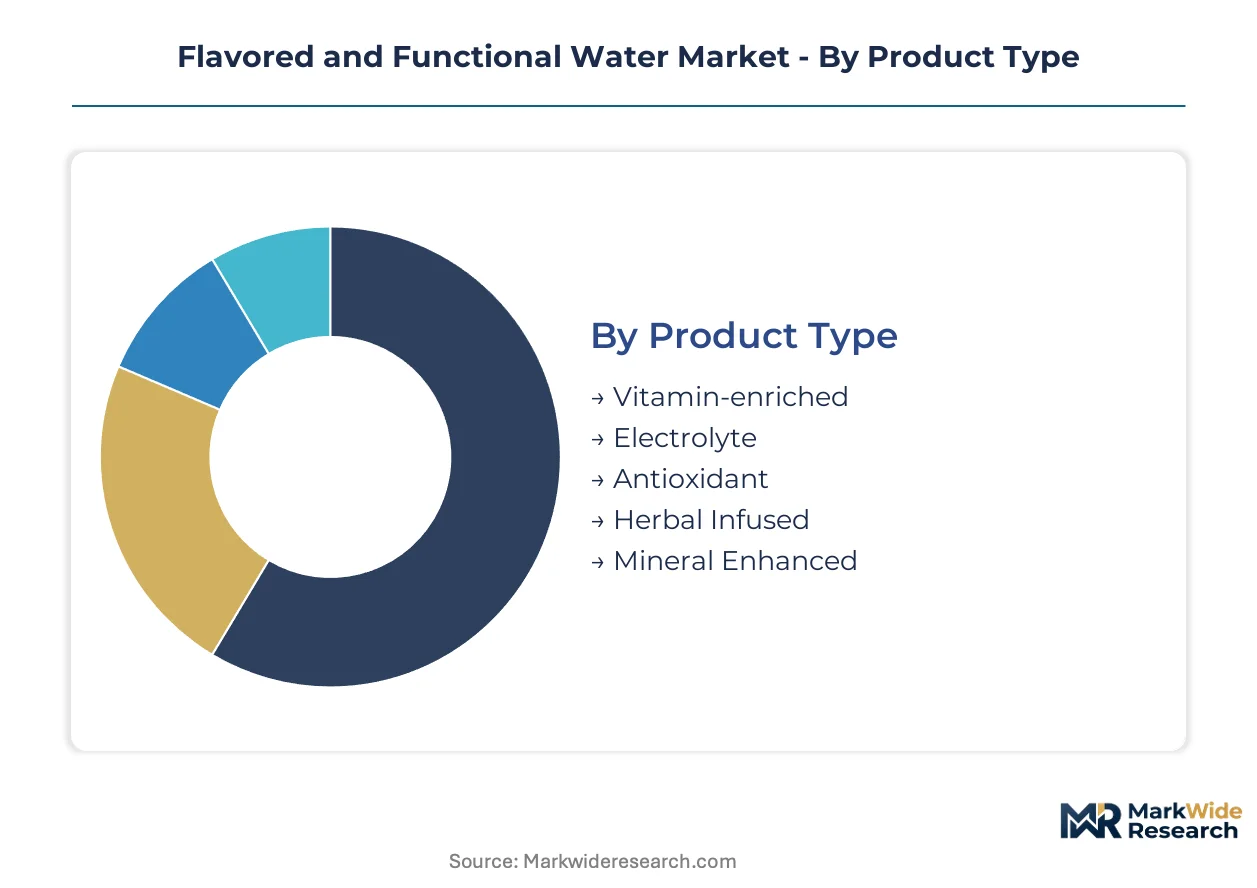
Segmentation in flavored and functional water separates volume-driven commodity plays from premium-positioned wellness solutions. Purchase triggers diverge sharply across fitness recovery, workplace convenience, and preventive health use cases, demanding distinct formulation and channel strategies.
Product Type:
Buyers in this category sort by intended physiological outcome and willingness to pay for bioactive complexity rather than basic flavoring.
- Electrolyte:Sodium, potassium, and magnesium formulations target rapid fluid balance restoration. Demand clusters with marathon training groups and construction crews in Texas and Florida where heat stress drives repeat consumption.
- Vitamin-enriched:B-complex and vitamin C fortification dominates conventional retail shelf space. Office workers in Chicago and Seattle metro areas sustain volume through grab-and-go convenience purchasing.
- Antioxidant:Polyphenol and vitamin E enhanced waters appeal to aging demographics seeking cellular protection claims.
- Herbal Infused:Botanical extracts including ginseng and ashwagandha navigate specialty channels with premium positioning.
- Mineral Enhanced:Calcium and magnesium additions leverage spring water provenance for differentiation in European markets.
Volume sits with electrolyte formulations; growth tilts toward herbal infused variants climbing the fastest on wellness positioning.
Functionality:
Margin structure here correlates with clinical credibility of health claims and regulatory scrutiny tolerance.
- Immunity Support:Zinc and vitamin C combinations address sustained post-pandemic vigilance. Urban parents in New York and Los Angeles drive premium pricing acceptance for pediatric-friendly formats.
- Hydration:Basic electrolyte replenishment commands the broadest distribution footprint. Fitness chains and university campuses sustain baseline volume through bulk procurement contracts.
- Energy Boost:Caffeine and B-vitamin combinations compete directly with energy drinks in convenience channels.
- Detoxification:Activated charcoal and chlorophyll variants target short-term cleanse protocols with episodic purchase patterns.
- Weight Management:Fiber-enhanced and appetite-suppressing formulations occupy niche positioning in pharmacy retail.
Revenue concentrates in hydration; steepest expansion trajectory belongs to immunity support as preventive health spending persists.
Packaging Type:
Material choice reflects sustainability credential requirements and consumption occasion portability needs.
- Bottle:R-PET and glass formats dominate premium positioning. Germany's deposit-return scheme infrastructure rewards brands with high-recyclability designs.
- Can:Aluminum formats gain share in fitness and outdoor recreation channels. Japan's vending machine networks favor single-serve can economics.
- Pouch:Flexible packaging reduces shipping weight for direct-to-consumer subscription models.
- Box:Bag-in-box formats serve workplace hydration programs with dispenser compatibility.
- Refillable Container:Returnable glass programs align with EU Single-Use Plastics Directive compliance mandates.
Unit economics favor bottles; regulatory pressure accelerates refillable container adoption.
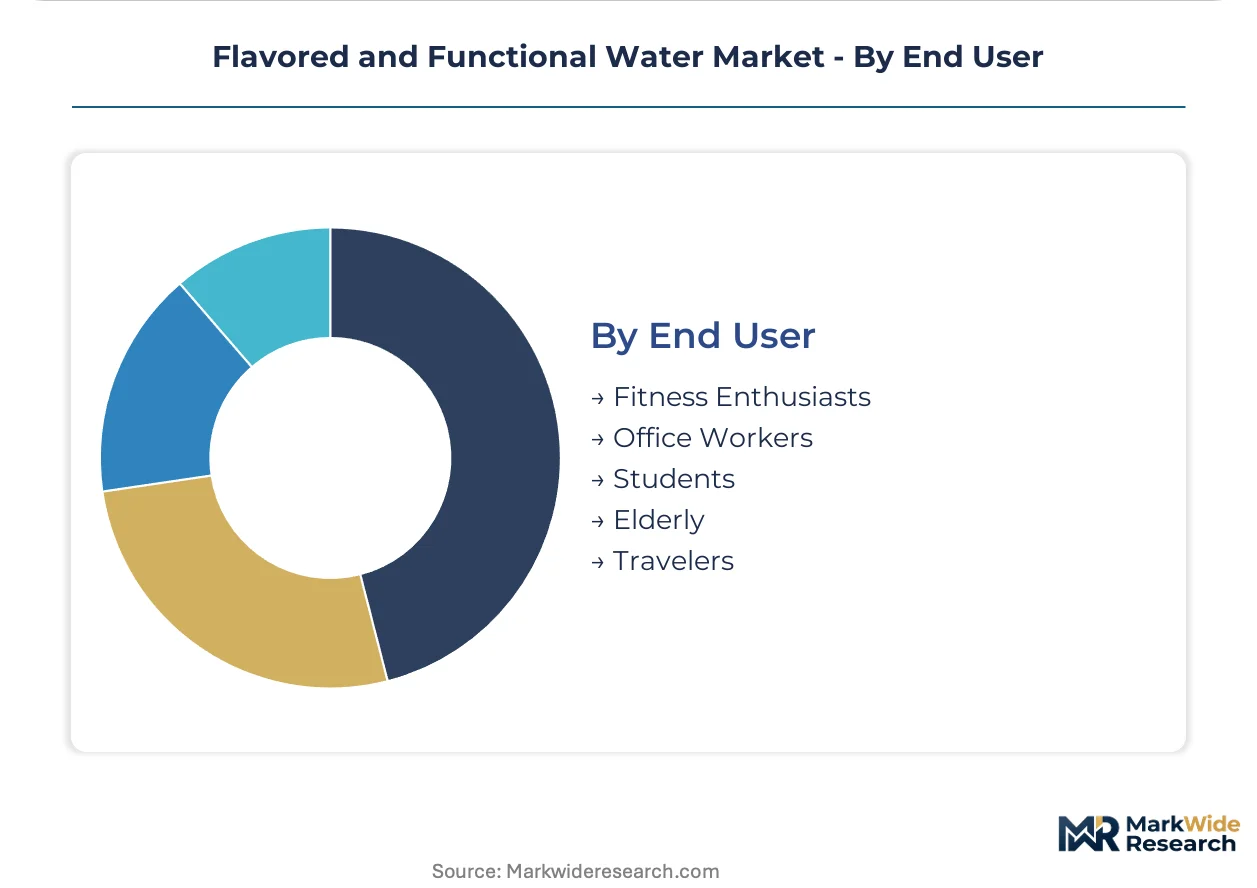
End User:
Demographic targeting determines channel placement, from gym-exclusive distribution to mass retail presence.
- Fitness Enthusiasts:Protein-carbohydrate ratios and electrolyte density drive formulation specifications. CrossFit affiliates and triathlon clubs in Colorado and California sustain subscription revenue models.
- Office Workers:Low-sugar, caffeine-modulated options replace soda in corporate wellness programs. Financial services firms in London and Frankfurt expand bulk procurement contracts.
- Students:Price-sensitive demand concentrates in convenience store channels with promotional sensitivity.
- Elderly:Medication interaction awareness shapes mineral content and botanical selection.
- Travelers:TSA-compliant sizing and immune support claims address airport and hotel retail.
Procurement volume aggregates with office workers; customer lifetime value peaks with fitness enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan and Brooklyn command the highest per-capita consumption of functional water in the United States, with premium positioning driving shelf space allocation in urban convenience networks. Metro clusters in Germany and Japan sustain parallel demand density through workplace wellness procurement and vending machine infrastructure.
United States
Fitness enthusiasts in Austin and Denver sustain subscription revenue for electrolyte formulations through CrossFit affiliate networks. The FDA enforces 21 CFR 165 standards on bottled water label claims, compressing permissible health assertions. Chicago and Seattle office workers drive volume for vitamin-enriched grab-and-go formats in corporate campus retail.
Germany
Financial services firms in Frankfurt expand bulk procurement contracts for low-sugar hydration alternatives replacing traditional vending soda. The EU Single-Use Plastics Directive mandates recycled content minimums by 2025, forcing packaging redesign timelines. Bavaria's deposit-return scheme infrastructure rewards brands with high-recyclability R-PET bottle formats.
Japan
Corporate wellness budgets in Tokyo and Osaka sustain electrolyte-enhanced SKU contracts for workplace hydration programs. The Ministry of Health, Labour and Welfare imposes additive approval requirements that shape cross-border formulation strategies. Vending machine networks across Kanto favor single-serve aluminum can economics for fitness and outdoor recreation channels.
France
Aging demographics in Lyon and Marseille drive demand for antioxidant polyphenol formulations targeting cellular protection claims. ANSM oversight of novel botanical extracts extends certification timelines for herbal-infused variants. Premium spring water sourcing clusters in alpine regions create geographic concentration for mineral-enhanced positioning.
United Kingdom
Pending deposit-return scheme implementation rewards brands with reusable or high-recyclability packaging formats ahead of regulatory deadlines. The FSA coordinates with EU-aligned standards on functional claim substantiation. London's financial district corporate wellness programs expand bulk procurement for immunity-support formulations among urban professional demographics.
Flavored and Functional Water Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and distribution density, with mineral heritage brands commanding shelf price multiples over flavor-only entrants. The vendor base stratifies into three tiers: multinational beverage conglomerates with mass-market scale, regional spring water specialists with provenance positioning, and emerging direct-to-subscription brands bypassing traditional retail slotting. Dominant competitive moves include cold aseptic filling infrastructure investments and vertical partnerships with recycling consortiums for EU compliance.
Within the multinational tier, Danone and The Coca-Cola Company exemplify divergent strategic archetypes—mineral water heritage versus mass-market distribution density. PepsiCo occupies a position bridging sports nutrition credibility through athlete-linked electrolyte formulations. Among emerging specialists, Hint Water and Spindrift Beverage Co. represent the direct-to-consumer subscription model disrupting conventional retail economics. These three archetypes—heritage mineral, mass-market scale, and digital-native specialty—collectively define competitive tension in metropolitan corridor penetration.
| Leading Market Players |
|---|
| Danone |
| Hint Water |
| Nestlé |
| Keurig Dr Pepper |
| Spindrift Beverage Co. |
| The Coca-Cola Company |
| Talking Rain |
| National Beverage Corp. |
| PepsiCo |
| Others |
Cost & Logistics Intelligence
Corporate wellness procurement teams in Frankfurt and Tokyo are mandating R-PET minimums and deposit-return compatibility in bulk hydration contracts, forcing suppliers to reconfigure sourcing footprints and absorb compliance premiums that compress mid-tier margin structures.
Pricing Analysis
Outcome-based pricing tied to employee hydration program participation rates anchors enterprise contracts for workplace wellness SKUs. Three-tier pricing structure across premium, standard, and economy levels separates mineral-heritage positioning from commodity flavoring and private-label alternatives. Price differentiation rests on spring water provenance certification and cold aseptic filling infrastructure ownership. Cost compression in the standard tier is intensifying because R-PET and aluminum input volatility outpaces brand pricing power. Students and price-sensitive households exhibit highest elasticity, while fitness enthusiasts and corporate procurement show lowest sensitivity.
Supply Chain Analysis
France's domestic-content requirements for recycled plastic and Germany's DRS infrastructure mandates are reshaping European sourcing strategies toward localized R-PET processing. Mineral extraction concentrates in French and Italian alpine territories, while aseptic filling equipment manufacturing centers on Germany and Japan. Raw material dependencies include pharmaceutical-grade electrolytes, botanical extracts, and food-safe barrier films. Single-source vulnerability in premium spring water aquifers creates yield risk from climate-induced recharge variation. Distribution runs through refrigerated trucking networks serving metropolitan convenience clusters and direct-to-subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive functions as a cost-of-compliance moat, elevating capital requirements for packaging redesign and recycling infrastructure that screens out undercapitalized entrants.
For Market Incumbents: Extend cold aseptic filling capacity in Germany and Japan to capture workplace wellness procurement contracts requiring extended shelf-life guarantees. Deepen backward integration into R-PET recycling consortiums to secure feedstock access ahead of recycled content mandates. Threat substitution from home filtration systems in North American metros demands premium positioning reinforcement through mineral provenance storytelling. For New Entrants and Emerging Players: Southeast Asian corporate wellness managers represent an underserved buyer archetype with expanding procurement budgets and limited incumbent relationships. Direct-to-subscription models targeting Indonesian and Vietnamese fitness enthusiasts bypass established retail slotting barriers. White-space concentration in immunity-support formulations for tropical climate hydration needs offers first-mover positioning. For Investors and Strategic Acquirers: Re-rating potential sits with mineral-heritage specialists given EU packaging compliance timelines that favor provenance-authenticated brands with existing recycling partnerships. Long-term viability frames around 5-10 year subscription revenue predictability and formulation R&D amortization across multi-jurisdiction approvals. Target acquisition archetype: regional spring water assets with untapped functional formulation pipelines. Signal to watch: Health Canada and Japan Ministry of Health additive approval acceleration for novel botanical extracts.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Aseptic Filling Investment | Preserves nutrient stability in vitamin-enriched lines under FDA 21 CFR 165 standards. |
| R-PET Recycling Consortium Partnership | Secures feedstock access for EU Single-Use Plastics Directive compliance deadlines. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from CrossFit affiliates and triathlon clubs in Colorado. |
| Herbal Infused Product Line Extension | Addresses fastest-growing immunity support segment with ANSM-compliant botanical sourcing. |
| Corporate Wellness Channel Expansion | Replaces traditional vending soda in Frankfurt financial services firm procurement. |
Research Approach
Trade association filings, EU regulatory databases, and Nielsen retail audit data formed the secondary backbone, cross-referenced with primary interviews of beverage R&D directors, sustainability procurement leads, and category buyers at metropolitan convenience chains. Conversations with cold aseptic equipment manufacturers and recycling consortium operators provided supply-side validation. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates from national accounts.
Bottom-up modeling aggregated electrolyte, vitamin-enriched, and herbal infused segment volumes across United States, Germany, Japan, France, and United Kingdom metro clusters. Top-down validation applied demographic hydration expenditure patterns and corporate wellness budget growth rates. CAGRs derived from segment-level momentum indicators and regulatory implementation timelines. Forecast inputs included FDA label claim scrutiny intensity, EU F-Gas Regulation refrigerant phase-down curves, and deposit-return scheme expansion schedules.
Revisions become necessary when additive approval delays at Health Canada or Japan's Ministry of Health extend beyond standard timelines, or when R-PET price volatility disrupts packaging cost assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Vitamin Functional Water Market