
 Food Grade Vitamin B1 Market | 2026-2036
Food Grade Vitamin B1 Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Vitamin B1 Market Insights
Contract manufacturing and toll-processing services is pivoting how thiamine suppliers monetize output, shifting revenue from commodity powder sales to value-added formulation partnerships. Brother Enterprises Holding leverages captive fermentation capacity to anchor supply security for multinational food brands. Huazhong Pharmaceutical specializes in high-purity thiamine mononitrate variants that command premium positioning in European nutritional supplement channels. Koninklijke DSM N.V. extends its quality certification portfolio to dominate pharmaceutical-grade thiamine segments where specification stringency exceeds standard food-grade thresholds.
Food grade vitamin B1 denotes thiamine hydrochloride or thiamine mononitrate meeting purity standards for human consumption, typically manufactured through chemical synthesis or microbial fermentation with subsequent crystallization and drying to achieve specified assay levels above 98.5 percent. Powder formulations occupy the highest volume share due to blending flexibility in industrial food production and cost-efficient bulk logistics, though tablet and granule formats capture expanding share in direct-to-consumer supplement lines where dosing precision and shelf stability differentiate competing brands. Nutritional supplements and food fortification applications concentrate margin pools, while animal feed segments compete primarily on scale-driven unit economics with thinner conversion spreads.
The FDA's food additive regulations and China's NMPA GB standards for vitamin fortification establish minimum purity benchmarks and maximum permitted usage levels that determine market access eligibility for thiamine suppliers across both jurisdictions. REACH compliance in Europe and emerging EFSA re-evaluations of B-vitamin safety profiles are tightening documentation requirements for novel food applications and imported additive certifications. Stakeholders must monitor evolving divergence between pharmaceutical-grade and food-grade specification standards, as regulatory overlap in thiamine testing protocols threatens to reshape qualification costs and competitive barriers for cross-segment suppliers.
Market Dynamics
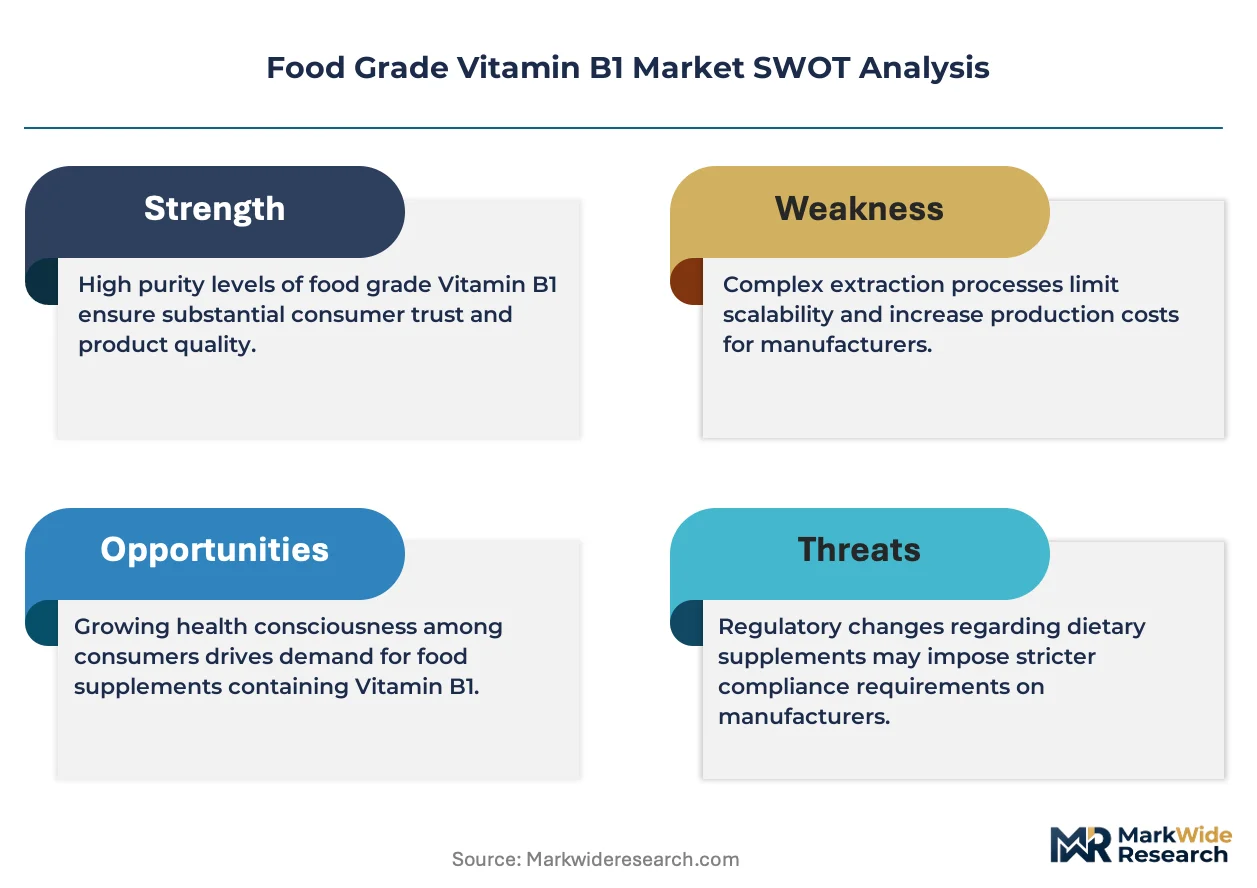
Regulatory divergence between pharmaceutical-grade and food-grade purity protocols is compressing supplier margins while forcing capital retooling across thiamine hydrochloride and mononitrate production lines.
Growth Catalysts
- FDA Food Additive Regulations:Tightened purity thresholds for vitamin fortification in beverages and clinical nutrition are disqualifying marginal suppliers and consolidating procurement toward certified producers.
- Fermentation process intensification:Microbial synthesis routes are achieving yield parity with chemical synthesis, lowering energy intensity and qualifying output for clean-label positioning in European supplement channels.
- Jiangsu-Zhejiang production clustering:Bulk thiamine concentration in these provinces creates captive feedstock security for exporters serving North American and European food fortification programs.
Market Restraints
- Acetaldehyde and pyridine input volatility:Key chemical precursors for synthetic thiamine routes face petrochemical price swings that transmit directly to mononitrate production economics.
- Single-source fermentation strain dependency:Proprietary microbial cultures held by limited suppliers create biological IP bottlenecks that constrain capacity expansion timelines.
- REACH documentation burdens:ECHA substance evaluation protocols for novel food applications are extending market access timelines by 18-24 months for imported thiamine additives.
Strategic Opportunities
- Direct-to-consumer gummy and effervescent formats:Supplement brands are bypassing bulk powder distribution to capture margin through finished-dosage positioning in pharmacy and e-commerce channels.
- EFSA novel food application windows:Re-evaluated safety profiles for high-dose thiamine derivatives are opening positioning space for enhanced-absorption formulations in clinical nutrition.
- Synthetic biology convergence with continuous processing:CRISPR-edited strains integrated with flow chemistry reactors promise step-change yield improvements for mononitrate variants.
Industry Challenges
- Pharmaceutical-grade crossover certification timelines:Food-grade producers seeking dual qualification face protracted FDA and EMA validation cycles that freeze working capital in qualification batches.
- Analytical method harmonization gaps:Divergent assay protocols between China's GB standards and USP monographs create retesting requirements at port of entry that delay customs clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Vitamin B1 Market |
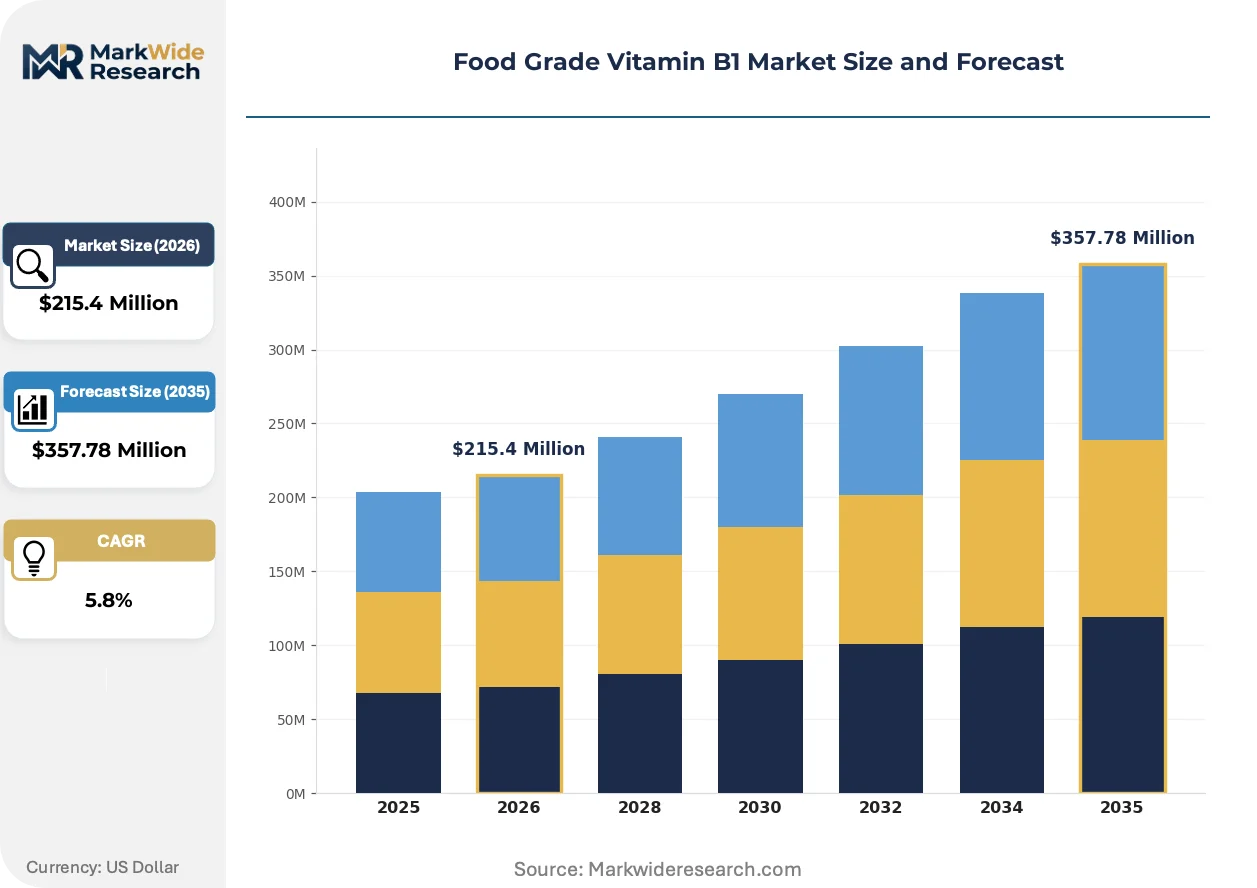
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Liquid, Granule Application: Nutritional Supplements, Food Fortification, Animal Feed, Pharmaceutical End User: Food Manufacturers, Dietary Supplement Producers, Pharmaceutical Companies, Livestock Feeders Packaging Type: Bottle, Pouch, Bulk, Sachet |
| Companies Covered | Jiangxi Tianxin Pharmaceutical, Brother Enterprises Holding, Huazhong Pharmaceutical, Koninklijke DSM N.V., Xinfa Pharmaceutical, BASF SE, Lonza Group, Merck KGaA, CSPC Pharmaceutical Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Vitamin B1 Market Trends and Innovations
Continuous manufacturing and biosynthetic routes are displacing batch chemical synthesis as the dominant thiamine production paradigm, while regulatory documentation requirements intensify competitive filtering.
Enzymatic cascade synthesis for thiamine mononitrate is absorbing capital allocation from traditional multi-step chemical routes. European nutritional supplement manufacturers are piloting this technology at commercial scale. The shift is compressing batch cycle times from weeks to days while reducing solvent waste volumes.
REACH substance evaluation under ECHA's 2023-2025 work program is tightening impurity profiling requirements for thiamine hydrochloride imports. Manufacturers must now submit full analytical datasets for residual solvents and elemental contaminants. Food fortification applicants in Germany and France are absorbing these compliance costs into qualification budgets.
Contract toll-manufacturing agreements are displacing spot powder purchases among mid-sized supplement brands. These arrangements transfer crystallization and micronization execution to specialized processors. The model concentrates most visibly in United States co-manufacturing corridors serving direct-to-consumer subscription channels.
Food Grade Vitamin B1 Market Segmentation
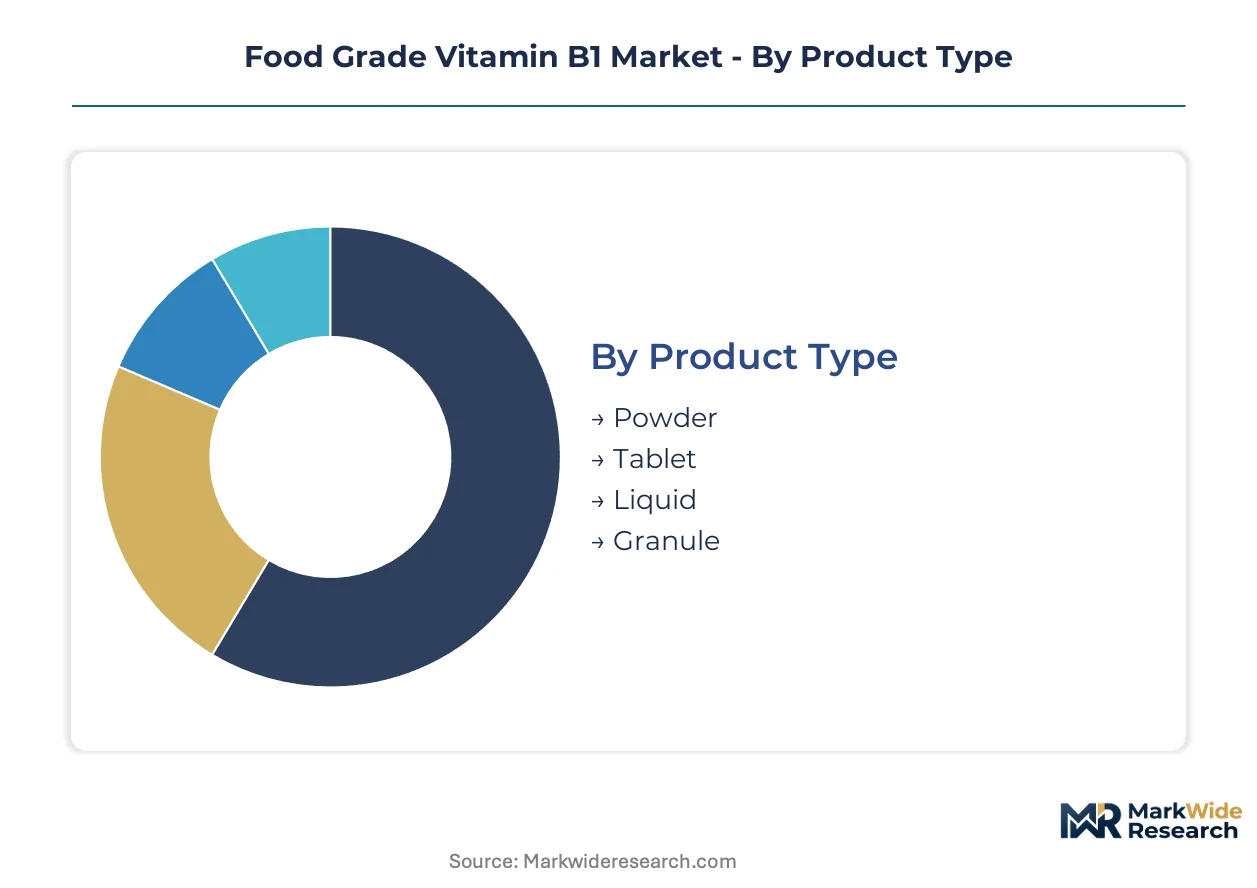
Thiamine suppliers must align production specifications with distinct integration requirements across pharmaceutical, food, and feed channels. Each segment demands different purity thresholds, documentation burdens, and formulation flexibility that reshape procurement relationships and margin structures.
Product Type:
Powder dominates as the foundational input for downstream blending operations, while finished-dosage formats capture value through convenience positioning.
- Powder:Thiamine hydrochloride and mononitrate powders above 98.5 percent assay serve industrial food fortification and bulk supplement manufacturing. Demand concentrates in Jiangsu province production clusters supplying North American beverage fortification programs. FDA food additive regulations mandate residual solvent documentation that disqualifies non-certified suppliers from pharmaceutical crossover opportunities.
- Tablet:Compressed thiamine formulations with precise unit dosing target direct-to-consumer supplement channels. European nutritional brands are expanding tablet SKUs through pharmacy and e-commerce distribution. EFSA novel food application windows for enhanced-absorption variants are opening formulation differentiation space.
- Liquid:Aqueous thiamine solutions enable beverage fortification and clinical nutrition applications requiring rapid dissolution.
- Granule:Free-flowing thiamine granules improve handling characteristics for automated feed mixing and instant drink powders.
Powder leads volumes today; tablet formats are gaining share fastest through finished-dosage margin capture.
Application:
End-use concentration determines regulatory pathway complexity and pricing power across thiamine value chains.
- Nutritional Supplements:Direct human consumption products command premium positioning through clean-label fermentation-derived sourcing. German and United States dietary supplement producers are expanding procurement of certified food-grade thiamine hydrochloride. EFSA re-evaluations of B-vitamin safety profiles are tightening documentation requirements for novel high-dose formulations.
- Food Fortification:Mandatory and discretionary thiamine addition to cereals, beverages, and baked goods drives volume procurement. China's NMPA GB standards and FDA regulations establish parallel purity benchmarks that determine market access eligibility. REACH compliance in Europe extends import timelines for novel food applicants.
- Animal Feed:Livestock and aquaculture nutrition applications compete on scale-driven unit economics with thinner conversion spreads.
- Pharmaceutical:Clinical nutrition and prescription formulations require pharmaceutical-grade process controls exceeding standard food-grade thresholds.
Food fortification anchors volume demand; nutritional supplements deliver the steepest expansion trajectory through premium positioning.
End User:
Customer scale and technical capability determine whether thiamine procurement flows through spot powder markets or integrated formulation partnerships.
- Food Manufacturers:Industrial bakers, beverage producers, and cereal processors blend thiamine into fortified finished goods. Procurement concentrates among multinational brands seeking supply security through captive fermentation partnerships. China's bulk production clusters serve both domestic fortification programs and export markets.
- Dietary Supplement Producers:Contract manufacturing and toll-processing arrangements are displacing spot powder purchases among mid-sized brands. United States co-manufacturing corridors concentrate these relationships for direct-to-consumer subscription channels. Synthetic biology convergence with continuous processing promises yield improvements for mononitrate variants.
- Pharmaceutical Companies:Clinical nutrition and parenteral formulation specialists demand pharmaceutical-grade certification with full impurity profiling.
- Livestock Feeders:Integrated animal protein operations procure thiamine through feed compounders on specification and price.
Food manufacturers dominate procurement volumes today; dietary supplement producers are climbing the fastest through value-added formulation partnerships.
Packaging Type:
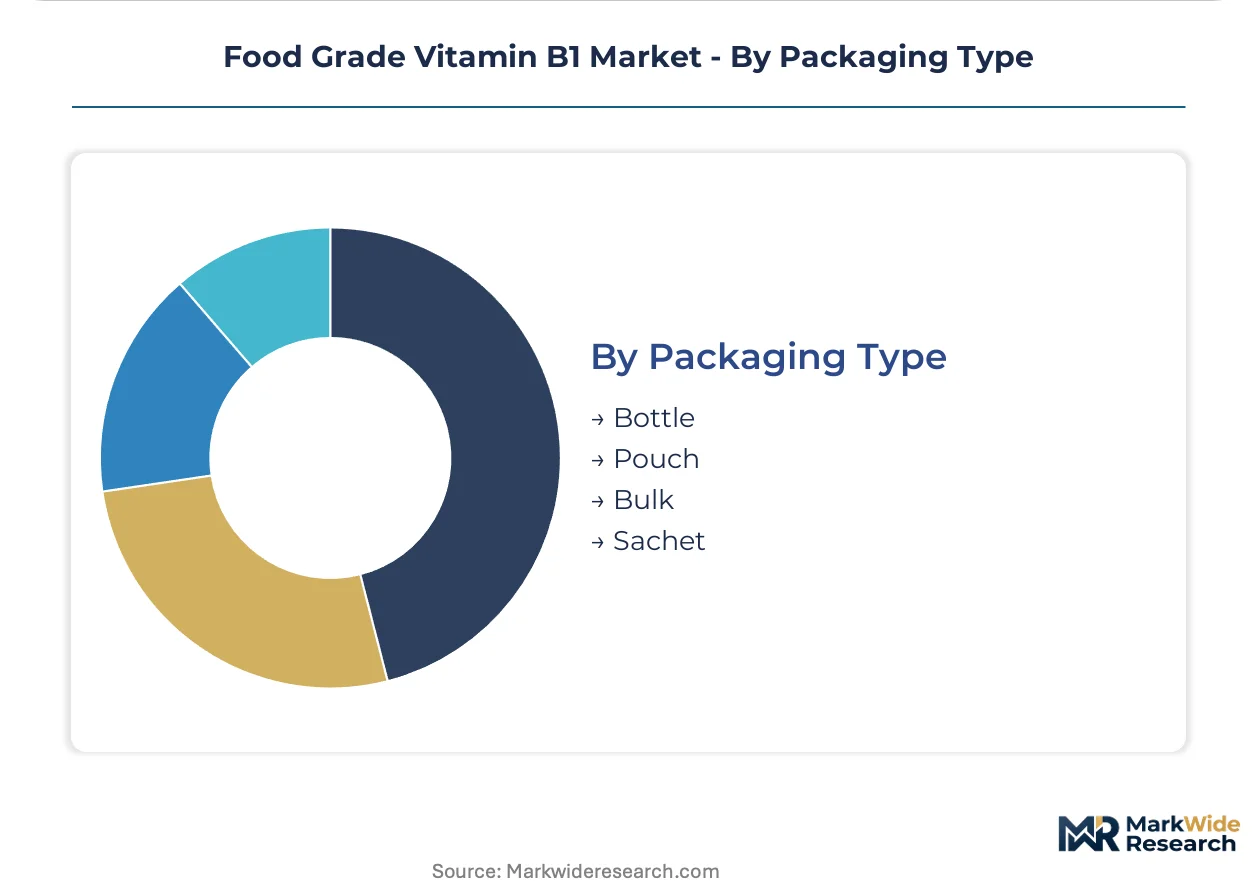
Packaging configuration reflects downstream handling requirements and regulatory traceability obligations across distribution channels.
- Bottle:Rigid containers with desiccant protection serve retail supplement channels requiring shelf stability and tamper evidence. German and French pharmacy distribution mandates child-resistant closures that add unit packaging cost. Direct-to-consumer brands are expanding bottle SKUs through subscription replenishment models.
- Pouch:Flexible laminated films enable single-serve and travel-format positioning in supplement and food applications. E-commerce fulfillment preferences are driving pouch adoption for lightweight shipping efficiency. REACH substance evaluation protocols extend to packaging material compliance for European market access.
- Bulk:Industrial drums and supersacks minimize per-kilogram logistics cost for high-volume food fortification operations.
- Sachet:Unit-dose foil strips target clinical nutrition and institutional feeding programs requiring precise portion control.
Bulk packaging leads volumes through industrial procurement; pouch formats are expanding most quickly through e-commerce channel alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands bulk production capacity while Germany sets purity benchmarks for European nutritional channels. The United States absorbs the largest import volumes for beverage fortification and direct-to-consumer supplements.
China
Jiangsu and Zhejiang provinces anchor global thiamine output through integrated fermentation clusters serving export markets. NMPA GB standards for vitamin fortification establish purity thresholds that determine market access eligibility for domestic and foreign suppliers. Bulk manufacturers in these coastal provinces supply North American food fortification programs through long-term procurement contracts.
United States
Dietary supplement producers expand certified food-grade thiamine hydrochloride procurement for fortified beverages and clinical nutrition applications. FDA food additive regulations tightened residual solvent documentation requirements, disqualifying marginal suppliers from pharmaceutical crossover opportunities. Co-manufacturing corridors in the Midwest and Southeast concentrate toll-processing arrangements for direct-to-consumer subscription channels.
Germany
European nutritional supplement manufacturers drive demand for high-purity thiamine mononitrate variants commanding premium positioning. EFSA re-evaluations of B-vitamin safety profiles tightened documentation requirements for novel high-dose formulations. Industrial buyers in Bavaria and North Rhine-Westphalia absorb REACH compliance costs into qualification budgets for imported additives.
India
Domestic food fortification programs and pharmaceutical formulation sectors create dual-demand channels for food-grade thiamine. FSSAI standards for vitamin additives establish parallel purity benchmarks to FDA and NMPA protocols. Manufacturing clusters in Maharashtra and Gujarat serve both local nutritional supplement brands and export markets across Southeast Asia and Africa.
Japan
Clinical nutrition and functional food sectors demand pharmaceutical-grade process controls exceeding standard food-grade thresholds. PMDA oversight of vitamin additives creates stringent impurity profiling requirements for imported thiamine hydrochloride. Production partnerships in the Kansai region integrate Japanese quality protocols with Chinese bulk feedstock supply.
Food Grade Vitamin B1 Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-based producers commanding premium positioning in clean-label channels while chemical synthesis specialists compete on scale in industrial fortification. The vendor base concentrates among integrated pharmaceutical conglomerates and dedicated B-vitamin houses with captive microbial culture libraries. Two strategic archetypes dominate: vertically integrated fermentation operators with proprietary strain IP, and toll-processing specialists monetizing crystallization and micronization capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers seek to anchor supply security for multinational food brands.
Within the fermentation-specialist tier, Brother Enterprises Holding and Huazhong Pharmaceutical exemplify Chinese producers leveraging captive microbial capacity to serve both domestic fortification programs and European nutritional channels. Koninklijke DSM N.V. occupies a position among Western pharmaceutical-grade specialists where quality certification portfolios determine access to clinical nutrition segments. These three anchors illustrate how geographic origin and process technology stratify competitive positioning across food-grade and pharmaceutical-grade specification thresholds.
| Leading Market Players |
|---|
| Jiangxi Tianxin Pharmaceutical |
| Brother Enterprises Holding |
| Huazhong Pharmaceutical |
| Koninklijke DSM N.V. |
| Xinfa Pharmaceutical |
| BASF SE |
| Lonza Group |
| Merck KGaA |
| CSPC Pharmaceutical Group Limited |
| Others |
Pricing and Supply Chain Analysis
Fermentation microbiologist concentrations in Jiangsu and Zhejiang provinces anchor labor-cost differentials that widen spreads between pharmaceutical-grade and food-grade thiamine pricing tiers. Skilled technician wages in these coastal clusters run below Western pharmaceutical hubs, enabling Chinese producers to undercut European and North American suppliers on standard-grade powder while maintaining margin on certified variants.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for standard-grade thiamine hydrochloride powder. Three-tier pricing structure across pharmaceutical-grade, certified food-grade, and feed-grade levels separates qualification-intensive clinical nutrition supply from commodity fortification markets. Cost compression in standard powder segments is intensifying because fermentation yield improvements are expanding effective supply. Contract food manufacturers exhibit highest price sensitivity due to thin conversion spreads, while pharmaceutical formulators absorb premium tiers for impurity documentation.
Supply Chain Analysis
REACH certification and FDA food additive qualification gating create 18-to-24-month entry barriers that protect incumbent supplier relationships. Supply concentrates in China, with secondary fermentation capacity in India and limited specialty production in the Netherlands. Acetaldehyde and pyridine precursors for chemical synthesis routes draw from petrochemical feedstocks, creating margin exposure to energy price cycles. Single-source dependency on proprietary microbial strains held by Brother Enterprises and Huazhong Pharmaceutical constitutes the primary structural vulnerability. Distribution runs through bulk drum shipments to industrial food fortification operations, with pouch and bottle formats expanding through e-commerce supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Vitamin B1 Market functions as a stable compounder anchored by mandatory fortification programs and clean-label supplement expansion. Regulatory qualification requirements create durable competitive moats that favor incumbents with established certification portfolios.
For Market Incumbents: Anchor supply security through captive fermentation partnerships with Jiangsu-Zhejiang producers before capacity tightens on environmental compliance upgrades. Invest in pharmaceutical-grade crossover certification to capture margin expansion from clinical nutrition demand. Defend against synthetic biology entrants by locking long-term toll-processing agreements with mid-sized supplement brands seeking formulation flexibility.
For New Entrants and Emerging Players: Begin with enzymatic cascade synthesis pilots for thiamine mononitrate variants, targeting European nutritional supplement channels where clean-label positioning commands premium absorption. White-space opportunity concentrates in direct-to-consumer gummy and effervescent formats bypassing bulk powder distribution. Penetrate through contract manufacturing arrangements with United States subscription supplement brands seeking domestic formulation partners.
For Investors and Strategic Acquirers: Multinational food ingredient conglomerates are the most active acquirer in this space, seeking captive thiamine supply for fortified beverage portfolios. Long-term viability frames around sustained regulatory divergence between food-grade and pharmaceutical-grade specifications that sustains qualification-based pricing power. Acquisition target archetype: mid-sized fermentation specialists with proprietary strain libraries and pending FDA food additive certifications. Signal to watch: EFSA novel food approvals for enhanced-absorption thiamine derivatives that would reshape clinical nutrition positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive microbial culture libraries insulate supply security from proprietary strain bottlenecks. |
| Pharmaceutical-Grade Crossover Certification | FDA and EMA validation cycles unlock clinical nutrition segments with specification premiums. |
| Continuous Processing Technology Adoption | Flow chemistry reactors integrated with CRISPR-edited strains promise yield step-changes for mononitrate. |
| Direct-to-Consumer Format Expansion | Gummy and effervescent SKUs bypass bulk powder margin compression through finished-dosage positioning. |
| EFSA Novel Food Application Filing | Enhanced-absorption derivative approvals open formulation differentiation space in European clinical nutrition. |
Research Methodology
Bottom-up food fortification and supplement procurement modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Jiangsu-Zhejiang production facilities, procurement leads at multinational beverage manufacturers, regulatory affairs specialists navigating FDA food additive pathways, and technical R&D directors at European nutritional brands were cross-validated against secondary sources including NMPA GB standard filings, EFSA safety re-evaluation dossiers, customs trade data for thiamine hydrochloride and mononitrate shipments, and SEC 10-K disclosures from listed ingredient suppliers.
Historical trendline analysis of thiamine production volumes, grade-tier pricing differentials, and certification timeline distributions established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type (powder, tablet, liquid, granule), application (nutritional supplements, food fortification, animal feed, pharmaceutical), and end-user scale (industrial food manufacturers, dietary supplement producers, pharmaceutical companies, livestock compounders). CAGRs were derived from elasticity-adjusted demand projections tied to fortification program expansion and clean-label supplement penetration rates. Industry-specific forecast inputs included fermentation yield improvement curves and REACH documentation burden escalation patterns.
Several conditions sit outside the modeled scope, including geopolitical trade restriction scenarios, breakthrough synthetic biology yield disruptions, and acute petrochemical precursor price shocks. Forecasts reflect documented assumptions regarding regulatory timeline stability and certification standard continuity. A model refresh is warranted upon material change in EFSA novel food evaluation protocols or NMPA environmental enforcement intensity at Jiangsu-Zhejiang production clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Essential Micronutrients Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Vitamin B Market