
 Functional Flavor Market | 2026-2036
Functional Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Flavor Market Foresight
The capital-intensity divergence between captive biotech fermentation assets and outsourced compound blending is rotating competitive advantage toward integrated producers. Givaudan leverages captive biotechnology platforms to control rare botanical extraction pathways. Firmenich sustains leadership in precision fermentation for nature-identical molecules. Symrise anchors its position through integrated savory flavor complexes and regional taste laboratories.
Functional flavors are engineered taste-active compounds—natural extracts, synthetic molecules, or nature-identical formulations—that deliver sensory performance alongside physiological benefits such as satiety signaling, stress modulation, or metabolic support. Production involves solvent extraction, enzymatic biotransformation, or microbial fermentation, with encapsulation technologies protecting volatile actives through thermal processing. The natural segment commands premium positioning as clean-label mandates from retail chains and food manufacturers eliminate synthetic alternatives from reformulation pipelines. Powder and encapsulated forms are capturing disproportionate growth in dietary supplement applications where stability and controlled release determine shelf-life performance. Liquid formats still dominate beverage applications where homogeneous dispersion remains the critical functional parameter.
The FDA's Food Safety Modernization Act and the EPA's chemical substance review protocols shape ingredient approval timelines and toxicological testing burdens for US market entry. EFSA's flavoring group evaluations and the EU's Novel Food Regulation create parallel compliance architectures that determine which botanical extracts and fermentation-derived molecules achieve commercial scale. REACH chemical registration requirements add another layer of substance characterization for synthetic and nature-identical compounds. Stakeholders must monitor regulatory divergence between jurisdictions as classification of bioactive flavor compounds shifts between food additive, novel food, and supplement regulatory pathways with divergent evidentiary demands.
Market Dynamics
Clean-label mandates from retail chains and food manufacturers are eliminating synthetic alternatives from reformulation pipelines, forcing producers to rebuild supply chains around captive biotechnology platforms and rare botanical extraction pathways.
Growth Catalysts
- EU Flavoring Regulation Framework:Tightening purity standards for natural claims accelerate investment in precision fermentation and enzymatic biotransformation capabilities across German and French production facilities.
- Beverage Reformulation:Producers of functional drinks and sports nutrition accelerate adoption of encapsulated flavor systems that protect volatile actives through thermal processing.
- Savory Complex Integration:Food manufacturers in Germany concentrate demand for integrated savory flavor complexes that deliver taste performance alongside metabolic support claims.
Market Restraints
- Captive Fermentation Asset Costs:The capital-intensity divergence between in-house biotech platforms and outsourced compound blending creates barriers for mid-scale producers lacking integrated production.
- Regulatory Divergence:Classification shifts between food additive, novel food, and supplement pathways across FDA, EFSA, and REACH frameworks multiply toxicological testing burdens and approval timelines.
- Botanical Supply Concentration:Rare botanical extraction pathways concentrate in limited geographic clusters, exposing formulations to raw material volatility and extraction capacity constraints.
Strategic Opportunities
- Dietary Supplement Powder Formats:Encapsulated and powder forms capture disproportionate growth where stability and controlled release determine shelf-life performance in supplement applications.
- Regional Taste Laboratory Networks:Establishment of localized sensory development centers enables faster regional customization and reduces dependence on centralized European R&D.
- Dual-Use Fermentation Infrastructure:Convergence of microbial fermentation platforms for both nature-identical molecules and bioactive compounds unlocks capacity utilization across flavor and nutraceutical production.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of flavor chemistry, encapsulation engineering, and regulatory science requires hybrid skill sets that remain scarce in traditional food science labor markets.
- Legacy System Integration:Reformulation of established product portfolios demands reconfiguration of existing production lines, quality control protocols, and supplier qualification systems without disrupting commercial operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Flavor Market |
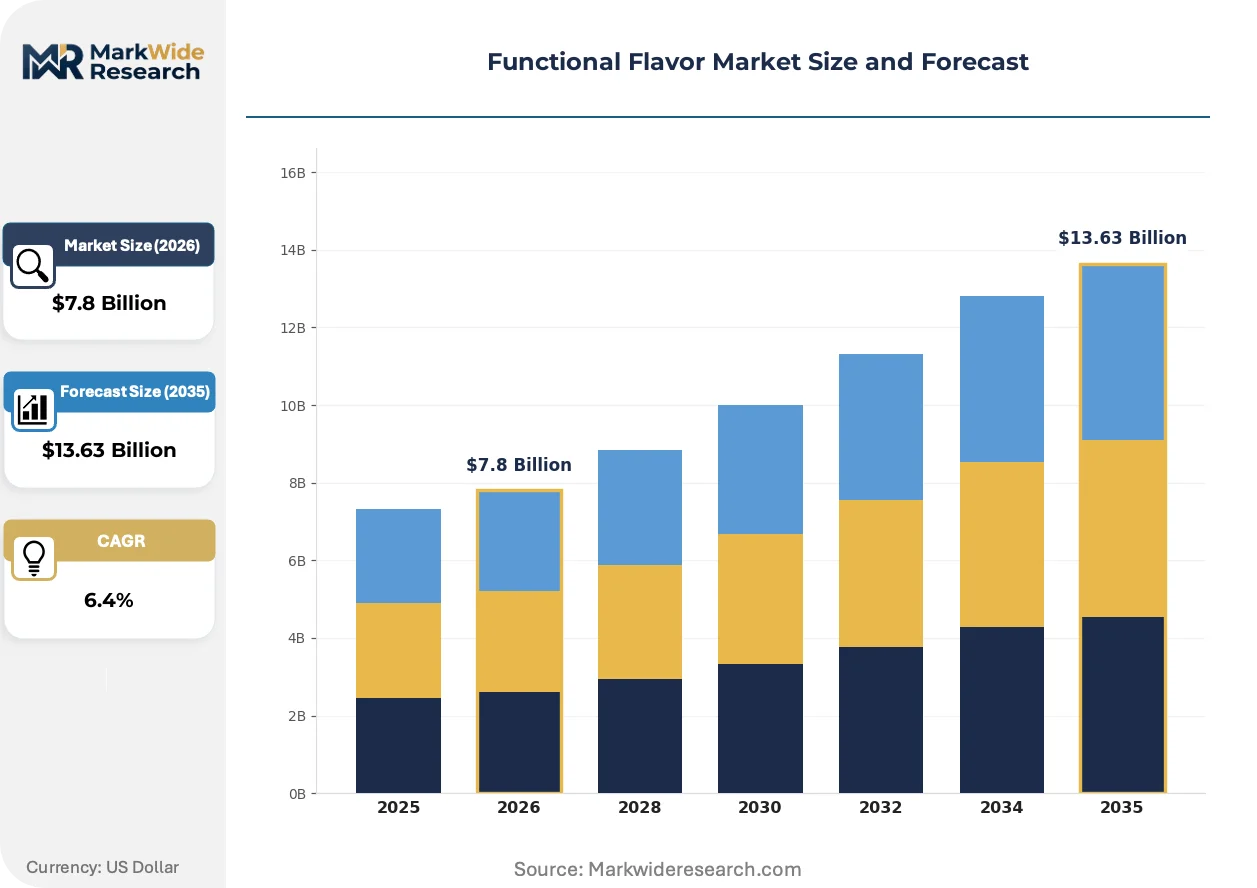
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Synthetic, Nature-Identical, Organic Application: Beverages, Confectionery, Dairy Alternatives, Savory Products, Nutraceuticals Form: Liquid, Powder, Encapsulated, Solid End User: Food Manufacturers, Beverage Producers, Dietary Supplement Companies, Bakeries |
| Companies Covered | Givaudan, Firmenich, Symrise, Sensient Technologies, International Flavors & Fragrances, Kerry Group, Mane, Archer-Daniels-Midland, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Flavor Market Shifts & Advancements
Biotechnology platforms are actively decomposing traditional extraction-based supply chains, while regulatory architectures in multiple jurisdictions simultaneously tighten evidentiary demands for bioactive claims.
Precision fermentation for nature-identical molecules is decomposing the economics of rare botanical sourcing. Beverage and supplement manufacturers accelerate adoption of fermentation-derived compounds as cost parity with extraction methods approaches. This technological shift compresses lead times for novel flavor launches and reduces geographic dependence on climate-vulnerable growing regions.
EFSA's flavoring group evaluations and the EU's Novel Food Regulation create parallel compliance architectures that determine which botanical extracts achieve commercial scale. The industrial consequence is a bifurcation between molecules with established safety dossiers and novel compounds facing multi-year evaluation timelines. Fermentation-derived ingredients with GRAS or novel food approval capture disproportionate investment as manufacturers prioritize regulatory certainty over unproven extraction innovations.
Buyer concentration among retail chains and contract manufacturers is compressing supplier qualification cycles and unbundling traditional full-service relationships. Direct sourcing of encapsulated actives by large beverage producers bypasses integrated flavor houses in specified applications. This pattern is most visible in Germany, where food manufacturer consolidation has reduced the number of qualified suppliers per reformulation category.
Functional Flavor Market Segmentation
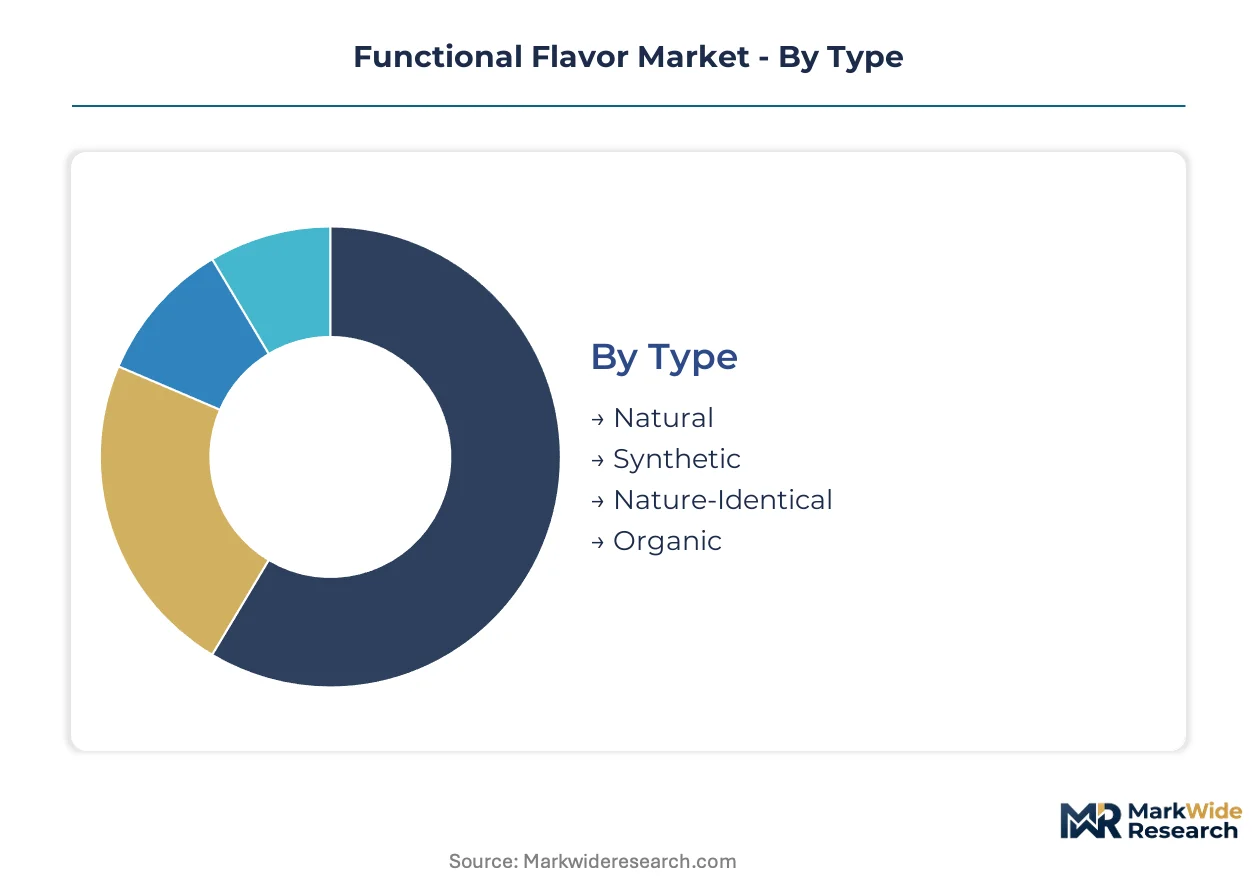
Segmentation in functional flavors reveals how clean-label mandates and biotechnology investments are reshaping procurement patterns across formulation types, application channels, and delivery formats. Manufacturers must align production capabilities with divergent technical requirements spanning beverage dispersion, supplement stability, and savory complex integration.
Type:
Natural and organic segments concentrate demand in Germany and France where EFSA purity standards drive domestic reformulation, while synthetic and nature-identical categories serve export markets with less stringent clean-label requirements.
- Natural:Botanical extracts and fermentation-derived compounds meeting EFSA flavoring group evaluations for unqualified natural claims. German beverage producers and French savory manufacturers anchor demand as retail chains enforce elimination of synthetic alternatives from shelved products.
- Synthetic:Chemically synthesized molecules produced through traditional organic synthesis routes. Cost-sensitive export markets in Eastern Europe and select Asian territories sustain volume as price positioning outweighs clean-label positioning.
- Nature-Identical:Precision fermentation and enzymatic biotransformation replicate molecular structures found in botanical sources. Givaudan and Firmenich leverage captive biotechnology platforms to supply German and French facilities with regulatory-certain alternatives to extraction-dependent supply chains.
- Organic:Certified organic botanical extracts and fermentation inputs meeting EU organic regulation standards. Premium positioning in German retail chains and Dutch organic food specialists drives disproportionate margin capture despite constrained raw material availability.
Natural holds the largest share; momentum sits with nature-identical as precision fermentation achieves cost parity with rare botanical extraction.
Application:
Beverage and nutraceutical applications command premium formulation complexity, while savory and dairy alternative segments concentrate volume in German manufacturing clusters.
- Beverages:Functional drinks and sports nutrition require homogeneous liquid dispersion and thermal stability through pasteurization. Encapsulated systems protect volatile actives as German producers reformulate legacy portfolios for clean-label retail mandates.
- Nutraceuticals:Dietary supplements demand powder and encapsulated formats with controlled-release profiles determining shelf-life performance. Symrise anchors supply through integrated savory flavor complexes adapted for metabolic support claims in German supplement brands.
- Confectionery:Heat-stable flavor systems for high-temperature processing environments. Cost-conscious formulation favors nature-identical molecules over premium natural extracts in mass-market product lines.
- Dairy Alternatives:Plant-based milk and yogurt applications requiring masking of off-notes from protein sources. Oat and pea protein bases in German and Benelux markets drive specialized savory and sweet flavor complex development.
- Savory Products:Integrated flavor systems delivering umami enhancement alongside sodium reduction and metabolic support positioning. German food manufacturer consolidation has reduced qualified supplier counts per reformulation category.
Beverages command the formulation premium; nutraceuticals are climbing the fastest as supplement powder formats capture disproportionate investment.
Form:
Liquid formats dominate beverage applications where dispersion homogeneity determines performance, while powder and encapsulated forms concentrate in dietary supplement and savory complex segments requiring extended stability.
- Liquid:Homogeneous solutions for immediate dispersion in aqueous systems. German beverage producers prioritize liquid formats for reformulated functional drinks despite shorter shelf-life constraints versus encapsulated alternatives.
- Powder:Spray-dried and agglomerated formats for dry blend applications and extended storage stability. Dietary supplement companies in Germany and France drive specification tightening around particle size distribution and flowability metrics.
- Encapsulated:Core-shell and matrix encapsulation protecting volatile actives through thermal processing and controlled release. Sports nutrition and supplement applications in German manufacturing clusters favor encapsulated systems for shelf-life extension.
- Solid:Compressed and extruded formats for confectionery and specific savory applications. Limited penetration outside traditional candy and seasoning tablet segments.
Liquid retains volume leadership; encapsulated formats gain share fastest as thermal processing protection becomes non-negotiable across beverage and supplement pipelines.
End User:
Food manufacturers and beverage producers concentrate procurement in Germany, while dietary supplement companies distribute demand across German, French, and Benelux production clusters.
- Food Manufacturers:Integrated savory flavor complexes for reformulated legacy portfolios. German consolidation has compressed supplier qualification cycles and unbundled traditional full-service relationships with integrated flavor houses.
- Beverage Producers:Direct sourcing of encapsulated actives bypasses integrated suppliers in specified applications. Large German functional drink manufacturers qualify alternative suppliers for cost leverage.
- Dietary Supplement Companies:Powder and encapsulated formats with stability and controlled-release specifications. German and Dutch contract manufacturers drive standardization around shelf-life performance metrics.
- Bakeries:Heat-stable flavor systems for industrial baking applications. Regional German and Austrian baking cooperatives sustain mid-scale demand outside consolidated manufacturer procurement.
Food manufacturers hold the largest procurement volume; dietary supplement companies are expanding most quickly as powder format specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French manufacturing clusters while cost-sensitive Eastern European markets absorb synthetic alternatives at compressed margins. EFSA flavoring group evaluations and REACH registration requirements create divergent compliance cost structures across Western and Eastern Europe. Regulatory friction between EU member states amplifies regional arbitrage opportunities for nature-identical compounds.
Germany
Food manufacturer consolidation in North Rhine-Westphalia and Bavaria compresses supplier qualification cycles for integrated savory flavor complexes. EFSA's tightening purity standards for natural claims accelerate investment in precision fermentation capabilities at facilities near Frankfurt and Munich. The country's central position in EU supply chains positions German producers as gatekeepers for clean-label distribution across the continent.
France
Savory flavor complex demand concentrates in Île-de-France and Auvergne-Rhône-Alpes as retail chains enforce elimination of synthetic alternatives from shelved products. ANSM and EFSA parallel compliance architectures determine which botanical extracts achieve commercial scale in French facilities. Lyon-based taste laboratories anchor regional customization capabilities for Mediterranean flavor profiles.
United States
FDA's Food Safety Modernization Act shapes ingredient approval timelines for fermentation-derived molecules entering beverage applications. EPA chemical substance review protocols add toxicological testing burdens distinct from EU REACH requirements. California and New Jersey manufacturing clusters specialize in encapsulated systems for sports nutrition brands demanding thermal processing protection.
China
SAMR flavor additive standards and GB food safety regulations create separate approval pathways for nature-identical compounds versus botanical extracts. Yangtze River Delta production clusters near Shanghai concentrate solvent extraction capacity for cost-sensitive export markets. Domestic beverage manufacturers accelerate adoption of encapsulated flavor systems as clean-label positioning penetrates tier-one cities.
India
FSSAI food additive regulations and BIS quality standards govern import and domestic production of synthetic and natural flavor categories. Maharashtra and Gujarat manufacturing corridors develop spray-dried powder capabilities for dietary supplement export markets. Domestic Ayurveda-inspired functional positioning drives specialized demand for botanical extracts with metabolic support claims.
Functional Flavor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the functional flavor market. Integrated biotechnology platforms command premium positioning in Western European and North American markets while extraction-dependent producers compete on cost in Asia-Pacific supply chains. The market structure bifurcates between captive fermentation asset owners and outsourced compound blenders. Strategic archetypes include integrated biotechnology houses, regional taste laboratories, and commodity extraction operators. Dominant competitive moves center on precision fermentation capacity expansion and regional sensory development center establishment.
Among Swiss and German-integrated biotechnology houses, Givaudan, Firmenich, and Symrise exemplify the technology-leadership archetype through captive control over rare botanical extraction pathways and fermentation-derived molecule supply. These entities occupy positions where regulatory certainty and supply security command pricing premiums over cost-optimized alternatives. Their geographic concentration in Western European regulatory jurisdictions reinforces competitive moats as EFSA and REACH frameworks tighten evidentiary demands.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| Sensient Technologies |
| International Flavors & Fragrances |
| Kerry Group |
| Mane |
| Archer-Daniels-Midland |
| Glanbia |
| Others |
Supply & Pricing Matrix
Precision fermentation substitution for rare botanical extraction is redrawing supply geography from climate-dependent growing regions to controlled bioreactor facilities near Frankfurt and Lyon, compressing input cost volatility while elevating capital-recovery premiums in contract pricing. This displacement simultaneously concentrates biotechnology asset ownership among integrated houses and fragments extraction-dependent suppliers into cost-competing tiers.
Pricing Analysis
The customization-premium spread between configured-to-order encapsulation systems and standard liquid formats spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade — EFSA flavoring group approval versus novel food dossier status — and volume scale, with German beverage producers commanding scale discounts unavailable to mid-tier supplement brands. Cost compression in synthetic categories is intensifying because Eastern European export markets absorb volume at compressed margins. Dietary supplement companies exhibit highest price sensitivity due to raw material concentration in qualified supplier networks, while integrated savory flavor complexes retain pricing power through captive formulation IP.
Supply Chain Analysis
Strait of Hormuz transit exposure for solvent extraction feedstocks underscores vulnerability in botanical supply chains serving European flavor houses. Geographic supply concentration centers on Germany, France, and Switzerland for precision fermentation capacity, with India and China anchoring solvent extraction and spray-dried powder production. Raw material dependencies include rare botanicals from specific growing regions, fermentation feedstocks, and encapsulation polymers. Single-source vulnerability in qualified extraction pathways for GRAS-approved botanicals creates supply chain risk. Distribution runs through integrated flavor houses for full-service relationships, while direct sourcing of encapsulated actives by large beverage producers bypasses traditional channels in specified applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across regulatory pathway bifurcation, as EFSA novel food evaluations and FDA GRAS determinations create divergent approval timelines that niche specialists can exploit. Clean-label mandate acceleration in German retail chains generates procurement niches for agile regional players.
For Market Incumbents: Fortify captive biotechnology platforms through precision fermentation capacity expansion near Frankfurt and Munich, securing regulatory-certain supply chains against extraction-dependent competitors. Defend margin position by accelerating novel food dossier submissions ahead of EFSA tightening, while consolidating regional taste laboratory networks to reduce R&D cycle times for customized savory complexes.
For New Entrants and Emerging Players: Anchor in dietary supplement powder formats where stability specifications and controlled-release engineering create technical barriers that favor specialized encapsulation houses over integrated flavor giants. White-space targets include German contract manufacturing clusters and Ayurveda-inspired metabolic support positioning for Indian export markets. A direct-sourcing partnership model with mid-scale beverage producers bypasses traditional supplier qualification bottlenecks.
For Investors and Strategic Acquirers: EFSA's 2023-2025 flavoring group evaluation reshapes the acquisition landscape toward fermentation-derived molecule platforms with established safety dossiers over unproven extraction innovations. Long-term viability favors vertically integrated biotechnology houses with dual-use infrastructure spanning flavor and nutraceutical production. Acquisition target archetype: regional taste laboratories with localized sensory capabilities and regulatory submission track records. The signal to watch is novel food approval velocity as inflection indicator for platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captive bioreactor assets near Frankfurt reduce dependence on climate-vulnerable botanical growing regions. |
| Regional Taste Laboratory Establishment | Lyon-based sensory centers accelerate Mediterranean flavor profile customization for French retail chains. |
| Novel Food Dossier Acceleration | EFSA submission timing determines commercial scale eligibility for fermentation-derived bioactive compounds. |
| Encapsulation Technology Licensing | Core-shell patent portfolios protect volatile actives through thermal processing in German beverage pipelines. |
| Backward Integration into Fermentation Feedstocks | Upstream control over glucose and nitrogen sources secures input cost stability for nature-identical production. |
Research Methodology
The analysis maps natural extracts, nature-identical molecules, synthetic compounds, and encapsulated delivery systems, each validated through flavor chemists, regulatory affairs directors, beverage procurement leads, and supplement formulation scientists. Primary interviews with integrated flavor house R&D heads and contract manufacturing procurement officers combined with secondary validation against EFSA flavoring group evaluations, FDA GRAS notices, REACH registration databases, and customs trade flows. Bottom-up segment sizing triangulates against top-down market consolidation from production capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models type, application, form, and end-user dimensions alongside regulatory pathway classification. CAGRs derive from segment-level growth rate synthesis and technology adoption curve positioning. Industry-specific forecast inputs include precision fermentation cost parity trajectories and EFSA evaluation timeline assumptions.
Material uncertainties — EFSA regulatory reclassification, botanical supply disruptions, and biotechnology platform cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about approval velocity and substitution economics. Practitioners should keep alternative scenarios live as clean-label mandate enforcement intensity and fermentation scale-up success rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Adaptogen Drink Market