
 Functional Water Market | 2026-2036
Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Water Market Intelligence
Subscription-based replenishment services is rebalancing how functional water reaches repeat buyers, shifting volume from impulse retail to predictable direct-to-home cadences. Danone leverages its European mineral water infrastructure to anchor premium positioning in regulated markets. PepsiCo competes through broad convenience store distribution that sustains mass-market electrolyte penetration. Nestlé specializes in pediatric and senior hydration formulations that occupy distinct benefit-led niches.
Functional water denotes potable water enhanced with dissolved minerals, vitamins, electrolytes, or botanical extracts to deliver specific physiological effects beyond basic hydration, typically formulated with total dissolved solids between 50 and 500 mg per liter depending on claimed benefit. Electrolyte water leads volume due to established sports consumption rituals, while vitamin water captures margin pools through higher per-unit pricing and immunity-positioned SKUs. E-commerce distribution channels represent the fastest-growing access point as fitness enthusiasts and working professionals adopt auto-replenishment models for home and workplace consumption.
The U.S. FDA governs health claim substantiation on functional water labels, while the EU EFSA evaluates permitted nutrition and health claims under EU Regulation 1924/2006, collectively restricting unsubstantiated benefit messaging that would otherwise accelerate trial. China's SAMR enforces national food safety standards for bottled drinking water including additive limits and label disclosures. Stakeholders must monitor evolving probiotic and adaptogen classification debates across these jurisdictions to anticipate reformulation requirements and preemptive compliance investments.
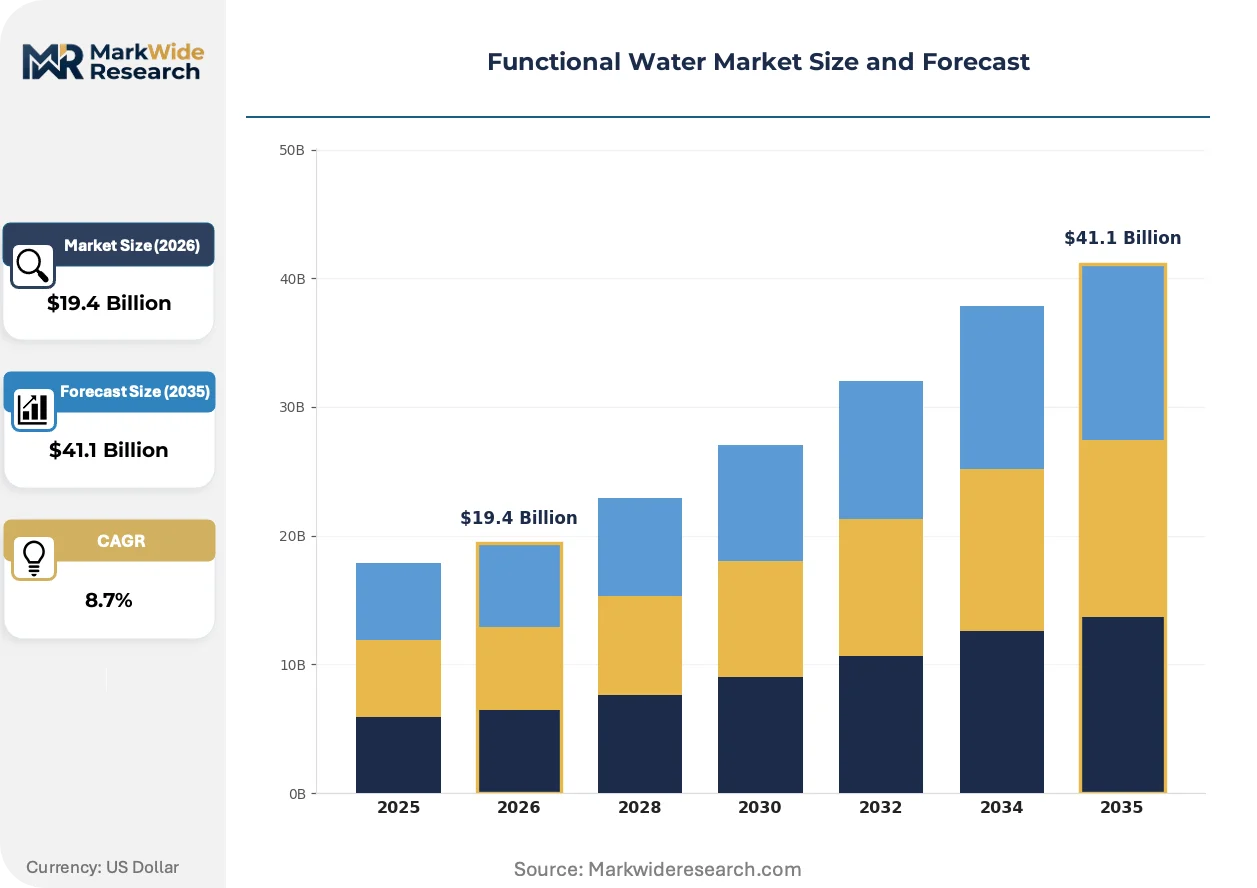
Market Dynamics
Subscription auto-replenishment is compressing traditional retail velocity for functional water, reconfiguring brand-consumer relationships around predictable consumption cadences rather than impulse purchase occasions. This shift demands reformulated logistics infrastructure and direct-to-home fulfillment capabilities that legacy beverage distribution networks were not architected to support.
Growth Catalysts
- Electrolyte Formulation Innovation:Precision mineral balancing for athletic recovery protocols is expanding consumption occasions beyond exercise into workplace hydration and travel wellness routines.
- China's SAMR Standards Evolution:Clarified additive approval pathways for functional beverages are accelerating product registration timelines for compliant international entrants.
- Sports Nutrition Channel Expansion:Gyms and fitness studios are dedicating refrigerated shelf space to recovery-positioned SKUs, creating dedicated consumption environments.
Market Restraints
- Spring Water Source Concentration:Premium functional water production depends on geographically concentrated natural mineral springs, creating supply vulnerability to regional drought or contamination events.
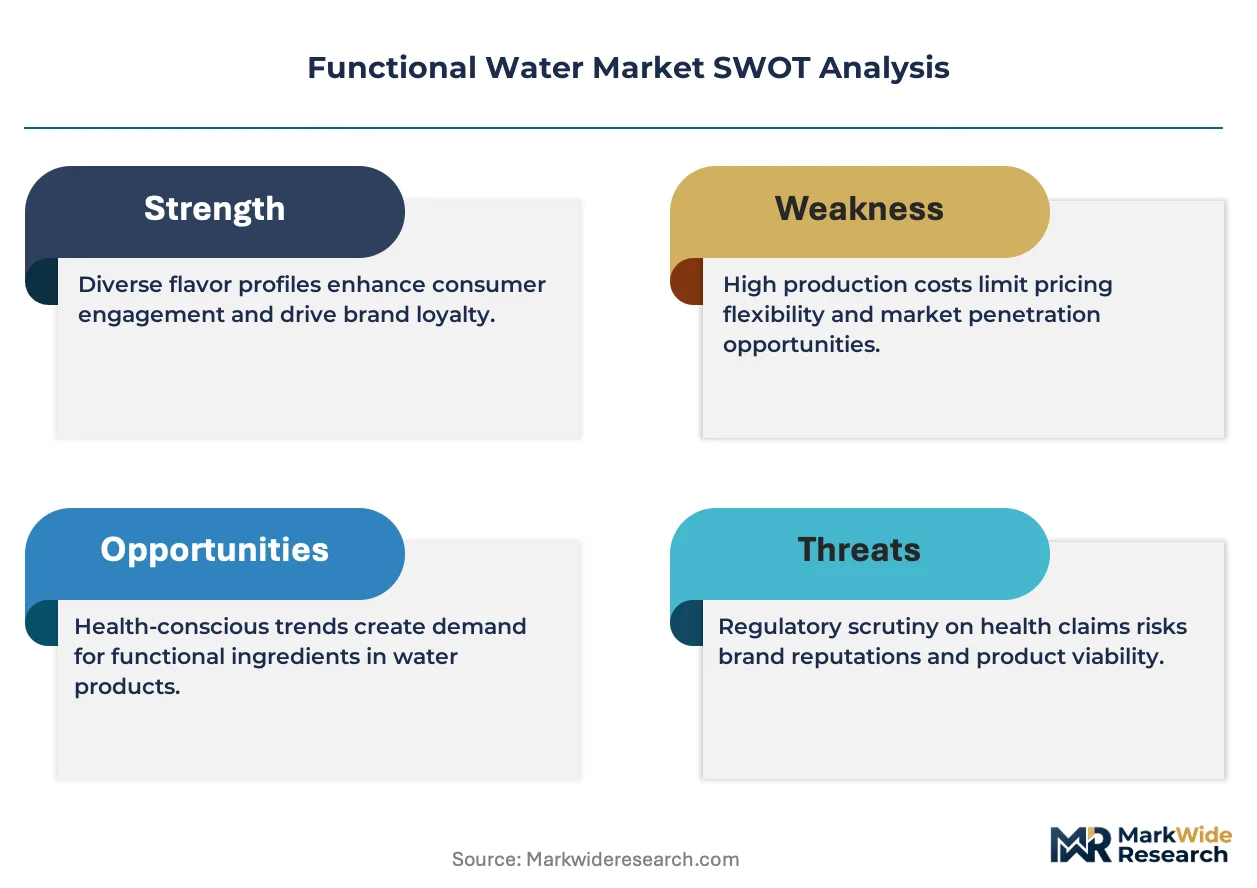
- EU EFSA Claim Substantiation Costs:Clinical trial requirements for permitted health claims impose six-figure validation burdens that filter out mid-tier competitors.
- Plain Filtered Water Substitution:Home filtration systems and reusable bottle infrastructure are capturing cost-conscious consumers who might otherwise trial functional alternatives.
Strategic Opportunities
- Pediatric Hydration Formulation Gap:Sugar-reduced, mineral-balanced products for children remain underdeveloped relative to adult-oriented SKUs, presenting first-mover positioning potential.
- Adaptogen Classification Clarity:Pending regulatory determinations on botanical additive status in China and the EU will unlock formulation possibilities currently constrained by uncertain compliance boundaries.
- Workplace Dispenser Integration:Corporate wellness programs are installing flavored and enhanced water stations as coffee alternatives, creating B2B volume channels with contracted annual commitments.
Industry Challenges
- Refrigerated Last-Mile Infrastructure:Direct-to-consumer subscription models require cold-chain fulfillment capabilities that strain existing logistics partnerships and capex budgets.
- Cross-Jurisdictional Label Harmonization:Divergent health claim permissible language between FDA, EFSA, and SAMR regimes forces SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Water Market |
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $41.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enhanced Water, Electrolyte Water, Vitamin Water, Mineral Water, Flavored Water Benefit: Hydration, Detoxification, Energy Boost, Immunity Support, Digestive Health Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, E-commerce, Specialty Stores, Vending Machines End User: Fitness Enthusiasts, Working Professionals, Students, Elderly Consumers, Travelers |
| Companies Covered | Danone, Hint Water, The Coca-Cola Company, The Alkaline Water Company, Tata Group, PepsiCo, Keurig Dr Pepper, Vitamin Well, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Water Market Strategic Shifts & Innovations
Functional water formulation is migrating from simple electrolyte replacement toward complex botanical and microbial systems that promise systemic wellness effects. This evolution demands new supplier capabilities, extended stability testing protocols, and revised regulatory engagement strategies.
Precision fermentation-derived bioactive compounds are integrating into functional water matrices as alternatives to plant-extracted adaptogens. Beverage formulators in North America and Western Europe are adopting these inputs to reduce agricultural supply dependencies and standardize potency. The technology is integrating supply chain control directly into manufacturing facilities, compressing reliance on volatile botanical commodity markets.
China's SAMR is tightening pre-market notification requirements for novel functional ingredients, extending approval timelines for probiotic and postbiotic formulations. Manufacturers are responding by front-loading clinical substantiation investments and establishing dedicated regulatory affairs functions in Beijing and Shanghai. Pediatric and senior-targeted SKUs face the most pronounced compliance burden given heightened safety scrutiny for vulnerable populations.
Fitness enthusiasts are consolidating purchasing decisions around bundled subscription services that combine functional water with supplements and recovery equipment. Specialty retailers and direct-to-consumer platforms are capturing this consolidated spend, displacing convenience store impulse purchases as the dominant trial channel. This behavioral shift is most visible in tier-one Chinese cities and coastal US metropolitan areas where delivery infrastructure density supports reliable auto-replenishment cadences.
Functional Water Market Segmentation
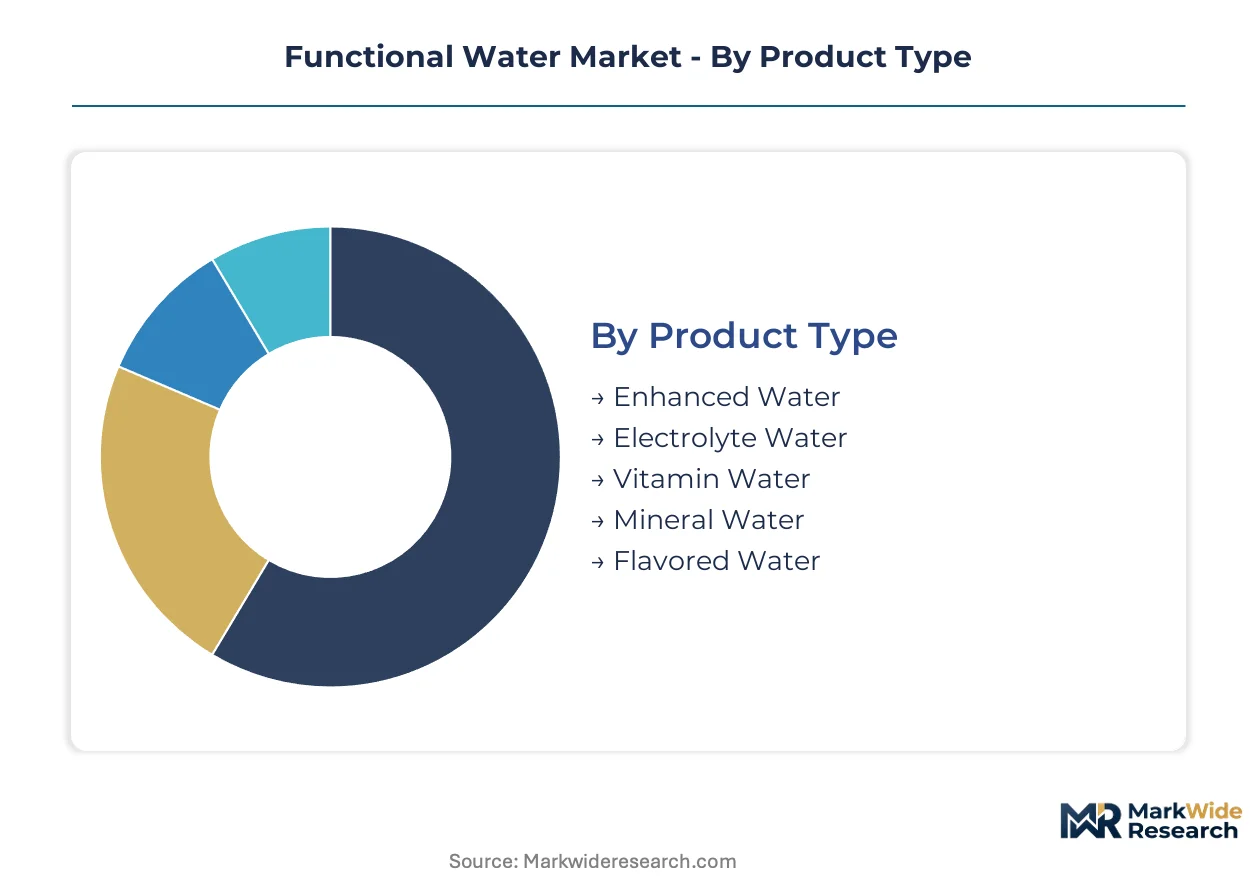
Functional water manufacturers configure product portfolios across four intersecting dimensions that determine pricing power, channel access, and regulatory burden. Each segmentation axis carries distinct margin profiles and compliance requirements that shape resource allocation decisions.
Product Type:
Price tolerance and consumption occasion intensity guide product selection, with athletic recovery rituals commanding premium positioning.
- Electrolyte Water:Formulated with sodium, potassium, and magnesium salts dissolved to 150-300 mg total dissolved solids per liter for rapid osmotic balance restoration. Demand concentrates in China's tier-one cities and coastal US metropolitan areas where gym culture and subscription auto-replenishment have created predictable consumption cadences.
- Vitamin Water:Fortified with water-soluble vitamins C, B-complex, and occasionally fat-soluble D and E through microemulsion stabilization. Immunity-positioned SKUs capture margin pools through higher per-unit pricing in specialty retail and direct-to-consumer channels.
- Enhanced Water:Broad category spanning botanical extracts, amino acids, and novel bioactive compounds with targeted physiological claims.
- Mineral Water:Naturally sourced from protected springs with inherent mineral content, subject to geographic concentration risk.
- Flavored Water:Taste-forward formulations with minimal functional positioning, competing on palatability rather than physiological benefit.
Volume sits with Electrolyte Water; growth tilts toward Vitamin Water.
Benefit:
Claim substantiation costs and regulatory pathway complexity stratify competitive entry barriers across benefit positions.
- Immunity Support:Vitamin C, zinc, and emerging postbiotic formulations targeting immune cell function require clinical validation under FDA and EFSA frameworks. China's SAMR pre-market notification timelines extend approval cycles, filtering out undercapitalized entrants.
- Energy Boost:Caffeine, taurine, and B-vitamin combinations deliver acute alertness effects with established safety profiles. Workplace consumption in corporate wellness programs and travel wellness routines expands occasion penetration beyond traditional retail.
- Hydration:Baseline functional positioning with minimal differentiation, competing on mineral balance precision and taste neutrality.
- Detoxification:Botanical and antioxidant claims face heightened scrutiny under EU Regulation 1924/2006 and evolving SAMR standards.
- Digestive Health:Probiotic and prebiotic formulations encounter classification debates across US, EU, and Chinese jurisdictions.
Revenue concentrates in Immunity Support; steepest expansion trajectory belongs to Energy Boost.
Distribution Channel:
Channel selection determines cold-chain infrastructure requirements and customer relationship depth.
- E-commerce:Auto-replenishment subscriptions and direct-to-consumer platforms compress traditional retail velocity. Fitness enthusiasts and working professionals in tier-one Chinese cities and US coastal metros drive adoption.
- Convenience Stores:Impulse purchase infrastructure sustains mass-market penetration for electrolyte and energy-positioned SKUs.
- Supermarkets & Hypermarkets:Refrigerated shelf space competition favors established brands with slotting fee capacity.
- Specialty Stores:Gyms, fitness studios, and wellness retailers create dedicated consumption environments for recovery-positioned products.
- Vending Machines:Workplace and transit placement captures on-the-go hydration occasions with limited assortment depth.
Transaction volume flows through Convenience Stores; customer lifetime value peaks in E-commerce.
End User:
Demographic targeting dictates formulation complexity, packaging format, and communication strategy.
- Fitness Enthusiasts:Athletes and gym members with established recovery protocols drive electrolyte water consumption through sports nutrition channels. Bundled subscription services with supplements and equipment consolidate purchasing decisions.
- Working Professionals:Corporate wellness program integration and workplace dispenser installations create B2B volume channels with contracted annual commitments.
- Students:Price-sensitive segment with energy and focus-positioned product preference.
- Elderly Consumers:Pediatric and senior hydration formulations face heightened safety scrutiny under China's SAMR and other regulatory regimes.
- Travelers:Portable format preference and jet lag recovery positioning drive airport and hospitality channel placement.
Current spend concentrates with Fitness Enthusiasts; penetration opportunity sits with Elderly Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional water production clusters around established mineral spring infrastructure, while consumption concentrates in affluent urban centers with fitness culture penetration and subscription logistics density.
United States
Fitness enthusiasts and working professionals drive electrolyte and vitamin water demand through gym channels and workplace wellness programs. The FDA tightens health claim substantiation requirements under evolving functional beverage frameworks. Coastal metropolitan areas from Los Angeles to New York sustain the highest subscription auto-replenishment adoption rates.
China
Tier-one city consumers command premium pricing for imported and domestic enhanced hydration products with immunity-positioned SKUs. SAMR enforces national food safety standards for bottled drinking water including additive limits and novel ingredient pre-market notification. Shanghai and Beijing host the densest concentration of specialty fitness retailers and direct-to-consumer fulfillment infrastructure.
Germany
Natural mineral water traditions intersect with demand for botanical-enhanced functional variants in wellness-oriented consumer segments. EFSA evaluates permitted nutrition and health claims under EU Regulation 1924/2006, imposing clinical validation burdens. Bavaria's protected spring sources anchor premium production capacity for regulated European markets.
Japan
Aging demographics sustain interest in senior-targeted hydration formulations with mineral balance precision. METI oversees food labeling and functional food standards including FOSHU claims for physiological benefits. The Kanto region around Tokyo concentrates both manufacturing R&D and high-frequency consumption in corporate wellness programs.
Brazil
Price-conscious consumers gravitate toward flavored and energy-positioned functional water in convenience retail channels. ANVISA regulates food additives and health claims with evolving frameworks for novel bioactive ingredients. São Paulo's metropolitan consumer base represents the primary volume opportunity for mass-market electrolyte penetration.
Functional Water Market Key Industry Players
Capital-heavy producers with captive spring sources and bottling infrastructure compete with asset-light brand developers that outsource manufacturing to contract packers. Market structure tilts toward consolidation at the premium tier while mid-market segments fragment across regional specialists and private label entrants. Three archetypes dominate: integrated beverage conglomerates with mineral water heritage, sports nutrition specialists with fitness channel access, and direct-to-consumer pure-plays with subscription-first business models. Competitive dynamics center on M&A activity to secure spring water concessions and strategic partnerships with fitness chains for exclusive placement.
Among diversified beverage conglomerates, Danone and PepsiCo occupy positions that exemplify contrasting strategic postures—European mineral water infrastructure anchoring premium regulated markets versus mass-market electrolyte penetration through convenience density. Nestlé sits within the specialized nutrition tier, representing formulation expertise in pediatric and senior hydration segments that command distinct benefit-led positioning. These three entities illustrate how scale, geographic origin, and portfolio breadth determine resource allocation across electrolyte, vitamin, and enhanced water sub-categories.
| Leading Market Players |
|---|
| Danone |
| Hint Water |
| The Coca-Cola Company |
| The Alkaline Water Company |
| Tata Group |
| PepsiCo |
| Keurig Dr Pepper |
| Vitamin Well |
| Nestlé |
| Others |
Cost & Logistics Intelligence
Fitness enthusiasts and working professionals in tier-one Chinese cities and US coastal metros anchor the dominant subscription-based pricing model, where predictable auto-replenishment cadences compress per-unit price sensitivity in exchange for lifetime value capture. This buyer concentration shapes how brands allocate margin between acquisition discounts and retention infrastructure.
Pricing Analysis
Margin tightening in the premium tier reflects SAMR pre-market notification burdens and EFSA clinical validation costs that filter out undercapitalized competitors. Three-tier pricing structure across premium, standard, and economy levels separates electrolyte formulations with precision mineral balancing from basic enhanced waters and flavored variants. Cost compression accelerates in the mass-market tier as home filtration systems capture price-conscious trial. Students and cost-sensitive Brazilian consumers exhibit highest price sensitivity; fitness enthusiasts and corporate wellness programs show lowest.
Supply Chain Analysis
Certification requirements for natural mineral spring sourcing and FDA label substantiation gate entry into premium regulated markets. Production draws from protected spring sources in Bavaria, France's Vosges region, and China's Changbai Mountain watershed. Key inputs include food-grade mineral salts, botanical extracts, and precision fermentation-derived bioactives. Single-source vulnerability concentrates around geographically fixed spring concessions vulnerable to drought or contamination. Distribution runs through cold-chain direct-to-home fulfillment for subscription tiers and refrigerated retail for impulse channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive spring water concessions and in-house precision fermentation capacity determine margin sustainability against contract-manufactured competitors.
For Market Incumbents: Anticipate probiotic classification clarity from SAMR and EFSA by front-loading clinical substantiation investments and establishing dedicated regulatory affairs functions in Beijing and Shanghai. Secure exclusive spring water concessions through concession extensions or strategic partnerships before drought risk escalates pricing volatility. Defend against direct-to-consumer pure-plays by accelerating cold-chain fulfillment infrastructure buildout. For New Entrants and Emerging Players: Capture the pediatric hydration formulation gap where sugar-reduced, mineral-balanced products remain underdeveloped relative to adult-oriented SKUs. Target China's tier-one cities through bundled subscription services combining functional water with supplements and recovery equipment. Penetrate via corporate wellness program integration with workplace dispenser installations that create B2B volume channels with contracted annual commitments. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light brand developers with subscription-first business models in North American coastal metros where delivery infrastructure density supports reliable auto-replenishment. Long-term viability hinges on regulatory navigation capabilities across FDA, EFSA, and SAMR regimes. Watch for SAMR probiotic classification determinations as inflection indicator for formulation expansion capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Spring Water Concession Security | Captive mineral spring access in Bavaria and Vosges insulates premium positioning from supply volatility. |
| Precision Fermentation Integration | In-house bioactive compound production reduces agricultural supply dependencies and standardizes potency consistency. |
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment compresses retail velocity while capturing higher customer lifetime value pools. |
| Pediatric Formulation Development | Sugar-reduced, mineral-balanced SKUs address underserved demographic with heightened safety scrutiny barriers. |
| Corporate Wellness Partnership | Workplace dispenser installations create B2B channels with contracted annual commitments beyond retail impulse. |
Research Approach
Document review covered FDA guidance documents, EFSA health claim registers, SAMR food safety standards, and trade customs records, complemented by interviews with brand managers at functional water manufacturers, category buyers at specialty fitness retailers, supply planners at contract packers, and regulatory affairs leads navigating multi-jurisdictional claim substantiation. Secondary validation drew from company SEC filings, Nielsen retail audit data, and spring source concession registries. Bottom-up volume modeling triangulated against top-down category spend analysis.
Segment-level projections across electrolyte, vitamin, enhanced, mineral, and flavored product types incorporated benefit-positioning stratification, distribution channel mix shifts, and end-user demographic penetration rates. The analytical framework modeled price elasticity differentials between subscription and transactional channels, regulatory approval timeline distributions for novel ingredients, and cold-chain logistics cost curves throughout the forecast period. CAGRs derived from historical consumption pattern analysis, fitness culture penetration trajectories, and corporate wellness program adoption curves.
The model holds under stable regulatory classification regimes for probiotics and adaptogens; deviation in SAMR or EFSA determinations would shift formulation investment timelines and competitive entry barriers. Forecasts reflect assumptions regarding spring source availability, subscription logistics infrastructure scaling, and health claim substantiation cost trajectories. A model refresh is warranted upon material change in China's novel ingredient approval pathways or significant drought events affecting protected European spring sources.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market