
 Middle East and Africa Functional Beverages Market | 2026-2036
Middle East and Africa Functional Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Functional Beverages Market Foresight
The Middle East and Africa functional beverages category is recalibrating around a widening split between premium fortified formulations and commodity energy drinks. Nestlé leverages its dairy and nutrition heritage to anchor premium positioning in probiotic and fortified segments across Gulf markets. PepsiCo competes through extensive convenience store and supermarket distribution networks that sustain volume leadership in mass-market energy and sports drinks. Almarai differentiates by integrating dairy-based functional beverages with its existing cold-chain infrastructure, occupying a distinctive position in regional nutritional juices.
Functional beverages are non-alcoholic drinks enhanced with bioactive ingredients, vitamins, minerals, amino acids, or botanical extracts, formulated to deliver targeted physiological benefits beyond basic hydration; manufacturing typically involves aseptic processing or hot-fill methods to preserve thermolabile compounds such as live probiotic cultures. Energy drinks and sports drinks dominate current volume, though probiotic formulations represent the fastest-expanding margin pool as Gulf consumers prioritize gut health claims. The formulation dimension—spanning organic, low-sugar, fortified, and herbal variants—determines pricing architecture, with low-sugar and herbal products commanding shelf-space premiums in health food shops and expanding e-commerce channels.
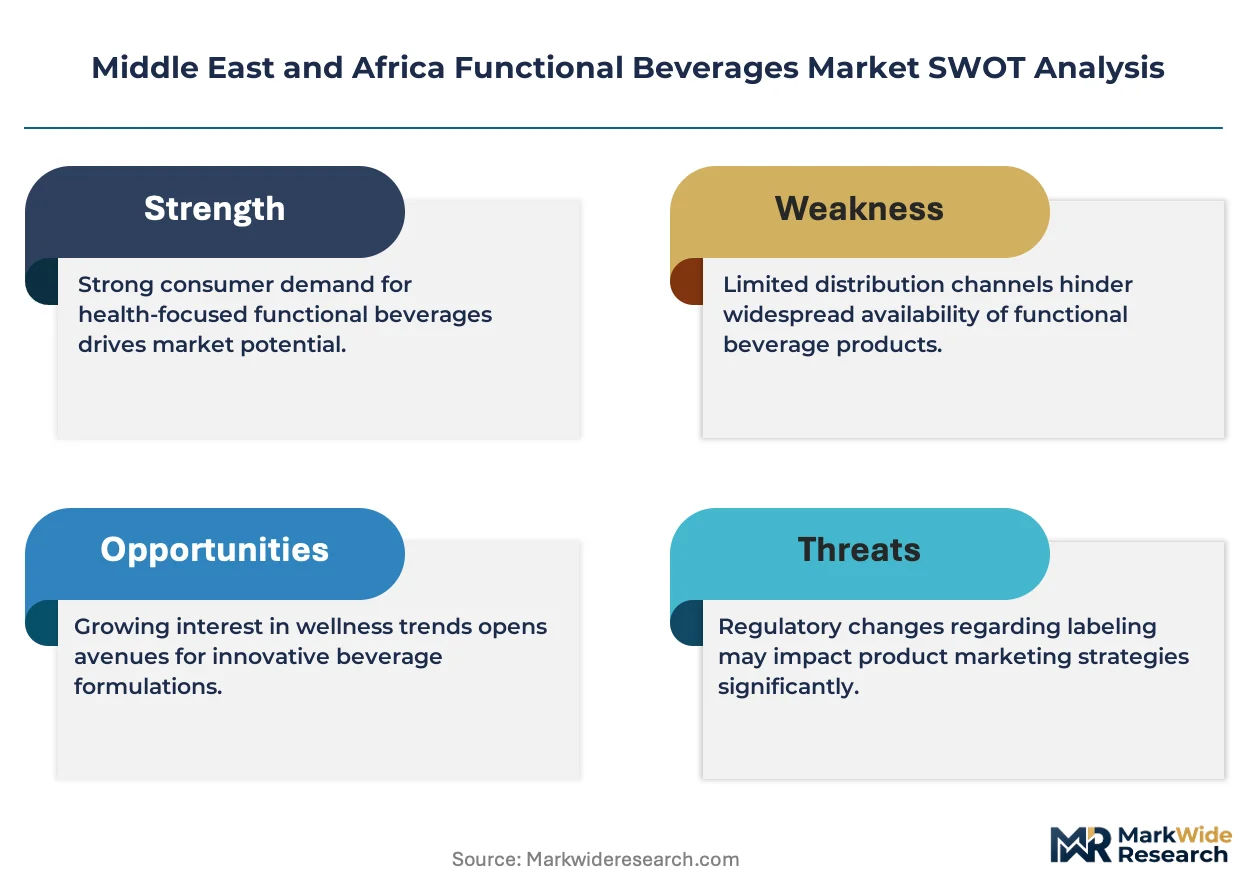
Saudi Food and Drug Authority standards on sugar content, UAE Ministry of Industry and Advanced Technology labeling requirements, and South African National Regulator for Compulsory Specifications fortification rules collectively reshape product composition and import eligibility across the region. These frameworks elevate compliance costs for new entrants while creating structural advantages for established players with in-house regulatory affairs capabilities. Stakeholders must monitor evolving Gulf harmonization initiatives and local content requirements that could redraw competitive boundaries faster than brand equity alone permits.
Market Dynamics
Sugar taxation frameworks across Gulf Cooperation Council states are compressing formulation margins and forcing manufacturers toward low-sugar and herbal repositioning faster than consumer preference alone would dictate.
Growth Catalysts
- SFDA Sugar Taxation Framework:Saudi Arabia's tiered excise duties on sweetened beverages redirect R&D investment toward reduced-sugar and botanical formulations, accelerating portfolio transformation.
- E-commerce Penetration:Digital grocery platforms across the UAE and Saudi Arabia expand addressable reach for premium probiotic and fortified SKUs beyond traditional retail footprints.
- Gut Health Prioritization:Health-conscious consumers in Dubai and Riyadh elevate probiotic claims to primary purchase criteria, expanding margin pools for live-culture formulations.
Market Restraints
- Import Dependency for Active Cultures:Thermolabile probiotic strains require temperature-controlled supply chains concentrated among European and North American suppliers, elevating input cost volatility.
- Cold-Chain Infrastructure Gaps:Last-mile refrigeration deficits in sub-Saharan African markets constrain live-culture product viability outside South Africa's urban corridors.
- Labeling Harmonization Friction:Divergent UAE Ministry of Industry and Advanced Technology and South African National Regulator for Compulsory Specifications requirements inflate compliance overhead for multi-market portfolios.
Strategic Opportunities
- Nigeria's Underpenetrated Urban Markets:Lagos and Abuja's expanding middle-class cohorts present first-mover potential for fortified dairy-based functional beverages with localized flavor profiles.
- Herbal-Functional Convergence:Traditional Middle Eastern botanicals—saffron, dates, black seed—offer differentiation vectors for wellness-positioned entrants seeking premium shelf placement.
- MOHAP Clean Label Incentives:UAE Ministry of Health and Prevention certification pathways for reduced-additive products create regulatory tailwinds for manufacturers investing in minimal-processing technologies.
Industry Challenges
- Live-Culture Formulation Expertise Scarcity:Gulf-based manufacturers face acute shortages of food microbiologists capable of optimizing probiotic stability across hot-fill and aseptic processing lines.
- Multi-Jurisdiction Certification Timelines:Sequential approvals across Saudi SFDA, UAE MOHAP, and South African NRCS extend product launch cycles by 14-22 months for regional rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Functional Beverages Market |
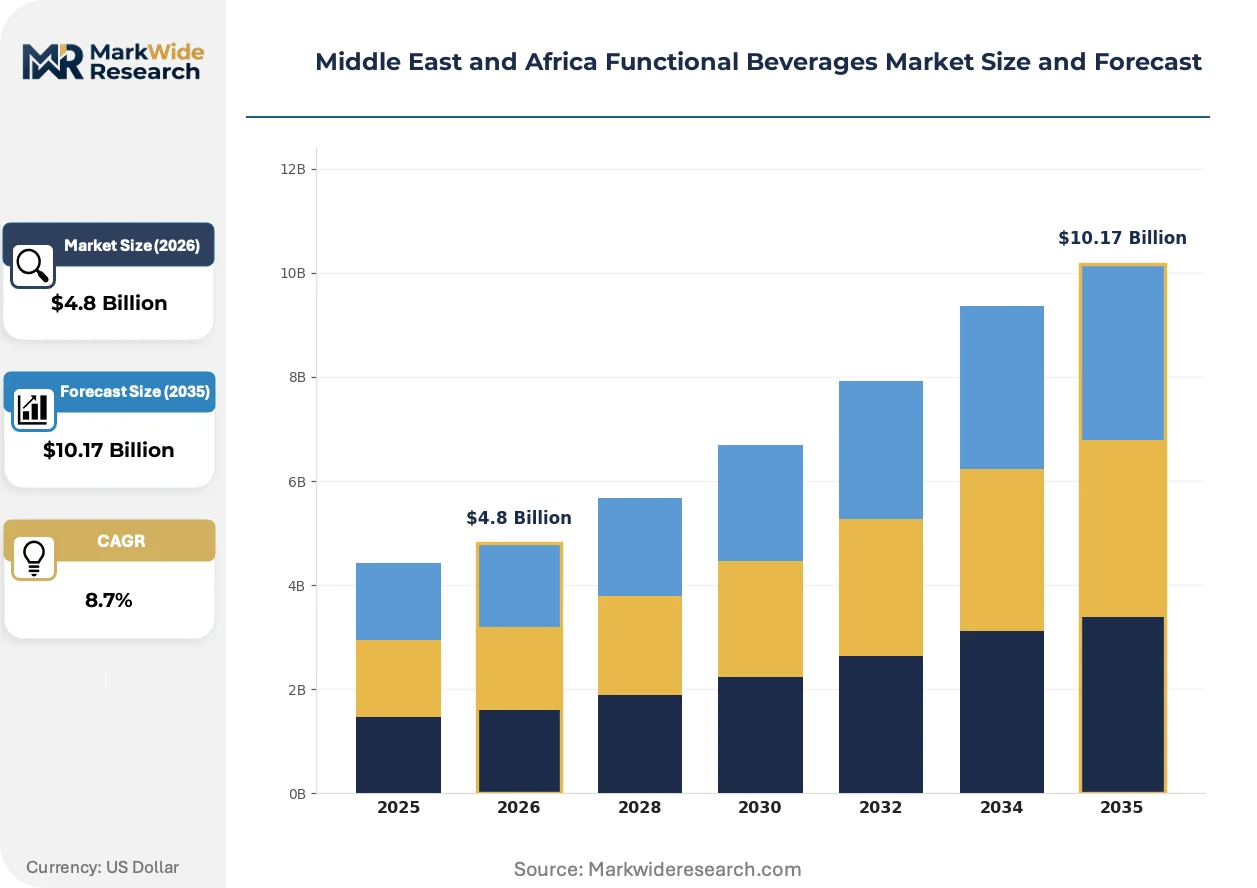
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Nutritional Juices, Probiotics Target Consumer: Health Enthusiasts, Athletes, Students, Busy Professionals Distribution Channel: Supermarkets, E-commerce, Convenience Stores, Health Food Shops Formulation: Organic, Low Sugar, Fortified, Herbal |
| Companies Covered | Nestlé, PepsiCo, The Coca-Cola Company, Red Bull GmbH, Monster Beverage Corporation, Danone S.A., Almarai, General Mills, Suntory Holdings Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Functional Beverages Market Shifts & Advancements
Formulation science and distribution architecture are converging to redefine competitive advantage, with preservation technologies and channel strategy displacing brand heritage as primary value drivers.
Aseptic processing with nitrogen flushing is decentralizing production economics for thermolabile functional beverages. Regional dairy processors in Saudi Arabia and the UAE are adopting modular aseptic lines at accelerating pace. This technology is decentralizing manufacturing scale requirements, enabling mid-cap entrants to challenge multinational volume positions in probiotic segments.
SFDA's 2023 extension of sugar taxation to include malt-based beverages is compressing energy drink formulation flexibility. Manufacturers must reformulate with alternative sweeteners or absorb margin erosion. The mass-market energy segment across Saudi Arabia responds with stevia-monk fruit blends and aggressive price repositioning to maintain volume.
Subscription-based replenishment models are displacing traditional supermarket stock-up behavior among affluent Gulf consumers. Direct-to-consumer platforms capture recurring revenue from health-committed households seeking personalized probiotic regimens. This shift concentrates most visibly in Dubai's high-income residential clusters where delivery infrastructure supports chilled last-mile execution.
Middle East and Africa Functional Beverages Market Segmentation
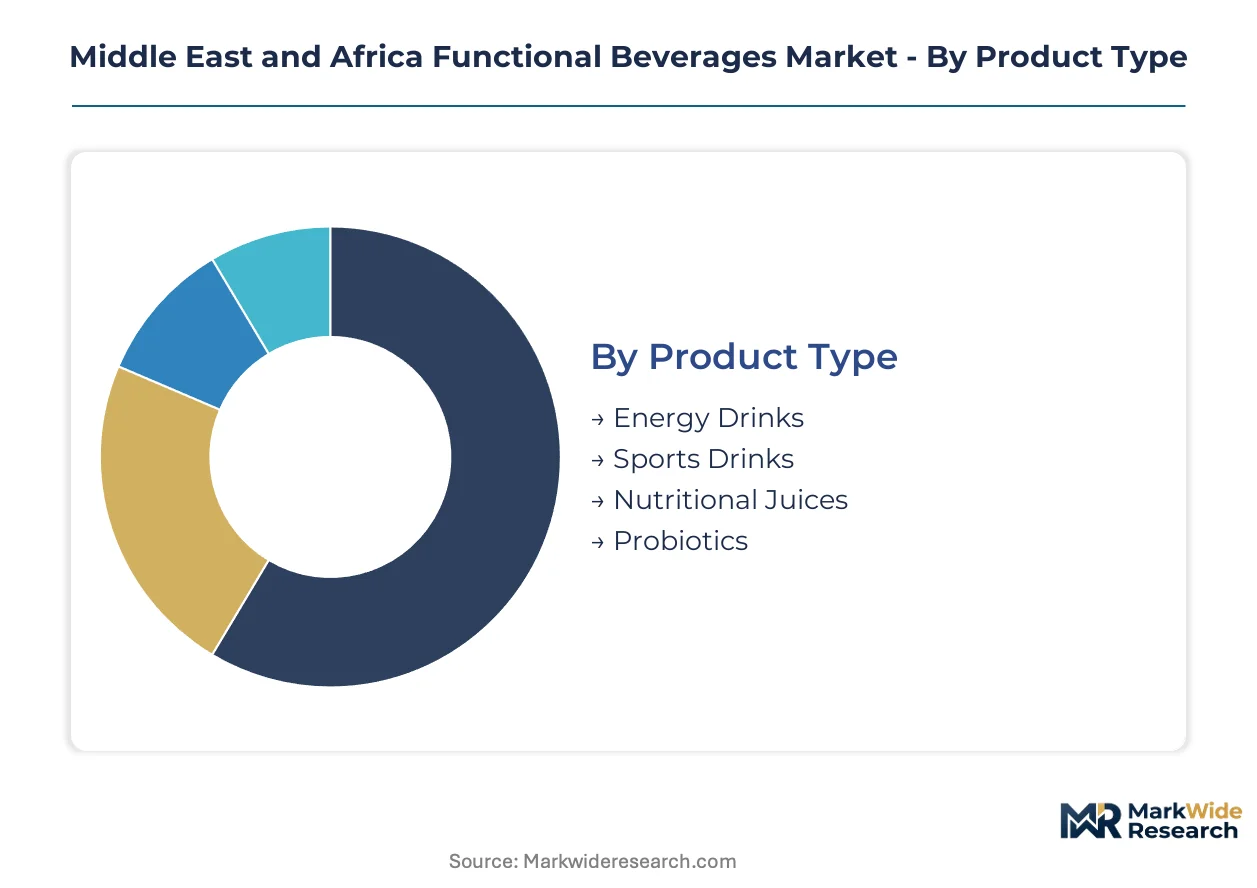
Segmentation in the Middle East and Africa functional beverages market reveals how formulation choices and channel strategies diverge sharply between Gulf premium corridors and price-sensitive African mass markets. Understanding these splits enables manufacturers to align R&D investment with regulatory pressures and distribution infrastructure realities.
Product Type:
Buyers differentiate primarily by consumption occasion and physiological need state rather than brand loyalty alone.
- Energy Drinks:Caffeine and taurine formulations dominate impulse purchases at convenience stores and fuel stations across Saudi Arabia and the UAE. SFDA sugar taxation is compressing margins and forcing reformulation with stevia-monk fruit blends to maintain volume positions.
- Sports Drinks:Electrolyte-replenishment formulations with sodium, potassium, and magnesium target fitness-conscious consumers in Dubai's gym clusters and Riyadh's athletic clubs. Demand concentrates where modern retail infrastructure supports chilled distribution.
- Nutritional Juices:Vitamin-fortified fruit and vegetable blends appeal to health-committed households seeking meal supplementation. Almarai leverages dairy-based integration to capture premium positioning in Saudi retail.
- Probiotics:Live-culture formulations with Lactobacillus and Bifidobacterium strains command shelf-space premiums in health food shops and e-commerce channels. Cold-chain requirements limit viability outside South Africa's urban corridors and Gulf metropolitan areas.
Energy Drinks leads volumes today; Probiotics is gaining share fastest.
Target Consumer:
Consumer archetypes map directly to pricing tiers and channel preferences across the region's fragmented retail landscape.
- Health Enthusiasts:Gut-health prioritizers in Dubai and Riyadh drive probiotic premiumization, accepting subscription pricing for personalized live-culture regimens delivered through direct-to-consumer platforms.
- Athletes:Electrolyte-focused consumers cluster around fitness infrastructure in Abu Dhabi and Johannesburg, purchasing sports drinks through gym partnerships and specialized retailers.
- Students:Price-sensitive caffeine seekers in Cairo and Lagos mass markets respond to aggressive convenience store promotions and smaller-format packaging.
- Busy Professionals:Time-constrained urban workers in Nairobi and Casablanca favor ready-to-drink nutritional juices for meal replacement, accessible through supermarket express lanes and digital grocery platforms.
Students represent the largest addressable population; Health Enthusiasts show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines formulation viability and temperature-control requirements throughout the supply chain.
- Supermarkets:Hypermarket and supermarket chains in the GCC anchor volume for fortified and low-sugar variants, with shelf-space allocation increasingly favoring reduced-sugar SKUs under regulatory pressure.
- E-commerce:Digital grocery platforms in the UAE and Saudi Arabia expand reach for premium probiotic SKUs beyond traditional retail footprints, capturing recurring revenue through subscription models.
- Convenience Stores:Petrol station and neighborhood convenience networks sustain energy drink velocity through impulse placement and promotional pricing.
- Health Food Shops:Specialized retailers in Dubai's Jumeirah and Riyadh's Al Olaya districts command premium positioning for organic and herbal formulations with minimal processing claims.
Supermarkets dominate transaction volumes; E-commerce climbs the fastest.
Formulation:
Formulation architecture separates premium shelf placement from commodity positioning as regulatory frameworks tighten.
- Organic:Certified organic formulations with pesticide-free ingredient sourcing occupy premium positioning in health food shops and affluent Gulf supermarkets, though certification costs limit manufacturer participation.
- Low Sugar:Reduced-sugar and sugar-free variants using stevia, monk fruit, and erythritol are redirecting R&D investment across Saudi manufacturing as SFDA taxation tiers penalize conventional sweeteners.
- Fortified:Vitamin D, calcium, and iron-enriched formulations target nutritional deficiency gaps in Nigerian and Kenyan urban markets, often integrated with dairy-based delivery systems.
- Herbal:Botanical formulations incorporating saffron, dates, black seed, and other traditional Middle Eastern ingredients offer differentiation vectors for wellness-positioned entrants seeking MOHAP clean label certification.
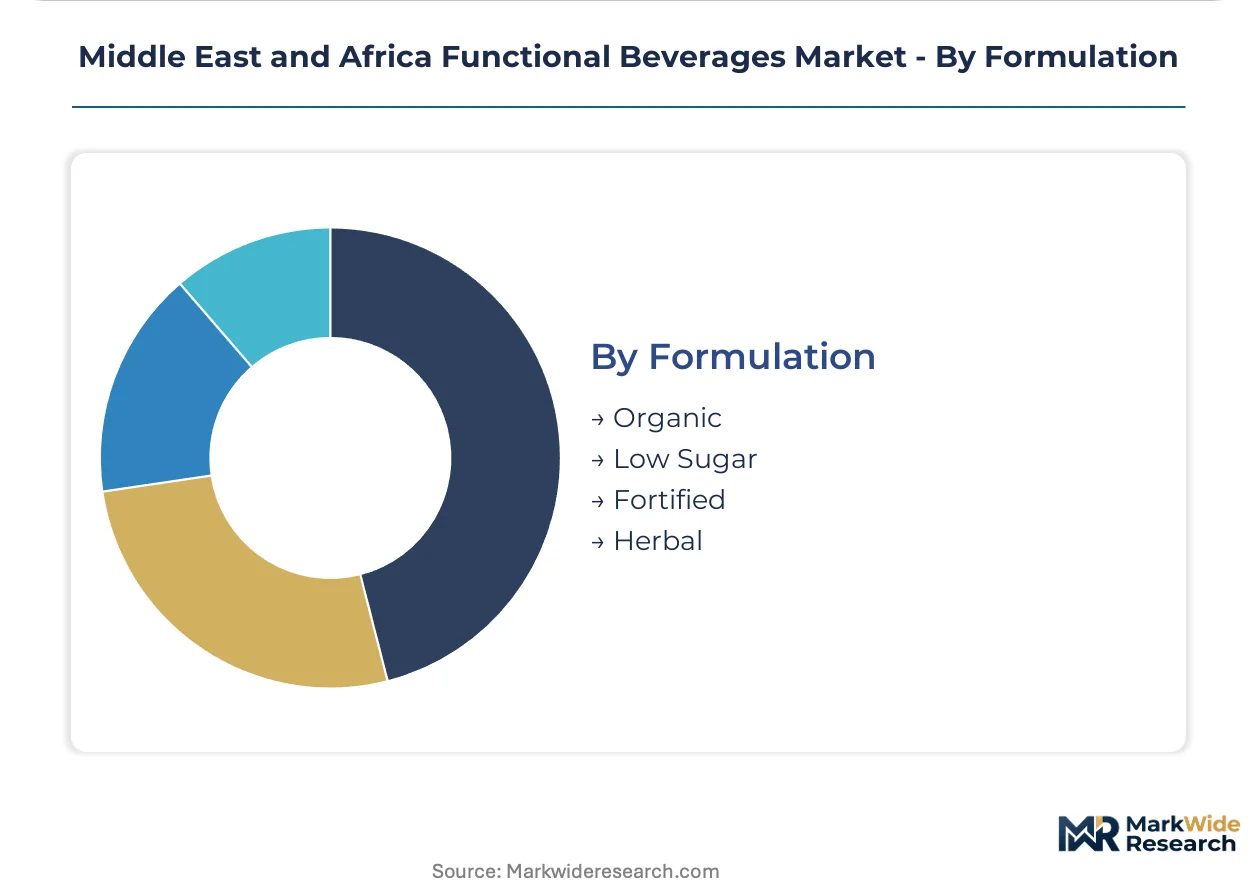
Fortified formulations hold current volume leadership; Herbal variants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food microbiologists and cold-chain engineers concentrate in Gulf metropolitan clusters, anchoring functional beverage innovation capacity across the Middle East and Africa corridor.
Saudi Arabia
Riyadh's health-committed professionals and Jeddah's fitness-oriented consumers drive probiotic and low-sugar formulation demand. The Saudi Food and Drug Authority's tiered sugar taxation redirects manufacturer R&D toward stevia-monk fruit blends and botanical alternatives. Dammam's Eastern Province industrial zone hosts expanding aseptic processing facilities serving GCC export markets.
United Arab Emirates
Dubai's affluent expatriate population and Abu Dhabi's wellness-focused government employees sustain premium positioning for fortified and herbal functional beverages. The UAE Ministry of Health and Prevention's clean label certification pathways reward minimal-processing investments with regulatory preferencing. Dubai's Jebel Ali free zone concentrates regional distribution headquarters for multinational beverage portfolios.
South Africa
Johannesburg's athletic club culture and Cape Town's organic food retail expansion support sports drink and nutritional juice segments. The National Regulator for Compulsory Specifications enforces fortification standards that elevate compliance costs for imported formulations. Durban's port infrastructure and cold-chain logistics enable live-culture product viability reaching sub-Saharan urban corridors.
Nigeria
Lagos middle-class households and Abuja's time-constrained professionals generate demand for ready-to-drink nutritional juices as meal replacements. The National Agency for Food and Drug Administration and Control regulates import eligibility for vitamin-fortified formulations. Lagos-Ibadan corridor manufacturing zones attract dairy-based functional beverage investment targeting West African distribution networks.
Egypt
Cairo's student population and Alexandria's young professional cohorts sustain volume demand for energy drinks through convenience store channels. The Egyptian Drug Authority oversees labeling requirements for functional claims on bioactive-enriched beverages. Cairo's 10th of Ramadan industrial city hosts contract manufacturing facilities serving North African markets with localized flavor adaptations.
Middle East and Africa Functional Beverages Market Competitive Landscape
Capital-heavy producers with integrated cold-chain infrastructure compete with asset-light brand licensors and regional contract manufacturers for shelf-space allocation across Middle East and Africa markets. The vendor base stratifies into three tiers: multinational nutrition conglomerates with Gulf distribution dominance, regional dairy processors leveraging captive supply networks, and specialized probiotic formulators targeting health food retail. Consolidation pressures intensify as sugar taxation and labeling harmonization elevate compliance costs beyond mid-cap balance sheet capacity. Dominant competitive moves include strategic partnerships with e-commerce platforms for direct-to-consumer subscription models and backward integration into aseptic processing technology to preserve thermolabile active cultures.
Within the multinational conglomerate tier, Nestlé and PepsiCo exemplify divergent strategic positioning—one anchored in dairy heritage and premium nutrition claims, the other in mass-market energy and sports drink velocity through convenience store saturation. Almarai occupies a distinctive regional archetype as a Saudi-based dairy processor integrating functional beverage lines with existing cold-chain infrastructure. Danone S.A. represents the European probiotic specialist model, competing through live-culture formulation credibility rather than distribution breadth.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| The Coca-Cola Company |
| Red Bull GmbH |
| Monster Beverage Corporation |
| Danone S.A. |
| Almarai |
| General Mills |
| Suntory Holdings Limited |
| Others |
Supply & Pricing Matrix
Thermolabile probiotic cultures from European suppliers feed through temperature-controlled logistics into Gulf retail tiers, with cold-chain integrity costs separating premium live-culture SKUs from ambient-stable commodity formulations across Saudi Arabia and the UAE.
Pricing Analysis
Subscription bundling versus single-unit transactional sales splits the market into recurring-revenue wellness regimens and impulse-driven convenience store purchases. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with live-culture probiotics commanding shelf-space premiums against malt-based energy drinks facing SFDA sugar-tax compression. Pricing pressure stems from stevia-monk fruit reformulation costs in Saudi energy drink manufacturing. Students in Cairo and Lagos mass markets exhibit highest price sensitivity; health enthusiasts in Dubai accept subscription premiums for personalized probiotic delivery.
Supply Chain Analysis
Saudi local-content requirements and UAE Ministry of Industry and Advanced Technology domestic-manufacturing incentives are redirecting sourcing toward regional aseptic processing facilities in Dammam and Jebel Ali. Active probiotic strains from France, Germany, and the United States anchor upstream supply, while packaging materials and alternative sweeteners draw from China and India. Single-source vulnerability concentrates in live-culture suppliers lacking regional replication. Distribution runs through supermarket chains and direct-to-consumer platforms, with cold-chain last-mile execution determining probiotic viability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with Gulf consumer demand shifting decisively toward gut-health-positioned premium formulations over commodity energy drinks.
For Market Incumbents: Deploy backward integration into aseptic processing technology to preserve thermolabile culture viability and defend margin pools against mid-cap regional entrants. Nestlé and Almarai should accelerate captive cold-chain infrastructure in Saudi Arabia's Eastern Province to preempt supply bottlenecks. Certification investment in UAE MOHAP clean label pathways creates regulatory moats against reformulation-heavy competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to Gulf health-enthusiast households, bypassing supermarket slotting-fee structures entirely. Nigeria's Lagos-Ibadan corridor presents first-mover white space for fortified dairy-based functional beverages with localized flavor profiles. Herbal-functional convergence using saffron and black seed botanicals enables premium positioning without multinational R&D scale. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance costs for multi-jurisdiction SFDA-MOHAP-NRCS certification exceed mid-cap balance sheet capacity. Regional dairy processors with integrated cold-chain infrastructure represent the most defensible acquisition profile over a five-to-ten-year horizon. Watch for Gulf harmonization initiatives on labeling standards as the signal for accelerated M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Investment | Modular nitrogen-flushing lines in Dammam preserve live-culture viability for probiotic expansion. |
| Direct-to-Consumer Launch | Subscription platforms in Dubai's Jumeirah district capture recurring revenue from wellness-committed households. |
| Herbal-Functional Convergence | Traditional botanicals like dates and black seed unlock MOHAP clean label certification for premium shelf placement. |
| Distribution Channel Expansion | E-commerce penetration in Saudi Arabia extends probiotic reach beyond supermarket cold-chain footprints. |
| Sustainability Repositioning | Reduced-additive formulations align with SFDA sugar taxation tiers and health-conscious Gulf consumer preferences. |
Research Methodology
Coverage spans the Gulf Cooperation Council corridor and sub-Saharan African markets, with primary inputs from each regional cluster. The research combines structured interviews with beverage category managers, cold-chain logistics directors, regulatory affairs specialists at Saudi and UAE authorities, and health food retail buyers with secondary validation. Sources include SFDA and MOHAP regulatory filings, customs import records for active cultures, Nielsen retail audit data for GCC supermarkets, and hospital procurement databases for clinical nutrition segments. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates.
Granularity-level modeling captures formulation architecture, distribution channel, and target consumer archetype as primary segmentation dimensions. Value projections across the analysis window derive from price-per-liter trajectories by formulation tier and volume growth assumptions by channel. CAGR calculations incorporate probiotic segment acceleration, energy drink reformulation cost pass-through, and e-commerce penetration curves. Industry-specific inputs include cold-chain infrastructure development timelines and regulatory harmonization probability assessments.
The model assumes a particular technology adoption path; alternative pathways for aseptic processing modularization would alter the outlook for mid-cap manufacturing economics. Forecasts reflect assumptions on SFDA sugar tax enforcement consistency and Gulf consumer willingness-to-pay for live-culture claims. Alternative scenarios involving accelerated labeling harmonization or cold-chain infrastructure gaps in Nigeria would revise volume projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Probiotic Drink Market