
 Vitamin Functional Water Market | 2026-2036
Vitamin Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin Functional Water Market Insights
Beverage co-packing capacity in Mexico is decoupling from U.S. brand ownership structures. Danone leverages its European mineral water infrastructure to anchor North American vitamin water production. PepsiCo sustains broad retail channel control through direct-store-delivery networks. The Coca-Cola Company differentiates via its glacéau vitaminwater portfolio and fountain equipment placement.
Vitamin functional water denotes fortified still or carbonated water containing added B-complex, C, D, or E vitamins alongside electrolytes, typically formulated at 10-100% daily value per serving through cold-fill aseptic processing. The product category serves hydration needs of consumers seeking nutritional supplementation without caloric sweeteners or artificial colorants. Vitamin-enhanced formulations occupy the dominant margin pool due to higher per-unit pricing and established consumer recognition. Electrolyte variants lead volume throughput in athletic channels. Probiotic-infused lines represent the fastest-growing technical segment as fermentation stabilization technologies mature.
The FDA governs nutrient content claims and fortification limits under 21 CFR 101, while the EPA regulates source water quality standards for bottled products. State-level container deposit laws in California, New York, and Oregon shape packaging format decisions and reverse logistics costs. Stakeholders must monitor evolving FDA guidance on structure-function claims and emerging state restrictions on single-use plastics to calibrate formulation and packaging strategies.
Market Dynamics
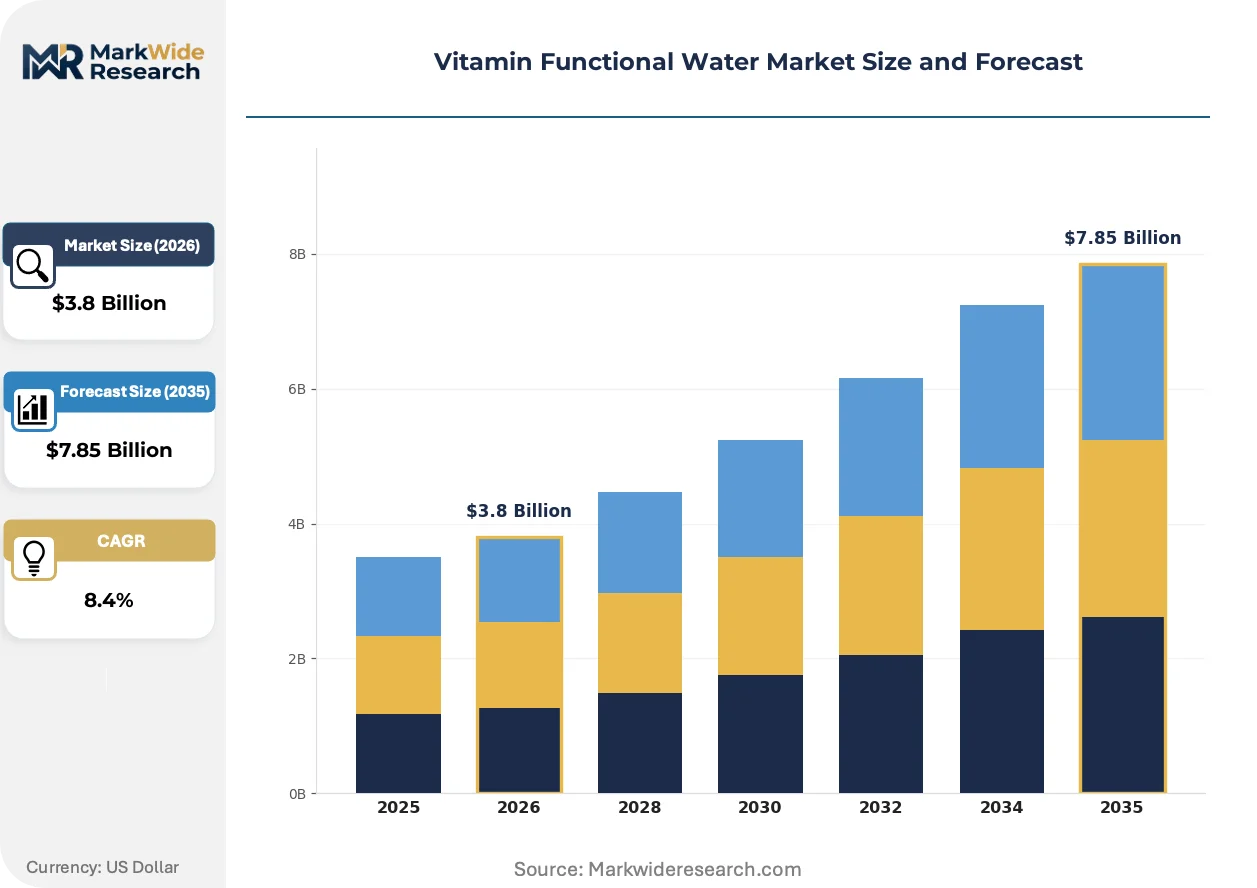
Cold-fill aseptic processing technology is compressing production economics for vitamin functional water, enabling smaller batch runs and faster flavor rotations while FDA fortification limits under 21 CFR 101 constrain formulation latitude.
Growth Catalysts
- Fitness channel expansion:Gym chains and boutique studios are embedding vitamin water into membership bundles, creating captive consumption occasions. Athletic facilities in metropolitan clusters drive repeat purchase velocity through placement at point-of-exertion.
- EPA source water standards:Stringent bottled water quality requirements elevate barriers for unqualified entrants, concentrating shelf space with compliant producers. This regulatory filtering protects margin pools for established fortifiers.
- Electrolyte stabilization chemistry:Advances in mineral bioavailability are extending shelf stability without preservative systems. Cold-fill lines now handle complex multi-ion matrices previously requiring hot-fill degradation of heat-sensitive vitamins.
Market Restraints
- Plastic input cost volatility:rPET and virgin resin prices swing with petroleum futures and recycling infrastructure bottlenecks. Bottle blow-molding operations face margin compression when polymer markets tighten.
- Co-packing concentration in Mexico:U.S. brand owners depend on cross-border production capacity exposed to tariff friction and logistics disruption. Geographic supply concentration creates vulnerability to trade policy shifts.
- Natural flavor extraction yields:Botanical and fruit-derived flavor systems suffer batch-to-batch variation. Formulation consistency demands costly quality control layers that erode unit economics at scale.
Strategic Opportunities
- Probiotic-fermentation convergence:Stabilization technologies for live cultures in aqueous matrices are maturing, opening white space between hydration and digestive health. This hybrid positioning commands premium shelf placement.
- Direct-to-subscription channels:Replenishment models bypass slotting fee structures of conventional retail. Digital-native brands are capturing lifetime value through personalized formulation curation.
- State container deposit expansion:California, New York, and Oregon laws are spreading to adjacent states, incentivizing reusable and aluminum format innovation. Early movers in circular packaging capture regulatory goodwill and consumer preference.
Industry Challenges
- Aseptic technician scarcity:Cold-fill line operation demands specialized microbiological training that outpaces vocational pipeline output. Facilities compete for limited talent pools in beverage manufacturing regions.
- Structure-function claim substantiation:FDA scrutiny of implied health benefits requires clinical documentation that stretches R&D timelines. Legal review cycles extend go-to-market schedules for novel vitamin combinations.
- Legacy fountain equipment retrofit:Foodservice dispensing infrastructure lacks compatibility with vitamin-fortified concentrates. Equipment replacement cycles delay adoption in away-from-home channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin Functional Water Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte, Herbal Infused, Probiotic, Vitamin-Enhanced Flavor Profile: Citrus, Berry, Tropical, Mixed Fruit Packaging Type: Bottles, Tetra Packs, Cans, Pouches Target Audience: Athletes, Health-Conscious Consumers, Millennials, Families |
| Companies Covered | Keurig Dr Pepper, Triamino Brands, Danone, Hint Water, Nestlé, The Coca-Cola Company, Vitamin Well, Talking Rain Beverage Company, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin Functional Water Market Trends and Innovations
Formulation science and packaging engineering are converging to redefine what functional water can deliver, with stability breakthroughs enabling ingredient combinations previously deemed incompatible in aqueous delivery systems.
Microencapsulation of lipid-soluble vitamins is electrifying bioavailability engineering in functional water. Sports nutrition buyers and clinical wellness segments are adopting these enhanced-delivery formats at accelerating rates. This technology is compressing the efficacy gap between beverage fortification and supplement dosing, reshaping competitive boundaries between categories.
REACH chemical registration requirements in Europe are tightening scrutiny on novel fortification compounds and packaging migrants. Industrial consequence includes reformulation costs for exporters and accelerated substitution of synthetic additives with natural alternatives. Vitamin D and omega-3 emulsion variants face the steepest compliance timelines, with manufacturers prioritizing EU market entry for premium-positioned lines.
Switching cycle compression is visible as health-conscious buyers rotate flavors and functional claims seasonally rather than maintaining brand loyalty. E-commerce subscription platforms and micro-fulfillment networks are displacing stock-up purchasing at conventional grocery. This pattern concentrates in United States metropolitan clusters where same-day delivery infrastructure supports impulse-driven experimentation.
Vitamin Functional Water Market Segmentation
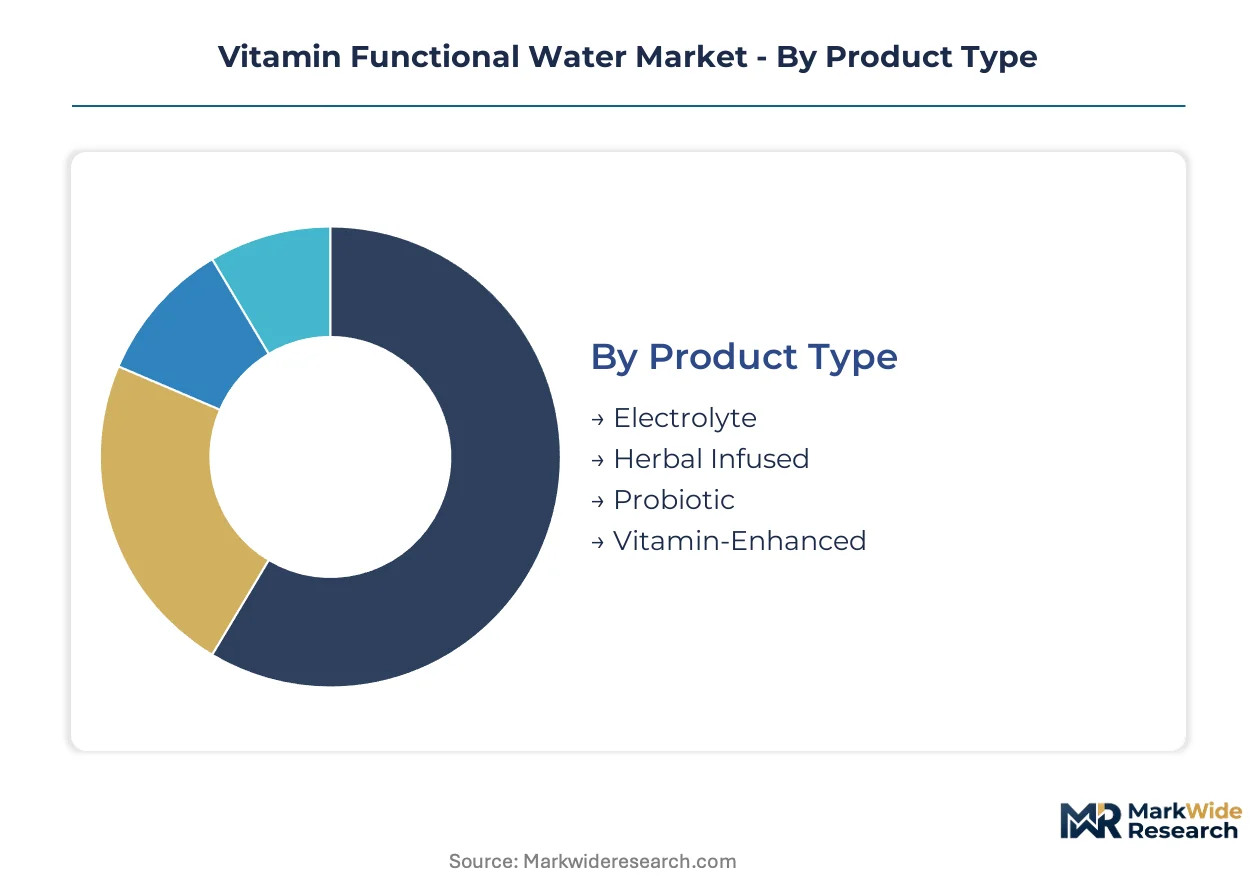
Segmentation in vitamin functional water reveals how formulation choices, packaging formats, and consumer targeting determine manufacturing complexity and channel economics. Supply concentration varies sharply across these dimensions, with some segments demanding specialized aseptic infrastructure while others tolerate conventional filling lines.
Product Type:
Production asset specificity concentrates around cold-fill aseptic capacity, with vitamin stability requirements filtering which formulations each facility can handle.
- Vitamin-Enhanced:Fortified still or carbonated water delivering B-complex, C, D, or E vitamins at 10-100% daily value per serving through cold-fill aseptic processing. Demand concentrates in United States metropolitan health-conscious clusters where established consumer recognition supports premium shelf placement and repeat purchase velocity.
- Electrolyte:Mineral-fortified formulations emphasizing sodium, potassium, and magnesium bioavailability for hydration recovery. Athletic facilities and gym chains in North America drive volume throughput through point-of-exertion placement, creating captive consumption occasions with high repeat velocity.
- Probiotic:Live culture aqueous matrices requiring fermentation stabilization technologies. Advances in cold-fill line compatibility are opening hybrid positioning between hydration and digestive health.
- Herbal Infused:Botanical-derived functional compounds in aqueous suspension. Batch-to-batch variation in natural extraction yields demands costly quality control layers.
Today's leader: Vitamin-Enhanced. Tomorrow's challenger: Probiotic.
Flavor Profile:
Flavor rotation speed and ingredient sourcing geography determine which profiles command dedicated production slots versus shared line time.
- Citrus:Lemon, lime, and orange-derived flavor systems with established supply chains and consistent extraction yields. Health-conscious consumers in fitness channels favor citrus for perceived refreshment and clean-label alignment.
- Berry:Strawberry, raspberry, and blueberry botanical formulations. United States metropolitan clusters show seasonal rotation patterns toward berry variants in warmer months.
- Tropical:Mango, pineapple, and passion fruit flavor matrices. Sourcing concentrates in equatorial supply regions with longer lead times.
- Mixed Fruit:Multi-botanical blends requiring complex formulation stability. E-commerce subscription platforms favor mixed fruit for personalization curation.
Volume concentrates in Citrus. Experimentation favors Mixed Fruit.
Packaging Type:
Container format decisions trace directly to state-level deposit law expansion and reverse logistics infrastructure availability.
- Bottles:rPET and virgin resin blow-molded containers dominating conventional retail. California, New York, and Oregon container deposit laws incentivize recycled content thresholds.
- Cans:Aluminum formats gaining share through circular packaging preferences and regulatory goodwill in deposit-law states. Gym chains favor cans for durability in athletic environments.
- Tetra Packs:Aseptic carton systems enabling ambient distribution with lower logistics costs. Shelf-stable positioning suits direct-to-subscription replenishment models.
- Pouches:Flexible format for single-serve and on-the-go consumption. Limited penetration due to recycling infrastructure gaps.
Current standard: Bottles. Regulatory momentum: Cans.
Target Audience:
Audience-specific demand patterns shape everything from formulation potency to channel placement and pricing architecture.
- Athletes:Electrolyte-focused buyers prioritizing mineral bioavailability and rapid hydration recovery. Boutique fitness studios embed these products into membership bundles.
- Health-Conscious Consumers:Vitamin-seeking buyers rotating flavors and functional claims seasonally. Same-day delivery infrastructure in United States metropolitan clusters supports impulse-driven experimentation.
- Millennials:Digital-native buyers captured through personalized formulation curation and subscription replenishment models bypassing conventional retail slotting fees.
- Families:Multi-serve purchasing oriented toward value positioning and clean-label assurance. Stock-up behavior persists in conventional grocery despite e-commerce displacement elsewhere.
Margin leader: Health-Conscious Consumers. Volume engine: Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in vitamin functional water trace cost-of-compliance arbitrage between jurisdictions with divergent fortification oversight and deposit-law stringency. Cold-fill aseptic capacity concentrates where EPA source water standards and FDA nutrient content claim guidelines create enforceable quality thresholds that smaller entrants cannot replicate.
United States
Fitness channel expansion and metropolitan health-conscious clusters drive adoption across California, New York, and Oregon. The FDA's 21 CFR 101 fortification limits and state-level container deposit laws shape formulation and packaging decisions. Los Angeles and New York City anchor point-of-exertion placement in boutique fitness studios and gym chains.
Germany
REACH chemical registration requirements tighten scrutiny on novel fortification compounds and packaging migrants. EFSA nutrient content claim standards filter which implied health benefits survive regulatory review. Bavaria and North Rhine-Westphalia concentrate mineral water infrastructure repurposed for vitamin water production.
Mexico
Beverage co-packing capacity serves U.S. brand ownership structures exposed to tariff friction and cross-border logistics disruption. COFEPRIS food safety oversight governs export-oriented production. Mexico City Metro and Nuevo León anchor blow-molding and aseptic filling operations for northbound supply chains.
Canada
Health Canada and PMRA standards for novel food ingredients create compliance thresholds for probiotic-infused lines. Provincial container deposit systems in British Columbia and Ontario incentivize aluminum format adoption. Toronto and Vancouver metropolitan clusters support direct-to-subscription replenishment models.
United Kingdom
Post-Brexit divergence from EU fortification standards creates labeling complexity for exporters. FSA structure-function claim guidance demands clinical documentation that stretches R&D timelines. London and Southeast England concentrate digital-native brand headquarters and e-commerce fulfillment infrastructure.
Vitamin Functional Water Market Competitive Landscape
United States producers anchor one tier through direct-store-delivery networks and fountain equipment placement; European specialists hold another through mineral water infrastructure repurposing and REACH-compliant formulation science. The vendor base splits between diversified beverage conglomerates with captive retail channels and focused functional water specialists with subscription-first distribution. Three archetypes dominate: scale-driven mass-market fortifiers, premium-positioned wellness brands, and co-packing-dependent digital natives. Competitive moves concentrate on portfolio diversification into probiotic-fermentation convergence and aluminum format innovation responding to state deposit law expansion.
Among diversified beverage conglomerates, The Coca-Cola Company and PepsiCo occupy positions defined by retail channel control and fountain infrastructure penetration. Danone represents the European infrastructure archetype, leveraging mineral water assets for North American production anchoring. Keurig Dr Pepper exemplifies the hybrid model combining traditional distribution with emerging format experimentation. These three entities illustrate how scale, geography, and asset specificity stratify competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Triamino Brands |
| Danone |
| Hint Water |
| Nestlé |
| The Coca-Cola Company |
| Vitamin Well |
| Talking Rain Beverage Company |
| PepsiCo |
| Others |
Pricing and Supply Chain Analysis
Metropolitan health-conscious clusters demanding aluminum format innovation force co-packers to retool blow-molding lines and absorb rPET resin volatility, compressing margin pools for brands locked into conventional bottle economics.
Pricing Analysis
Retailer slotting fees and direct-store-delivery premiums stratify pricing across premium, standard, and economy tiers. Vitamin potency certification under FDA 21 CFR 101 and cold-fill aseptic processing capability separate premium positioning from commodity hydration. Pricing pressure stems from plastic input cost volatility eroding unit economics at scale. Health-conscious consumers in fitness channels show lowest price sensitivity; family-oriented stock-up buyers in conventional grocery exhibit highest.
Supply Chain Analysis
Reverse logistics flows for California, New York, and Oregon container deposit schemes concentrate aluminum can refurbishment and rPET reclamation infrastructure near urban consumption hubs. Blow-molding and aseptic filling capacity clusters in Mexico, the United States, and Germany. Virgin resin and cold-fill line equipment feed production economics. Tariff exposure on cross-border Mexican capacity threatens supply continuity. Distribution runs through direct-store-delivery networks and gym chain captive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin functional water has entered late-cycle quality phase as probiotic-fermentation convergence and microencapsulation bioavailability shifts buyer preference toward clinically substantiated premium specifications.
For Market Incumbents: Acquire cold-fill aseptic production facilities in deposit-law states to anchor aluminum format capacity and capture regulatory goodwill. Consolidate co-packing relationships away from tariff-exposed Mexican concentration toward domestic certified infrastructure. Defend against digital-native subscription entrants by embedding fountain equipment placement in boutique fitness studios. For New Entrants and Emerging Players: The mid-tier price gap between PepsiCo-controlled mass retail and premium wellness specialists opens white space for personalized formulation curation. Target probiotic-infused lines in United States metropolitan clusters with same-day delivery infrastructure. Capture lifetime value through direct-to-subscription replenishment bypassing slotting fee structures. For Investors and Strategic Acquirers: Asymmetric upside sits with co-packing-dependent digital natives possessing captive subscriber bases and aluminum format readiness. Five-to-ten year viability hinges on fermentation stabilization technology maturation and state deposit law expansion momentum. Monitor FDA structure-function claim enforcement intensity as inflection indicator for R&D timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic-Fermentation Convergence | Stabilization technology maturation opens hybrid hydration-digestive health positioning commanding premium shelf placement. |
| Aluminum Format Transition | California, New York, and Oregon deposit law expansion incentivizes circular packaging capturing regulatory goodwill. |
| Direct-to-Subscription Launch | Digital-native replenishment models bypass conventional retail slotting fees and capture personalized formulation lifetime value. |
| Cold-Fill Aseptic Capacity Expansion | Specialized microbiological processing infrastructure enables complex multi-vitamin matrices previously requiring hot-fill degradation. |
| Fountain Equipment Placement | Foodservice dispensing infrastructure penetration in boutique fitness studios creates captive point-of-exertion consumption occasions. |
Research Methodology
Multiple input streams — primary interviews with beverage brand managers, co-packing operations directors, and gym chain procurement leads; secondary validation through FDA 21 CFR 101 filings, EPA source water quality databases, and Nielsen retail audit data — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories cross-referenced against panel input from cold-fill aseptic technicians and flavor formulation scientists anchored CAGR derivation across the analysis window. Segmentation modeling spanned product type, packaging format, flavor profile, and target audience dimensions. Forecast inputs incorporated electrolyte stabilization chemistry advances and state container deposit law diffusion patterns.
Caveats apply where FDA structure-function claim enforcement intensity, rPET resin price volatility, or cross-border tariff friction could materially shift the outlook. Practitioners should monitor probiotic live culture shelf stability breakthroughs and aluminum recycling infrastructure buildout for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
North America Functional Water Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market