
 Saudi Arabia Protein Bar Market | 2026-2036
Saudi Arabia Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Protein Bar Market Analytics
Subscription-based replenishment models is expanding how protein bars reach Saudi consumers, shifting one-time purchases into recurring revenue streams. PepsiCo leverages its beverage distribution network to secure shelf placement in major retail chains across the Kingdom. Almarai anchors its position through backward integration into dairy-derived protein sourcing, while Barebells Functional Foods competes via specialized formulations targeting gym-affiliated consumers in Riyadh and Jeddah.
A protein bar is a shelf-stable, extruded or cold-pressed confectionery product containing protein isolates or concentrates at concentrations typically ranging from ten to thirty grams per serving, designed to deliver portable macronutrient supplementation for athletic recovery or dietary management. Meal replacement bars command premium positioning among time-constrained professionals in Riyadh, while plant-based ingredient formulations capture growing interest from consumers seeking alternatives to whey and soy derivatives. Online distribution channels show the steepest trajectory as Saudi Arabia's e-commerce infrastructure matures, though supermarkets retain volume dominance through impulse placement near checkout zones.
SFDA mandates strict nutrition labeling and health claim verification for functional food products, while halal certification requirements governed by Saudi authorities govern ingredient sourcing and manufacturing process approval. These dual compliance layers elevate barriers for imported brands and favor domestic production partnerships. Stakeholders must monitor evolving diabetics-focused formulations and regulatory clarity on protein content claims as the consumer base diversifies beyond traditional fitness segments.
Market Dynamics
SFDA nutrition labeling mandates and halal certification requirements are compressing formulation timelines while elevating compliance costs, forcing manufacturers to restructure supply chains around domestic production partnerships rather than direct import models.
Growth Catalysts
- Fitness segment expansion:Gym culture penetration in Riyadh and Jeddah is generating concentrated demand for portable protein supplementation among urban professionals seeking convenient recovery solutions.
- SFDA regulatory clarity:Streamlined health claim verification processes for functional foods is accelerating product registration timelines and reducing market entry friction for compliant formulations.
- E-commerce infrastructure maturation:Digital payment adoption and last-mile logistics improvements across Saudi Arabia is enabling direct-to-consumer replenishment models previously constrained by cash-on-delivery limitations.
Market Restraints
- Whey protein import dependency:Concentrated global supply of dairy-derived protein isolates exposes manufacturers to input cost volatility and currency fluctuation risks.
- Halal certification complexity:Multi-layered approval processes governing ingredient sourcing and manufacturing creates extended validation timelines that disadvantage smaller market entrants.
- Plant-based formulation limitations:Taste and texture constraints in pea and rice protein combinations restrict adoption among consumers accustomed to conventional dairy-based products.
Strategic Opportunities
- Diabetics-focused formulations:Low-glycemic index and sugar-alternative recipes targeting metabolic health management represent underserved demand within Saudi Arabia's expanding wellness consumer base.
- Subscription channel development:Automated replenishment platforms leveraging Saudi Arabia's young, mobile-first demographic can capture recurring revenue streams beyond traditional retail impulse purchases.
- PLI scheme alignment:Domestic manufacturing incentives under Saudi industrial policy frameworks support backward integration into localized protein processing capabilities.
Industry Challenges
- Food technologist scarcity:Specialized expertise in extrusion and cold-press bar formulation remains concentrated among multinational R&D teams, constraining indigenous product development capacity.
- Legacy ERP integration:Batch traceability and allergen management systems required for SFDA compliance often conflict with existing manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Protein Bar Market |
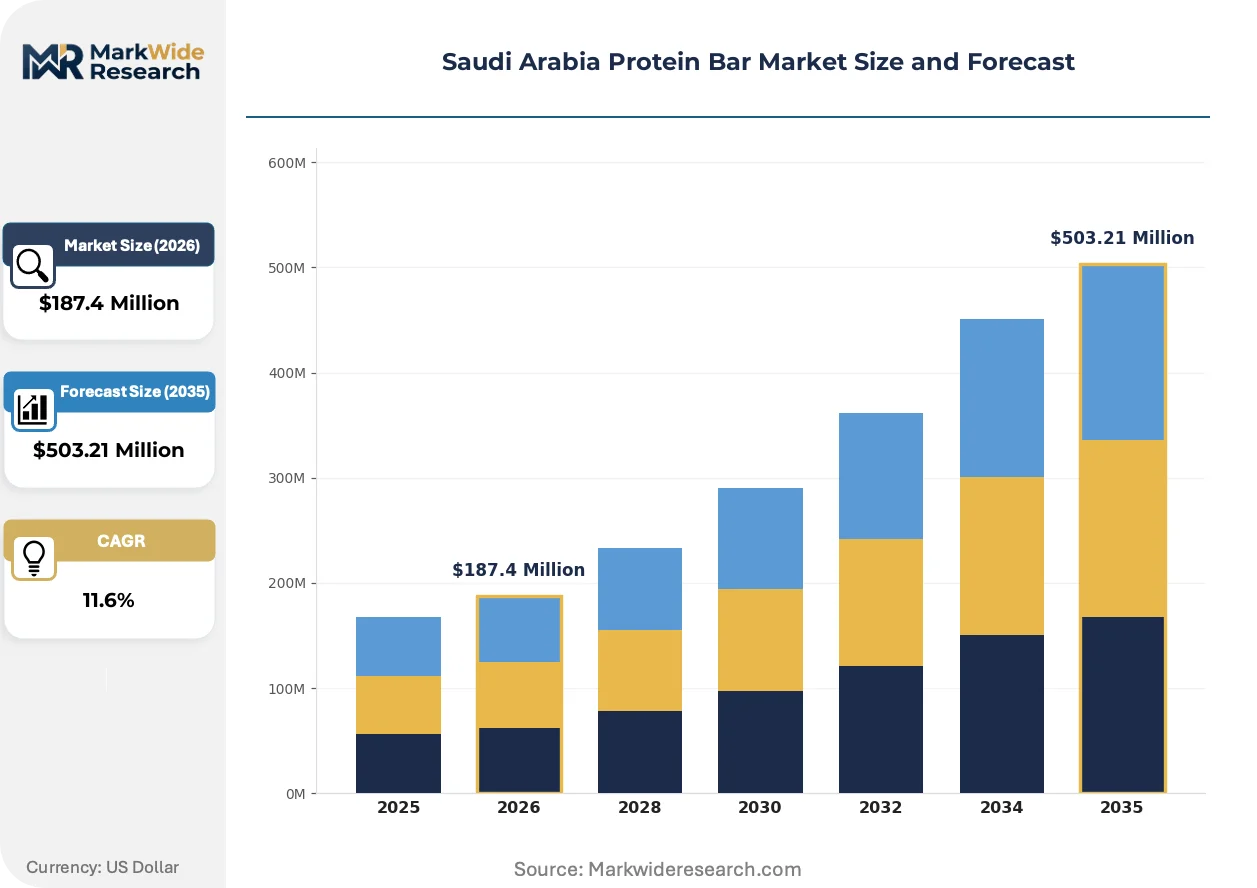
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Energy, Low Carb, Organic Ingredient Type: Whey Protein, Soy Protein, Plant-Based, Casein Distribution Channel: Supermarkets, Health Stores, Online, Gyms End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Diabetics |
| Companies Covered | The Hershey Company, Almarai, PepsiCo, KBF Enterprises, Glanbia Performance Nutrition, The Simply Good Foods Company, Barebells Functional Foods, Kind LLC, General Mills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Protein Bar Market Evolving Landscape
Cold-press manufacturing is displacing conventional extrusion methods as brands compete on texture differentiation and clean-label positioning, while regulatory pressure on added sugars accelerates reformulation cycles across the category.
Precision fermentation-derived proteins is converging with traditional bar manufacturing infrastructure, enabling novel amino acid profiles without conventional dairy supply chains. Boutique fitness operators in Jeddah are piloting these formulations for member-exclusive product lines. This convergence is compressing the innovation cycle between laboratory-scale development and commercial shelf placement.
SFDA health claim substantiation requirements are tightening evidentiary standards for muscle recovery and satiety messaging, forcing brands to invest in localized clinical validation studies. Manufacturers are responding by narrowing advertised benefits to those supported by existing regional research. Meal replacement positioning faces particular scrutiny as regulators distinguish between sports nutrition and medical food categories.
Health-conscious coastal consumers in Jeddah are rotating toward plant-derived alternatives faster than inland markets, creating geographic segmentation in flavor development priorities. Retailers are responding with region-specific SKU allocation rather than national assortment uniformity. This demand rotation is pressuring national distributors to abandon one-size-fits-all merchandising strategies.
Saudi Arabia Protein Bar Market Segmentation
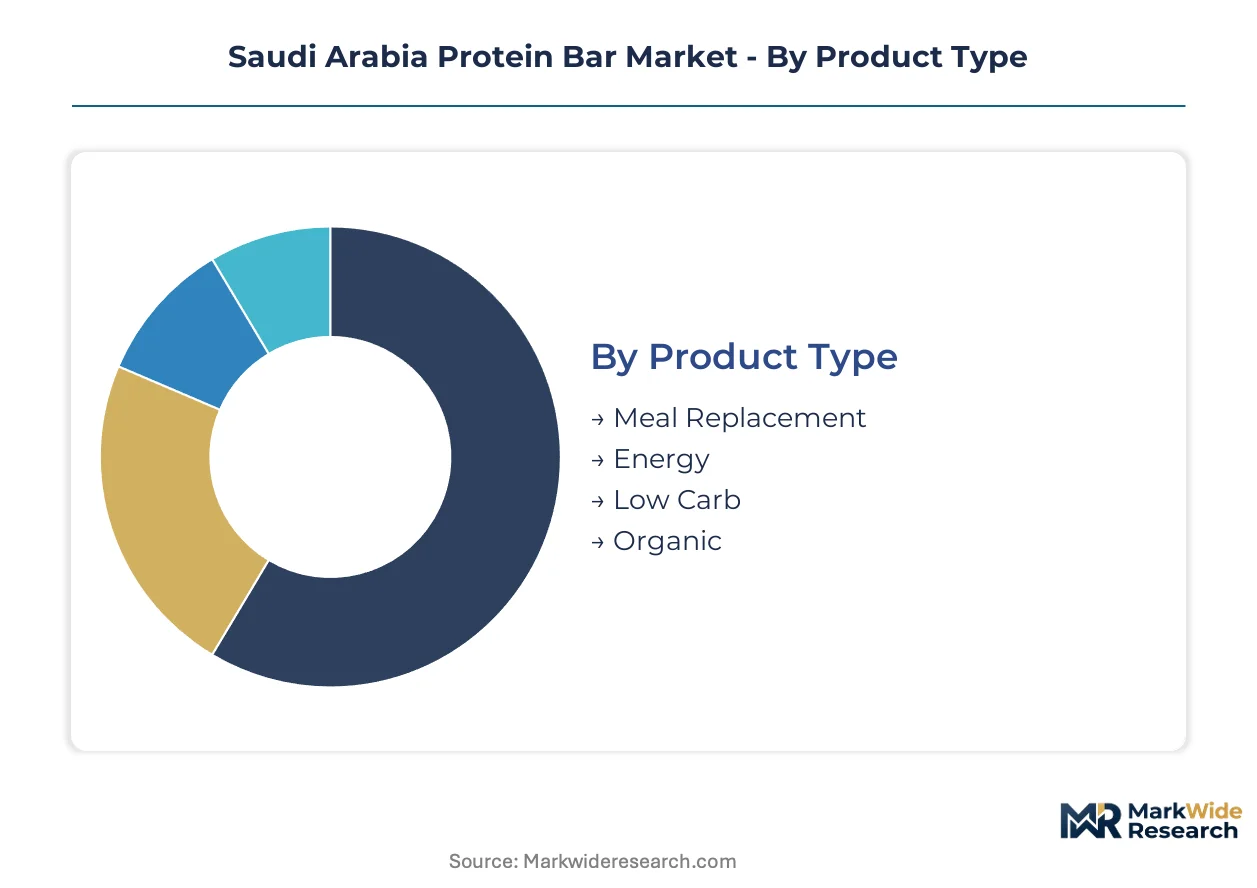
SFDA nutrition labeling mandates and halal certification requirements create uneven compliance burdens across segment categories, with dairy-derived formulations facing stricter scrutiny than plant-based alternatives. Manufacturers must align product development with certification timelines that vary by ingredient sourcing and end-use positioning.
Product Type:
Meal Replacement bars carry the heaviest SFDA health claim verification load, while Energy bars navigate simpler registration pathways focused on macronutrient disclosure rather than physiological benefit assertions.
- Meal Replacement:These bars integrate balanced macronutrient profiles with vitamin and mineral fortification at concentrations intended to substitute complete meals. Demand concentrates among time-constrained professionals in Riyadh's financial district, where convenience premiums override price sensitivity. SFDA scrutiny on meal replacement positioning intensified as regulators distinguish sports nutrition from medical food categories.
- Energy:Formulations prioritize rapid carbohydrate absorption alongside moderate protein content for immediate fuel delivery. Coastal consumers in Jeddah favor these for pre-workout consumption, driving flavor innovation toward date-derived sweeteners that align with local palate preferences.
- Low Carb:Ketogenic-compliant bars restrict net carbohydrates below ten grams per serving through sugar alcohol and fiber manipulation.
- Organic:Certification requires documented supply chain integrity from agricultural inputs through finished goods.
Meal Replacement sits at the top of the volume ranking, with Energy climbing the fastest.
Ingredient Type:
Cost tiers separate dairy-derived isolates from emerging plant proteins, with whey commanding premium positioning and pea-rice blends penetrating value-conscious segments.
- Whey Protein:Dairy-derived isolates deliver complete amino acid profiles with superior bioavailability metrics. Import dependency exposes manufacturers to currency fluctuation risks, compressing margins for brands without backward integration into captive dairy processing.
- Plant-Based:Pea, rice, and fava bean combinations address lactose intolerance and ethical consumption preferences. Jeddah's health-conscious coastal consumer base rotates toward these alternatives faster than inland markets, creating geographic segmentation in flavor development priorities.
- Soy Protein:Cost-effective isolates face consumer skepticism around phytoestrogen content and genetic modification concerns.
- Casein:Slow-digesting dairy protein targets overnight recovery applications with extended amino acid release kinetics.
Whey Protein maintains volume leadership, though Plant-Based gains share fastest among younger demographics.
Distribution Channel:
Margin structures diverge sharply across channels, with direct-to-consumer platforms capturing subscription recurring revenue while supermarkets dominate impulse-driven trial purchases.
- Online:Digital platforms leverage automated replenishment algorithms and mobile payment integration to reduce friction in repeat purchases. Last-mile logistics improvements across Saudi Arabia enable same-day delivery in Riyadh and Jeddah metropolitan zones.
- Supermarkets:Impulse placement near checkout zones drives trial among casual health seekers rather than committed fitness practitioners.
- Health Stores:Staff-assisted consultation environments support premium positioning through education on protein bioavailability and certification authenticity.
- Gyms:Boutique fitness operators in Riyadh and Jeddah pilot member-exclusive product lines with specialized formulations.
Supermarkets anchor volume throughput, while Online expands most quickly as e-commerce infrastructure matures.
End User:
Application maturity separates established athletic recovery segments from emerging metabolic health management use cases with distinct formulation requirements.
- Fitness Enthusiasts:Gym culture penetration in Riyadh and Jeddah generates concentrated demand for portable protein supplementation. This segment drives innovation in texture differentiation and clean-label positioning as consumers scrutinize ingredient lists.
- Diabetics:Low-glycemic index formulations with sugar alternatives target metabolic health management. Regulatory clarity on protein content claims for diabetic populations remains under development at SFDA.
- Athletes:Competitive performers prioritize batch-tested products with banned substance verification through third-party certification.
- Health-Conscious Consumers:Casual wellness seekers respond to marketing emphasizing natural ingredients and absence of artificial additives.
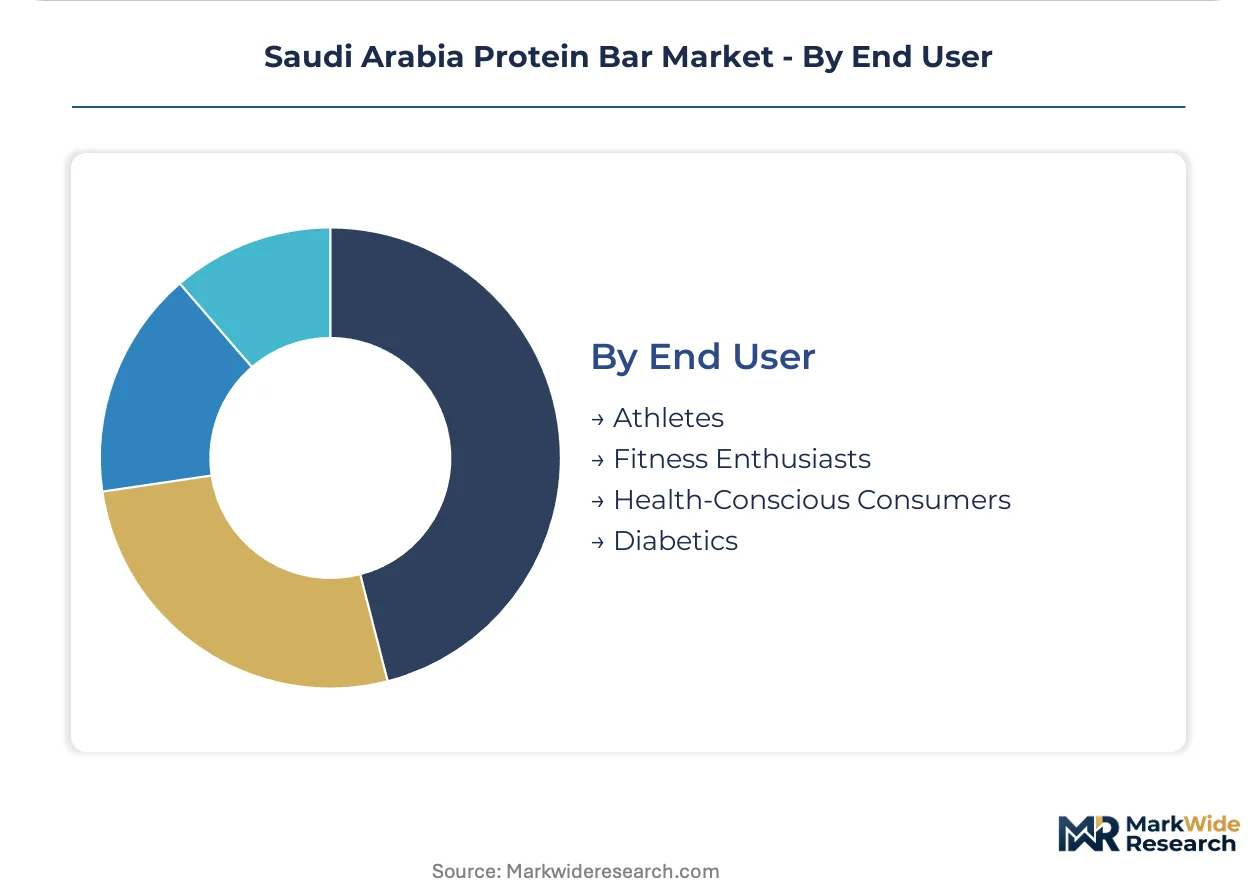
Fitness Enthusiasts occupy the largest addressable base, with Diabetics representing the steepest expansion trajectory as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production partnerships are displacing direct import models as SFDA compliance costs and halal certification timelines create arbitrage advantages for localized manufacturing. Manufacturers restructure supply chains around captive facilities rather than cross-border shipment.
Riyadh
Premium retail corridors in Riyadh's financial district concentrate demand for meal replacement bars among time-constrained professionals. SFDA streamlined health claim verification processes accelerate product registration timelines for compliant formulations. Boutique fitness operators in Riyadh's diplomatic quarter pilot member-exclusive product lines with specialized formulations.
Jeddah
Health-conscious coastal consumers in Jeddah rotate toward plant-derived alternatives faster than inland markets. Halal certification complexity creates extended validation timelines that disadvantage smaller market entrants. Retailers respond with region-specific SKU allocation rather than national assortment uniformity.
Eastern Province
Industrial zones in Dammam and Al-Khobar host backward integration projects into dairy-derived protein sourcing. PLI scheme alignment under Saudi industrial policy frameworks supports localized protein processing capabilities. Food technologist scarcity constrains indigenous product development capacity despite infrastructure investment.
NEOM Northwest
Precision fermentation-derived proteins converge with traditional bar manufacturing infrastructure in experimental zones. Regulatory clarity on protein content claims for novel ingredients remains under development at SFDA. Cold-press manufacturing displaces conventional extrusion methods as brands compete on texture differentiation.
Saudi Arabia Protein Bar Market Competitive Landscape
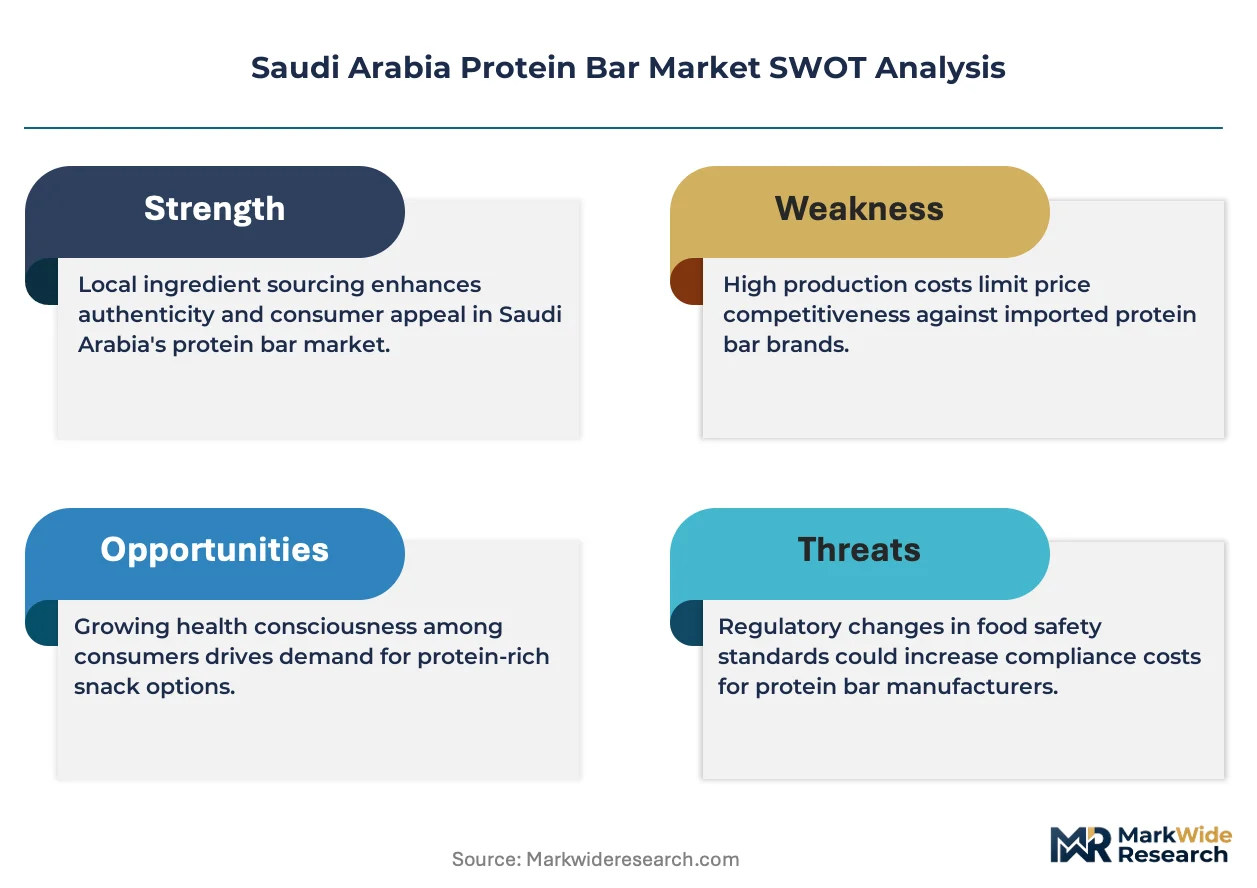
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG conglomerates leveraging beverage distribution networks against domestic dairy-integrated players. The vendor base organizes around three archetypes: global snack conglomerates with shelf placement advantages, regional dairy processors with captive protein supply, and specialized functional food formulators targeting gym-affiliated consumers. Consolidation pressure intensifies as compliance costs favor scaled operations with dedicated regulatory affairs teams. Dominant competitive moves include strategic partnerships for halal certification acceleration and portfolio diversification into diabetics-focused formulations.
Among global snack conglomerates, PepsiCo and The Hershey Company exemplify scale-driven market presence through existing retail relationships. Almarai anchors the regional dairy-integrated tier with backward integration into protein sourcing. Barebells Functional Foods occupies the specialized formulator position targeting fitness enthusiasts in Riyadh and Jeddah.
| Leading Market Players |
|---|
| The Hershey Company |
| Almarai |
| PepsiCo |
| KBF Enterprises |
| Glanbia Performance Nutrition |
| The Simply Good Foods Company |
| Barebells Functional Foods |
| Kind LLC |
| General Mills |
| Others |
Value Network & Pricing Analysis
Fitness enthusiasts in Riyadh and Jeddah anchor demand concentration, enabling subscription-based replenishment models to command premium pricing over supermarket impulse purchases. This buyer archetype segmentation forces manufacturers to stratify pricing across direct-to-consumer, retail, and gym-exclusive channels.
Pricing Analysis
Capacity additions in domestic dairy processing are reshaping price floors for whey-derived formulations. Three-tier pricing structure across premium, standard, and economy levels separates meal replacement bars with full SFDA health claim verification from energy bars with simpler macronutrient disclosure. Cost compression in plant-based tiers is intensifying as pea-rice blend suppliers multiply. Health-conscious coastal consumers in Jeddah show lowest price sensitivity, while casual supermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with concentrated whey protein isolate imports from the United States and Europe. Domestic manufacturing draws from date-derived sweeteners, locally processed dairy proteins, and imported pea protein concentrates. Tariff exposure on dairy-derived inputs creates margin volatility for brands without backward integration into captive supply. Distribution runs through PepsiCo's beverage network, Almarai's dairy logistics, and boutique fitness channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's protein bar market compounds steadily as gym culture penetration deepens the addressable base beyond traditional athletic segments. Regulatory clarity from SFDA on health claim verification accelerates product registration timelines for compliant entrants.
For Market Incumbents: Deepen backward integration into dairy-derived protein sourcing to insulate margins from currency fluctuation on whey imports. Accelerate halal certification timelines through dedicated regulatory affairs teams to outpace smaller entrants disadvantaged by multi-layered approval processes. Defend shelf placement through exclusive partnerships with boutique fitness operators in Riyadh's diplomatic quarter.
For New Entrants and Emerging Players: SFDA streamlined health claim verification processes in Saudi Arabia open a window for diabetics-focused formulations targeting metabolic health management. White-space concentrates in low-glycemic index recipes with sugar alternatives, where regulatory clarity remains under development. Penetrate through subscription channel development leveraging automated replenishment algorithms and mobile payment integration.
For Investors and Strategic Acquirers: Regional dairy processors with captive protein supply are the most active acquirer in this space, seeking portfolio diversification into functional food categories. Target acquisition archetypes include specialized formulators with gym-affiliated distribution and precision fermentation capabilities in NEOM experimental zones. Watch for inflection when SFDA issues definitive guidance on protein content claims for novel ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | Dedicated regulatory teams compress SFDA approval timelines versus smaller competitors. |
| Backward Integration into Dairy Processing | Almarai's captive protein sourcing insulates margins from import cost volatility. |
| Subscription Channel Development | Automated replenishment captures recurring revenue from Riyadh's mobile-first demographic. |
| Precision Fermentation Partnership | NEOM experimental zones enable novel amino acid profiles without conventional dairy chains. |
| Diabetics-Focused Formulation Launch | Low-glycemic index recipes address underserved metabolic health demand ahead of regulatory clarity. |
Research Methodology
Bottom-up fitness enthusiast and diabetic end-user modeling reconciled against top-down whey and plant protein supply tracking forms the analytical core. Primary interviews with product development executives at functional food manufacturers, regulatory affairs specialists navigating SFDA certification, category buyers at Saudi supermarket chains, and supply planners at dairy-integrated processors combined with secondary validation from SFDA registration databases, Saudi Customs import records, and gym operator procurement disclosures. Triangulation between demand-side consumption patterns and supply-side production capacity anchors volume estimates.
Input-output matrices map protein isolate sourcing through finished bar production to channel-specific offtake across supermarkets, online platforms, health stores, and gym exclusives. Segmentation dimensions include product type, ingredient source, distribution channel, and end-user application. CAGRs derive from fitted growth curves calibrated against historical gym membership expansion and e-commerce penetration rates. Forecast inputs incorporate SFDA regulatory timeline assumptions and halal certification pipeline visibility.
Revisions become necessary when SFDA issues unexpected health claim restrictions, whey protein import tariffs shift, or precision fermentation achieves commercial scale ahead of projected timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market