
 United States Milk Protein Market | 2026-2036
United States Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Milk Protein Market Analytics
A capital-intensity divergence between large-scale cheese cooperatives and specialized ingredient processors is reorganizing competitive dynamics in United States milk protein production. Dairy Farmers of America leverages its captive raw milk supply across multi-state processing networks to secure whey stream volumes. Glanbia sustains R&D intensity in protein hydrolysate technologies at its Idaho innovation center. Hilmar Cheese Company anchors its position through backward integration into California dairy farming operations.
United States milk protein comprises fractionated dairy solids—primarily whey proteins and caseinates—recovered through membrane filtration, ion exchange, or precipitation from cheese manufacturing streams, with protein content ranging from 34% in concentrates to 90%+ in isolates. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources across formulated food systems. Whey protein dominates value capture in sports nutrition applications where isolate grades command premium positioning over concentrates. Casein retains structural importance in functional foods requiring sustained amino acid release profiles. Milk protein concentrate competes on cost efficiency in bakery and dairy product reformulations.
FDA nutrition labeling standards, USDA organic certification requirements, and FSIS dairy plant inspection protocols collectively shape product specifications and market access for domestic suppliers. Protein quality scoring methodologies under FDA guidance directly influence ingredient selection by nutritional supplement companies seeking label-compliant formulations. Stakeholders must monitor evolving FDA positions on protein digestibility-corrected amino acid scoring and state-level dairy processor permitting to anticipate formulation and sourcing constraints.
Market Dynamics
Cheese cooperative consolidation across the Upper Midwest is capturing whey stream volumes that previously flowed to independent fractionators, reshaping raw material access for specialized milk protein processors.
Growth Catalysts
- Ready-to-drink sports nutrition:Beverage brands are incorporating whey protein isolates into shelf-stable formulations, expanding addressable occasions beyond powder mixes.
- FDA protein quality scoring:Updated nutrition labeling requirements for PDCAAS validation are pushing supplement manufacturers toward certified high-biological-value ingredients.
- California Central Valley clustering:Co-located whey fractionation capacity adjacent to cheese manufacturing reduces logistics costs for West Coast nutritional supplement producers.
Market Restraints
- Fluid milk price volatility:Federal Milk Marketing Order pricing fluctuations compress margin predictability for processors dependent on spot whey stream purchases.
- Cooperative supply concentration:Dairy Farmers of America and Land O'Lakes control substantial whey stream volumes, limiting independent processor raw material security.
- Plant protein substitution:Pea and rice protein blends are capturing share in cost-sensitive bakery and snack applications where complete amino acid profiles are not mandatory.
Strategic Opportunities
- Medical nutrition expansion:Enteral and clinical nutrition formulations represent underpenetrated demand for hydrolyzed whey and micellar casein with rapid gastric emptying properties.
- USDA organic certification:Premium positioning for organic milk protein isolate is widening price spreads as supply constraints persist in certified fluid milk sourcing.
- Membrane technology convergence:Ceramic microfiltration paired with chromatographic separation is enabling native whey protein recovery with superior gelling functionality.
Industry Challenges
- Fractionation engineering talent:Specialized expertise in membrane process optimization and protein denaturation control remains concentrated among retiring dairy technology veterans.
- Organic certification timelines:Three-year transition requirements for dairy herd certification delay market entry for suppliers targeting organic positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Milk Protein Market |
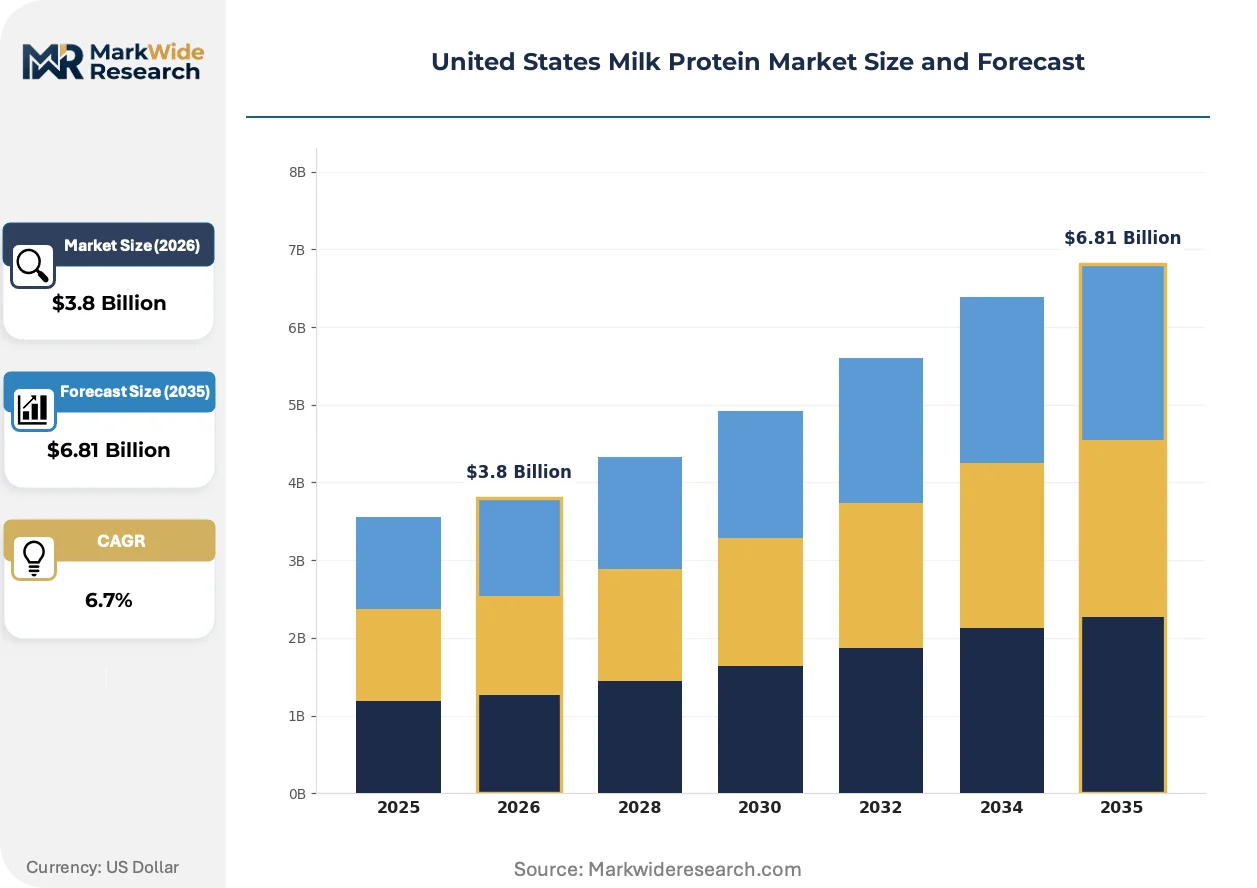
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Concentrate, Milk Protein Isolate Application: Sports Nutrition, Functional Foods, Dairy Products, Bakery Products End User: Food Manufacturers, Nutritional Supplement Companies, Retail Consumers, Healthcare Providers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Dairy Farmers of America, Glanbia, Fonterra Co-operative Group, Saputo, Arla Foods Ingredients Group, Hilmar Cheese Company, Leprino Foods Company, Kerry Group, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Milk Protein Market Evolving Landscape
Processing technology evolution and regulatory precision are compressing product differentiation cycles while opening new functional application spaces for fractionated dairy proteins.
Precision fermentation-derived dairy proteins are fragmenting traditional sourcing assumptions for whey and casein analogs. Ingredient procurement teams at CPG manufacturers are piloting microbially-produced proteins in ice cream and yogurt applications. This technology is fragmenting established supply relationships between cheese cooperatives and downstream fractionators by decoupling protein production from fluid milk dependency.
FDA guidance on protein digestibility-corrected amino acid scoring is tightening label claim substantiation requirements. Nutritional supplement manufacturers must now validate protein quality through controlled human studies rather than predictive modeling. Sports nutrition brands sourcing whey protein isolate are reformulating to maintain PDCAAS scores above 1.0 for competitive label positioning.
Direct-to-consumer subscription models are displacing traditional distribution through brick-and-mortar supplement retailers. Specialty protein brands are building recurring revenue through personalized nutrition platforms with flavor and formulation customization. California and Texas metropolitan markets show highest penetration of these digitally-native purchasing patterns among fitness-oriented demographics.
United States Milk Protein Market Segmentation
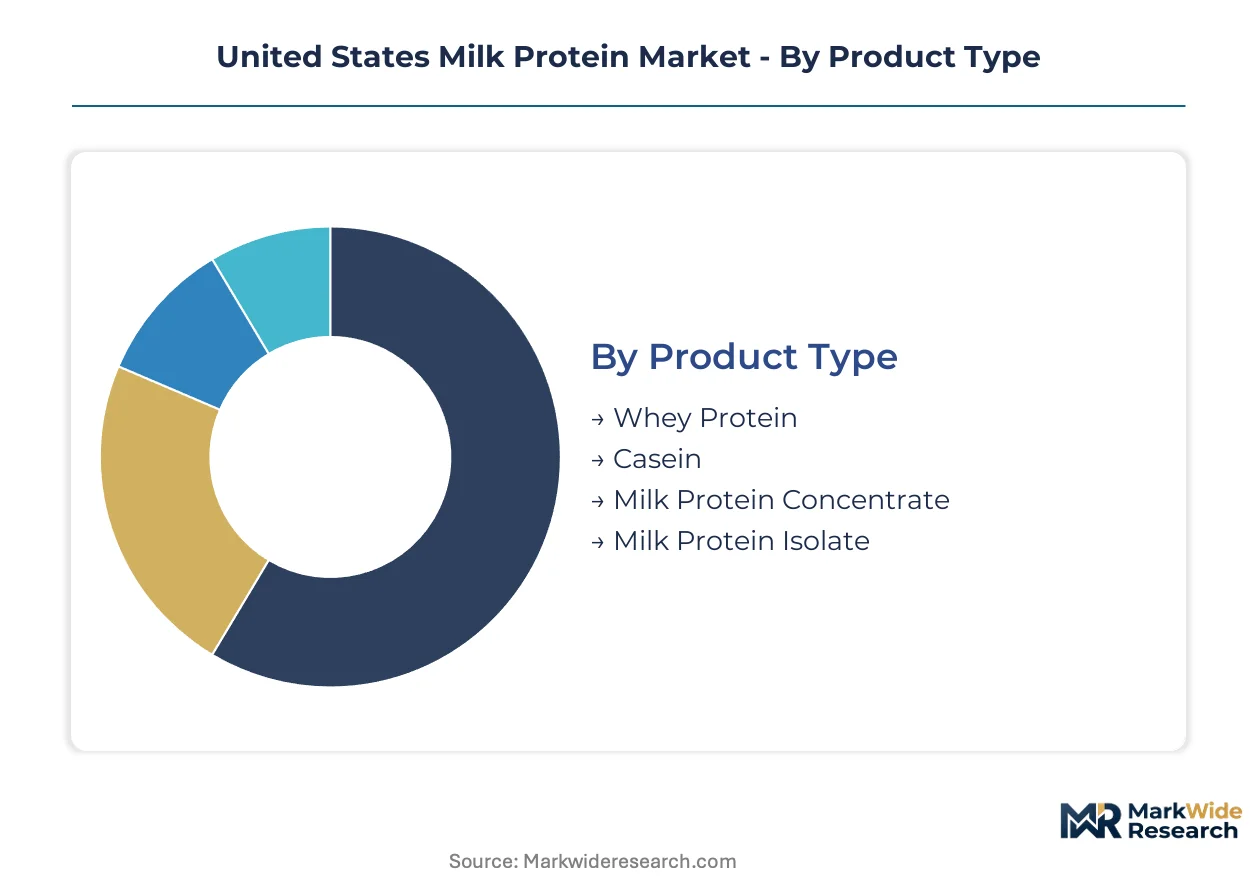
Milk protein segmentation reveals how substitute threats concentrate in cost-sensitive tiers while premium grades defend through functional differentiation. Understanding these fault lines guides portfolio positioning against plant protein incursion.
Product Type:
Whey protein faces the most acute substitution pressure from pea-rice blends in mass-market applications, while casein and isolate grades maintain stronger defensive moats through technical performance barriers.
- Whey Protein:Fractionated dairy solids with 34-90% protein content spanning concentrate to isolate grades, differentiated by filtration methodology and denaturation control. Demand concentrates in California's Central Valley processing corridor where co-located fractionation serves West Coast sports nutrition manufacturers facing FDA PDCAAS validation requirements. Sports nutrition brands expanding ready-to-drink formulations drive isolate grade premiumization against concentrate commoditization.
- Casein:Slow-digesting phosphoprotein retaining micellar structure for sustained amino acid release profiles in clinical and overnight recovery applications. Demand concentrates in medical nutrition formulations where gastric emptying properties outweigh cost considerations, with micellar casein commanding substantial premia over acid-precipitated variants in enteral feeding systems.
- Milk Protein Concentrate:Intermediate protein concentration (40-85%) serving cost-driven bakery and dairy reformulations where complete amino acid profiles remain secondary to emulsification and water-binding functionality.
- Milk Protein Isolate:Premium grade exceeding 90% protein with minimal lactose and fat, positioned in USDA organic certification tiers where three-year herd transition requirements constrain supply expansion.
Whey protein retains volume leadership; milk protein isolate holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity bulk applications from precision-formulated segments where protein quality scoring drives specification rigidity.
- Sports Nutrition:Powder mixes and ready-to-drink beverages commanding highest value per kilogram through isolate-grade incorporation and PDCAAS-validated label claims. Direct-to-consumer subscription models in California and Texas metropolitan markets displace traditional brick-and-mortar distribution.
- Functional Foods:Positioned nutrition products requiring sustained release or rapid gastric emptying properties, where casein and hydrolyzed whey fractions defend against plant protein substitution through performance differentiation.
- Dairy Products:Standardized ingredient streams for cheese and yogurt manufacturing where milk protein concentrate competes on cost efficiency in protein fortification and texture modification.
- Bakery Products:Most exposed to pea and rice protein blend substitution where emulsification requirements do not mandate complete amino acid profiles or high biological value scoring.
Dairy products retain volume leadership; sports nutrition holds the steepest expansion curve.
End User:
Customer type determines specification stringency, with nutritional supplement companies facing the most demanding protein quality validation protocols.
- Food Manufacturers:High-volume buyers prioritizing cost stability through cooperative supply agreements, concentrated in Midwest dairy processing networks.
- Nutritional Supplement Companies:Specification-intensive purchasers requiring PDCAAS-validated isolates for competitive label positioning, concentrated in West Coast and Texas markets with direct-to-consumer distribution infrastructure.
- Retail Consumers:Fragmented demand accessed through digital-native subscription platforms with flavor customization, showing highest penetration in fitness-oriented metropolitan demographics.
- Healthcare Providers:Clinical and enteral nutrition procurement teams sourcing hydrolyzed fractions for rapid gastric emptying applications, representing underpenetrated demand expansion opportunity.
Food manufacturers retain volume leadership; nutritional supplement companies hold the steepest expansion curve.
Distribution Channel:
Geography shapes channel effectiveness, with digital infrastructure penetration varying substantially across metropolitan and rural markets.
- Online Retail:Direct-to-consumer platforms enabling personalized nutrition subscriptions with formulation customization, concentrated in California and Texas urban corridors.
- Supermarkets:Mass-market access for commodity concentrate grades in conventional food applications, concentrated in Midwest dairy belt population centers.
- Health Stores:Specialty retail positioning for isolate and organic-certified grades serving fitness-oriented consumers with premium willingness-to-pay.
- Direct Sales:Bulk institutional procurement by food manufacturers and healthcare systems through negotiated supply agreements with cooperative processors.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across U.S. sub-regions. California and Texas buyers absorb premium isolate grades for sports nutrition, while Midwest food manufacturers prioritize cost-stable concentrate volumes for commodity applications.
California Central Valley
Hilmar Cheese Company anchors whey fractionation capacity adjacent to dairy farming operations, serving West Coast sports nutrition manufacturers. FDA PDCAAS validation requirements concentrate specification-intensive procurement in this corridor. Co-located processing reduces logistics costs for ready-to-drink formulation brands targeting metropolitan fitness demographics.
Texas Triangle
Direct-to-consumer subscription models show highest penetration in Houston-Dallas-Austin metropolitan markets. Nutritional supplement companies leverage Texas distribution infrastructure for personalized nutrition platforms with flavor customization. State-level dairy processor permitting under Texas Department of State Health Services shapes plant expansion timelines.
Upper Midwest Dairy Belt
Dairy Farmers of America and Land O'Lakes control substantial whey stream volumes across Wisconsin and Minnesota cheese cooperative networks. Federal Milk Marketing Order pricing fluctuations compress margin predictability for independent processors dependent on spot purchases. USDA organic certification requirements constrain supply expansion for premium positioning tiers.
Idaho Mountain West
Glanbia sustains R&D intensity in protein hydrolysate technologies at its Idaho innovation center. Captive raw milk supply across multi-state processing networks secures whey stream volumes for specialized ingredient production. State-level environmental permitting under Idaho Department of Environmental Quality influences membrane filtration capacity expansion.
Northeast Corridor
Medical nutrition demand concentrates in Boston-New York-Philadelphia healthcare procurement networks for enteral and clinical formulations. Hydrolyzed whey and micellar casein with rapid gastric emptying properties command substantial premia in this underpenetrated segment. FDA nutrition labeling standards directly influence hospital system ingredient selection protocols.
United States Milk Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the U.S. milk protein market. Large-scale cheese cooperatives leverage captive raw milk supply for volume security, while specialized ingredient processors compete through R&D intensity in fractionation technologies. Three archetypes dominate: cooperative-backed integrators with multi-state networks, innovation-focused hydrolysate specialists, and backward-integrated California processors. Competitive moves concentrate on membrane technology licensing and strategic partnerships with sports nutrition brands.
Within the cooperative-backed tier, Dairy Farmers of America exemplifies scale-driven supply security across Upper Midwest networks. Glanbia occupies a position representing R&D-intensive specialization in hydrolysate technologies. Hilmar Cheese Company anchors the backward-integrated archetype through California dairy farming operations. These three players collectively illustrate how divergent capital-intensity strategies reorganize competitive dynamics in domestic milk protein production.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Glanbia |
| Fonterra Co-operative Group |
| Saputo |
| Arla Foods Ingredients Group |
| Hilmar Cheese Company |
| Leprino Foods Company |
| Kerry Group |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
FDA PDCAAS certification gates both supplier qualification and price stratification simultaneously, with validated isolates commanding substantial premia over unverified concentrates while excluding non-compliant processors from specification-intensive procurement channels.
Pricing Analysis
After-sales formulation support and technical service contracts drive lifetime value capture beyond commodity protein sales. Three-tier pricing structure across organic-certified premium, PDCAAS-validated standard, and commodity concentrate economy levels reflects certification investment recovery. Pricing pressure stems from Federal Milk Marketing Order volatility compressing spot whey stream margins. Food manufacturers exhibit highest price sensitivity in bulk concentrate procurement, while nutritional supplement companies absorb isolate premia for label-compliant positioning.
Supply Chain Analysis
Inventory cycles and lead-time variability concentrate around cheese production scheduling rather than downstream demand signals. Supply concentrates in California, Wisconsin, and Idaho, with whey stream volumes tethered to regional cheese manufacturing capacity. Raw material dependencies center on fluid milk supply under cooperative control, membrane filtration equipment, and chromatographic separation resins. Single-source vulnerability runs through Dairy Farmers of America and Land O'Lakes whey stream concentration. Distribution runs through direct bulk sales to food manufacturers, supplemented by distributor networks serving supplement companies and healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are fragmenting traditional milk protein economics, with microbially-produced whey analogs threatening to decouple protein supply from fluid milk dependency and reshape interoperability between ingredient suppliers and CPG manufacturers.
For Market Incumbents: Consolidate whey stream access through captive supply agreements with Upper Midwest cheese cooperatives before cooperative concentration locks out independent fractionators. Deepen backward integration into California dairy farming to secure organic certification pipelines against three-year herd transition bottlenecks. Invest in ceramic microfiltration capacity to defend technical differentiation against precision fermentation substitutes. For New Entrants and Emerging Players: Medical nutrition service gaps in enteral and clinical formulation support represent underexploited white space where incumbent ingredient processors under-invest in application technical service. Target Northeast Corridor healthcare procurement networks with hydrolyzed whey and micellar casein specialized for rapid gastric emptying protocols. Pursue USDA organic certification early to capture widening price spreads before supply constraints ease. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across membrane technology and chromatographic separation infrastructure, favoring scaled players with existing fractionation assets over greenfield entrants. Acquisition target archetype: specialized hydrolysate processors with FDA-validated PDCAAS dossiers and established sports nutrition brand relationships. Signal to watch: precision fermentation scale-up announcements indicating timeline compression for dairy protein analog commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Farming | Secures captive raw milk supply for whey stream volumes under Federal Milk Marketing Order pricing. |
| Ceramic Microfiltration Capacity Expansion | Enables native whey protein recovery with superior gelling functionality against precision fermentation substitutes. |
| USDA Organic Certification Investment | Captures premium positioning in supply-constrained organic milk protein isolate tiers. |
| Medical Nutrition Partnership Development | Builds enteral and clinical formulation expertise in underpenetrated healthcare procurement networks. |
| Direct-to-Consumer Platform Launch | Displaces brick-and-mortar supplement retail through personalized nutrition subscriptions in California and Texas metros. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in this analysis. Primary research encompassed dairy processing executives, sports nutrition brand formulation directors, membrane technology engineers, healthcare procurement managers, and cooperative supply chain officers. Secondary validation drew from FDA guidance documents, USDA organic certification records, Federal Milk Marketing Order pricing data, and SEC filings of publicly traded dairy processors. Bottom-up volume modeling triangulated against top-down market sizing across protein grade tiers.
Sensitivity analysis across fluid milk price volatility scenarios and precision fermentation adoption curves stress-tested projection robustness. Segmentation dimensions modeled include protein type, application category, end-user archetype, and distribution channel, with additional granularity on PDCAAS validation status and organic certification tier. CAGRs were derived from trend extrapolation of historical volume and value trajectories, incorporating inputs from cheese production forecasts and sports nutrition consumption patterns.
Underlying assumptions cover cooperative supply concentration persistence, FDA protein quality scoring stability, and precision fermentation timeline uncertainty, with deviation risk concentrated in Federal Milk Marketing Order reform and microbial protein regulatory approval pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactic Butter Market
Dairy Products
North America Sour Cream Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Lactose and Derivative Market
Dairy Products
North America Flavored Milk Market
Dairy Products
GCC Casein Market
Dairy Products
Germany Milk Protein Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Germany Dairy Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
United States Yogurt Market