
 Grape Skin–Carob Synergy Antioxidant Systems Market | 2026-2036
Grape Skin–Carob Synergy Antioxidant Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Grape Skin–Carob Synergy Antioxidant Systems Market Insights
Functional beverage formulations is shifting toward polyphenol-rich stabilizers as clean-label priorities reshape antioxidant sourcing. Givaudan leverages its flavor-integrated ingredient platform to embed grape skin–carob complexes into premium beverage lines. Nexira anchors Mediterranean supply chains through controlled carob gum and extract procurement from southern France. ADM competes via backward integration into North American grape processing operations.
Grape Skin–Carob Synergy Antioxidant Systems combine procyanidin-rich Vitis vinifera dermal extracts with galactomannan-polyphenol matrices from Ceratonia siliqua pods, typically standardized to 40-60% total polyphenol content via spray drying or cold-pressing protocols. These systems function primarily as lipid oxidation inhibitors in shelf-stable emulsions and as bioactive carriers in controlled-release nutraceutical matrices. Powder formats dominate current volume owing to stability advantages in bulk ingredient handling, while nanoemulsion technologies represent the fastest-expanding formulation segment as absorption bioavailability claims intensify. Dietary supplements command the largest application share, though functional foods exhibit steeper growth trajectories as European retailers enforce stricter clean-shelf policies.
EMA botanical drug guidelines, EFSA novel food regulations, and REACH Annex XVII restrictions collectively elevate analytical documentation burdens for suppliers entering European markets. FDA GRAS self-affirmation pathways create parallel compliance tracks for US-bound nutraceutical manufacturers, though FSMA foreign supplier verification demands intensify audit requirements. Stakeholders must monitor evolving EFSA health claim substantiation thresholds for polyphenol-specific cardiovascular and cognitive function assertions.
Market Dynamics
REACH Annex XVII restrictions on botanical extract purity are compressing supplier margins while accelerating consolidation among European carob processors capable of certifying contaminant-free galactomannan matrices.
Growth Catalysts
- Clean-label mandates:European retailers enforce stricter shelf-stability policies without synthetic preservatives, forcing reformulation toward polyphenol-rich natural stabilizers in functional beverages.
- EFSA novel food pathways:Streamlined approval processes for Ceratonia siliqua-derived ingredients accelerate time-to-market for standardized extract suppliers meeting 40-60% polyphenol benchmarks.
- Mediterranean processing clusters:Concentrated carob gum extraction capacity in southern France and Sicily creates supply security for nutraceutical capsule manufacturers scaling procurement.
Market Restraints
- Input cost volatility:Grape skin availability fluctuates with Vitis vinifera harvest cycles and wine industry diversion priorities, squeezing raw material procurement budgets.
- Supply concentration risk:Over 70% of pharmaceutical-grade carob gum originates from southern French cooperatives, creating single-geography exposure for buyers.
- Regulatory friction:Divergent FDA GRAS self-affirmation and EMA botanical drug documentation requirements force dual-track compliance investments for cross-Atlantic suppliers.
Strategic Opportunities
- Nanoemulsion white space:Bioavailability-optimized delivery formats remain underdeveloped compared to powder dominance, offering first-mover advantages for absorption-claim substantiation.
- Controlled-release matrices:Convergence of spray-drying protocols with lipid encapsulation technologies enables extended-release nutraceutical applications in cognitive health segments.
- US functional food penetration:FSMA foreign supplier verification creates barriers for European competitors, rewarding early compliance investments by domestic grape processors.
Industry Challenges
- Analytical capability gaps:Procyanidin quantification and galactomannan molecular weight profiling require specialized HPLC-MS infrastructure scarce among mid-tier contract manufacturers.
- Certification timeline compression:EFSA health claim substantiation for cardiovascular endpoints demands 12-18 month clinical documentation cycles incompatible with rapid product refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grape Skin–Carob Synergy Antioxidant Systems Market |
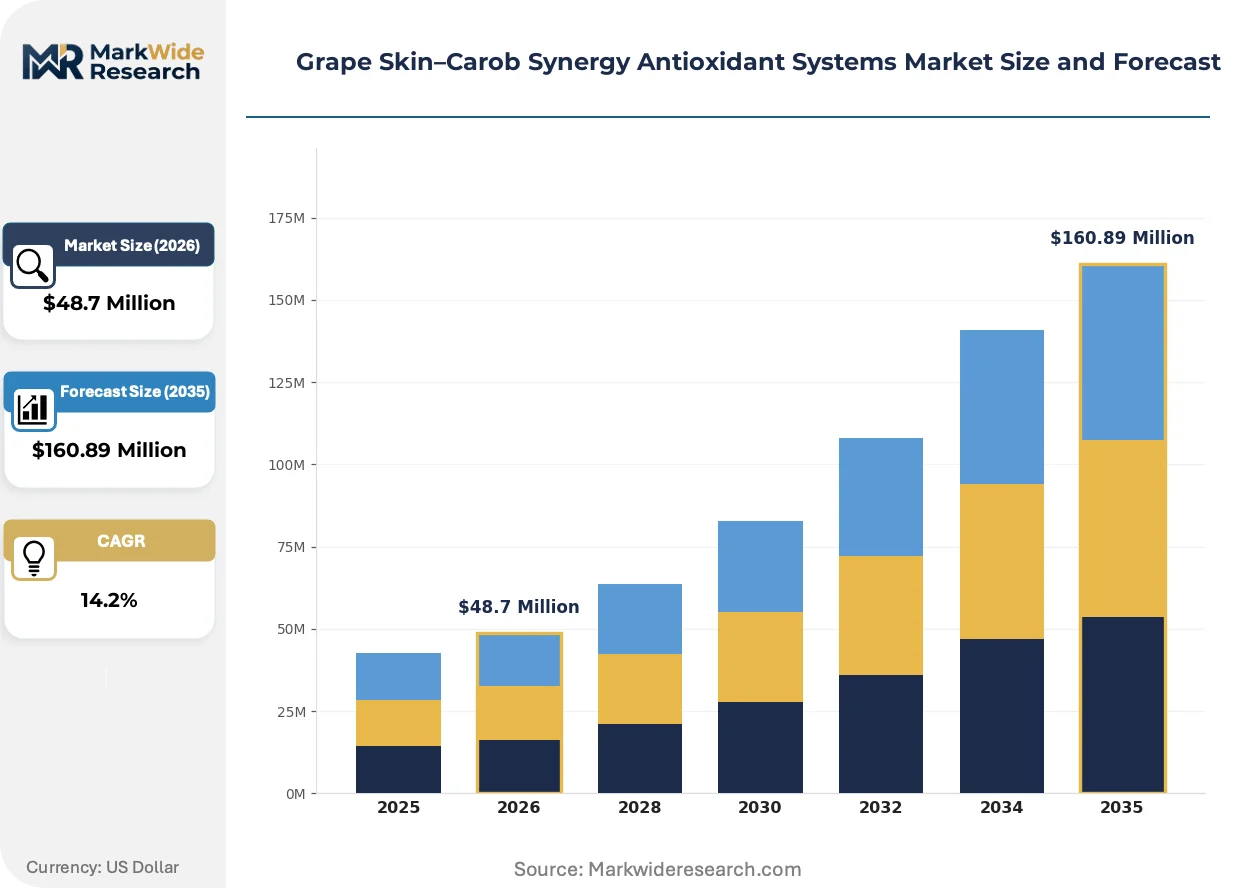
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $160.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powder, Emulsions, Capsules, Liquids Application: Dietary Supplements, Functional Foods, Cosmetics, Animal Nutrition, Food Preservation Formulation Technology: Microencapsulation, Nanoemulsions, Spray Drying, Cold Pressing, Fermentation End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Beverage Producers, Personal Care Brands, Animal Feed Companies |
| Companies Covered | Givaudan, Nexira, Indena, ADM, Symrise, Kalsec, Döhler, Polyphenolics, Botanic Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grape Skin–Carob Synergy Antioxidant Systems Market Trends and Innovations
Formulation science is pivoting from bulk powder standardization toward precision delivery systems that maximize polyphenol bioavailability while satisfying clean-label audit requirements.
Nanoemulsion technologies are converging with lipid oxidation inhibition applications, enabling water-dispersible grape skin–carob complexes with enhanced intestinal absorption kinetics. Premium beverage manufacturers in Germany and France adopt these systems at accelerated pace for shelf-stable functional drinks. The structural consequence is compressing demand for conventional spray-dried powders in high-margin applications.
REACH compliance deadlines for extract purity are tightening contaminant thresholds for botanical drug precursors, forcing processors to implement HPLC-MS screening protocols for pesticide residues and heavy metals. Industrial consequence includes capital intensity elevation for small-scale Mediterranean suppliers. Dietary supplement contract manufacturers face the steepest adaptation burden, with several German firms consolidating supplier bases to reduce audit complexity.
Retailer-driven clean-shelf policies are shortening ingredient approval cycles and compressing supplier qualification timelines. European functional food brands bypass traditional distributor networks for direct processor relationships, fragmenting historical procurement channels. This pattern concentrates in France and Italy where retail consolidation gives buyers asymmetric negotiating leverage over extract suppliers.
Grape Skin–Carob Synergy Antioxidant Systems Market Segmentation
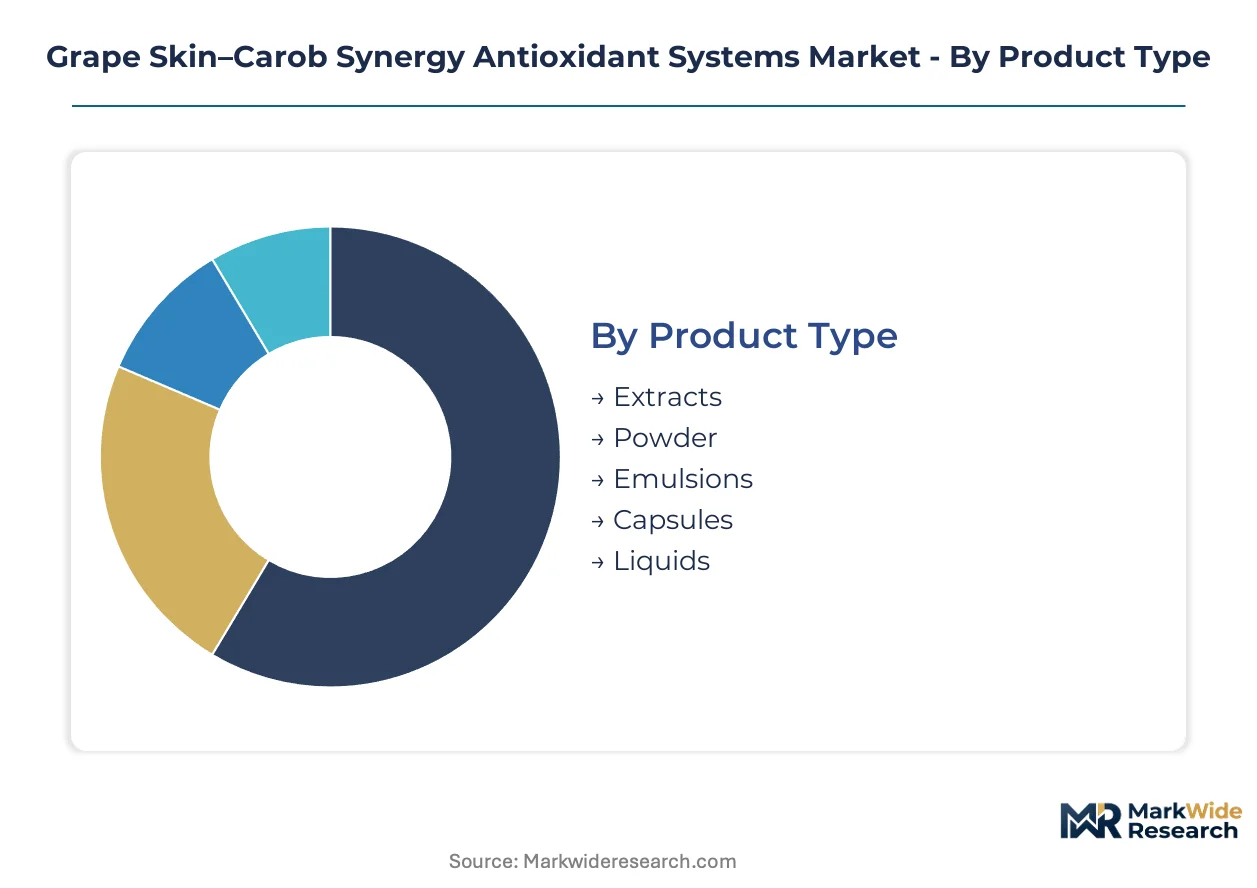
Segmentation in this market reveals how capital requirements and technical complexity stratify competitive positioning across delivery formats, end-use applications, and processing technologies. Understanding these divisions exposes where procurement budgets concentrate and where formulation science creates differentiation.
Product Type:
Capital intensity peaks in formats requiring specialized drying infrastructure and containment systems for active polyphenol preservation.
- Powder:Spray-dried matrices standardized to 40-60% total polyphenol content dominate bulk ingredient handling through superior oxidative stability during storage. German nutraceutical capsule manufacturers anchor procurement volumes here, though margin compression from commodity-grade competition intensifies.
- Emulsions:Water-dispersible nanoemulsion systems demand homogenization equipment and lipid-phase engineering that multiplies production capex versus dry formats. French and German functional beverage producers drive adoption for clean-label shelf-stable drinks, with bioavailability claims justifying premium positioning.
- Extracts:Semi-liquid concentrates require solvent recovery systems and refrigerated supply chains.
- Capsules:Pre-formulated dosage units need encapsulation lines and blister packaging infrastructure.
- Liquids:Aqueous suspensions face microbial stability challenges requiring pasteurization or aseptic filling investments.
Powder absorbs the bulk of installed capacity; emulsions are expanding most quickly.
Application:
Regulatory documentation burdens and clinical substantiation requirements vary sharply across end-use categories, reshaping supplier qualification timelines.
- Dietary Supplements:Capsule and tablet formats command established procurement channels through nutraceutical contract manufacturers, with EFSA health claim pathways for cardiovascular endpoints driving R&D investment. French and Italian Mediterranean processing clusters supply standardized extracts meeting 40-60% polyphenol benchmarks for this segment.
- Functional Foods:Clean-shelf policies at major European retailers force reformulation away from synthetic preservatives toward polyphenol-rich natural stabilizers in shelf-stable emulsions. German beverage producers lead adoption of nanoemulsion-integrated grape skin–carob systems for premium positioning.
- Cosmetics:Topical antioxidant claims require dermal safety testing that extends development cycles.
- Animal Nutrition:Feed-grade specifications tolerate lower purity thresholds than human applications.
- Food Preservation:Lipid oxidation inhibition applications compete on cost with synthetic alternatives.
Dietary supplements retain the largest revenue footprint; functional foods exhibit the steepest expansion trajectory.
Formulation Technology:
Patent-protected delivery systems concentrate margin capture among technology-integrated processors versus commodity extract suppliers.
- Nanoemulsions:Lipid-phase engineering with particle sizes below 200 nanometers maximizes intestinal absorption kinetics for bioavailability-optimized claims. Premium beverage manufacturers in France and Germany prioritize these systems despite 3-4x production cost premiums over conventional powders.
- Microencapsulation:Spray-dried or coacervated matrices protect polyphenols from gastric degradation for controlled-release nutraceutical applications. Cognitive health segment demand drives investment in extended-release protocols combining galactomannan carriers with lipid encapsulation.
- Spray Drying:Established industrial scale minimizes unit costs for bulk powder production.
- Cold Pressing:Low-temperature extraction preserves heat-labile procyanidin profiles but limits throughput.
- Fermentation:Biotransformation approaches remain experimental for polyphenol glycoside modification.
Spray drying holds the majority of production assets; nanoemulsions attract the fastest capacity additions.
End User:
Procurement sophistication and audit intensity separate pharmaceutical-grade buyers from feed-grade commodity purchasers.
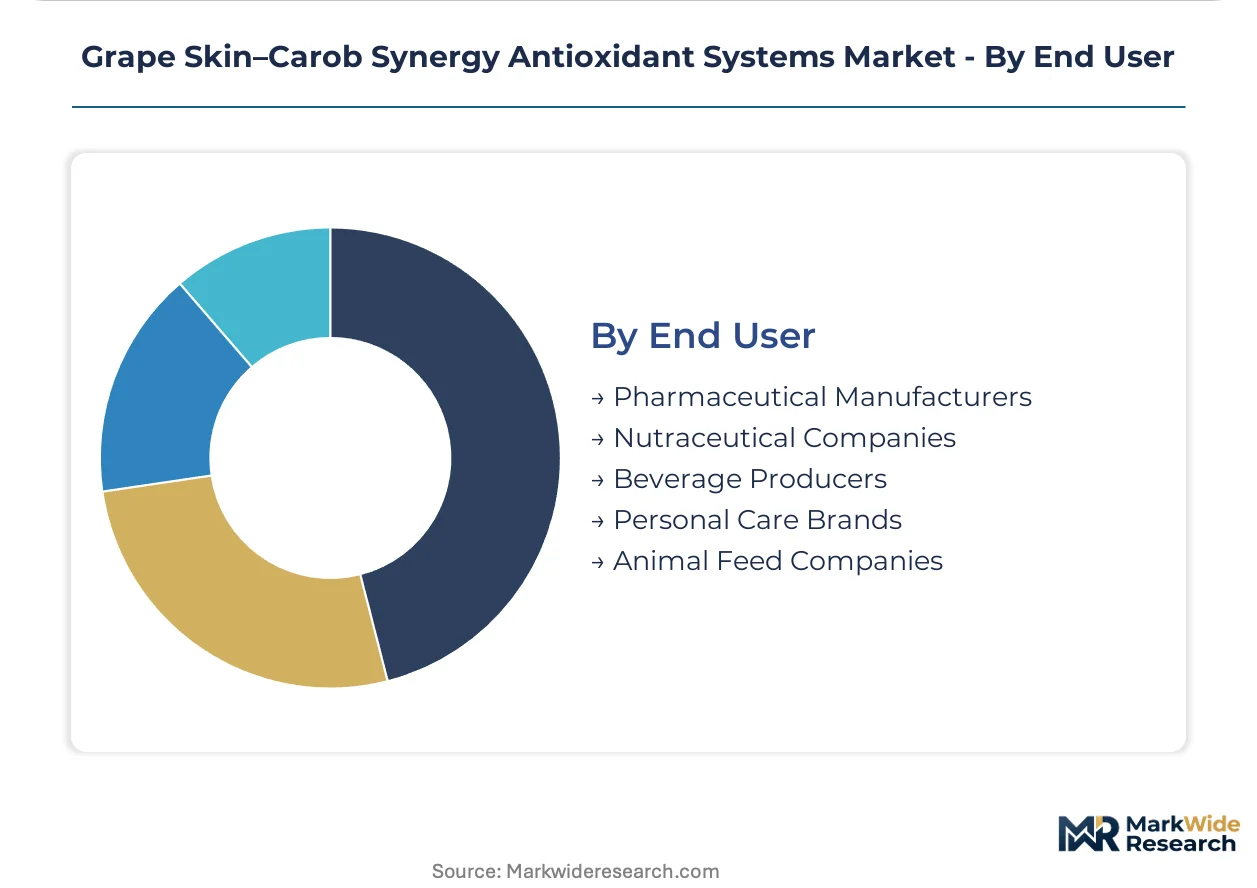
- Nutraceutical Companies:German capsule and tablet manufacturers enforce stringent REACH Annex XVII compliance for contaminant-free galactomannan matrices, consolidating supplier bases to reduce audit complexity. Direct processor relationships bypass traditional distributors as retailer-driven clean-shelf policies compress qualification timelines.
- Pharmaceutical Manufacturers:EMA botanical drug guidelines demand HPLC-MS documentation for pesticide residues and heavy metals that exceeds nutraceutical requirements. This tier commands highest purity premiums but represents limited volume given regulatory friction.
- Beverage Producers:Functional drink brands prioritize water-dispersibility and clean-label positioning over standardization precision.
- Personal Care Brands:Cosmetic applications require dermal safety dossiers that extend development cycles.
- Animal Feed Companies:Feed-grade specifications tolerate broader contaminant ranges at corresponding price discounts.
Nutraceutical companies deploy the largest procurement budgets; beverage producers are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Zona Franca regime in Barcelona accelerates botanical extract processing investments, concentrating Mediterranean carob value chains near port infrastructure. Tax-advantaged zones in southern France and Italy's Sicily anchor comparable clustering dynamics for grape skin procurement networks.
Germany
Nutraceutical capsule manufacturers in Bavaria and North Rhine-Westphalia scale procurement of polyphenol-rich stabilizers for clean-label formulations. REACH Annex XVII compliance requirements tighten contaminant thresholds for botanical drug precursors, compressing supplier qualification timelines. The Baden-Württemberg processing corridor hosts specialized HPLC-MS screening facilities serving contract manufacturers consolidating supplier bases.
France
Functional beverage producers in the Île-de-France and Provence-Alpes-Côte d'Azur regions drive nanoemulsion adoption for water-dispersible antioxidant systems. EFSA novel food pathways for Ceratonia siliqua-derived ingredients accelerate regulatory approvals for standardized extracts. Mediterranean carob gum extraction capacity concentrates in southern French cooperatives near Marseille, creating supply security for pharmaceutical-grade buyers.
Italy
Sicilian carob processing clusters anchor galactomannan-polyphenol matrix production for European nutraceutical supply chains. EMA botanical drug guidelines elevate analytical documentation burdens for pesticide residue screening. The Emilia-Romagna food technology corridor integrates grape skin procurement from regional wine cooperatives into shelf-stable emulsion formulations.
United States
Domestic grape processors in California's Central Valley leverage FSMA foreign supplier verification requirements to capture functional food market share from European competitors. FDA GRAS self-affirmation pathways create parallel compliance tracks for polyphenol-specific cardiovascular health claims. Pacific Northwest beverage innovators pilot nanoemulsion delivery systems for bioavailability-optimized positioning.
Switzerland
Swissmedic pharmaceutical-grade standards attract premium-tier antioxidant system procurement for cognitive health applications. Precision delivery system specialists in the Basel-Zurich corridor converge spray-drying protocols with lipid encapsulation technologies. Alpine contract manufacturers enforce extended-release matrix specifications exceeding EFSA novel food benchmarks.
Grape Skin–Carob Synergy Antioxidant Systems Market Competitive Landscape
Top-tier vendors anchor flavor-integrated ingredient platforms and Mediterranean supply chain control, while mid-tier extract processors compete on polyphenol standardization precision. The vendor base stratifies across three archetypes: integrated flavor houses with botanical extraction capabilities, specialized carob gum and grape skin processors, and contract manufacturers with nanoemulsion formulation expertise. Consolidation accelerates among European carob processors capable of certifying contaminant-free galactomannan matrices. Backward integration into North American grape processing operations and technology licensing for lipid-phase engineering represent dominant competitive vectors.
Within the integrated flavor house tier, Givaudan and Symrise occupy positions leveraging cross-category ingredient platforms for premium beverage embedding. Nexira anchors Mediterranean supply chain control through southern French procurement networks. Among diversified agricultural processors, ADM exemplifies scale-driven backward integration strategies into North American grape value chains. These three represent distinct archetypes: flavor-technology integration, geographic supply concentration, and upstream raw material capture.
| Leading Market Players |
|---|
| Givaudan |
| Nexira |
| Indena |
| ADM |
| Symrise |
| Kalsec |
| Döhler |
| Polyphenolics |
| Botanic Innovations |
| Others |
Pricing and Supply Chain Analysis
Procurement consolidation among German nutraceutical capsule manufacturers is compressing supplier qualification timelines and forcing Mediterranean extract processors to absorb certification costs that feed into delivered price premiums for REACH-compliant galactomannan matrices.
Pricing Analysis
Spot inventory discounts versus premium pricing for short lead times structures transactional dynamics across powder and emulsion formats. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified extracts from nutraceutical-grade powders and feed-grade alternatives. Price differentiation rests on REACH Annex XVII certification status and HPLC-MS documentation completeness. Cost compression in standard-grade powders is intensifying because wine industry diversion priorities constrain grape skin feedstock availability. Animal nutrition buyers exhibit highest price sensitivity; Swiss pharmaceutical manufacturers accept steepest premiums for Swissmedic-grade specifications.
Supply Chain Analysis
Direct-to-nutraceutical-manufacturer channels handle volume procurement from Bavarian and North Rhine-Westphalia capsule producers, bypassing traditional distributors as retailer clean-shelf policies compress approval cycles. Geographic supply concentrates in France, Italy, and Spain where Mediterranean carob processing clusters anchor galactomannan extraction capacity and Zona Franca regimes accelerate Barcelona-area investments. Raw material dependencies center on Vitis vinifera harvest cycles, wine industry diversion priorities, and Ceratonia siliqua pod procurement from southern French cooperatives. Single-geography exposure exceeding seventy percent of pharmaceutical-grade carob gum origin creates structural vulnerability to regional climate disruption or cooperative consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side capacity constraints in HPLC-MS-certified Mediterranean processing infrastructure prop pricing power for incumbent extract suppliers capable of documenting contaminant-free matrices.
For Market Incumbents: Acquire specialized HPLC-MS screening facilities in the Baden-Württemberg corridor to internalize analytical documentation burdens that EMA botanical drug guidelines impose on external suppliers. Consolidate supplier relationships with Sicilian and southern French carob cooperatives to secure captive galactomannan feedstock against emerging backward-integrated competitors from North American grape processing operations. For New Entrants and Emerging Players: Functional beverage contract manufacturers in Germany and France represent the most penetrable channel entry point given their accelerating adoption of nanoemulsion delivery systems and limited incumbent relationships with lipid-phase engineering specialists. Target white-space positioning in bioavailability-optimized cognitive health applications where extended-release matrix protocols remain underdeveloped relative to powder dominance. For Investors and Strategic Acquirers: Re-rating potential sits with nanoemulsion technology specialists given EFSA health claim substantiation thresholds for polyphenol-specific cardiovascular endpoints that reward absorption-claim differentiation. Monitor EMA botanical drug guideline enforcement intensity as inflection signal for pharmaceutical-grade purity premium sustainability across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grape Processing | ADM's California Central Valley operations capture FSMA-compliant supply security against European import friction. |
| Nanoemulsion Capacity Expansion | Givaudan's lipid-phase engineering investments embed flavor-integrated antioxidant systems into premium beverage lines. |
| REACH Certification Investment | Nexira's southern French cooperative consolidation secures contaminant-free galactomannan documentation for pharmaceutical buyers. |
| Direct Processor Relationships | Bavarian capsule manufacturers bypass distributors to compress qualification timelines under retailer clean-shelf mandates. |
| Extended-Release Matrix Development | Swiss precision delivery specialists converge spray-drying with lipid encapsulation for cognitive health applications. |
Research Methodology
Trade databases, EFSA novel food submission records, and REACH Annex XVII compliance filings formed the secondary backbone, cross-referenced against primary interviews with nutraceutical contract manufacturing procurement leads, Mediterranean carob cooperative processing managers, German functional beverage R&D directors, and Swiss pharmaceutical-grade extract qualification specialists. Bottom-up volume estimates from individual processor capacity disclosures and top-down demand aggregation from end-use application consumption patterns enabled triangulation validation.
Bottom-up modeling anchored segment-level projections across powder, emulsion, and extract formats; top-down macro validation referenced functional food and dietary supplement consumption trends. Segmentation dimensions included product type, application category, formulation technology tier, and end-user procurement sophistication. CAGRs derived from fitted growth curves incorporating EFSA regulatory timeline assumptions, REACH compliance cost trajectories, and nanoemulsion adoption rate sensitivity across the projection horizon.
Caveats apply where EMA botanical drug guideline enforcement intensity, wine industry grape skin diversion priorities, or nanoemulsion bioavailability claim substantiation requirements could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Europe Functional Beverages Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
APAC Functional Food Ingredients Market