
 Botanical Infusions Market | 2026-2036
Botanical Infusions Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Infusions Market Analytics
Botanical sourcing expertise is bifurcating the competitive landscape as traditional herbal knowledge becomes scarce and extraction science grows more complex. Martin Bauer Group leverages its century-old supplier relationships across European growing regions to secure rare botanical inputs. Givaudan differentiates through advanced CO2 extraction capabilities that preserve volatile aromatic compounds. Fever Tree anchors the premium mixer segment with concentrated botanical formulations designed for cocktail applications.
Botanical infusions comprise plant-derived extracts, essential oils, and tisanes produced through steeping, distillation, or solvent extraction to yield bioactive compounds for flavoring, therapeutic, or functional applications. Cold-pressed and supercritical CO2 methods now dominate premium extraction, preserving heat-sensitive terpenes and polyphenols that define sensory and functional potency. Herbal teas occupy the largest volume share among product types, reflecting established consumer rituals and accessible price positioning. Infused beverages represent the fastest-expanding category as functional drink formulations incorporate adaptogenic botanicals targeting stress and cognitive performance. Extracts command the highest margin pool due to concentrated dosing requirements in wellness products and pharmaceutical-grade applications.
EFSA novel food assessments and EU REACH compliance govern botanical ingredient safety and market access across Europe, while FDA GRAS self-affirmation and DSHEA framework regulate U.S. positioning. These overlapping standards create compliance complexity that favors vertically integrated players with dedicated regulatory affairs teams. Stakeholders must monitor evolving novel food rulings on emerging botanicals like ashwagandha and lion's mane, as classification decisions will determine which ingredients achieve mainstream formulation scale.
Market Dynamics
Clean-label mandates from food service operators are compressing formulation timelines for botanical infusions, forcing suppliers to validate novel extraction methods before artificial additive bans take full effect.
Growth Catalysts
- EU Novel Food Regulation streamlining:Accelerated safety assessments for traditional botanicals are reducing time-to-market for heritage ingredients like chamomile and elderflower. German regulators have pioneered mutual recognition pathways that other member states now adopt.
- Adaptogenic functional beverages:Stress-management positioning is pulling ashwagandha and rhodiola into mainstream ready-to-drink formulations. Beverage manufacturers in the wellness channel are reformulating entire product lines around these bioactives.
- Carbon dioxide extraction maturation:Supercritical CO2 systems now operate at tonnage scale, preserving heat-sensitive terpenes that steam distillation degrades. Premium extractors are retrofitting facilities to capture volatile aromatic fractions previously lost to thermal damage.
Market Restraints
- Wild-harvested supply volatility:Climate stress on Alpine growing regions is compressing yields for gentian and wormwood. Collectors in Bavaria and Tyrol face harvest windows that have narrowed by several weeks over the past decade.
- EFSA novel food backlog:Pending safety opinions for lion's mane and reishi extracts are freezing formulation investment. Brands cannot commit to scale until classification resolves whether these fungi qualify as food or novel ingredients.
- Synthetic flavor substitution:Advanced biotechnology-derived aroma compounds are achieving cost parity with botanical extracts in beverage applications. Flavor houses are pitching precision fermentation as a supply-guaranteed alternative to agricultural sourcing.
Strategic Opportunities
- Indian ayurvedic export expansion:FSSAI certification alignment with EU standards is opening formulation partnerships between Mumbai extractors and European beverage brands. Tulsi and brahmi are crossing from traditional medicine into functional drink applications.
- Direct-to-brewer supply contracts:Craft distilleries and microbreweries are bypassing flavor houses to source single-origin botanicals. Small-batch producers in Scotland and Vermont are specifying terroir-grade ingredients with full provenance documentation.
- EU Green Deal agricultural incentives:Conversion subsidies for organic cultivation are expanding hectarage for medicinal herbs in France and Poland. Growers are shifting from commodity crops to contract-grown botanicals with guaranteed offtake.
Industry Challenges
- Phytochemical standardization expertise:Consistent marker compound quantification requires analytical chemists trained in HPLC and mass spectrometry methods. The talent pool for botanical quality control is concentrated in university clusters around Montpellier and Wageningen.
- Dual-use export licensing:Concentrated essential oils with pharmaceutical applications trigger controlled substance protocols. Shippers navigating EU dual-use regulations face documentation burdens that delay container movements by several weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Infusions Market |
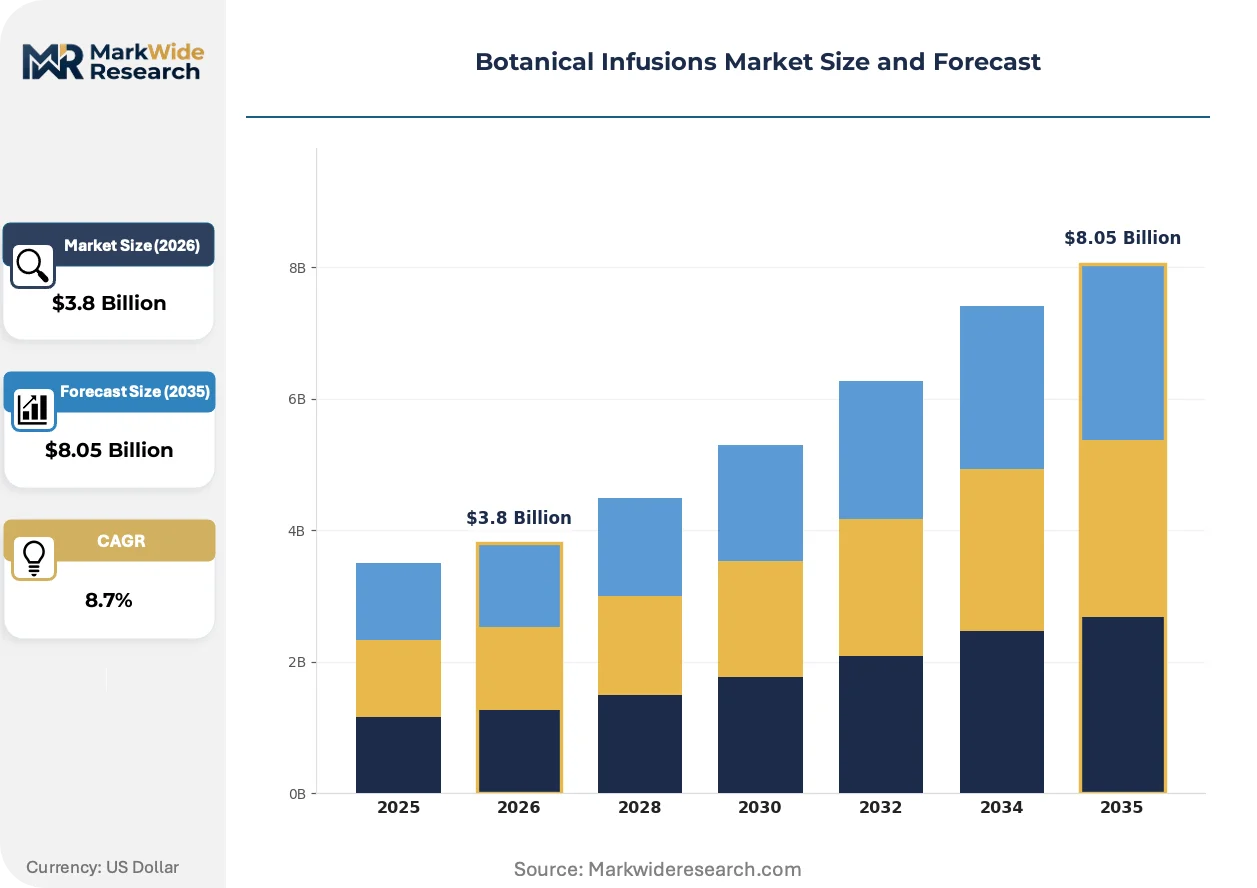
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Teas, Essential Oils, Extracts, Infused Beverages Application: Culinary Uses, Wellness Products, Aromatherapy, Household Cleaning End User: Retail Consumers, Food Service, Wellness Centers, Manufacturers Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Shops |
| Companies Covered | Archer Daniels Midland Company, Martin Bauer Group, Givaudan, Nestlé S.A., Döhler GmbH, Fever Tree, Blue Sky Botanics Ltd., Bumblezest, Cotswolds Distillery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Infusions Market Evolving Landscape
Extraction technology convergence with precision agriculture is redefining how botanical potency is captured, standardized, and traced from field to formulation. Three developments are compressing the innovation cycle.
Supercritical CO2 extraction is decomposing the traditional steam distillation supply base by enabling cold processing of heat-sensitive botanicals. Premium beverage formulators in Germany and California are specifying CO2-extracted terpene profiles for their cocktail mixer lines. The technology is compressing minimum viable batch sizes, allowing craft-scale producers to access extraction quality previously reserved for industrial flavor houses.
EFSA's updated guidance on botanical safety assessments is tightening evidentiary requirements for novel ingredient submissions. The regulation is forcing extractors to commission 90-day toxicology studies that add substantial cost to development timelines. Smaller suppliers without dedicated regulatory affairs teams are withdrawing marginal botanical candidates rather than absorbing compliance investment.
Food service procurement teams are consolidating supplier relationships around vertically integrated extractors with captive organic cultivation. Contract brewers and restaurant groups are replacing spot-market purchasing with multi-year supply agreements that specify harvest batch traceability. The shift is most visible in Nordic markets where procurement directors prioritize single-origin documentation for menu transparency claims.
Botanical Infusions Market Segmentation
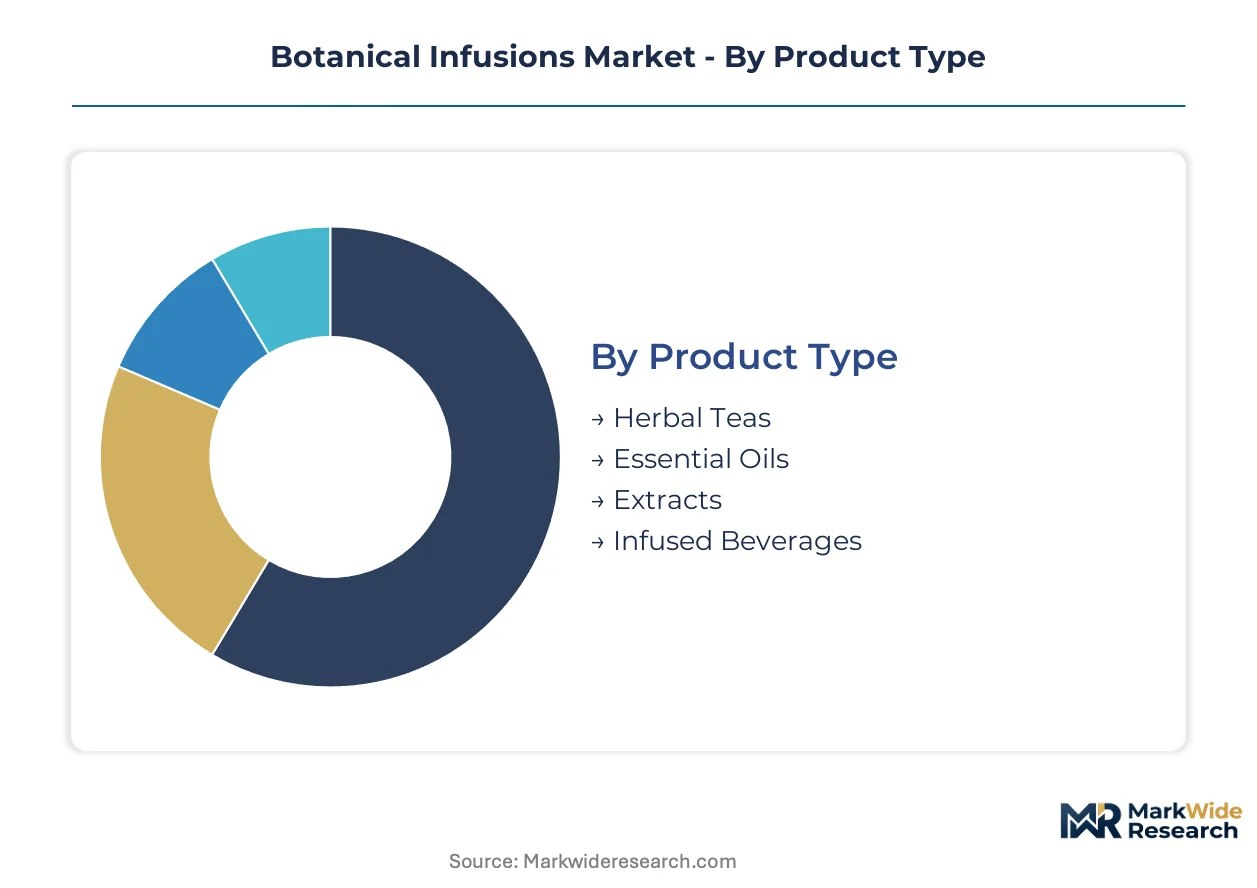
Botanical infusions fragment across extraction intensity, end-use sophistication, and regulatory exposure. Each segment carries distinct margin profiles and compliance burdens that reshape supplier priorities and buyer procurement patterns.
Product Type:
EFSA novel food classifications and FDA GRAS pathways create divergent approval timelines across extraction formats, with concentrated extracts facing the steepest evidentiary requirements.
- Herbal Teas:Dried plant material steeped in hot water delivers accessible polyphenol content with minimal processing. German pharmacy chains and French hypermarkets move the highest volumes, though price compression from private-label competition erodes branded margins.
- Essential Oils:Steam-distilled or cold-pressed volatile concentrates command premium positioning in aromatherapy and natural cleaning formulations. French lavender and Bulgarian rose oils anchor the luxury tier, with climate volatility in Provence and Kazanlak narrowing harvest windows and tightening supply.
- Extracts:Standardized bioactive compounds from solvent or CO2 processing serve pharmaceutical and functional beverage applications.
- Infused Beverages:Ready-to-drink formulations incorporating adaptogenic botanicals target stress-management positioning.
Established volume favors herbal teas; emerging adoption favors infused beverages.
Application:
End-use specifications range from sensory-driven culinary formulations to evidence-based therapeutic claims, with regulatory scrutiny intensifying proportionally to health positioning.
- Culinary Uses:Flavoring applications in premium restaurants and artisan food production emphasize terroir documentation and single-origin traceability. Michelin-starred kitchens in Copenhagen and San Francisco now specify harvest batch provenance for menu transparency.
- Wellness Products:Dietary supplements and functional foods require EFSA health claim validation or FDA structure-function disclaimers. Ashwagandha and lion's mane formulations face pending novel food opinions that freeze brand investment until classification resolves.
- Aromatherapy:Inhalation and topical applications of essential oils for mood and stress modulation.
- Household Cleaning:Botanical antimicrobials replacing synthetic disinfectants in eco-formulations.
Culinary applications dominate current revenue; wellness products are expanding most quickly.
End User:
Procurement sophistication varies from impulse-driven retail selection to multi-year supply contracts with embedded quality specifications and audit rights.
- Retail Consumers:Supermarket and online purchasers respond to clean-label claims and organic certification. German consumers show highest willingness-to-pay for Demeter biodynamic seals.
- Food Service:Restaurant groups and contract brewers bypass distributors for direct botanical sourcing with full traceability documentation.
- Wellness Centers:Spas and clinics incorporate botanical treatments into service menus.
- Manufacturers:Flavor houses and pharmaceutical formulators purchase standardized extracts in bulk quantities.
Retail channels capture the widest volume base; food service procurement is gaining share fastest.
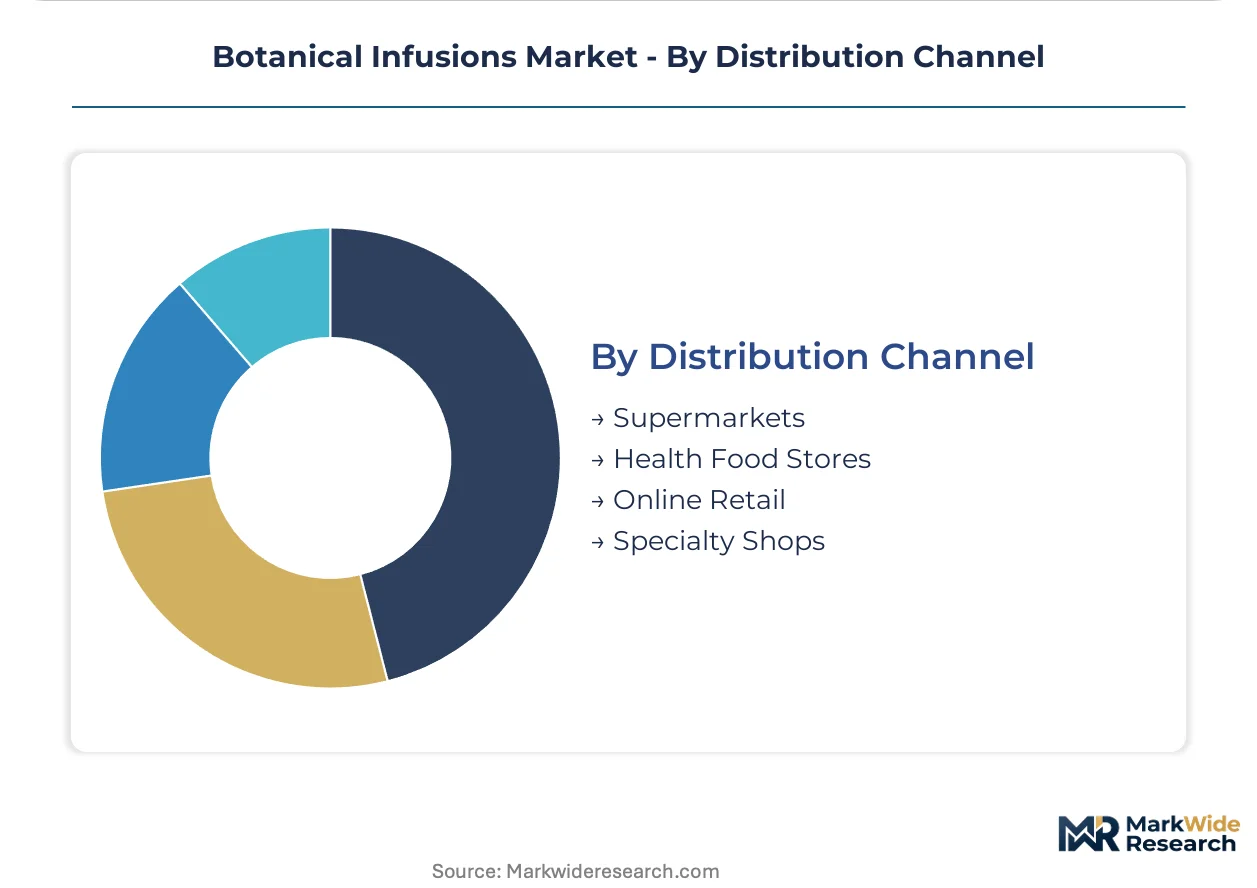
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer platforms capturing value previously allocated to wholesale intermediaries.
- Supermarkets:Mass-market penetration requires slotting fees and promotional investment that favor scaled suppliers. Carrefour and REWE chains in France and Germany dominate continental European volume.
- Health Food Stores:Specialized retailers command premium shelf positioning for certified organic and biodynamic lines. Independent stores in the Netherlands and Austria maintain buyer relationships with specific growing cooperatives.
- Online Retail:Direct-to-consumer platforms enable subscription models and harvest-fresh positioning.
- Specialty Shops:Tea merchants and apothecaries serve connoisseur segments with rare varietals.
Supermarkets anchor volume concentration; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's novel food assessments and the EU Green Deal agricultural incentives anchor European regulatory influence over botanical ingredient flows, while FDA GRAS pathways and India's FSSAI certification alignment shape parallel approval architectures in North America and Asia-Pacific.
Germany
Traditional herbal medicine culture intersects with modern functional beverage innovation across pharmacy chains and craft distilleries. The EU's updated Novel Food Regulation streamlines safety assessments for heritage ingredients like chamomile and elderflower through German-pioneered mutual recognition pathways. Bavaria and Tyrol host concentrated gentian and wormwood harvesting operations where climate stress has narrowed collection windows.
United States
Adaptogenic functional beverages pull ashwagandha and rhodiola into mainstream ready-to-drink formulations targeting stress management. FDA GRAS self-affirmation and DSHEA framework regulate botanical positioning, creating compliance complexity for imported extracts. California beverage manufacturers and Vermont microbreweries increasingly specify single-origin botanicals with full provenance documentation.
India
Ayurvedic export expansion accelerates as FSSAI certification alignment with EU standards opens formulation partnerships between Mumbai extractors and European brands. Tulsi and brahmi cross from traditional medicine into functional drink applications. Cultivation clusters in Maharashtra and Karnataka benefit from contract-growing arrangements with guaranteed offtake.
France
EU Green Deal agricultural conversion subsidies expand organic hectarage for medicinal herbs in Provence and other growing regions. Lavender and rose oil production faces climate volatility narrowing harvest windows in Provence and Kazanlak supply zones. Montpellier anchors analytical chemistry talent pools essential for phytochemical standardization.
United Kingdom
Premium mixer and craft spirits segments drive concentrated botanical formulation demand. EFSA regulatory alignment post-Brexit maintains novel food assessment requirements for ingredient imports. Cotswolds and Scottish distilleries bypass flavor houses for direct single-origin botanical sourcing with batch traceability specifications.
Botanical Infusions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the competitive landscape bifurcating between century-old supplier relationships and advanced extraction capabilities. Traditional herbal knowledge scarcity and extraction science complexity drive this stratification. Three archetypes dominate: vertically integrated growers with captive cultivation, technology-forward extractors with CO2 capabilities, and premium beverage formulators with direct sourcing relationships. Competitive moves concentrate on multi-year supply agreements with embedded traceability requirements and regulatory affairs team expansion to navigate overlapping EFSA and FDA frameworks.
Within the integrated supplier tier, Martin Bauer Group and Givaudan exemplify contrasting capability configurations, while Fever Tree occupies a distinct position in premium beverage formulation. Martin Bauer Group represents the heritage-anchored archetype leveraging long-standing European growing region relationships. Givaudan exemplifies technology-differentiated extraction science capabilities. Fever Tree sits within the direct-to-channel formulation segment, anchoring premium mixer positioning through concentrated botanical specifications designed for cocktail applications.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Martin Bauer Group |
| Givaudan |
| Nestlé S.A. |
| Döhler GmbH |
| Fever Tree |
| Blue Sky Botanics Ltd. |
| Bumblezest |
| Cotswolds Distillery |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between European beverage manufacturers and Alpine botanical collectors lock in supply access while capping price volatility for gentian and wormwood harvests. These contracts embed climate-adjustment clauses that transfer yield-risk exposure from growers to processors, reshaping margin distribution across the extraction value chain.
Pricing Analysis
Contract-based long-term offtake dominates premium extract transactions, with spot markets handling only commodity-grade herbal teas. Price differentiation rests on organic certification tier and single-origin traceability documentation, with Demeter biodynamic seals commanding substantial premia over EU Organic. Cost compression in standard-grade extracts is intensifying because synthetic biotechnology-derived aroma compounds achieve cost parity in beverage applications. Retail consumers show highest price sensitivity, while food service procurement teams prioritize supply security over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for Indian ayurvedic exports and Southeast Asian spice shipments. Geographic supply concentration centers on Germany, France, and India, with raw material dependencies spanning Alpine gentian, Provence lavender, and Maharashtra tulsi. Single-source vulnerability runs through wild-harvested Alpine botanicals where climate stress has narrowed collection windows. Distribution runs through vertically integrated extractors with captive organic cultivation, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
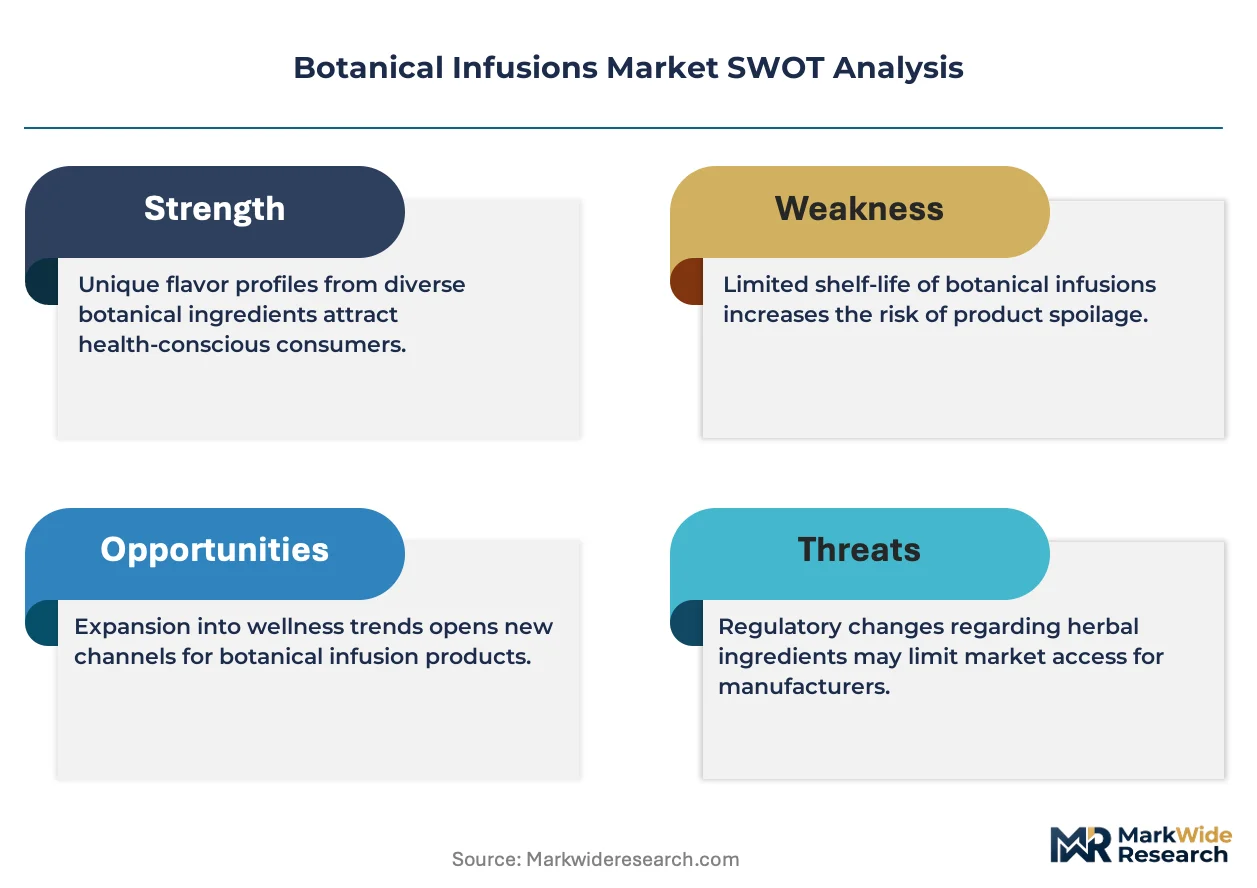
Regulatory entrenchment around EFSA novel food assessments and FDA GRAS pathways constructs formidable defensive moats for established players with dedicated compliance infrastructure. Switching costs for food service buyers escalate as multi-year supply agreements embed audit rights and batch-traceability specifications.
For Market Incumbents: Secure backward integration into captive organic cultivation in France and Poland to buffer wild-harvested supply volatility from Alpine climate stress. Deepen regulatory affairs capabilities to navigate pending EFSA opinions on lion's mane and reishi classifications before competitors achieve formulation scale. For New Entrants and Emerging Players: Anchor in direct-to-brewer supply contracts with Scottish and Vermont craft distilleries seeking single-origin botanicals with full provenance documentation. Target the penetrable ayurvedic export channel where FSSAI-EU certification alignment is opening formulation partnerships for tulsi and brahmi applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated extractors with multi-year supply agreements and embedded traceability requirements. Acquisition focus should center on mid-cap specialists with CO2 extraction capabilities and established EFSA regulatory dossiers. Monitor EFSA novel food opinion publication timelines as the critical inflection signal for ingredient-scale investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | EU Green Deal subsidies in France and Poland reduce reliance on climate-stressed Alpine wild harvesting. |
| Regulatory Affairs Expansion | Dedicated EFSA and FDA compliance teams accelerate novel ingredient approval timelines for adaptogenic botanicals. |
| CO2 Extraction Scale-Up | Supercritical systems preserve heat-sensitive terpenes that steam distillation degrades in premium mixer formulations. |
| Direct-to-Brewer Supply Contracts | Craft distilleries in Scotland and Vermont bypass flavor houses for single-origin botanicals with batch traceability. |
| Ayurvedic Export Certification | FSSAI-EU alignment opens formulation partnerships between Mumbai extractors and European wellness beverage brands. |
Research Methodology
Operator-level perspectives from extraction facility managers, food service procurement directors, organic cultivation cooperatives, and regulatory affairs specialists anchored the qualitative base. These primary insights combined with secondary validation from EFSA novel food opinion databases, EU customs trade records, FDA GRAS notification filings, and FSSAI certification registries. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level estimates.
Sensitivity analysis tested forecast robustness across alternative regulatory approval timelines and climate yield scenarios over the projection horizon. Segmentation dimensions modeled include extraction intensity, application sophistication, end-user procurement type, and distribution channel structure. CAGRs derived from fitted growth curves incorporate EFSA opinion backlog resolution assumptions and EU Green Deal hectarage expansion trajectories for medicinal herb cultivation.
Material uncertainties — EFSA classification reversals, Alpine harvest window compression, synthetic biotechnology cost parity achievement — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and climate yield stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market