
 Fisetin Market | 2026-2036
Fisetin Market Size, Share, and Industry Trends Forecast 2026-2036
Fisetin Market Analytics
EU Green Deal bioeconomy targets is consolidating demand for plant-derived nutraceuticals across European formulators. Xi'an SR Bio-Engineering anchors supply from China's botanical extraction corridor, leveraging vertical integration from raw strawberry and smoke tree sourcing through refined isolate output. Stanford Chemicals competes on synthesis purity grades for pharmaceutical-grade fisetin, while Nutra Biotechnology specializes in capsule formulation for North American dietary supplement brands.
Fisetin is a flavonoid polyphenol, specifically 3,3',4',7-tetrahydroxyflavone, typically extracted from Rhus verniciflua bark or strawberries and purified to 98% assay for research and nutraceutical use. Its primary commercial purpose centers on senolytic applications—selective clearance of senescent cells—and antioxidant formulation in anti-aging supplements. Natural extract fisetin commands premium positioning in dietary supplements due to clean-label preference, while synthetic grades dominate pharmaceutical research quantities where batch consistency outweighs botanical provenance. Cosmetics application remains nascent but shows accelerating interest from Korean functional beauty formulators seeking novel antioxidant actives.
FDA New Dietary Ingredient notification requirements govern fisetin's entry into US supplement formulations, while EFSA Novel Food regulations constrain European commercialization timelines for non-traditional extracts. China's NMPA and SAMR jointly supervise botanical extract GMP compliance, with GB standards dictating heavy metal and solvent residue limits for export-grade flavonoids. Stakeholders must monitor evolving senolytic clinical trial readouts and corresponding regulatory reclassification risks that could shift fisetin from supplement ingredient to drug precursor status.
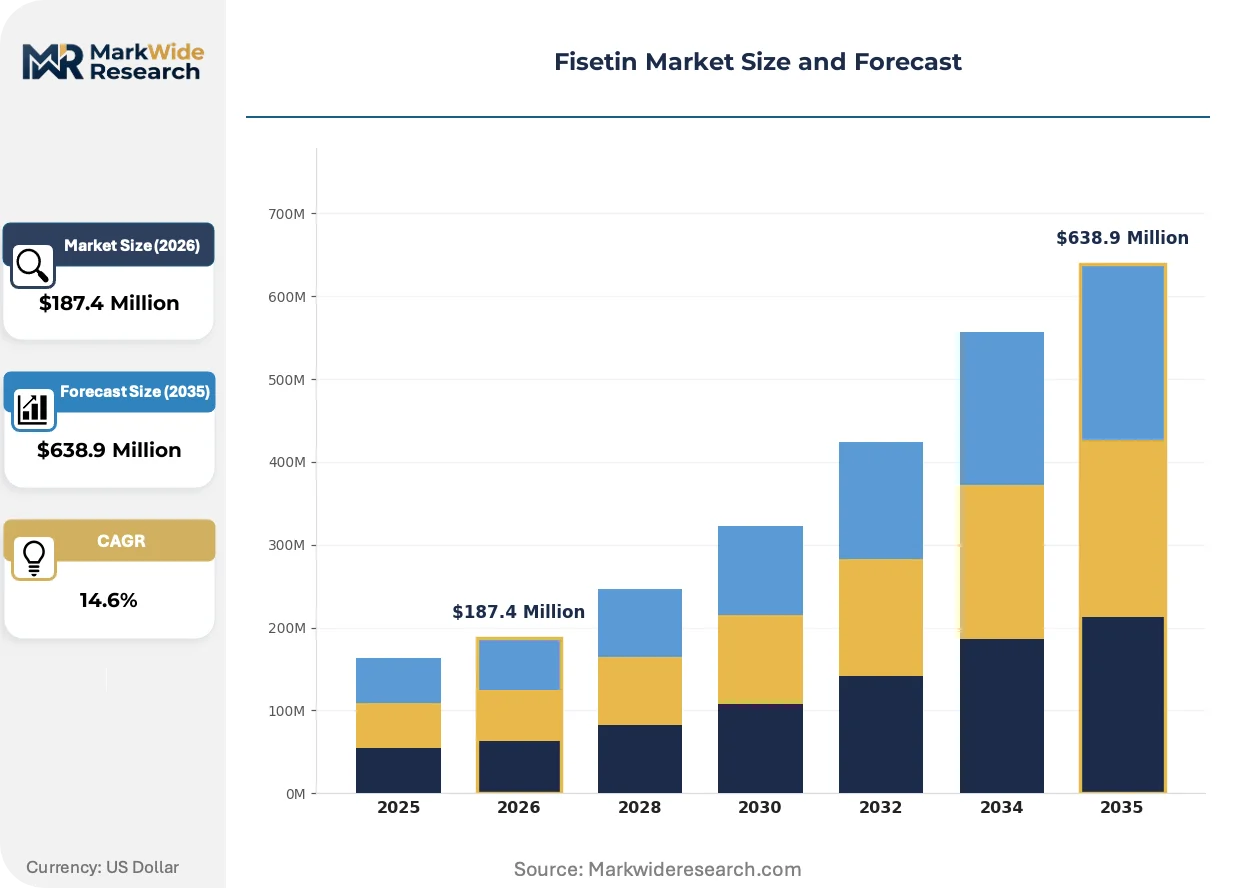
Market Dynamics
Clinical validation of senolytic mechanisms is concentrating procurement decisions among nutraceutical formulators seeking ingredient suppliers with published safety data. The FDA's evolving New Dietary Ingredient notification requirements are compressing qualification timelines for flavonoid entrants.
Growth Catalysts
- EU Green Deal bioeconomy targets:European formulators face procurement mandates favoring plant-derived nutraceuticals over synthetic alternatives, consolidating demand for botanical-extract fisetin.
- Senolytic supplement category expansion:Japanese and South Korean nutraceutical companies are building dedicated product lines around cellular senescence modulation, pulling refined fisetin through contract manufacturing channels.
- Shaanxi extraction corridor maturation:China's concentrated botanical processing clusters now supply 98% assay fisetin at pharmaceutical-grade purity, reducing formulator qualification burden.
Market Restraints
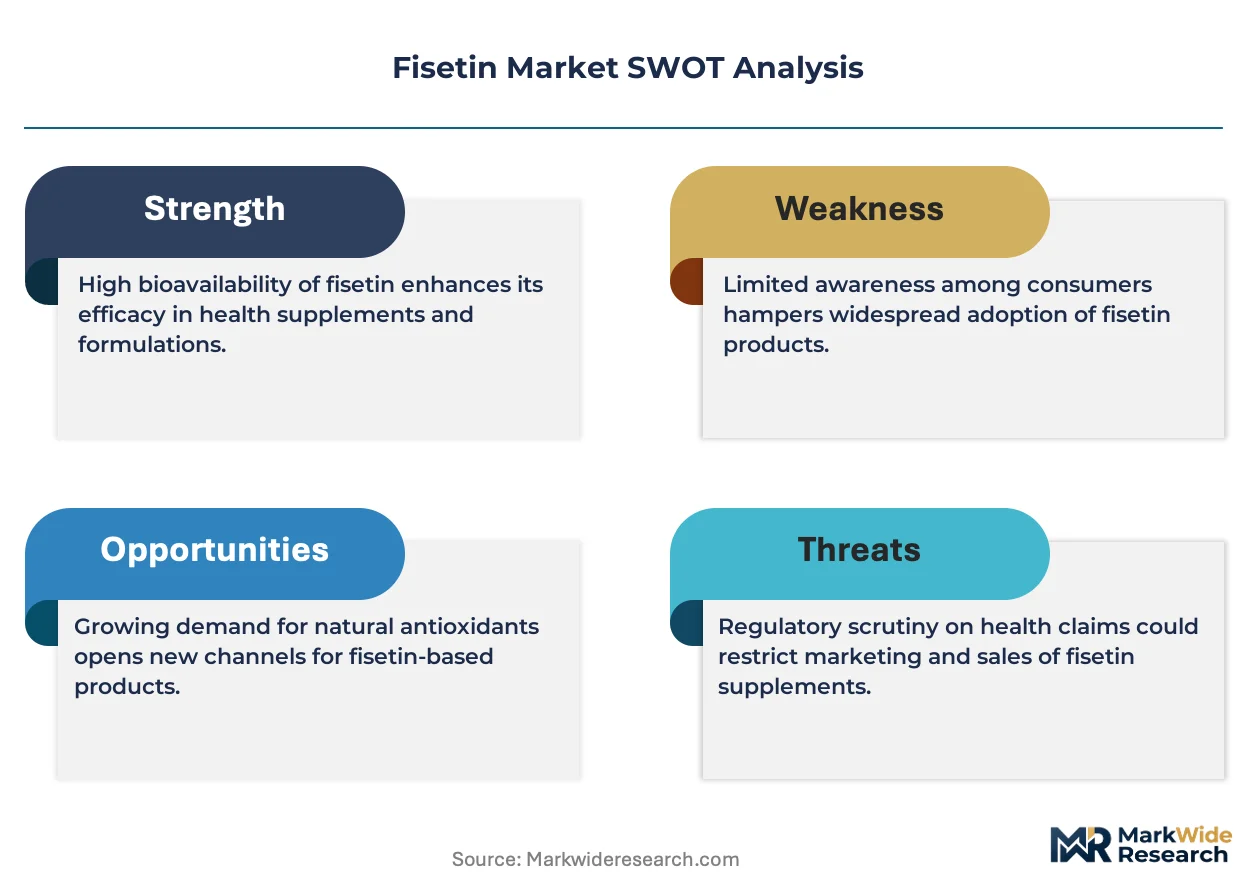
- Raw material concentration risk:Smoke tree bark and strawberry biomass supply chains cluster in specific temperate growing regions, exposing processors to climate volatility and harvest yield fluctuation.
- Regulatory friction from FDA NDI pathway:The notification requirement for novel flavonoid entrants creates 12-18 month commercialization delays and elevates legal compliance expenditure for US market access.
- Substitution threat from quercetin and resveratrol:Established polyphenol ingredients with deeper clinical bibliography compete for identical anti-aging positioning at lower procurement cost.
Strategic Opportunities
- Korean functional beauty channel:Cosmetic formulators in Seoul and Busan are testing fisetin antioxidant actives for anti-pollution skincare, creating demand outside traditional nutraceutical verticals.
- EFSA Novel Food regulatory tailwind:Successful authorization would unlock European food-grade applications beyond current supplement capsule formats, expanding addressable consumption occasions.
- Direct-to-consumer telehealth integration:Longevity-focused digital health platforms are bundling senolytic supplements with biomarker testing, creating subscription-based demand capture.
Industry Challenges
- Phytochemical standardization expertise gap:Formulators struggle to verify batch-to-batch flavonoid profile consistency when sourcing from multi-botanical extraction facilities.
- Clinical trial design complexity:Senescence biomarker validation for supplement claims requires specialized geroscience partnerships that mid-size ingredient suppliers lack capital to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fisetin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extract, Synthetic, Capsules, Powder End User: Pharmaceutical Companies, Dietary Supplement Manufacturers, Research Institutions, Nutraceutical Companies Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Xi’an SR Bio-Engineering, AdooQ, Stanford Chemicals, Nutra Biotechnology, Lingding Biological, Tocris Bioscience, Bio-Techne, Santa Cruz Biotechnology, Cayman Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fisetin Market Evolving Landscape
Bioprocess engineering advances are compressing production economics for high-purity flavonoid isolation while regulatory science evolves around cellular senescence claims. Three developments are restructuring competitive position.
Continuous chromatography purification is overtaking traditional solvent crystallization for fisetin isolation. Nutraceutical contract manufacturers in Japan and South Korea are adopting this platform to achieve 99.5% purity at commercial scale. The technology is compressing cost structures for natural-extract grades that previously required synthetic chemistry to match specification.
REACH registration requirements for novel botanical extracts are reshaping European commercialization strategy. The industrial consequence is forced pre-market safety dossier compilation that advantages established suppliers with existing toxicology portfolios. Pharmaceutical-grade fisetin destined for research quantities faces compressed timeline pressure as ECHA evaluation windows extend.
Subscription-based longevity protocols are fragmenting traditional wholesale distribution. Direct-to-consumer channels with integrated biomarker testing are displacing bulk ingredient sales to brand manufacturers in North American and Australian markets. This pattern concentrates margin capture with vertically integrated platform operators rather than ingredient specialists.
Fisetin Market Segmentation
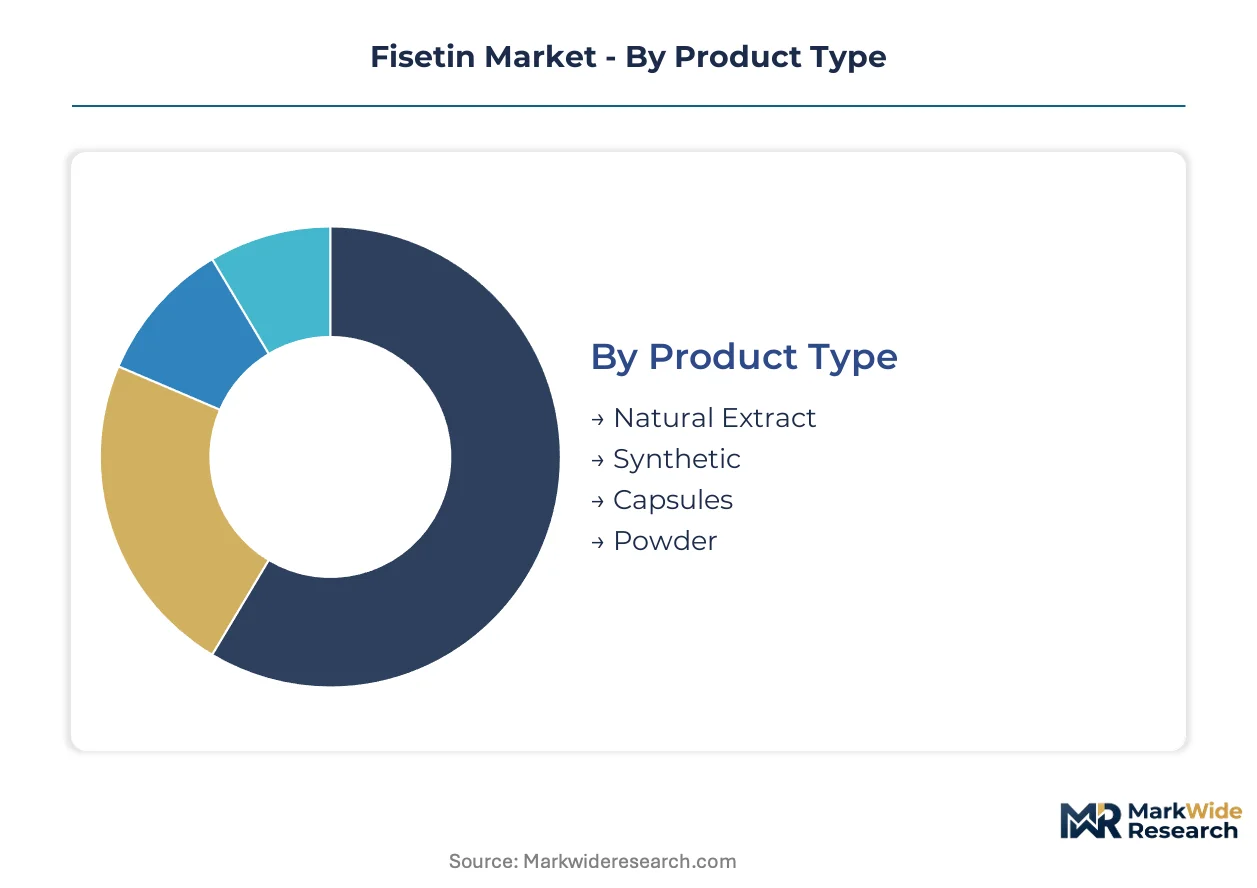
Fisetin procurement patterns diverge sharply across customer types, with pharmaceutical-grade specifications commanding wholly different supply relationships than nutraceutical bulk purchasing. Understanding these segment boundaries clarifies why pricing spreads and qualification timelines vary by an order of magnitude within the same molecular category.
Product Type:
Buyers differentiate primarily by purity specification and provenance documentation burden, not simply by format preference.
- Natural Extract:Botanical-derived material from Rhus verniciflua bark or strawberry biomass, standardized to 98% assay with full heavy metal and solvent residue documentation. Clean-label positioning drives premium procurement in Japanese and South Korean senolytic supplement lines, though batch-to-batch flavonoid profile variation requires formulator verification expertise.
- Synthetic:Chemically synthesized 3,3',4',7-tetrahydroxyflavone achieving 99.5% purity through controlled process chemistry. Research institutions and pharmaceutical companies prioritize batch consistency and traceability over botanical provenance, accepting synthetic origin for IND-enabling toxicology studies.
- Capsules:Pre-formulated unit-dose delivery in gelatin or vegetable shell formats, typically 100mg standardized strength. Contract manufacturers in North America source these for direct-to-consumer longevity platforms.
- Powder:Bulk isolate in kilogram-scale packaging for in-house formulation by mid-size nutraceutical brands. China's Shaanxi extraction corridor dominates supply, with Xi'an-based processors offering vertical integration from raw material through refined output.
Natural extract leads volumes today; synthetic grades are gaining share fastest in pharmaceutical research channels.
End User:
Procurement sophistication scales with regulatory exposure and clinical trial obligations.
- Pharmaceutical Companies:Demand GMP-certified synthetic grades with full CMC documentation for senolytic drug candidate development. FDA IND requirements and EMA quality guidelines dictate supplier qualification timelines stretching 18-24 months.
- Dietary Supplement Manufacturers:Source natural-extract grades for anti-aging capsule and tablet formulations. These buyers prioritize NDI notification support from suppliers navigating FDA pre-market safety dossier requirements.
- Research Institutions:Academic geroscience laboratories procure small-quantity synthetic fisetin for mechanistic senescence studies. Price sensitivity is high; grant-funded purchases favor competitive bidding across multiple catalog suppliers.
- Nutraceutical Companies:Integrated brand-owners developing proprietary senolytic stacks combine fisetin with quercetin and resveratrol. Korean functional beauty formulators represent emerging demand within this segment for topical antioxidant applications.
Dietary supplement manufacturers anchor current procurement volumes; pharmaceutical companies are expanding their share most rapidly.
Application:
Regulatory classification boundaries determine addressable market scope and margin structure.
- Dietary Supplements:Capsule and tablet formats positioned for cellular senescence modulation and antioxidant support. FDA NDI notification requirements create 12-18 month commercialization delays for novel flavonoid entrants.
- Functional Foods:Beverage and fortified food applications awaiting EFSA Novel Food authorization in Europe. Successful regulatory clearance would unlock food-grade consumption occasions beyond current supplement formats.
- Pharmaceuticals:Drug precursor status for senolytic therapeutic candidates targeting age-related disease. Clinical trial readouts from Mayo Clinic and other geroscience centers could trigger regulatory reclassification risks for supplement-grade supply.
- Cosmetics:Topical antioxidant actives for anti-pollution skincare formulations. Korean functional beauty brands in Seoul and Busan are testing fisetin against established polyphenol competitors.
Dietary supplements dominate current revenue; cosmetics application is climbing the fastest as Korean beauty formulators accelerate testing.
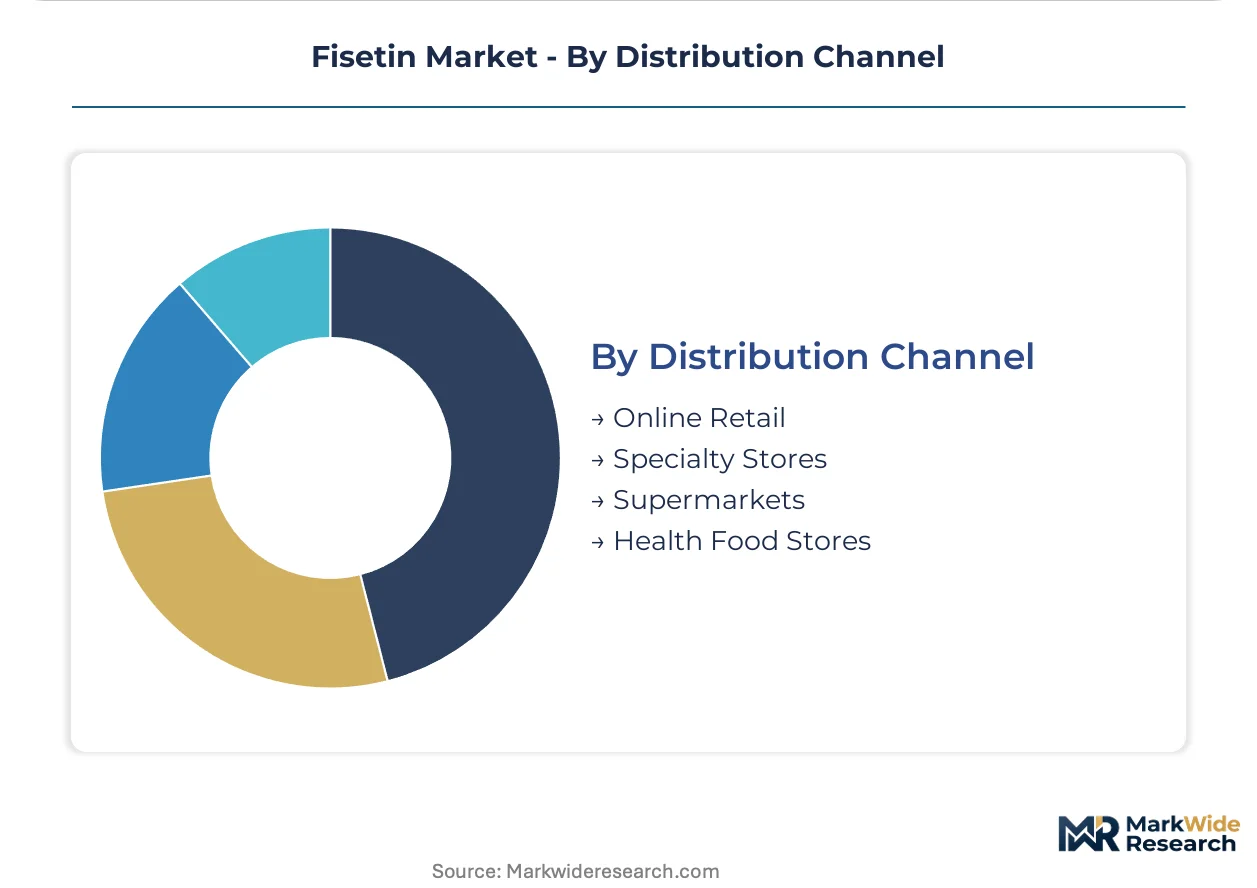
Distribution Channel:
Channel selection reflects customer acquisition cost tradeoffs and subscription model viability.
- Online Retail:Direct-to-consumer platforms with integrated biomarker testing and subscription protocols. These channels displace traditional wholesale distribution in North American and Australian longevity markets.
- Specialty Stores:High-touch retail environments with educated staff explaining senolytic mechanisms. Premium positioning supports margin capture for niche anti-aging brands.
- Supermarkets:Mass-market accessibility contingent on EFSA Novel Food or FDA GRAS status expansion. Current regulatory constraints limit penetration.
- Health Food Stores:Established channel for early-adopter consumers seeking clean-label botanical extracts. Staff training on cellular senescence claims varies by location.
Online retail leads transaction volumes today; specialty stores are expanding most quickly as educated consumer segments concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shaanxi province pioneered concentrated botanical extraction infrastructure during the 2010s, establishing the processing clusters now supplying refined fisetin to global formulators. Japan and South Korea subsequently developed dedicated senolytic supplement manufacturing capabilities. European and North American markets now drive regulatory evolution for flavonoid commercialization.
China
Shaanxi extraction corridors anchor global supply of 98% assay fisetin, with Xi'an-based processors leveraging captive smoke tree bark sourcing. NMPA and SAMR jointly supervise GMP compliance through GB standards dictating heavy metal limits. The province's vertical integration from raw material through refined isolate output reduces formulator qualification burden for export-grade flavonoids.
United States
Direct-to-consumer longevity platforms in California and Massachusetts drive demand for capsule-formulated senolytic supplements. FDA New Dietary Ingredient notification requirements create 12-18 month commercialization delays for novel flavonoid entrants. Stanford Chemicals and research-grade suppliers concentrate on synthetic purity grades for pharmaceutical applications.
Japan
Nutraceutical companies in Tokyo and Osaka are expanding procurement of natural extract fisetin for dedicated cellular senescence modulation product lines. METI bioeconomy frameworks support plant-derived ingredient qualification pathways. Continuous chromatography purification adoption is compressing cost structures for natural-extract grades previously requiring synthetic chemistry.
South Korea
Seoul and Busan formulators are testing fisetin antioxidant actives for anti-pollution skincare applications beyond traditional nutraceutical verticals. MFDS cosmetic ingredient regulations govern novel polyphenol deployment in functional beauty channels. Korean nutraceutical brands are building proprietary senolytic stacks combining fisetin with established polyphenol competitors.
Germany
REACH registration requirements for novel botanical extracts are reshaping European commercialization strategy for fisetin suppliers. ECHA evaluation windows are extending timeline pressure for pharmaceutical-grade material destined for research quantities. German formulators face EU Green Deal procurement mandates favoring plant-derived nutraceuticals over synthetic alternatives.
Fisetin Market Competitive Landscape
Capital-heavy extraction specialists compete with asset-light formulation houses across divergent margin structures. The supplier base clusters around three operational models: integrated botanical processors controlling raw material through refined output, synthesis-focused chemical houses serving pharmaceutical research channels, and contract manufacturers delivering finished dosage forms. Strategic differentiation centers on purity certification depth and regulatory dossier compilation speed rather than scale economics alone. Market participants are pursuing backward integration into captive biomass sourcing and geographic expansion into Korean functional beauty channels.
Among China-based extraction specialists, Xi'an SR Bio-Engineering and Lingding Biological exemplify the integrated processor archetype, occupying positions anchored in Shaanxi's botanical processing infrastructure. Stanford Chemicals represents the synthesis-focused tier, serving pharmaceutical research demand where batch consistency outweighs botanical provenance. These three entities illustrate how competitive positioning fragments across provenance preference, purity specification, and end-market regulatory exposure.
| Leading Market Players |
|---|
| Xi'an SR Bio-Engineering |
| AdooQ |
| Stanford Chemicals |
| Nutra Biotechnology |
| Lingding Biological |
| Tocris Bioscience |
| Bio-Techne |
| Santa Cruz Biotechnology |
| Cayman Chemical |
| Others |
Value Network & Pricing Analysis
Japanese and South Korean nutraceutical procurement mandates for 98% assay fisetin with full heavy metal documentation are forcing Shaanxi processors to upgrade purification infrastructure. This specification tightening compresses margins for mid-tier extractors while concentrating pricing power with integrated suppliers capable of captive smoke tree bark sourcing and continuous chromatography output.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and research-catalog tiers dominates fisetin transactions. Price differentiation hinges on purity certification depth and NDI notification support quality, with synthetic 99.5% grades commanding premiums over natural-extract alternatives. Cost compression in nutraceutical-grade supply is intensifying because continuous chromatography adoption is collapsing purification economics. Research institutions exhibit highest price sensitivity; pharmaceutical companies prioritize batch consistency over procurement cost.
Supply Chain Analysis
Smoke tree bark supply rests on China's Shaanxi province, with secondary biomass sourcing from temperate strawberry cultivation regions in the United States and Poland. Rhus verniciflua cultivation, solvent extraction capacity, and chromatography purification hardware constitute critical input dependencies. Single-source vulnerability in Shaanxi extraction corridors exposes global formulators to climate-driven harvest volatility. Distribution runs through contract manufacturing channels in Japan and South Korea for finished senolytic supplements, with bulk isolate moving directly to North American direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fisetin procurement is transitioning toward late-cycle quality concentration as clinical validation of senolytic mechanisms elevates specification requirements above commodity sourcing. Buyers now prioritize suppliers with published safety data and regulatory dossier compilation capability over lowest-unit-cost alternatives.
For Market Incumbents: Deploy backward integration into captive smoke tree bark cultivation to secure biomass supply against climate volatility. Incumbent processors must also accelerate EFSA Novel Food dossier preparation ahead of European formulators' EU Green Deal procurement mandates. Quercetin substitution threats from established polyphenol suppliers with deeper clinical bibliographies demand defensive patent positioning around fisetin-specific senolytic formulations.
For New Entrants and Emerging Players: Launch via Korean functional beauty contract manufacturing channels where MFDS cosmetic ingredient regulations are testing novel polyphenol actives for anti-pollution skincare. White-space opportunity concentrates in topical antioxidant applications beyond traditional nutraceutical verticals. Direct-to-consumer telehealth integration with biomarker testing subscription bundles offers the most penetrable go-to-market angle for capsule-formulated entrants.
For Investors and Strategic Acquirers: Asymmetric upside sits with extraction specialists possessing existing toxicology portfolios and REACH registration progress. Long-term viability in this market depends on regulatory reclassification risk management as senolytic clinical trial readouts could shift fisetin from supplement ingredient to drug precursor status. The signal to watch is Mayo Clinic geroscience center publication velocity around senescence biomarker validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography Scale-Up | Compresses purification economics for natural-extract grades competing with synthetic alternatives. |
| Captive Biomass Cultivation | Secures smoke tree bark supply chains against temperate region climate volatility. |
| EFSA Novel Food Dossier Submission | Unlocks European food-grade applications beyond current supplement capsule formats. |
| Direct-to-Consumer Platform Integration | Captures subscription-based demand through telehealth biomarker testing bundles. |
| Korean Functional Beauty Channel Entry | Tests topical antioxidant positioning against established polyphenol competitors in Seoul formulator networks. |
Research Methodology
Coverage spans China, Japan, South Korea, the United States, and Germany, with primary inputs from each region's extraction specialists and nutraceutical formulators. The study combines interviews with botanical processing plant managers, dietary supplement procurement leads, geroscience laboratory directors, and MFDS regulatory affairs specialists with secondary validation from NMPA filings, FDA NDI notification databases, EFSA Novel Food registers, and customs trade records. Bottom-up volume modeling and top-down value triangulation reconcile procurement patterns across these inputs.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across the projection horizon. The analytical framework models segmentation dimensions including purity grade tier, end-use application, provenance documentation burden, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation moderated by clinical trial publication velocity and regulatory reclassification probability assessments. Forecast inputs incorporate continuous chromatography adoption curves and EU Green Deal procurement mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA NDI pathway friction or ECHA REACH evaluation window extensions. Forecasts reflect assumptions around senolytic clinical validation progress and corresponding regulatory reclassification risks. A small set of named triggers warrants ongoing watch: Mayo Clinic geroscience readouts, EFSA Novel Food authorization decisions, and MFDS cosmetic ingredient regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Protein Water Market