
 Liquid Breakfast Products Market | 2026-2036
Liquid Breakfast Products Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Breakfast Products Market Outlook
Asset-light contract manufacturing and third-party co-packing arrangements are reshaping competitive entry in liquid breakfast products, lowering capital barriers for new brands. General Mills leverages its North American manufacturing scale to dominate ready-to-drink cereal formats. Danone anchors its position through specialized dairy-based protein shake expertise across European retail channels. Nestlé competes via extensive vending machine and convenience store distribution networks in Asia-Pacific markets.
Liquid breakfast products comprise shelf-stable or refrigerated ready-to-drink formulations combining dairy, grains, fruits, or protein isolates, typically processed through UHT treatment or high-pressure processing to achieve 30-180 day stability without preservatives. These products serve time-constrained consumers seeking complete morning nutrition outside traditional sit-down meals. The smoothies segment leads value contribution due to premium positioning and fresh-perception marketing, while protein shakes represent the fastest-expanding category as sports nutrition crosses into mainstream breakfast occasions. Tetra Packs sustain margin pools through lower logistics costs and extended ambient shelf life compared to refrigerated bottles.
FDA nutrition labeling rules and EFSA health claim regulations determine which functional benefits brands may communicate on-pack, directly constraining formulation and marketing strategies. The EU Green Deal packaging directives and emerging extended producer responsibility frameworks in California and New York reshape material choices toward recyclable or biodegradable alternatives. Stakeholders must monitor evolving sugar taxation proposals across multiple jurisdictions and decide whether to reformulate proactively or absorb compliance costs.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing permissible ingredient palettes while UHT and high-pressure processing investments concentrate production capacity among capitalized processors.
Growth Catalysts
- EFSA Clean-Label Standards:Prohibited artificial stabilizers and synthetic vitamins force brands toward recognizable whole-food ingredients, accelerating premium positioning in German and French retail channels.
- On-the-Go Corporate Foodservice:Urban professional demand for desk-consumable nutrition drives volume through workplace canteen contracts and grab-and-go retail formats in Tokyo and New York.
- High-Pressure Processing:Cold-pasteurization technology preserves enzyme activity and fresh taste perception without thermal degradation, enabling 45-day refrigerated shelf life for smoothie formulations.
Market Restraints
- Dairy Protein Input Volatility:Whey and casein isolate prices fluctuate with global milk powder auctions, compressing margin predictability for protein shake specialists dependent on New Zealand and EU supply.
- Tetra Pak Equipment Concentration:Aseptic filling machinery supply concentrates among Swedish and Swiss engineering firms, creating 18-24 month lead times for capacity expansion.
- Sugar Taxation Proposals:Pending legislation in California, New York, and UK Treasury consultations threaten 20-40% excise burdens on sweetened formulations, forcing costly reformulation or price absorption.
Strategic Opportunities
- Underpenetrated Indian Urban Markets:Rising middle-class time scarcity in Mumbai and Bangalore creates first-mover advantage for shelf-stable breakfast formats adapted to local flavor preferences.
- EU Green Deal Packaging Directives:Mandated recyclability timelines reward early adopters of paper-based barrier materials and biodegradable caps, differentiating premium brands in Dutch and Scandinavian retail.
- Sports Nutrition Crossover:Post-workout protein shake consumption is migrating to morning occasions, opening formulation white space between 20g and 30g protein thresholds for mainstream breakfast positioning.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise spanning dairy chemistry, emulsion stability, and clean-label preservation commands premium compensation, constraining R&D throughput for mid-tier brands.
- Extended Producer Responsibility Compliance:California and New York frameworks impose packaging recovery cost obligations requiring new reverse-logistics partnerships and material tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Breakfast Products Market |
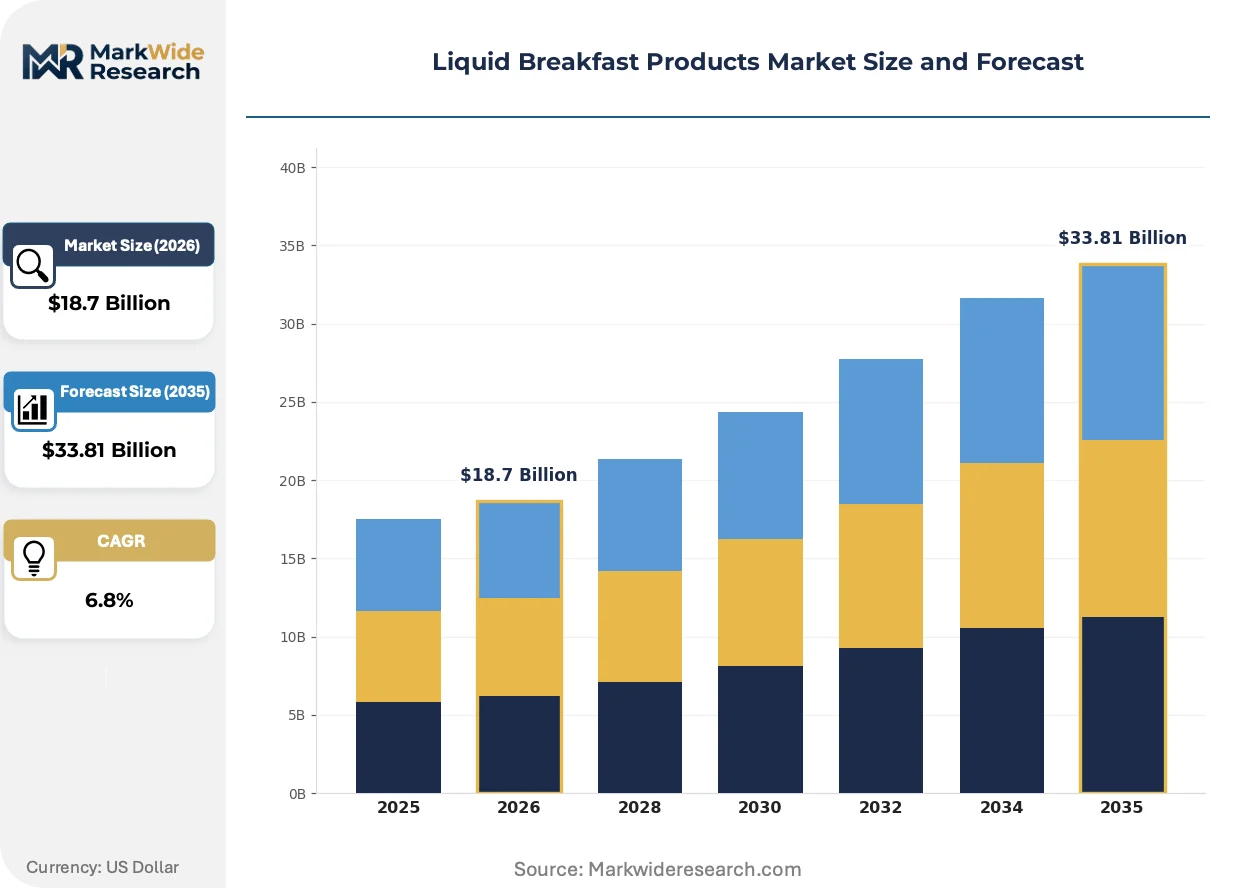
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoothies, Meal Replacements, Protein Shakes, Cold Cereals Ingredients: Fruits, Dairy, Grains, Nutritional Supplements Packaging Type: Bottles, Tetra Packs, Pouches, Cans Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Vending Machines |
| Companies Covered | General Mills, Sanitarium Health & Wellbeing, Nestlé, Quaker Oats Company, Kellogg, Danone, Kraft Heinz, Unilever, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Breakfast Products Market Strategic Shifts
Processing technology convergence and regulatory packaging mandates are reconfiguring production economics while distribution channels fragment toward direct-to-subscription models.
Pulse-based protein isolates from pea, fava, and mung sources are collapsing the cost premium between plant and dairy formulations. Vegan-positioned brands in German and UK markets are capturing price parity with conventional shakes, compressing the historical 40-60% plant-based surcharge. This ingredient shift is collapsing category boundaries between sports nutrition and mainstream breakfast.
EU Green Deal packaging directives and emerging extended producer responsibility frameworks in California are mandating recyclable or biodegradable material transitions by 2030. Aseptic carton manufacturers are accelerating fiber-based barrier development to replace aluminum layers. Refrigerated bottle formats face stranded asset risk as deposit-return schemes expand across German and Nordic retail.
Corporate procurement of liquid breakfast for workplace wellness programs is displacing individual retail purchase in urban centers. Foodservice distributors are bundling breakfast shakes with coffee and snack contracts for technology sector clients in San Francisco and London. This channel pivot concentrates volume among contract catering specialists while eroding traditional grocery velocity for single-serve formats.
Liquid Breakfast Products Market Segmentation
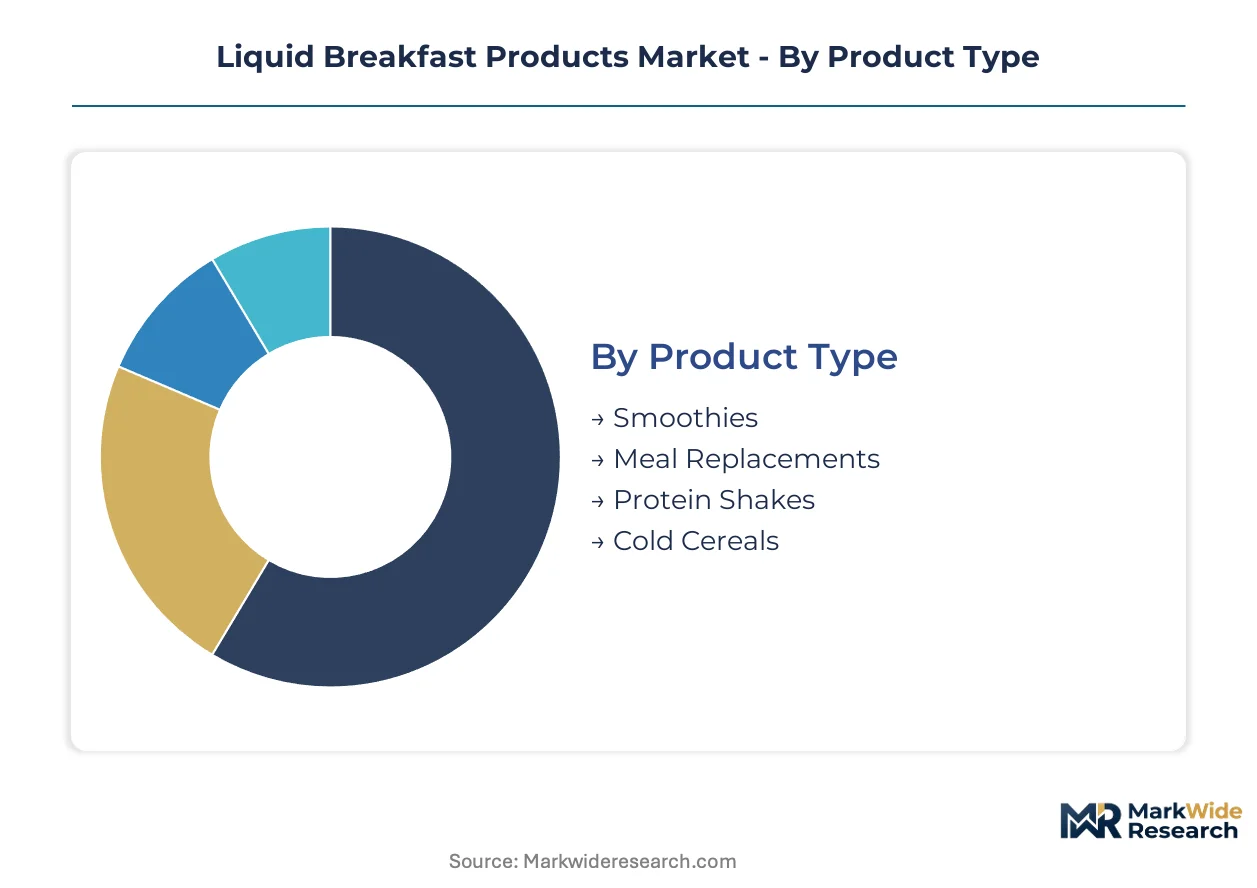
Liquid breakfast products fragment across four distinct classification axes, each reshaping procurement priorities and margin architecture. Product type and packaging format decisions determine shelf-life economics, while ingredient sourcing and channel strategy dictate geographic reach and regulatory exposure.
Product Type:
Inventory velocity varies dramatically across formats, with refrigerated smoothies turning weekly while shelf-stable meal replacements sit for months.
- Smoothies:Blended fruit-dairy or plant-based formulations with 7-14 day refrigerated shelf life. German and French retailers prioritize these for premium positioning, though cold-chain costs compress margins in convenience channels.
- Protein Shakes:Isolated whey, casein, or pulse-protein concentrates delivering 20-40g protein per serving. Post-workout consumption patterns are migrating to morning occasions in Tokyo and New York, expanding addressable demand.
- Meal Replacements:Complete macronutrient formulations targeting 400-600 calorie breakfast substitution. Extended ambient stability suits Indian and Brazilian distribution infrastructure.
- Cold Cereals:Ready-to-drink grain suspensions requiring continuous refrigeration. Limited to developed-market cold-chain density.
Smoothies anchor the volume base while protein shakes gain share at the steepest rate.
Ingredients:
Input cost structures stratify sharply, with dairy proteins tracking global commodity auctions while fruit concentrates offer more predictable sourcing.
- Fruits:Purees, concentrates, and NFC juices from tropical and temperate sources. Clean-label mandates from EFSA are accelerating whole-fruit formulation in European retail.
- Dairy:Milk, whey isolates, and fermented bases. New Zealand and EU supply concentration creates margin vulnerability for protein shake specialists.
- Grains:Oat, rice, and ancient grain suspensions. Rising demand in Scandinavian markets for fiber-forward positioning.
- Nutritional Supplements:Vitamin premixes, mineral fortificants, and adaptogenic additives. FDA nutrition labeling rules constrain permissible health claims on-pack.
Dairy inputs dominate current formulation volumes, though fruit-based alternatives are climbing fastest in premium positioning.
Packaging Type:
Capital intensity and logistics economics diverge substantially, with aseptic cartons demanding specialized equipment while bottles leverage existing bottling infrastructure.
- Tetra Packs:Multi-layer aseptic cartons enabling 6-12 month ambient stability. Lower logistics costs and extended shelf life sustain margin pools in German and Japanese retail.
- Bottles:PET or HDPE formats for refrigerated distribution. Facing stranded asset risk as deposit-return schemes expand across Nordic markets.
- Pouches:Flexible films for single-serve portions. Growing traction in Indian urban markets for affordability and portability.
- Cans:Aluminum formats for carbonated or nitrogen-flushed products. Limited adoption outside experimental premium positioning.
Tetra Packs command the installed production base while pouches expand most quickly in emerging-market penetration.
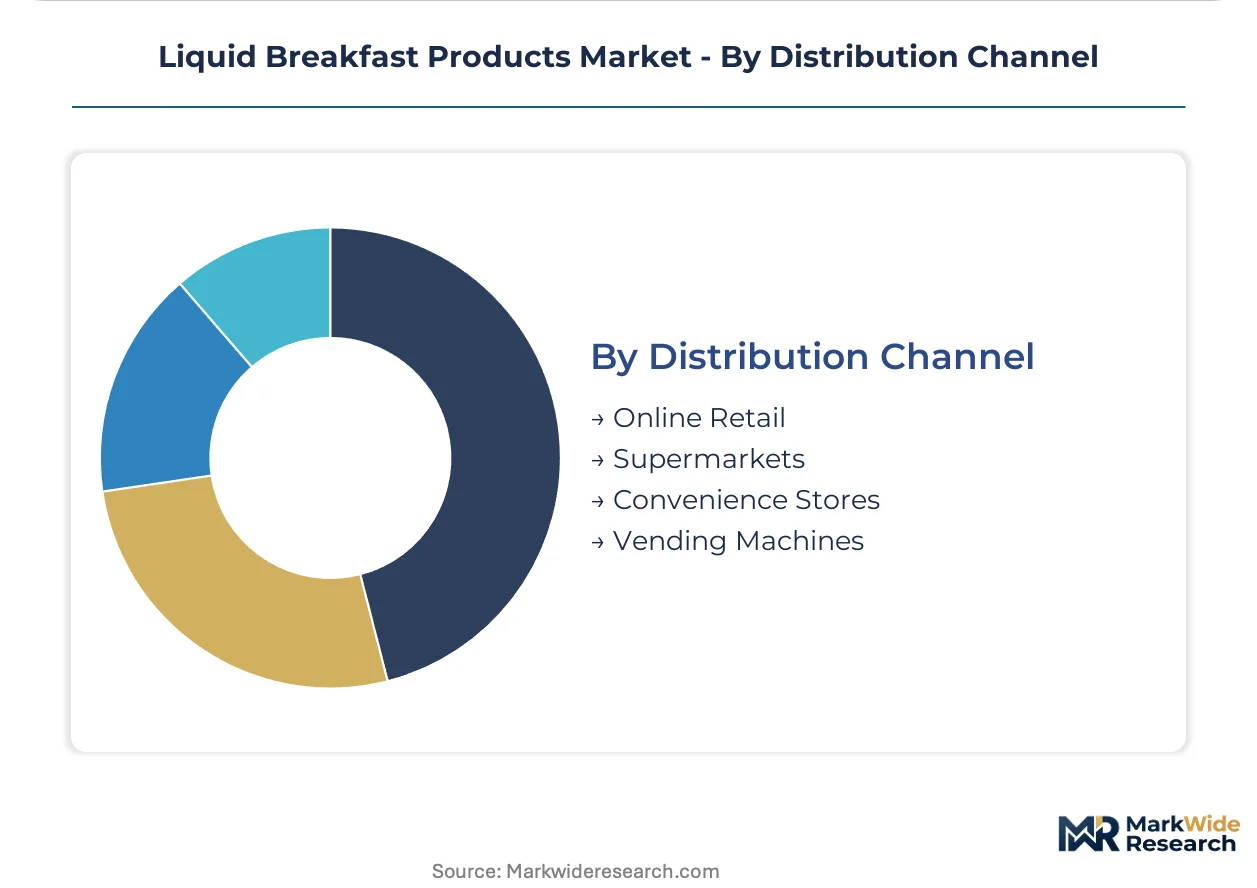
Distribution Channel:
Channel economics are fragmenting as corporate procurement displaces individual retail purchase in major metropolitan clusters.
- Supermarkets:Multi-brand shelf space with promotional velocity driving placement. Eroding share in urban centers as convenience formats capture time-scarce consumers.
- Convenience Stores:Grab-and-go refrigeration with premium pricing tolerance. Critical volume driver in Tokyo, New York, and London corporate districts.
- Online Retail:Subscription models and direct-to-consumer fulfillment. Enabling challenger brand entry without retail slotting fee barriers.
- Vending Machines:Chilled automated retail in workplaces and transit hubs. Concentrating volume among contract catering specialists in San Francisco and London technology corridors.
Supermarkets retain the broadest volume footprint, though vending and corporate foodservice channels are climbing fastest in urban professional penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retailers command 15-20% price premiums over Indian equivalents for comparable protein shake formulations, reflecting cold-chain infrastructure gaps and import tariff structures that compress margin pools in emerging markets.
Germany
Workplace canteen contracts and REWE Group shelf-space allocations drive volume for ambient-stable formats. EFSA clean-label enforcement accelerates whole-fruit formulation migration. Bavarian dairy processors in Munich supply whey isolates to shake specialists.
United States
Corporate wellness procurement through Aramark and Compass Group displaces individual retail purchase in Manhattan and San Francisco corridors. FDA nutrition labeling rules constrain permissible protein-content claims. Chicago-area co-packers concentrate aseptic filling capacity for challenger brands.
Japan
Convenience store refrigeration density in Tokyo and Osaka enables premium smoothie positioning at Lawson and 7-Eleven outlets. METI packaging directives mandate 2030 recyclability timelines. Kanto-region vending machine operators expand chilled automated retail in transit hubs.
India
Middle-class time scarcity in Mumbai and Bangalore creates first-mover opportunity for shelf-stable breakfast formats. FSSAI fortification guidelines determine permissible vitamin premix additions. Gujarat dairy cooperatives supply cost-competitive milk protein bases to formulation houses.
United Kingdom
Tesco and Sainsbury's promotional velocity determines placement economics for meal-replacement lines. Treasury sugar-tax consultations threaten excise burdens on sweetened formulations. London contract caterers bundle breakfast shakes with coffee service for technology sector clients.
Liquid Breakfast Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and co-manufacturing services. The vendor base concentrates among five multinational food conglomerates with dairy processing heritage and refrigerated distribution infrastructure. Strategic archetypes include: diversified nutrition conglomerates leveraging cross-category R&D spillover; dairy-centric specialists anchoring protein shake expertise; and beverage-platform operators exploiting vending and convenience store channels. Dominant competitive moves center on asset-light co-packing partnerships to bypass capital-intensive aseptic filling investments, and backward integration into whey isolate processing to secure margin pools against dairy commodity volatility.
Within the diversified conglomerate tier, General Mills and Nestlé occupy positions spanning cereal-derived and dairy-based format expertise. Danone exemplifies the dairy-specialist archetype with concentrated capabilities in fermented protein systems. These three entities anchor competitive dynamics through distinct channel strategies: General Mills through North American retail scale, Nestlé through Asia-Pacific vending penetration, and Danone through European pharmacy and health-store positioning.
| Leading Market Players |
|---|
| General Mills |
| Sanitarium Health & Wellbeing |
| Nestlé |
| Quaker Oats Company |
| Kellogg |
| Danone |
| Kraft Heinz |
| Unilever |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Munich's Bavarian dairy processing cluster anchors European whey isolate supply, concentrating margin capture among German protein shake specialists while downstream brands absorb commodity volatility through long-term offtake contracts. This geographic concentration of dairy chemistry expertise translates directly into pricing power for UHT-treated formulations across German and French retail channels.
Pricing Analysis
The customization-premium spread between configured-to-order contract catering formulations and standard retail SKUs spans roughly 35-45% at the unit level. Three-tier pricing structure across premium, standard, and economy levels tracks ingredient sourcing tiers, with clean-label whole-fruit formulations commanding the top tier and commodity dairy-based products occupying the base. Pricing pressure stems from pending sugar taxation consultations in California and the UK Treasury, forcing reformulation costs onto manufacturers or absorption into already-thin convenience channel margins. Corporate foodservice buyers in Manhattan and San Francisco technology corridors exhibit the lowest price sensitivity due to bundled wellness program budgets, while Indian urban consumers in Mumbai remain highly sensitive to per-unit pricing and favor pouch formats.
Supply Chain Analysis
Export-control regimes on high-pressure processing equipment from Swiss and Swedish engineering firms constrain capacity expansion timelines for cold-pasteurization technology, limiting supply growth for premium smoothie formulations. Geographic supply concentration centers on New Zealand and EU dairy cooperatives for whey and casein isolates, with Gujarat dairy collectives emerging as cost-competitive alternatives for Indian market production. Raw material dependencies include tropical fruit purees from Southeast Asian processors, aluminum-layer barrier films facing EU Green Deal phaseout mandates, and pulse-based protein isolates from Canadian and Ukrainian pea processing facilities. Single-source vulnerability concentrates in aseptic filling machinery supply, where 18-24 month equipment lead times create bottlenecks for challenger brand expansion. Distribution runs through foodservice distributors bundling breakfast shakes with coffee contracts in corporate corridors, displacing traditional supermarket velocity in urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid breakfast products sit in early-cycle expansion as sports nutrition consumption migrates to morning occasions and workplace wellness procurement displaces individual retail purchase in major metropolitan clusters.
For Market Incumbents: Harden clean-label formulation capabilities ahead of EFSA enforcement timelines to preempt challenger brand entry in German and French pharmacy channels. Deepen backward integration into whey isolate processing to secure margin pools against New Zealand dairy auction volatility, while expanding co-packing partnerships to service corporate foodservice contracts without capital-intensive aseptic filling investments. For New Entrants and Emerging Players: Shelf-stable meal replacement formats in Indian urban markets represent the most penetrable entry point, with Mumbai and Bangalore middle-class time scarcity creating first-mover advantage for localized flavor adaptations. Direct-to-subscription models bypass retail slotting fee barriers while capturing recurring revenue from time-constrained professionals, with corporate wellness procurement bundling offering the most efficient customer acquisition pathway in London and San Francisco technology corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core beverage assets, particularly refrigerated distribution networks with established convenience store placement in Tokyo and Osaka. Long-term viability hinges on regulatory compliance infrastructure for extended producer responsibility frameworks and clean-label certification pathways. The signal to watch is acceleration in corporate procurement contract velocity relative to individual retail scan data, indicating channel mix inflection toward higher-margin foodservice volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA enforcement timelines in German retail accelerate whole-fruit migration ahead of synthetic additive prohibitions. |
| Backward Integration into Whey Processing | Captive supply of dairy isolates insulates margin pools from New Zealand commodity auction volatility. |
| Corporate Foodservice Contracting | Workplace wellness procurement through Aramark and Compass Group displaces individual retail purchase in urban corridors. |
| Pulse-Protein Formulation Expansion | Pea and fava isolate adoption collapses the 40-60% plant-based surcharge toward price parity with conventional shakes. |
| Biodegradable Packaging Transition | EU Green Deal recyclability mandates reward early fiber-based barrier adoption in Dutch and Scandinavian retail channels. |
Study Parameters
A spread of perspectives from brand managers at multinational food conglomerates, category buyers at REWE Group and Tesco, supply planners at Bavarian dairy processors, and channel sales heads at foodservice distributors converged on the working assumptions. Primary interviews combined with secondary validation from FSSAI fortification guidelines, FDA nutrition labeling rules, EFSA clean-label enforcement documentation, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, ingredient sourcing tier, packaging format, and distribution channel, with regional regulatory clusters overlaying geographic variation. CAGRs derived from trend extrapolation of historical adoption curves, adjusted for channel mix shifts toward corporate procurement. Industry-specific forecast inputs incorporated dairy commodity auction price trajectories and high-pressure processing equipment installation pipelines.
Practitioners should monitor sugar taxation legislative progress, EFSA additive prohibition timelines, and corporate wellness procurement contract announcements for early signals of forecast deviation. Forecasts reflect assumptions regarding clean-label migration rates and cold-chain infrastructure expansion in emerging markets. Material shifts in dairy protein input costs or abrupt regulatory enforcement acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Tobacco Alternative Gum Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Zero-Fat Protein Market