
 Functional Coffee Market | 2026-2036
Functional Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Coffee Market Analysis
Precision fermentation and adaptogen extraction is rewriting how functional coffee achieves bioactive consistency at scale. Nestle S.A. leverages its global R&D network to standardize mushroom-derived compound profiles across batches. Bulletproof 360, Inc. sustains brand authority through in-house MCT oil sourcing and ketogenic positioning. Four Sigma Foods, Inc. specializes in dual-extract lion's mane and chaga integration for cognitive positioning.
Functional coffee denotes roasted or instant coffee matrices fortified with bioactive compounds including adaptogenic mushrooms, nootropic amino acids, hydrolyzed collagen, or plant proteins, processed through spray-drying or low-temperature extraction to preserve thermolabile actives. Its primary commercial purpose is to deliver targeted physiological outcomes—cognitive enhancement, stress modulation, or protein supplementation—beyond caffeine stimulation. Mushroom Blends command premium shelf positioning due to dual-extract processing costs and limited raw material suppliers. Ready-to-drink formats attract the fastest volume growth as convenience-oriented working professionals bypass brewing rituals. Online Retail channels capture disproportionate margin pools through direct-to-consumer subscription models that reduce intermediary markups.
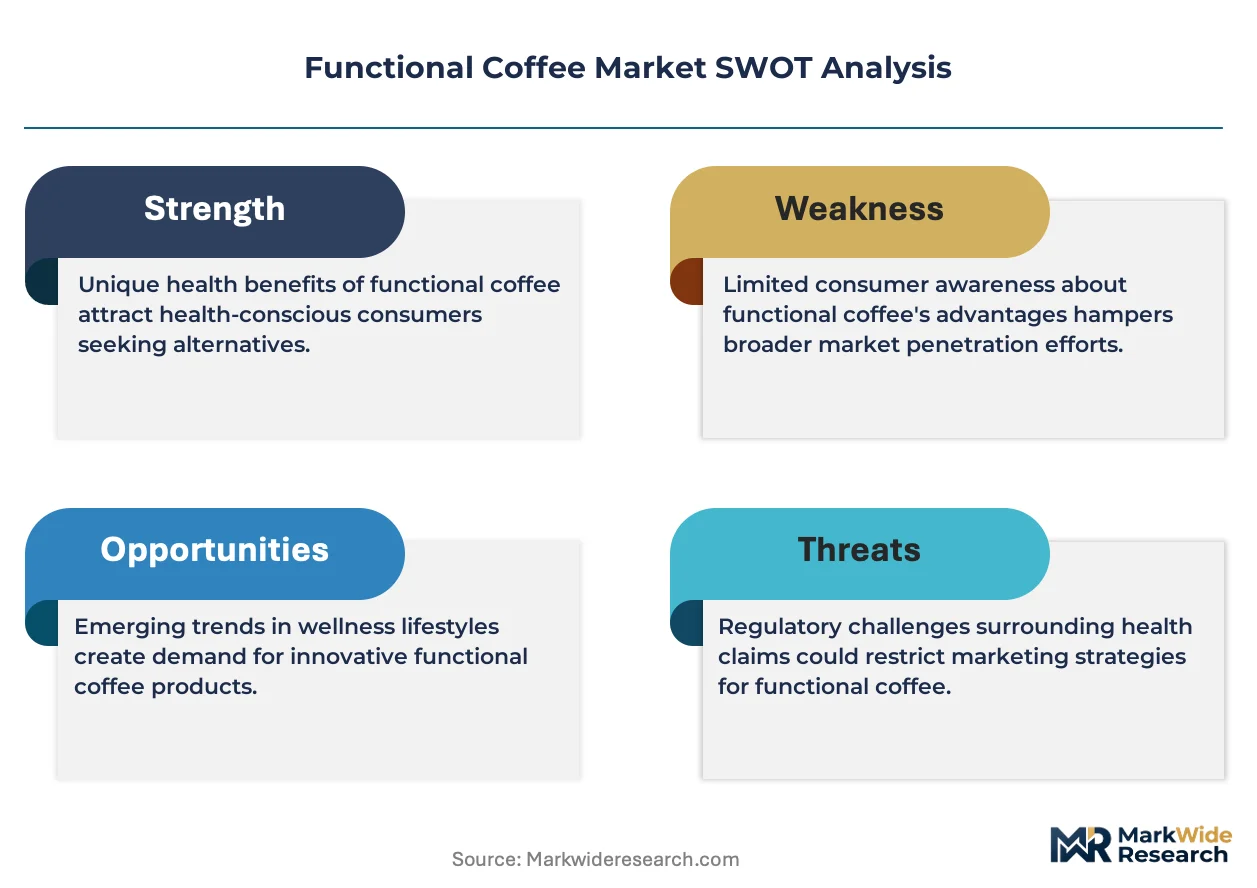
The FDA exercises oversight through GRAS self-affirmation requirements and New Dietary Ingredient notifications for adaptogenic additives, while the USDA governs organic certification claims on functional coffee labels. The FTC monitors substantiation of cognitive and performance claims in direct-to-consumer advertising, pressuring brands to invest in clinical validation. EFSA's novel food assessments in Europe create parallel compliance burdens for exporters seeking cross-border market access. Stakeholders must monitor regulatory divergence between permissive self-affirmation frameworks and precautionary approval systems as they scale multi-territory distribution.
Market Dynamics
Precision fermentation infrastructure is compressing batch-to-batch variability in adaptogen extraction, forcing legacy spray-drying operations to retool for thermolabile compound preservation or surrender premium shelf positioning to biotech-enabled competitors.
Growth Catalysts
- Corporate Wellness Mandates:United States employers are subsidizing functional beverage programs as tax-advantaged perks under IRS Section 125 cafeteria plans, channeling payroll dollars into adaptogen-fortified coffee subscriptions.
- Dual-Extract Processing Advances:Low-temperature ethanol and hot-water sequential extraction protocols now yield standardized beta-glucan and triterpene profiles from lion's mane and chaga substrates.
- FDA GRAS Self-Affirmation Pathway:The permissive regulatory framework for novel dietary ingredients accelerates formulation iterations without pre-market approval delays, compressing product development cycles.
Market Restraints
- Raw Material Concentration:Certified organic mushroom substrate suppliers cluster in Pacific Northwest growing regions, creating geographic single-point vulnerability for dual-extract processors.
- Thermolabile Degradation:Conventional roasting temperatures above 205°C destroy L-theanine and heat-sensitive triterpenes, forcing costly process reengineering.
- Substitution by Energy Drinks:Ready-to-drink nootropic beverages with synthetic caffeine and B-vitamin complexes capture price-sensitive cognitive enhancement seekers.
Strategic Opportunities
- Underpenetrated German Market:EFSA novel food assessments have historically delayed adaptogen introduction, but recent regulatory guidance clarity opens pathway for mushroom-coffee hybrids.
- Protein-Fortified Positioning:Hydrolyzed collagen and pea protein integration targets fitness-oriented consumers seeking post-workout recovery matrices beyond standard caffeine delivery.
- Direct-to-Consumer Subscription Models:Online retail channels bypass specialty coffee intermediary markups, capturing margin pools previously allocated to brick-and-mortar distributors.
Industry Challenges
- Clinical Validation Requirements:FTC substantiation rules for cognitive and stress-modulation claims demand peer-reviewed trials, stretching R&D budgets for mid-tier brands.
- Cross-Border Compliance Complexity:Divergent GRAS self-affirmation in the United States versus EFSA precautionary approval systems forces dual regulatory track investments for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Coffee Market |
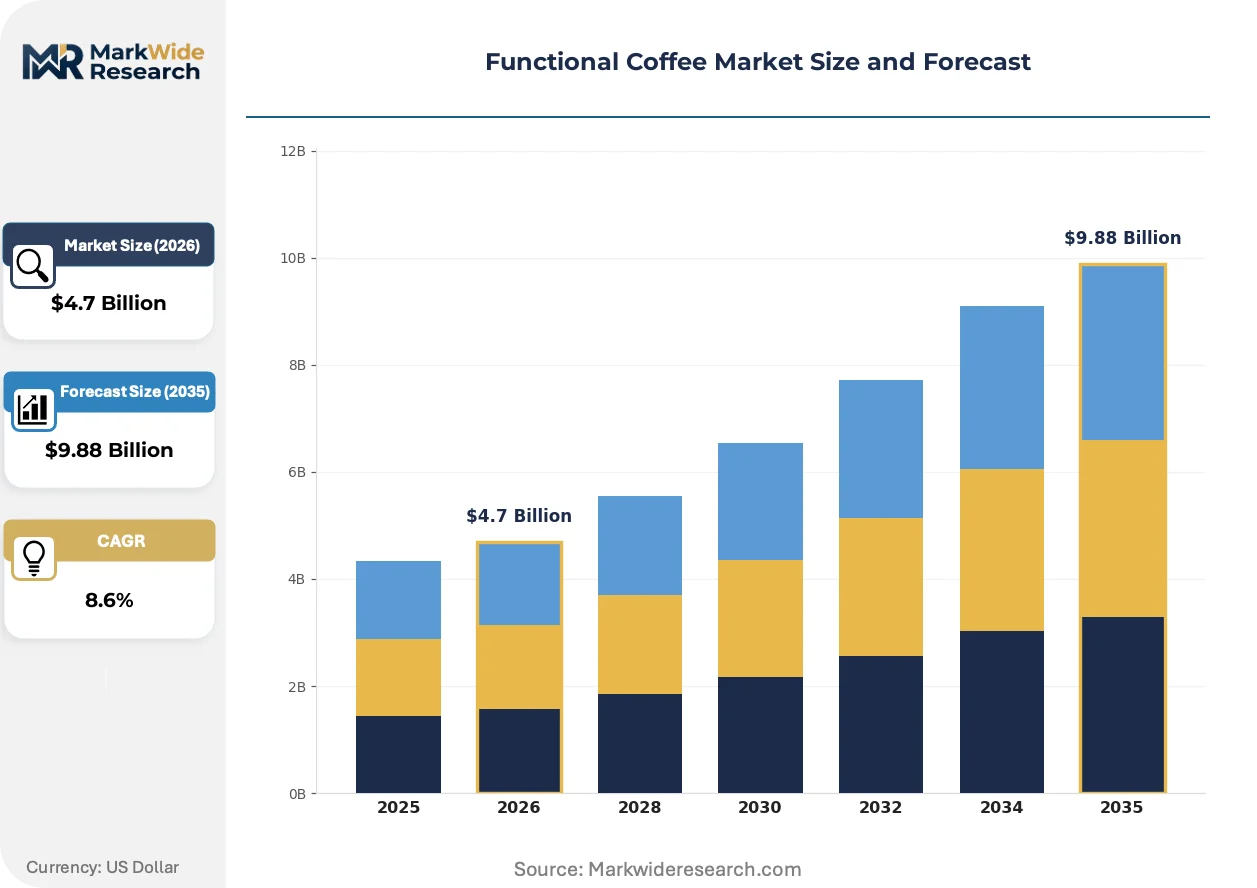
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Infusions, Protein-enriched, Mushroom Blends, Energy Boosters Target Audience: Health Enthusiasts, Athletes, Working Professionals, Students Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafés Consumption Format: Ready-to-drink, Ground Coffee, Pods, Instant Coffee |
| Companies Covered | Starbucks Corporation, Berner Food and Beverage LLC, Nestle S.A., Beforeyouspeak Coffee, Peak State, Bulletproof 360, Inc., Tata Coffee Ltd., Hi!Coffee, Four Sigma Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Coffee Market Emerging Trajectories
Bioprocessing convergence with beverage formulation is collapsing the traditional separation between agricultural commodity roasting and pharmaceutical-grade compound standardization.
Precision fermentation is hybridizing functional coffee manufacturing by enabling biosynthesis of rare adaptogenic molecules previously extractable only from wild-harvested fungal biomass. Venture-backed biotech firms now license standardized compound libraries to roasters, compressing raw material lead times from seasonal harvest cycles to bioreactor batch schedules. This shift is collapsing premium pricing power held by limited wild-foraged suppliers.
EFSA novel food assessments in Europe are tightening evidentiary requirements for mushroom-derived ingredients, forcing exporters to commission 90-day toxicology studies previously unnecessary under FDA frameworks. The industrial consequence is a bifurcation between US-first launch strategies and delayed European market entry. Ready-to-drink formats face the steepest compliance burdens due to higher per-serving bioactive concentrations.
Subscription-based replenishment cycles are displacing traditional grocery channel purchasing among urban working professionals, with automated reorder algorithms keyed to consumption velocity data. Specialty coffee retailers are responding by unbundling brewing equipment from consumable sales, pivoting to recurring revenue models. This behavioral shift concentrates most visibly in United States metropolitan corridors with dense corporate wellness program penetration.
Functional Coffee Market Segmentation
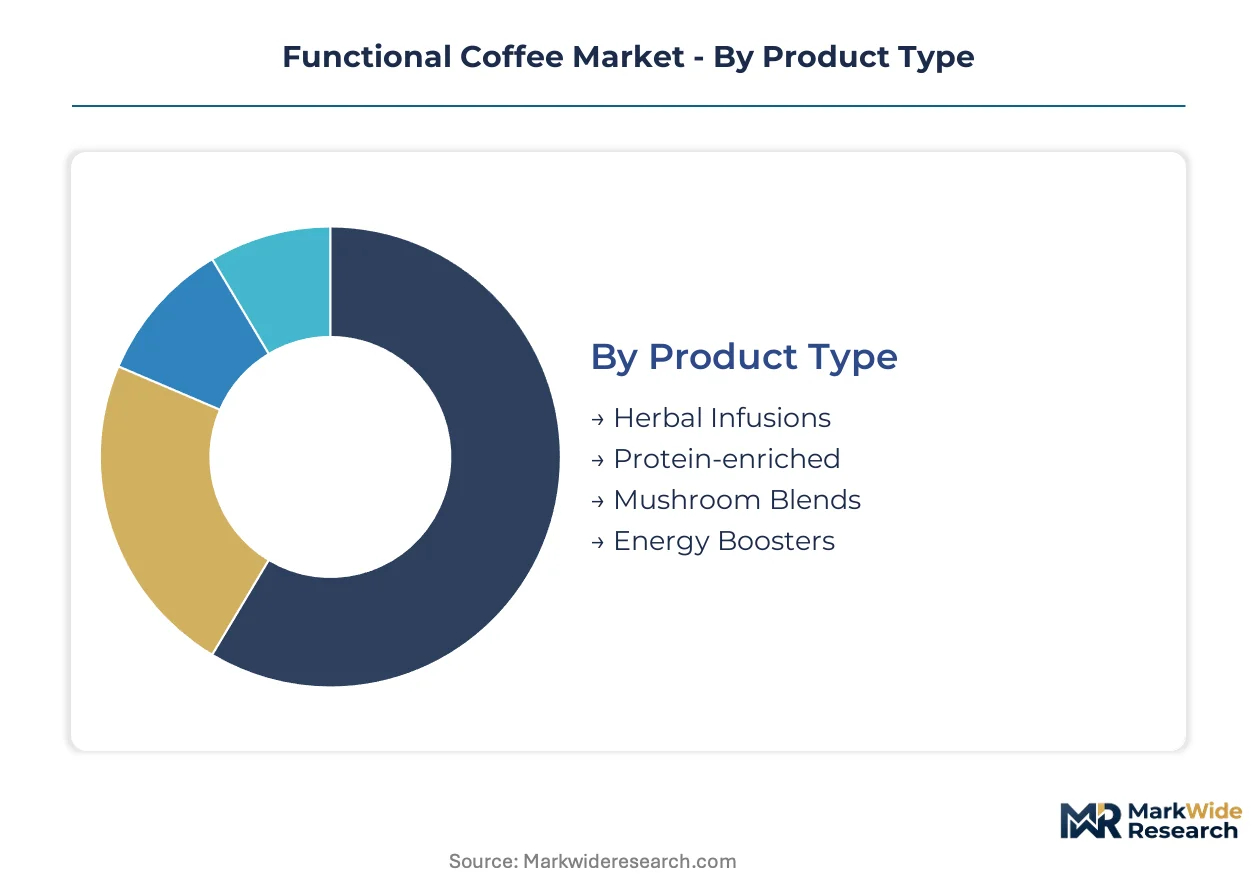
Functional coffee segmentation reveals divergent technical requirements across bioactive delivery formats and consumer ritual preferences. Each dimension carries distinct margin structures, regulatory exposure, and supply chain complexity that shape competitive positioning.
Product Type:
Mature roasting infrastructure collides with emerging bioprocessing capabilities across this spectrum, creating tiered barriers to entry.
- Mushroom Blends:Dual-extract lion's mane and chaga formulations require sequential ethanol and hot-water processing to preserve beta-glucan and triterpene integrity. Demand concentrates among United States corporate wellness programs seeking IRS Section 125 tax-advantaged cognitive enhancement perks.
- Protein-enriched:Hydrolyzed collagen and pea protein integration targets post-workout recovery matrices, demanding low-temperature spray-drying below 180°C to prevent amino acid denaturation. Fitness-oriented consumers in metropolitan United States corridors drive subscription velocity through direct-to-consumer channels.
- Herbal Infusions:Adaptogenic botanicals such as ashwagandha and rhodiola require GRAS self-affirmation documentation under FDA frameworks.
- Energy Boosters:Synthetic caffeine-B-vitamin complexes compete on price against natural nootropic positioning.
Mushroom Blends retain volume leadership; Protein-enriched holds the steepest expansion curve.
Target Audience:
Customer archetypes stratify by ritual complexity tolerance and price elasticity for bioactive standardization.
- Working Professionals:Convenience-driven subscription adopters prioritize ready-to-drink formats with automated replenishment keyed to consumption velocity data. United States urban corridors with dense employer-sponsored wellness programs concentrate demand.
- Health Enthusiasts:Quality-sensitive buyers demand third-party organic certification and dual-extract processing transparency, accepting premium pricing for batch-level compound standardization.
- Athletes:Protein-fortified positioning attracts post-workout recovery seekers seeking caffeine-protein synergy.
- Students:Price-sensitive cognitive enhancement seekers face substitution pressure from synthetic nootropic beverages.
Working Professionals dominate current revenue; Health Enthusiasts command the highest per-unit margins.
Distribution Channel:
Channel economics diverge sharply between recurring revenue capture and intermediary margin surrender.
- Online Retail:Direct-to-consumer subscription models bypass specialty coffee distributor markups, capturing margin pools previously allocated to brick-and-mortar intermediaries. Automated reorder algorithms reduce customer acquisition costs for United States brands with established replenishment data.
- Specialty Stores:Premium shelf positioning depends on dual-extract processing credentials and third-party organic certification visibility.
- Supermarkets:Mass-market penetration requires price compression that conflicts with bioactive standardization costs.
- Cafés:On-premise consumption rituals face competition from at-home brewing equipment unbundling.
Online Retail expands most quickly; Specialty Stores maintain premium price realization.
Consumption Format:
Format selection dictates thermolabile compound preservation requirements and regulatory compliance burden intensity.
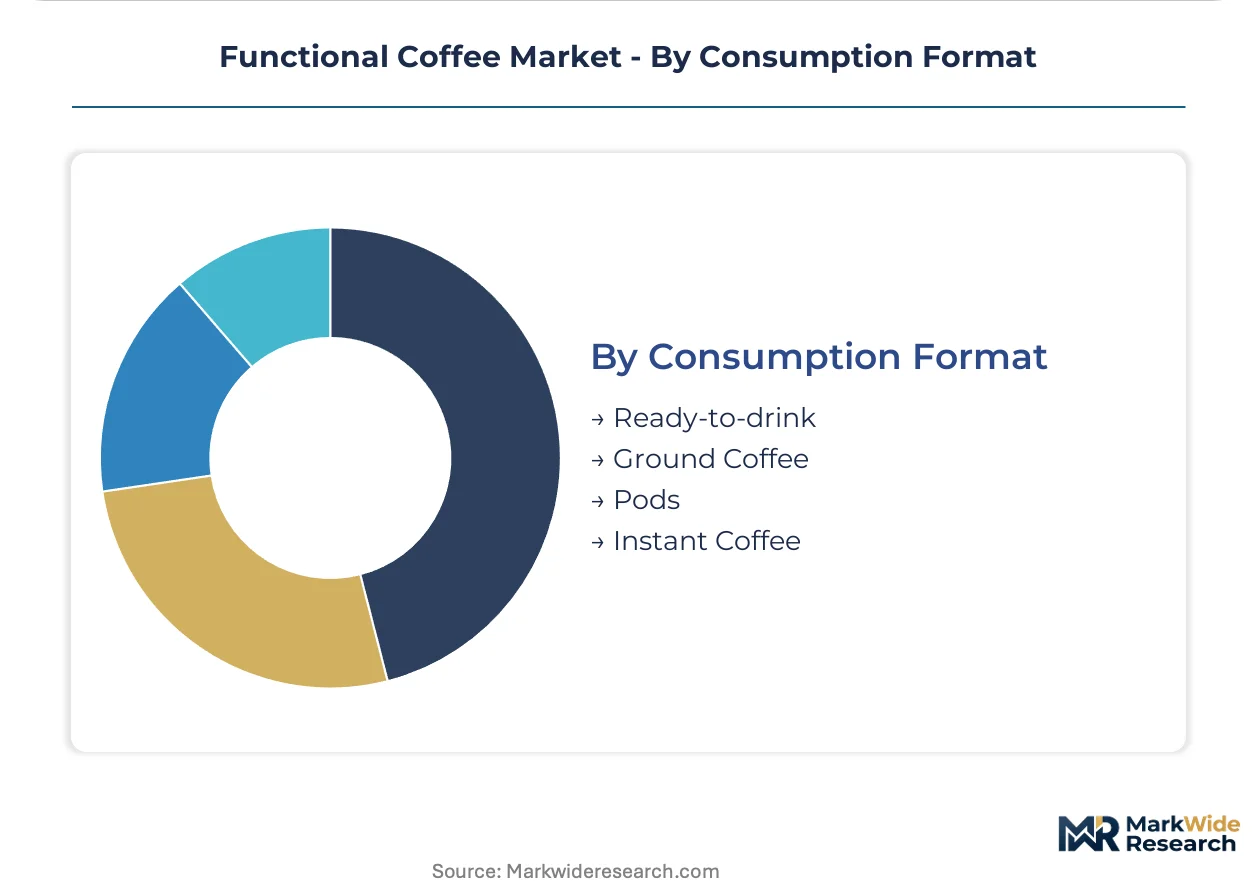
- Ready-to-drink:Higher per-serving bioactive concentrations attract the steepest EFSA novel food assessment burdens in Europe, delaying cross-border market entry. United States convenience-oriented professionals bypass brewing rituals entirely.
- Ground Coffee:Traditional roasting above 205°C destroys L-theanine and heat-sensitive triterpenes, forcing costly process reengineering for functional positioning.
- Pods:Single-serve convenience aligns with office consumption patterns but generates sustainability scrutiny.
- Instant Coffee:Spray-dried matrices enable global distribution but sacrifice compound potency through thermal degradation.
Ready-to-drink gains share fastest; Ground Coffee retains ritual-loyal volume bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional coffee supply chains route through Pacific Northwest extraction facilities into United States corporate distribution networks, with secondary flows reaching European wellness retailers through Rotterdam and Hamburg logistics hubs.
United States
Employer-sponsored wellness programs under IRS Section 125 cafeteria plans channel payroll dollars into adaptogen-fortified subscriptions. The FDA exercises GRAS self-affirmation oversight for novel dietary ingredients. Seattle and Portland extraction clusters process dual-extract lion's mane for cognitive positioning brands.
Germany
Recent EFSA novel food assessment guidance clarity opens pathways for mushroom-coffee hybrids previously delayed by precautionary approval systems. The Federal Office of Consumer Protection and Food Safety enforces novel food compliance documentation. Berlin and Munich specialty retailers pilot protein-enriched functional formats for fitness-oriented professionals.
United Kingdom
Corporate wellness tax incentives mirror United States structures, driving subscription adoption among London financial services employers. The Food Standards Agency coordinates with EFSA on novel food dossier requirements. Manchester and Birmingham direct-to-consumer brands leverage automated replenishment algorithms keyed to consumption velocity data.
Canada
Health Canada and PMRA regulate natural health product claims on functional coffee labels, creating parallel substantiation requirements to FDA frameworks. The Prairie Provinces supply organic mushroom substrate for Pacific Northwest processors. Toronto and Vancouver urban corridors concentrate ready-to-drink format demand among convenience-oriented professionals.
Australia
TGA therapeutic goods classifications apply to adaptogenic claims exceeding general food positioning, compressing formulation flexibility. New South Wales and Victoria roasting facilities retool for low-temperature processing to preserve thermolabile compounds. Sydney and Melbourne specialty coffee retailers unbundle brewing equipment from consumable sales to capture recurring revenue.
Functional Coffee Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base stratifies between multinational beverage conglomerates with R&D networks and venture-backed biotech-enabled challengers with precision fermentation capabilities. Three archetypes dominate: scale-driven commodity roasters, dual-extract processing specialists, and direct-to-consumer subscription operators. Capacity expansion in low-temperature extraction infrastructure and strategic licensing of biosynthesized compound libraries represent the primary competitive vectors.
Among Swiss-based conglomerates, Nestle S.A. occupies a position exemplifying scale-driven R&D standardization. Bulletproof 360, Inc. and Four Sigma Foods, Inc. anchor the specialist tier, representing archetypes focused on ketogenic positioning and mushroom-derived cognitive formulations respectively. These named entities illustrate how geographic origin and stated specializations segment competitive positioning without guaranteeing specific strategic outcomes.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Berner Food and Beverage LLC |
| Nestle S.A. |
| Beforeyouspeak Coffee |
| Peak State |
| Bulletproof 360, Inc. |
| Tata Coffee Ltd. |
| Hi!Coffee |
| Four Sigma Foods, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Pacific Northwest dual-extract processing facilities is compressing supplier margins while amplifying pricing power for certified organic mushroom substrate holders, forcing roasters to absorb premium feedstock costs or surrender volume to biotech-enabled competitors with precision fermentation alternatives.
Pricing Analysis
Prior-generation spray-dried instant formats trade at commodity coffee price points, current-generation ground functional coffee with dual-extract credentials commands 40-60% premiums, and next-generation precision-fermented biosynthetic adaptogens threaten to collapse wild-harvested premium structures entirely. Three-tier pricing structure across premium, standard, and economy levels separates GRAS-documented mushroom blends from generic herbal infusions from conventional energy boosters. Pricing pressure stems from synthetic nootropic beverage substitution in student and price-sensitive professional segments. Corporate wellness program buyers exhibit lowest price sensitivity; convenience-oriented ready-to-drink purchasers face highest elasticity.
Supply Chain Analysis
Certified organic lion's mane and chaga substrate concentrates in United States Pacific Northwest growing regions, with secondary sourcing from Canadian Prairie Provinces and emerging cultivation in Germany. Dual-extract processing draws from ethanol and hot-water extraction equipment, low-temperature spray-drying infrastructure, and GRAS self-affirmation documentation services. Single-source vulnerability in Pacific Northwest substrate supply creates geographic concentration risk during climate-induced harvest variability. Distribution runs through direct-to-consumer subscription platforms, specialty retail channels, and corporate wellness program procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional coffee is cycling through a recovery phase as employer-sponsored wellness program adoption rebounds from pandemic-era remote work disruptions, with IRS Section 125 cafeteria plan utilization serving as the cyclical demand driver.
For Market Incumbents: Pre-empt precision fermentation commoditization by locking multi-year contracts with Pacific Northwest substrate suppliers before biotech alternatives achieve cost parity. Secure GRAS self-affirmation documentation for novel adaptogenic formulations ahead of FTC substantiation rule tightening. Vertical integration into low-temperature extraction infrastructure defends margin position against toll-processing dependency. For New Entrants and Emerging Players: Establish a beachhead in German specialty retail channels where recent EFSA novel food guidance clarity has opened white-space for mushroom-coffee hybrids previously blocked by precautionary approval delays. Target protein-enriched positioning for fitness-oriented professionals in underpenetrated metropolitan corridors. Deploy direct-to-consumer subscription models with automated replenishment algorithms to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation-enabled bioprocessing as venture-backed firms license standardized compound libraries rather than build captive extraction infrastructure. Five-to-ten year viability favors hybrid models combining agricultural substrate sourcing with biosynthetic supplementation. Acquisition targets should demonstrate dual-extract processing credentials paired with subscription revenue concentration. Monitor FDA novel dietary ingredient notification volumes as inflection signal for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Extract Processing Certification | GRAS self-affirmation documentation unlocks premium shelf positioning in United States specialty retail channels. |
| Precision Fermentation Licensing | Biosynthetic adaptogen libraries collapse raw material lead times from seasonal harvests to bioreactor batch schedules. |
| Corporate Wellness Program Integration | IRS Section 125 cafeteria plan eligibility channels payroll dollars into recurring subscription revenue streams. |
| Direct-to-Consumer Subscription Buildout | Automated replenishment algorithms reduce customer acquisition costs and capture margin pools from brick-and-mortar intermediaries. |
| EFSA Novel Food Dossier Investment | 90-day toxicology studies enable European market entry for ready-to-drink formats with higher bioactive concentrations. |
Methodological Framework
Cross-validation between primary interviews with functional coffee brand managers, dual-extract processing facility operators, and corporate wellness program procurement directors anchors the qualitative findings against secondary validation from FDA GRAS notification databases, EFSA novel food assessment registers, and IRS Section 125 cafeteria plan utilization disclosures. Bottom-up triangulation aggregates segment-level subscription velocity data, extraction capacity utilization rates, and raw material spot pricing; top-down verification cross-checks against functional beverage category retail audit data and employer-sponsored wellness program penetration statistics.
Calibration against historical CAGRs in adjacent functional beverage categories informs the projection framework across the analysis window, with segmentation modeling spanning product type, target audience archetype, distribution channel economics, and consumption format thermolability requirements. CAGRs derive from regression analysis of subscription growth velocities, extraction capacity expansion announcements, and regulatory approval timeline distributions. Forecast inputs incorporate precision fermentation technology adoption curves and EFSA novel food assessment backlog clearance rates.
Macroeconomic conditions sit as an overlay; deviation in employer wellness program tax incentive policy or Pacific Northwest agricultural labor availability would shift the trajectory. Forecasts reflect documented assumptions regarding GRAS self-affirmation pathway continuity and EFSA regulatory guidance stability. Cross-checking against functional beverage industry association membership growth and venture capital flow into precision fermentation startups is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market