
 Functional Beverage Market | 2026-2036
Functional Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Beverage Market Intelligence
The EU's Farm to Fork Strategy is realigning cost-of-entry calculus for functional beverage manufacturers by tightening additive transparency and sustainable sourcing mandates. Danone S.A. leverages its probiotic fermentation infrastructure to anchor European market positioning. PepsiCo Inc. sustains global scale through its Gatorade sports drink portfolio and direct-store-delivery network. Monster Beverage Corporation differentiates through energy drink specialization and sponsorship-driven brand equity in action sports culture.
Functional beverages are non-alcoholic drinks formulated with bioactive compounds—vitamins, amino acids, adaptogens, or probiotics—at concentrations sufficient to deliver targeted physiological effects beyond basic hydration. Manufacturing relies on aseptic cold-fill processing or hot-fill pasteurization to preserve thermolabile functional ingredients such as live probiotic cultures and heat-sensitive antioxidants. Energy drinks and sports drinks command the largest revenue pools due to established distribution infrastructure and habitual consumption patterns among fitness enthusiasts and athletes. Probiotic drinks represent the fastest-expanding segment as gut-health science penetrates mainstream consumer awareness and drives premium shelf placement.
The FDA governs health claim substantiation and GRAS self-affirmation for novel functional ingredients in the United States, while the EMA and EFSA coordinate novel food assessments and health claim validations across European markets. China's SAMR enforces GB standards for functional food labeling and restricts permitted ingredient lists, creating divergent compliance pathways for multinational portfolios. Stakeholders must monitor evolving adaptogen classification debates and prebiotic fiber regulatory thresholds to anticipate reformulation costs and market access barriers.
Market Dynamics
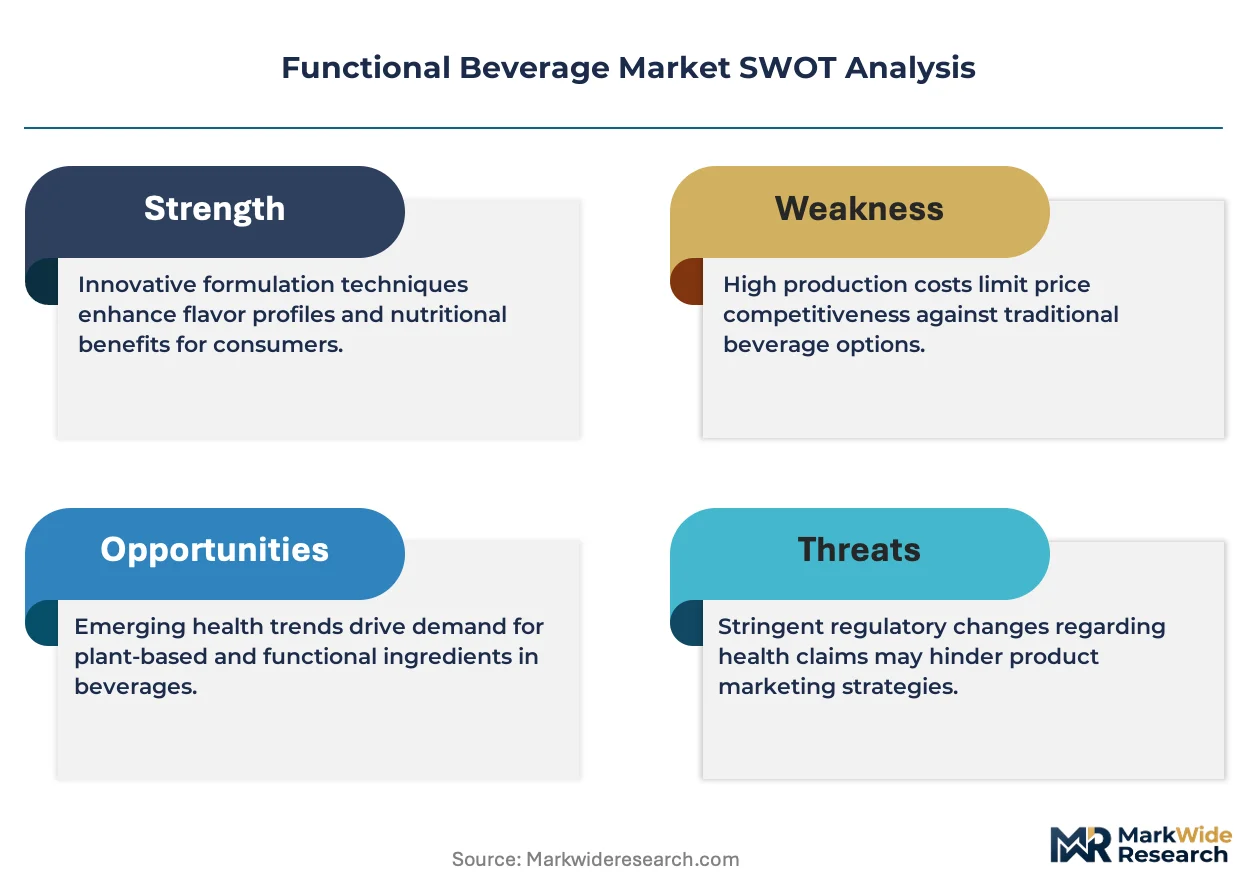
The functional beverage market is being fundamentally restructured by the EU's Farm to Fork Strategy, which mandates additive transparency and sustainable sourcing protocols that force reformulation across entire supply chains.
Growth Catalysts
- Fitness Enthusiast Adoption:Sports nutrition demand from gym-goers and amateur athletes creates recurring purchase velocity for protein-fortified and electrolyte-replenishment formulations.
- EFSA Health Claim Pathways:Validated gut-health science enables probiotic beverages to secure premium shelf placement and justified price positioning in European retail.
- California Innovation Clusters:Concentrated R&D infrastructure around San Francisco and Los Angeles accelerates adaptogen and nootropic ingredient commercialization.
Market Restraints
- Thermolabile Ingredient Costs:Aseptic cold-fill processing requirements for live probiotic preservation inflate capital expenditure versus standard hot-fill lines.
- Chinese SAMR Ingredient Lists:Restricted permitted functional ingredient catalogs force multinational portfolios into costly China-specific reformulation.
- Natural Sweetener Supply Volatility:Stevia and monk fruit harvest sensitivity concentrates input cost risk with Southeast Asian agricultural suppliers.
Strategic Opportunities
- Cognitive Performance Positioning:Nootropic beverages targeting remote workers and students represent an underdeveloped application adjacent to established energy and sports segments.
- Direct-to-Consumer Subscription:Personalized probiotic formulations delivered on recurring schedules bypass traditional retail slotting fee structures.
- EU Green Deal Alignment:Carbon-neutral certification and regenerative agriculture sourcing credentials unlock preferential placement in European public procurement and institutional foodservice.
Industry Challenges
- GRAS Self-Affirmation Expertise:FDA novel ingredient substantiation requires specialized toxicology and clinical trial design capabilities scarce among mid-tier formulators.
- Legacy Hot-Fill Retooling:Existing pasteurization infrastructure cannot accommodate heat-sensitive functional compounds without complete production line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Beverage Market |
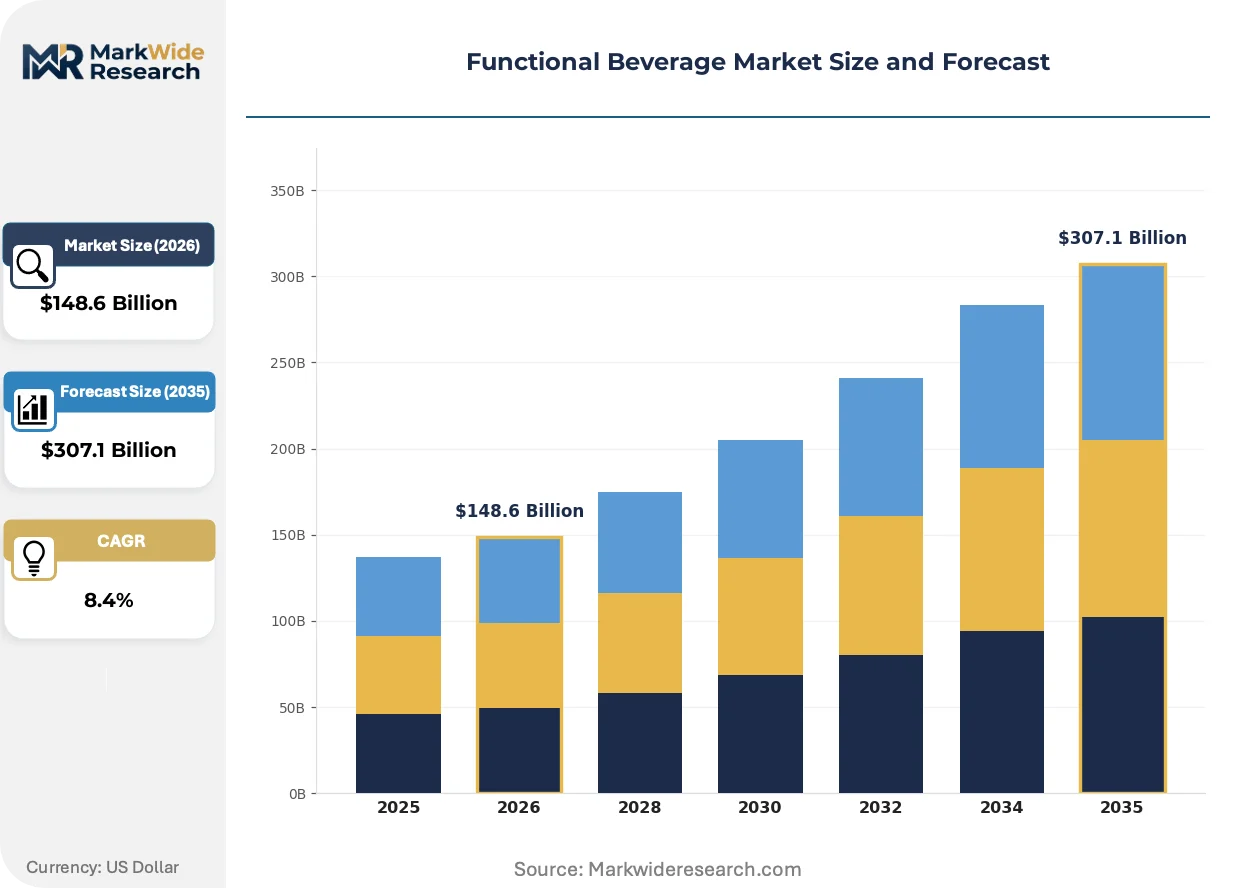
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $307.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Probiotic Drinks, Herbal Refreshers, Vitamin-Enhanced Waters Functional Ingredient: Vitamins, Minerals, Amino Acids, Antioxidants, Adaptogens Packaging Type: Bottles, Cans, Cartons, Pouches, Tetra Packs End Consumer: Fitness Enthusiasts, Students, Office Workers, Elderly, Athletes |
| Companies Covered | Red Bull GmbH, Danone S.A., PepsiCo Inc., Fonterra Co-operative Group Limited, Keurig Dr Pepper Inc., The Coca-Cola Company, Monster Beverage Corporation, Glanbia plc, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Beverage Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to compress development cycles and fragment consumption occasions beyond traditional sports and energy use cases.
Precision fermentation for bioactive compound production is decentralizing manufacturing economics previously dominated by agricultural extraction. Biotech startups and beverage co-packers are adopting microbial cultivation systems to synthesize rare adaptogens and customized probiotic strains at commercial scale. This distributed production model is decentralizing geographic dependence on tropical botanical harvesting and compressing ingredient lead times from months to weeks.
REACH chemical registration requirements in Europe are tightening scrutiny on novel functional extracts and synthetic bioactives. Manufacturers must now submit comprehensive safety dossiers for ingredients previously self-affirmed as GRAS in the United States. Adaptogen-heavy energy drink portfolios face the steepest compliance burden, with several brands accelerating European reformulation ahead of 2025 registration deadlines.
Consumers are treating functional beverages as meal-adjacent nutrition rather than occasional performance boosters. This behavior shift expands addressable occasions from pre-workout and recovery to breakfast replacement and afternoon focus maintenance. German and Nordic markets exhibit the strongest penetration of daily consumption rituals, with refrigerated probiotic shots and protein coffees displacing traditional dairy in morning routines.
Functional Beverage Market Segmentation
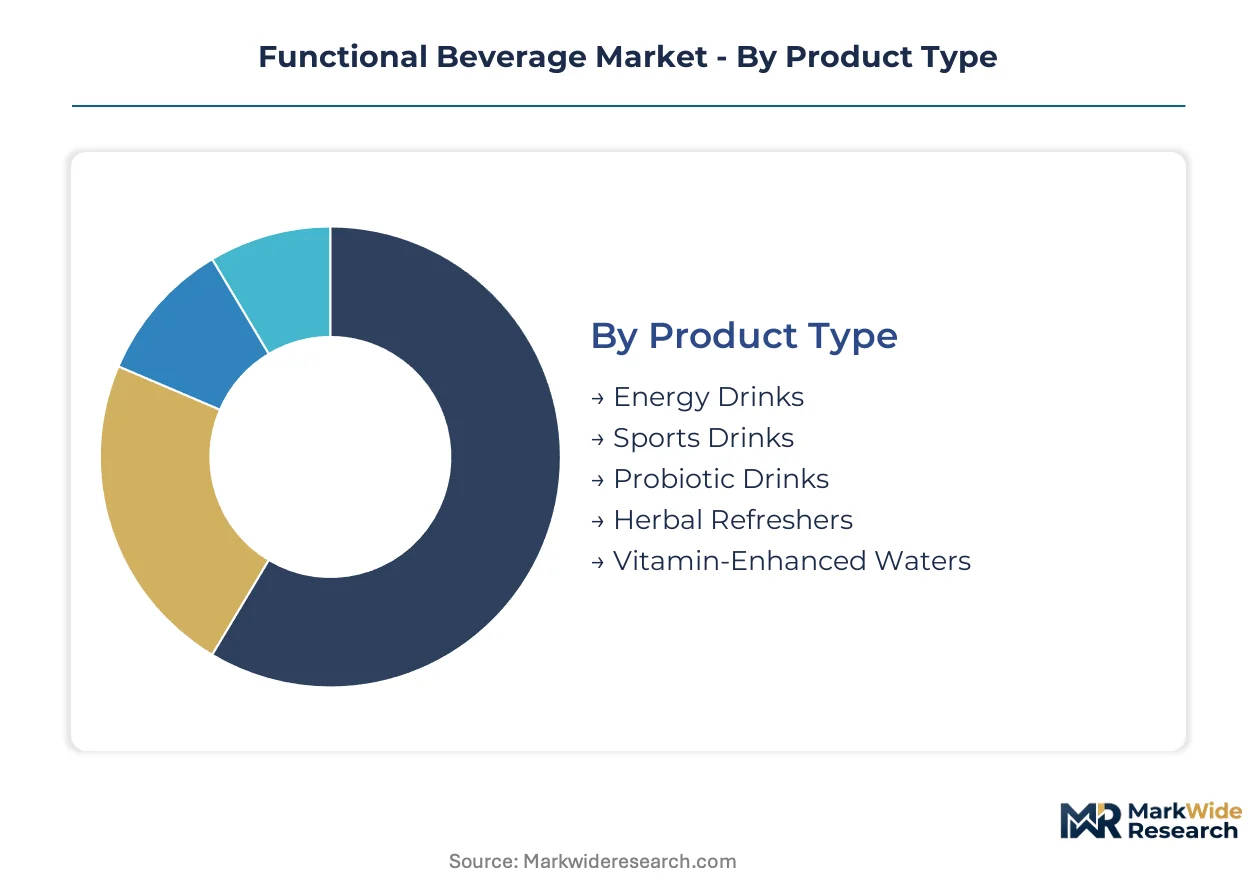
Functional beverage segmentation reveals divergent margin structures across consumption occasions and ingredient technologies. Manufacturers must align formulation investments with distinct purchasing triggers rather than treating the category as monolithic.
Product Type:
Consumption frequency and price tolerance separate habitual daily drinkers from occasional performance seekers.
- Energy Drinks:Caffeine-forward formulations with taurine and B-vitamin complexes dominate convenience store velocity. United States fitness enthusiasts and gamers sustain repeat purchase patterns through established brand loyalty and sponsorship-driven cultural embedding.
- Sports Drinks:Electrolyte-replenishment formulations with sodium-potassium balance target dehydration recovery. California and Colorado athletic communities drive innovation in isotonic and hypotonic concentration variants.
- Probiotic Drinks:Live culture beverages with documented CFU counts deliver gut-health positioning. German and Nordic consumers integrate these into breakfast routines, displacing traditional dairy.
- Herbal Refreshers:Botanical infusions with chamomile, ginger, or hibiscus target relaxation and digestive wellness. European regulatory pathways through EFSA health claim validation constrain rapid commercialization.
- Vitamin-Enhanced Waters:Fortified still or sparkling waters with water-soluble vitamin additions compete in the hydration-plus-nutrition space. Shelf-stable formulations bypass cold-chain requirements but sacrifice live ingredient claims.
Sports drinks lead volumes today; probiotic drinks are gaining share fastest.
Functional Ingredient:
Ingredient sourcing geography and thermostability dictate processing capital requirements and regulatory pathway complexity.
- Vitamins:Water-soluble B-complex and C vitamins enable hot-fill processing compatibility. Synthetic production through pharmaceutical-grade fermentation secures supply consistency independent of agricultural harvest volatility.
- Minerals:Electrolyte salts including magnesium, zinc, and calcium carbonate support hydration and metabolic function. Sports drink manufacturers concentrate procurement around certified mineral suppliers with USP-grade verification.
- Amino Acids:Branched-chain and essential amino acid fortification targets muscle protein synthesis. Fitness enthusiasts in United States metropolitan clusters sustain premium pricing for leucine-enriched recovery formulations.
- Antioxidants:Polyphenol extracts from green tea, berries, and cocoa deliver oxidative stress mitigation. Heat-sensitive compound structures mandate aseptic cold-fill infrastructure investments.
- Adaptogens:Ashwagandha, rhodiola, and ginseng extracts target stress response modulation. REACH registration requirements in Europe force comprehensive safety dossier submissions ahead of commercial launch.
Vitamins dominate current formulation volumes; adaptogens show the steepest expansion trajectory.
Packaging Type:
Distribution channel access and shelf-life requirements determine format selection across retail and foodservice.
- Bottles:PET and rPET containers with resealable closures support multi-serve consumption and on-the-go portability. California innovation clusters drive recycled content mandates and lightweighting technologies.
- Cans:Aluminum formats with internal epoxy linings protect acidic and carbonated formulations. Sports and energy drink portfolios favor this format for vending machine compatibility and chill speed.
- Cartons:Aseptic paperboard with aluminum barrier layers extends ambient shelf life for probiotic and dairy-adjacent beverages. European retail chains prioritize this format for sustainability credentials.
- Pouches:Flexible film structures with spout fitments reduce shipping cube and material weight. Emerging brands deploy this format for direct-to-consumer subscription logistics.
- Tetra Packs:Multilayer carton systems with sterile filling technology enable ambient distribution without refrigeration. Asian markets with fragmented cold-chain infrastructure favor this capital-efficient solution.
Bottles and cans command equivalent volume shares today; cartons are climbing the fastest in European markets.
End Consumer:
Life stage and activity patterns shape functional benefit prioritization and channel preferences.
- Fitness Enthusiasts:Recreational athletes and gym members seeking performance optimization and recovery acceleration. United States demand concentrates in metropolitan fitness studio ecosystems.
- Students:Cognitive performance and sustained attention targeting through nootropic and moderate-caffeine formulations. Campus retail and e-commerce direct delivery shape distribution design.
- Office Workers:Afternoon energy maintenance and stress management without sleep disruption. Adaptogen and L-theanine combinations gain traction in remote work routines.
- Elderly:Bone health, immune support, and hydration compliance through palatable fortification. Medical and pharmacy channel placement requires distinct regulatory positioning.
- Athletes:Competitive and professional performers with precise electrolyte and macronutrient timing requirements. Institutional sports nutrition partnerships and team supply contracts anchor volume.
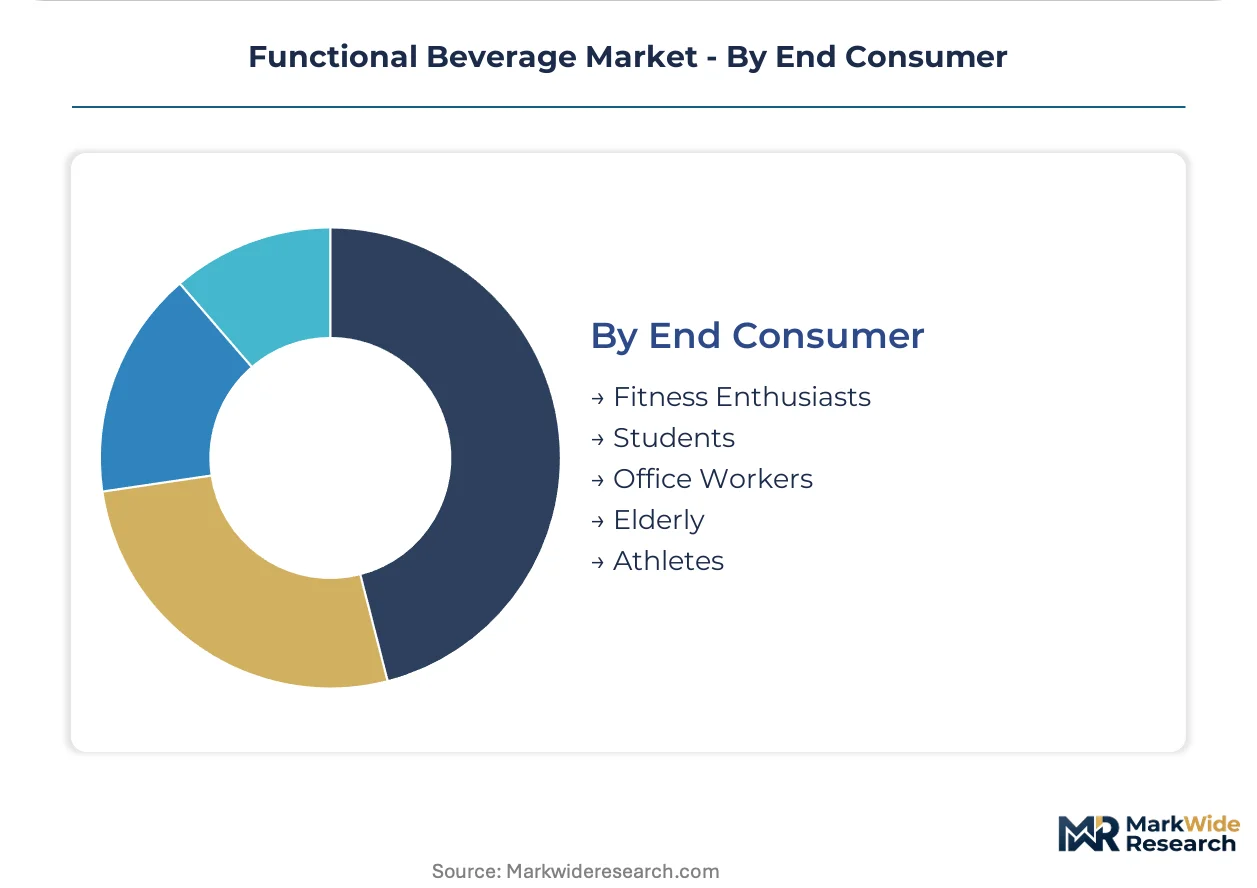
Fitness enthusiasts anchor current consumption volumes; office workers are expanding most quickly as work-from-home routines normalize functional beverage integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness professionals and food scientists cluster disproportionately in coastal metropolitan areas, anchoring regional innovation capacity for functional beverage development.
United States
Gym culture penetration and esports viewership sustain energy drink velocity through habitual consumption patterns. FDA GRAS self-affirmation pathways for novel adaptogens create regulatory headroom for formulation experimentation. California's San Francisco Bay Area and Los Angeles corridor concentrate venture-backed nootropic startups and precision fermentation biotechs.
Germany
Probiotic daily consumption rituals displace traditional dairy in breakfast routines across metropolitan households. EFSA health claim validation requirements enforce rigorous clinical substantiation for gut-health positioning. Bavaria's dairy processing heritage and Baden-Württemberg's ingredient technology base support fermentation infrastructure expansion.
China
Middle-class wellness expenditure and traditional medicine familiarity drive adaptogen acceptance in tier-one cities. SAMR's restricted permitted ingredient lists force multinational portfolios into costly China-specific reformulation cycles. Yangtze River Delta manufacturing clusters around Shanghai accommodate aseptic cold-fill capacity for live culture preservation.
Japan
Aging demographics and preventative health focus expand functional beverage occasions beyond sports into daily nutrition. PMDA and FOSHU (Foods for Specified Health Uses) notification requirements structure health claim substantiation. Tokyo-Osaka corridor hosts concentrated R&D facilities for bioactive peptide and collagen fortification technologies.
Brazil
Fitness studio proliferation and tropical botanical access support local adaptogen sourcing advantages. ANVISA's novel food assessments create compliance timelines for imported functional ingredients. São Paulo's beverage co-packing infrastructure and Rio de Janeiro's consumer brand development clusters anchor South American market development.
Functional Beverage Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The functional beverage sector exhibits consolidated leadership in energy and sports segments alongside fragmented innovation at the probiotic and adaptogen frontier. Three archetypes dominate: multinational beverage conglomerates with direct-store-delivery networks, dairy-origin probiotic specialists with fermentation infrastructure, and energy drink pure-plays with sponsorship-driven brand equity. Competitive dynamics center on M&A absorption of regional adaptogen brands and capacity expansion into aseptic cold-fill processing for live culture preservation.
Within the multinational tier, PepsiCo Inc., The Coca-Cola Company, and Danone S.A. occupy positions reflecting divergent heritage advantages. PepsiCo exemplifies sports drink dominance through established athletic partnerships and retail distribution density. The Coca-Cola Company represents global scale infrastructure applied to functional portfolio extension. Danone anchors European probiotic positioning through dairy-adjacent fermentation expertise and EFSA health claim validation experience.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Danone S.A. |
| PepsiCo Inc. |
| Fonterra Co-operative Group Limited |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Monster Beverage Corporation |
| Glanbia plc |
| Nestlé S.A. |
| Others |
Cost & Logistics Intelligence
Fermentation scientists and aseptic processing engineers cluster around California's Bay Area and Colorado's Front Range, creating labor-cost differentials that widen pricing spreads between premium live-culture formulations and standard hot-fill alternatives. Manufacturers with captive cold-fill capacity command tier premiums while commodity vitamin-fortified waters compete on input-cost efficiency.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based personalized probiotic programs from transactional retail purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EFSA-validated gut-health claims justify shelf price premiums while generic wellness positioning competes on volume scale. Pricing pressure stems from natural sweetener harvest volatility concentrated with Southeast Asian agricultural suppliers. Fitness enthusiasts show least price sensitivity for leucine-enriched recovery formulations; mass-market vitamin waters face highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for reusable glass bottle programs and expired live-culture returns concentrate cost burdens on direct-to-consumer subscription operators. Supply concentrates in China for precision fermentation equipment, Germany for aseptic carton barrier technology, and Brazil for tropical adaptogen botanical extraction. Raw material dependencies include pharmaceutical-grade vitamin fermentation feedstocks, certified mineral salts, and heat-sensitive antioxidant extracts. Single-source vulnerability runs through Southeast Asian stevia and monk fruit harvests. Distribution runs through direct-store-delivery networks for convenience store velocity and cold-chain logistics for probiotic preservation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional beverage market operates as a regulatory compounder where EFSA health claim validation and FDA GRAS self-affirmation pathways create accelerating compliance moats that favor incumbents with established substantiation expertise.
For Market Incumbents: Hedge against adaptogen classification uncertainty by diversifying ingredient portfolios across validated probiotic strains and mineral-electrolyte formulations with established regulatory status. Accelerate aseptic cold-fill capacity expansion into Yangtze River Delta manufacturing clusters to capture China-specific live-culture demand. Channel control through direct-store-delivery density remains the priority defensive lever against digital-native entrants. For New Entrants and Emerging Players: Direct-to-consumer subscription routes bypass retail slotting fee structures and enable personalized formulation premiums. White-space targets include nootropic positioning for remote office workers and carbon-neutral certification alignment for European institutional procurement. Campus retail and esports sponsorship ecosystems represent the most penetrable go-to-market angle for cognitive performance beverages. For Investors and Strategic Acquirers: Dairy-origin conglomerates with fermentation infrastructure are the most active acquirer in this space, seeking probiotic technology bolt-ons to extend wellness portfolios. Five-to-ten year viability hinges on adaptogen regulatory clarity and precision fermentation cost curves. Acquisition target archetypes include regional adaptogen brands with EFSA dossier preparation underway. Signal to monitor: REACH registration deadline compliance acceleration among energy drink portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Live probiotic preservation enables premium shelf placement and EFSA-validated health claims. |
| EFSA Health Claim Validation Investment | Documented gut-health substantiation secures justified price positioning in German and Nordic retail. |
| Direct-to-Consumer Subscription Launch | Recurring revenue bypasses traditional retail slotting fees and enables personalized formulation premiums. |
| Precision Fermentation Partnership | Distributed bioactive production compresses ingredient lead times from agricultural extraction dependence. |
| Regenerative Agriculture Sourcing Certification | EU Green Deal alignment unlocks preferential placement in European public procurement channels. |
Research Approach
Direct dialogue with beverage formulators, fermentation R&D directors, retail category buyers, and regulatory affairs specialists anchored qualitative foundations. Secondary validation drew from FDA GRAS notification databases, EFSA health claim register entries, SAMR functional food labeling standards, and customs trade data for functional ingredient flows. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity disclosures and consumption survey panels.
Bottom-up modeling segmented by product type, functional ingredient technology, packaging format, and end-consumer archetype across the analysis window. Top-down validation referenced macroeconomic wellness expenditure indices and gym membership penetration rates. CAGRs derived from regression against historical adoption curves and regulatory milestone impacts. Forecast inputs incorporated precision fermentation cost reduction trajectories and EFSA validation pipeline timelines.
Regulatory reclassification, harvest volatility in natural sweetener supply, and cold-chain infrastructure gaps are the dominant revision risks. Forecasts reflect documented assumptions on consumer adoption rates and regulatory pathway timelines. Practitioners should monitor EFSA adaptogen registration deadlines, Southeast Asian agricultural yield reports, and SAMR permitted ingredient list updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Functional Chewing Gums Market