
 South America Functional Beverages Market | 2026-2036
South America Functional Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Functional Beverages Market Analytics
ANVISA's updated caffeine-disclosure rules are restructuring the cost-of-entry calculus for new functional beverage entrants in Brazil. Ambev S.A. leverages its deep distribution network across Brazilian states to sustain volume leadership in energy drink segments. Monster Beverage Corporation anchors its regional position through specialized marketing toward extreme-sports communities. PepsiCo Inc. competes by extending its Gatorade portfolio into electrolyte-enhanced waters tailored for humid climates.
Functional beverages comprise non-alcoholic drinks fortified with bioactive compounds, vitamins, minerals, amino acids, or herbal extracts designed to deliver targeted physiological benefits beyond basic hydration. These products typically contain precise concentrations of functional ingredients measured in milligrams per serving, manufactured through cold-aseptic filling or hot-fill processes to preserve bioactivity. Energy drinks dominate current revenue pools given established consumer habits and higher per-unit pricing, while nutraceutical beverages represent the fastest-expanding category as wellness seekers prioritize immune-support and gut-health formulations. Sports drinks maintain mature growth trajectories in Brazil and Argentina where athletic participation rates have plateaued, though margin pools concentrate in premium isotonic variants with natural sweeteners.
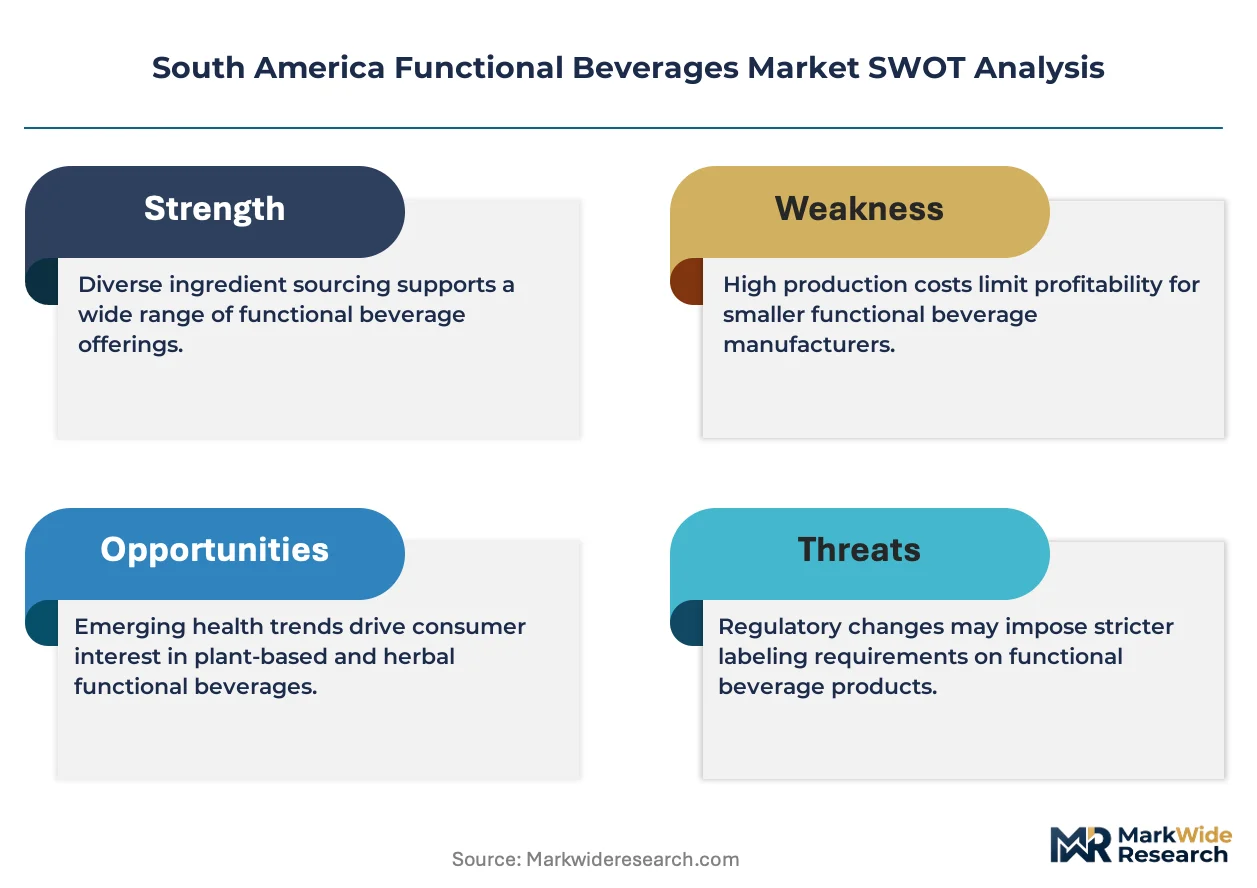
ANVISA in Brazil, INVIMA in Colombia, and Argentina's ANMAT enforce divergent caffeine caps, probiotic strain approvals, and front-of-package warning labels that fragment compliance costs across national borders. These regulatory frameworks directly shape product portfolios, as manufacturers must reformulate or label separately for each jurisdiction rather than deploying standardized SKUs. Stakeholders must monitor pending harmonization discussions within Mercosur while building modular formulation capabilities that adapt to shifting national standards without full line overhauls.
Market Dynamics
ANVISA's tightened caffeine-disclosure mandates are forcing simultaneous reformulation and relabeling investments across Brazilian manufacturing lines, compressing margin structures for multinational and domestic producers alike.
Growth Catalysts
- Urban Preventive Wellness Adoption:São Paulo's professional workforce integrates functional beverages into daily routines, creating sustained pull for immune-support and gut-health formulations.
- ANVISA's Regulatory Clarity:Brazil's updated labeling framework reduces compliance ambiguity, enabling faster new-product introductions by standardizing disclosure requirements.
- Metropolitan Retail Premiumization:Rio de Janeiro's upscale grocery channels dedicate expanded shelf space to nutraceutical beverages, validating higher price points for bioactive-enriched products.
Market Restraints
- Input Cost Volatility:Stevia and monk fruit extract prices fluctuate with Brazilian agricultural harvest cycles, squeezing natural-sweetener formulation economics.
- Supply Concentration Risk:Aseptic cold-fill capacity clusters in São Paulo state, creating geographic single-point vulnerabilities for national distribution.
- Regulatory Fragmentation:Divergent caffeine caps between ANVISA, INVIMA, and ANMAT prevent standardized SKU deployment across Mercosur borders.
Strategic Opportunities
- Colombian Market Underpenetration:Bogotá's health-conscious consumer base lacks dedicated functional beverage retail infrastructure, opening first-mover positioning for specialized entrants.
- Direct-to-Home Subscription Models:Personalized nutraceutical delivery bypasses traditional retail slotting fees while capturing recurring revenue from wellness-focused households.
- Probiotic Strain Approval Harmonization:Pending Mercosur alignment discussions could streamline multi-country product registration, reducing time-to-market for gut-health formulations.
Industry Challenges
- Formulation Talent Scarcity:Brazil's food science programs produce insufficient specialists in bioactive compound stabilization for humid-climate shelf-life extension.
- Capex Intensity for Modular Lines:Equipment capable of rapid reformulation switching between ANVISA, INVIMA, and ANMAT specifications demands substantial upfront investment.
- Cross-Border Labeling Complexity:Front-of-package warning label variations require separate packaging runs, inflating working capital requirements for inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Functional Beverages Market |
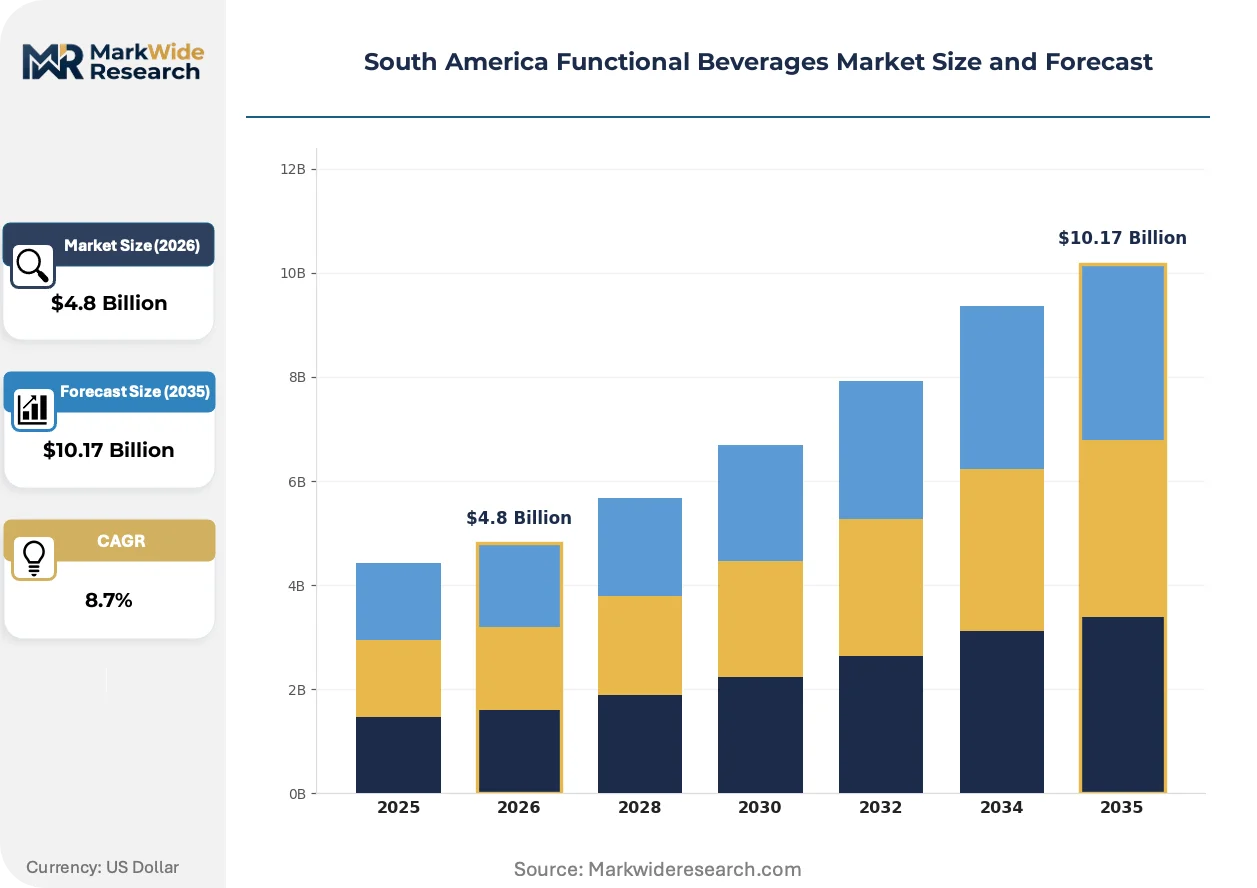
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Nutraceutical Beverages, Enhanced Water End User: Health Enthusiasts, Athletes, Casual Drinkers, Wellness Seekers Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Ingredient Type: Vitamins, Herbal Extracts, Probiotics, Amino Acids |
| Companies Covered | Monster Beverage Corporation, Keurig Dr Pepper Inc., PepsiCo Inc., Grupo AJE, Ambev S.A., The Coca-Cola Company, Danone SA, Fonterra Co-operative Group, Red Bull GmbH, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Functional Beverages Market Evolving Landscape
Cold-aseptic filling technology is converging with digital traceability systems, enabling real-time bioactivity verification that reshapes quality assurance protocols across South American production networks.
Enzymatic extraction methods for plant-based adaptogens are converging with blockchain-verified supply chain documentation. Brazilian nutraceutical startups adopt these dual capabilities to substantiate purity claims demanded by São Paulo's premium retail buyers. This convergence is compressing traditional third-party certification timelines while raising competitive barriers for legacy hot-fill operations.
ANVISA's front-of-package warning label expansion for high-caffeine products is restructuring formulation priorities. Manufacturers redirect R&D spending toward moderate-caffeine and caffeine-free functional alternatives to avoid visual deterrent placement. Energy drink portfolios face the steepest adaptation requirements, with several brands accelerating botanical stimulant research to maintain perceptual energy positioning without triggering disclosure thresholds.
Specialty pharmacy channels in Buenos Aires and Santiago are displacing conventional supermarket placement for clinical-grade nutraceutical beverages. Physicians and nutritionists increasingly recommend specific formulations, transferring purchase authority from impulse-driven retail selection to professional guidance. This channel rotation concentrates volume in credential-verified products while marginalizing undifferentiated mass-market entries lacking clinical substantiation.
South America Functional Beverages Market Segmentation
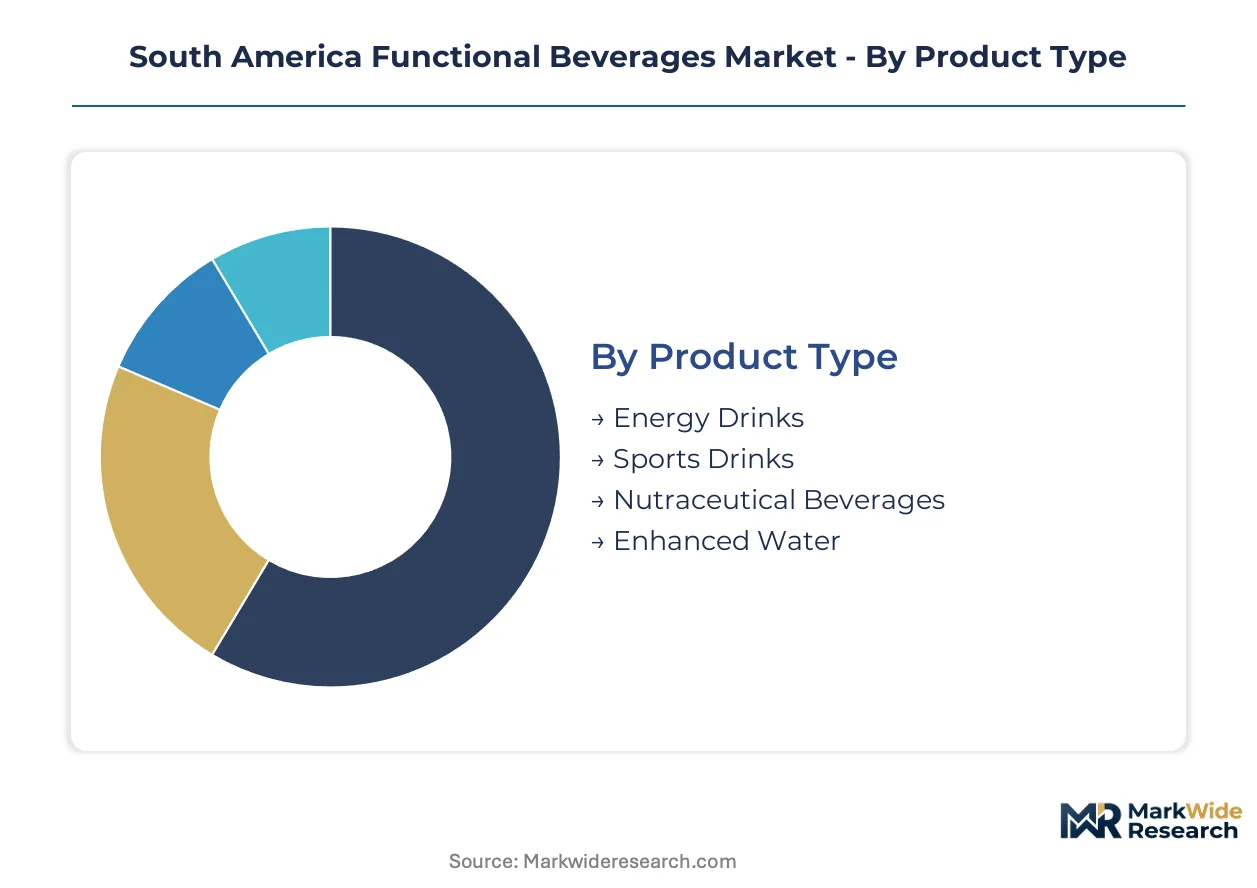
Segmentation in South America's functional beverages market reveals how formulation specifications, distribution economics, and consumer wellness priorities intersect to create distinct competitive arenas. Manufacturers must align cold-aseptic filling capabilities with channel-specific margin structures while navigating ANVISA's caffeine-disclosure mandates.
Product Type:
Formulation technology and bioactive stabilization requirements differentiate competitive positioning across the four product categories.
- Energy Drinks:High-caffeine formulations with taurine and B-vitamin complexes dominate current revenue pools, though ANVISA's front-of-package warning labels are forcing reformulation toward moderate-caffeine alternatives. São Paulo's urban professionals sustain volume through established consumption habits despite regulatory pressure.
- Nutraceutical Beverages:Immune-support and gut-health formulations with clinically substantiated probiotic strains are gaining shelf space in Rio de Janeiro's upscale retail channels. São Paulo's preventive wellness adoption concentrates demand for bioactive-enriched products with verified purity documentation.
- Sports Drinks:Electrolyte-enhanced isotonic formulations serve athletic participation in Brazil and Argentina where natural sweetener variants command premium positioning.
- Enhanced Water:Low-calorie functional hydration with vitamin or mineral fortification targets casual consumption occasions in humid metropolitan climates.
Energy Drinks leads on scale; Nutraceutical Beverages leads on momentum.
End User:
Consumer wellness sophistication and purchasing authority shape product development priorities across four distinct user profiles.
- Health Enthusiasts:São Paulo's professional workforce integrates preventive wellness routines with clinically validated nutraceutical formulations, driving demand for blockchain-verified supply chain documentation.
- Wellness Seekers:Expanding cohort prioritizing immune function and digestive health through daily functional beverage consumption, particularly in metropolitan Brazil.
- Athletes:Performance-oriented users in Brazil and Argentina sustain mature demand for electrolyte-replacement formulations with natural sweetener profiles.
- Casual Drinkers:Occasional functional beverage consumers seeking convenient hydration alternatives with moderate functional claims.
Health Enthusiasts commands premium pricing power; Wellness Seekers exhibits steepest expansion trajectory.
Distribution Channel:
Channel economics and regulatory compliance requirements determine margin structures and inventory management complexity.
- Supermarkets:Traditional mass-market volume concentration in São Paulo and Rio de Janeiro metropolitan corridors, where slotting fees and front-of-package label placement create competitive barriers.
- Health Stores:Specialty retail channels in Buenos Aires and Santiago are displacing conventional placement for clinical-grade nutraceutical beverages with physician recommendation authority.
- Online Retail:Direct-to-home subscription models bypass traditional slotting fees while capturing recurring revenue from wellness-focused households across Brazilian states.
- Convenience Stores:Impulse-driven energy drink purchases in urban transit corridors, though warning label visibility dampens velocity for high-caffeine SKUs.
Supermarkets dominates volume throughput; Health Stores captures margin expansion.
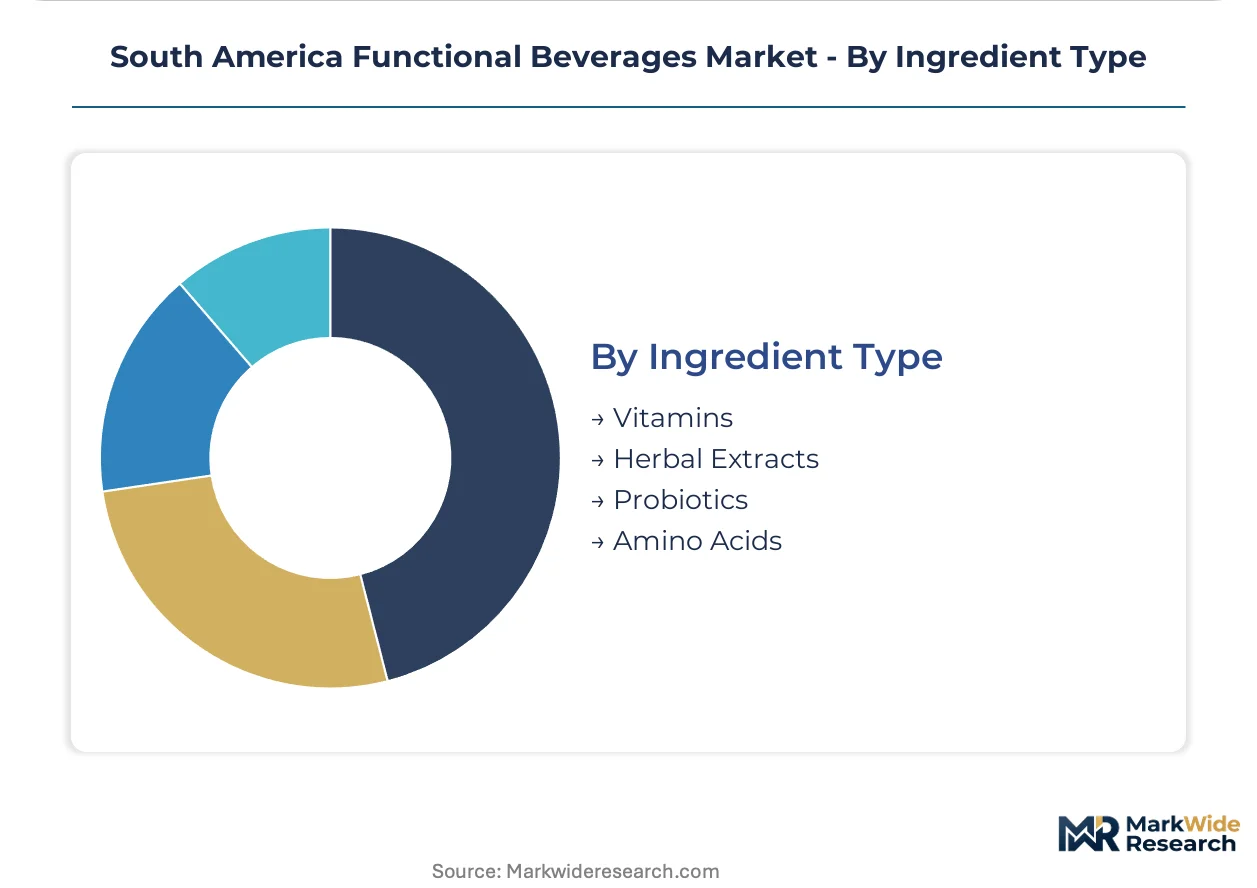
Ingredient Type:
Bioactive compound stability and regulatory approval status differentiate formulation strategies across four ingredient categories.
- Probiotics:Strain-specific formulations with ANVISA, INVIMA, and ANMAT approvals face fragmented compliance costs, though pending Mercosur harmonization could streamline multi-country registration.
- Herbal Extracts:Enzymatic extraction methods for plant-based adaptogens are converging with digital traceability systems to substantiate purity claims demanded by premium retail buyers.
- Vitamins:Water-soluble fortification for immune-support positioning in humid-climate shelf-life applications.
- Amino Acids:Recovery-focused formulations targeting athletic end-users with specific performance claims.
Probiotics leads on regulatory complexity; Herbal Extracts gains share fastest through traceability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's concentration of food science talent and formulation specialists anchors South America's functional beverage production capacity, with metropolitan clusters in Brazil, Argentina, Colombia, and Chile driving distinct demand patterns shaped by local regulatory frameworks.
Brazil
Urban professionals in São Paulo and Rio de Janeiro integrate preventive wellness routines into daily consumption habits, pulling immune-support formulations through upscale retail channels. ANVISA's tightened caffeine-disclosure mandates and front-of-package warning label requirements are forcing simultaneous reformulation and relabeling investments across manufacturing lines. Cold-aseptic filling capacity clusters in São Paulo state, creating geographic concentration for national distribution networks serving Brazil's metropolitan corridors.
Argentina
Buenos Aires anchors demand for clinical-grade nutraceutical beverages as specialty pharmacy channels displace conventional supermarket placement. ANMAT enforces divergent caffeine caps and probiotic strain approvals that fragment compliance costs with neighboring jurisdictions. The metropolitan region's physician and nutritionist networks increasingly recommend specific formulations, transferring purchase authority from impulse-driven retail to professional guidance.
Colombia
Bogotá's health-conscious consumer base lacks dedicated functional beverage retail infrastructure, opening first-mover positioning for specialized entrants targeting wellness-focused households. INVIMA maintains separate regulatory standards for caffeine content and front-of-package labeling that prevent standardized SKU deployment from Brazilian manufacturing lines. Direct-to-home subscription models bypass traditional slotting fees while capturing recurring revenue in this underpenetrated market.
Chile
Santiago's specialty pharmacy channels concentrate volume for credential-verified nutraceutical products with clinical substantiation requirements. The country's national pharmaceutical regulator enforces strict probiotic strain documentation that raises competitive barriers for undifferentiated mass-market entries. Metropolitan retail buyers demand blockchain-verified supply chain documentation to substantiate purity claims for premium positioning.
South America Functional Beverages Market Competitive Landscape
The competitive structure tilts toward diversified beverage conglomerates with deep distribution networks and specialized energy drink marketers with extreme-sports positioning. Tiered concentration separates multinational portfolio owners from regional bottling specialists and niche nutraceutical formulators. Strategic archetypes include scale-driven distribution leverage, regulatory compliance modularization, and premium traceability differentiation. Dominant competitive moves encompass portfolio diversification into electrolyte-enhanced variants and geographic expansion through modular formulation capabilities.
Among multinational beverage conglomerates, Ambev S.A. and PepsiCo Inc. exemplify scale-driven distribution archetypes, while Monster Beverage Corporation occupies a specialized marketing position. These three entities anchor distinct competitive vectors within the regional market structure.
| Leading Market Players |
|---|
| Monster Beverage Corporation |
| Keurig Dr Pepper Inc. |
| PepsiCo Inc. |
| Grupo AJE |
| Ambev S.A. |
| The Coca-Cola Company |
| Danone SA |
| Fonterra Co-operative Group |
| Red Bull GmbH |
| Others |
Value Network & Pricing Analysis
Captive aseptic cold-fill capacity in São Paulo state anchors both supply security and premium pricing power for nutraceutical formulations. Brazilian manufacturers with in-house filling lines command margin premiums over toll-dependent competitors, while ANVISA's reformulation mandates force modular equipment investments that concentrate pricing leverage among capitalized players.
Pricing Analysis
Bundled service contracts combining formulation development with regulatory compliance support separate premium nutraceutical producers from transactional commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and blockchain traceability investments. Pricing pressure stems from stevia and monk fruit extract harvest volatility squeezing natural-sweetener economics. Wellness Seekers exhibit highest price sensitivity, while Health Enthusiasts absorb premiums for clinically substantiated probiotic strains.
Supply Chain Analysis
Regional distribution centers in São Paulo state operate hub-and-spoke patterns feeding Brazilian metropolitan corridors with 48-hour replenishment cycles. Brazil, Argentina, and Colombia anchor South American functional beverage manufacturing, with cold-fill capacity clustering in São Paulo while Buenos Aires specializes in clinical-grade nutraceutical packaging. Raw material dependencies center on Brazilian stevia extracts, Colombian coffee-derived caffeine, and imported probiotic cultures from European fermentation specialists. Single-source vulnerability runs through São Paulo's concentrated aseptic filling infrastructure. Distribution runs through supermarket slotting agreements in Rio de Janeiro and direct-to-home subscription platforms bypassing traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's functional beverage market reads as a late-cycle quality story where urban professionals in São Paulo and Rio de Janeiro redirect spending toward preventive wellness formulations with verified bioactive content.
For Market Incumbents: To counter ANVISA's front-of-package warning label expansion, accelerate botanical stimulant R&D to maintain energy positioning without triggering disclosure thresholds. Backward integration into stevia cultivation in Minas Gerais secures sweetener supply against harvest-driven price spikes while supporting premium natural-claim positioning. For New Entrants and Emerging Players: Enter via Bogotá's underpenetrated health-conscious consumer base, where dedicated functional beverage retail infrastructure remains sparse. Target direct-to-home subscription models for Wellness Seekers in Colombian metropolitan zones, leveraging regulatory arbitrage before INVIMA-Brazil harmonization closes the window. For Investors and Strategic Acquirers: Roll-up economics work for regional nutraceutical formulators with modular ANVISA-INVIMA-ANMAT compliance capabilities because regulatory fragmentation prevents standardized SKU deployment and rewards acquisition of multi-jurisdiction registration expertise. Watch probiotic strain approval harmonization discussions within Mercosur as the inflection signal for consolidated regional players.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Formulation Line Investment | Enables rapid switching between ANVISA, INVIMA, and ANMAT specifications without full line overhauls. |
| Blockchain Supply Chain Verification | Satisfies São Paulo premium retail buyer demands for documented probiotic strain purity and herbal extract origin. |
| Direct-to-Home Subscription Launch | Bypasses supermarket slotting fees while capturing recurring revenue from wellness-focused Brazilian households. |
| Botanical Stimulant R&D Program | Develops moderate-caffeine alternatives that maintain perceptual energy positioning under tightened ANVISA disclosure rules. |
| Specialty Pharmacy Channel Partnership | Secures physician recommendation authority in Buenos Aires and Santiago clinical-grade placement. |
Research Methodology
Multiple input streams — regulatory filing analysis, retail audit data, and executive interviews — were reconciled to construct market estimates. Primary conversations with ANVISA compliance officers, São Paulo supermarket category buyers, Colombian nutraceutical formulators, and Brazilian food science program directors informed operational assumptions. Secondary validation drew from ANVISA resolution databases, INVIMA registration filings, Mercosur harmonization committee minutes, and Brazilian agricultural harvest statistics. Bottom-up SKU-level volume builds were cross-checked against top-down category spending estimates.
Historical volume trajectories were cross-referenced against panel input from manufacturing executives to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, end-user wellness sophistication, distribution channel economics, and ingredient regulatory status dimensions. CAGRs were derived from trend extrapolation moderated by regulatory event probability weighting. Forecast inputs included ANVISA reformulation timeline assumptions and Mercosur harmonization negotiation status.
Inputs from Brazilian regulatory filings and Colombian retail channel interviews were available through the study window; gaps in real-time INVIMA enforcement consistency introduce uncertainty bands around Colombian market penetration assumptions. Forecasts reflect documented scenario assumptions around probiotic strain approval timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
RTD Protein Beverages Market