
 APAC Functional Food Ingredients Market | 2026-2036
APAC Functional Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Functional Food Ingredients Market Outlook
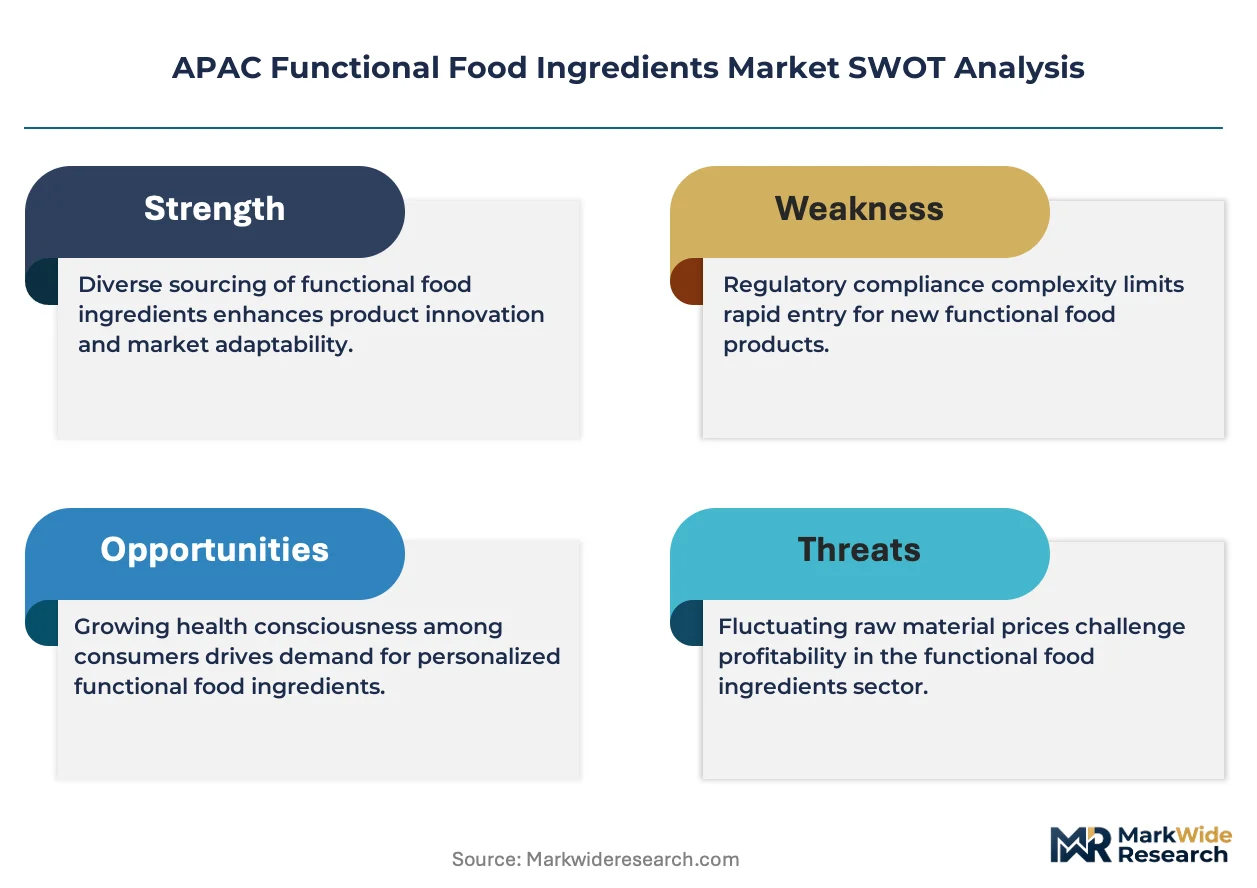
China's GB standards for food fortification is consolidating compliance burdens across ingredient suppliers. Cargill, Incorporated leverages its oilseed processing infrastructure to secure cost positions in omega-3 and protein isolates across East Asia. Kerry Group plc anchors its growth through taste-and-nutrition integration labs in Shanghai and Singapore. DSM Nutritional Products specializes in vitamin and premix formulations that meet divergent national labeling rules.
Functional food ingredients comprise bioactive compounds, probiotics, fibers, amino acids, and vitamins engineered into conventional foods to deliver physiological benefits beyond basic nutrition, typically manufactured through fermentation, extraction, or microencapsulation to preserve stability during thermal processing. Probiotics and fiber categories occupy the largest volume positions due to established digestive health positioning across Japan and South Korea. Functional beverages and dietary supplements command premium margin pools as athletes and health-conscious consumers shift spending toward portable, science-backed formats. Amino acids and vitamins represent the fastest-growing ingredient types as clinical sports nutrition and senior care applications deepen.
Japan's Ministry of Health, Labour and Welfare maintains Foods for Specified Health Uses (FOSHU) standards that constrain which functional claims manufacturers may print, directly shaping R&D investment toward clinically validated strains and dosages. India's FSSAI fortification guidelines and China's SAMR registration requirements for novel food ingredients create layered approval pathways that favor suppliers with dedicated regulatory affairs teams in Mumbai and Beijing. Stakeholders must monitor how BIS harmonization with Codex Alimentarius affects import timelines for probiotic cultures and specialty fibers.
Market Dynamics
China's dual carbon goals are forcing ingredient manufacturers to overhaul energy-intensive extraction and fermentation processes, compressing margins for suppliers lacking renewable-powered facilities or carbon-accounting capabilities.
Growth Catalysts
- Probiotic fortification mandates:India's FSSAI guidelines for staple food fortification are accelerating premix procurement by flour millers and edible oil processors in Maharashtra and Gujarat.
- Sports nutrition procurement:Fitness-focused consumers in South Korea and Australia are prioritizing amino acid and protein isolate formulations backed by clinical validation.
- Japan's FOSHU framework:The Ministry of Health, Labour and Welfare's claims authorization system rewards suppliers investing in strain-specific clinical trials for digestive health positioning.
Market Restraints
- Novel ingredient registration timelines:China's SAMR approval pathways for new probiotic strains and bioactive peptides extend commercialization cycles by 18-36 months.
- Omega-3 raw material concentration:Marine oil supply chains cluster in Peruvian and Chilean fisheries, exposing APAC processors to catch-quota volatility and currency fluctuations.
- Clean-label reformulation costs:Replacing synthetic preservatives with natural alternatives in heat-stable applications demands capital-intensive microencapsulation infrastructure.
Strategic Opportunities
- Senior nutrition applications:Japan's aging demographic generates demand for vitamin D and calcium-fortified convenience foods targeting sarcopenia prevention.
- Plant-based protein convergence:Fermentation-derived amino acids and precision-processed pulse isolates are merging to serve flexitarian formulations in Singapore and urban China.
- E-commerce direct channels:Supplement brands in India are bypassing traditional pharmacy distribution through platform-specific SKUs on Reliance JioMart and Amazon India.
Industry Challenges
- Regulatory affairs specialization:Divergent national labeling rules across China, Japan, India, and Australia require country-dedicated compliance teams, inflating overhead for mid-tier suppliers.
- Thermal stability engineering:Maintaining probiotic viability through UHT processing and retort applications demands strain selection expertise and process validation capabilities that outpace current talent pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Functional Food Ingredients Market |
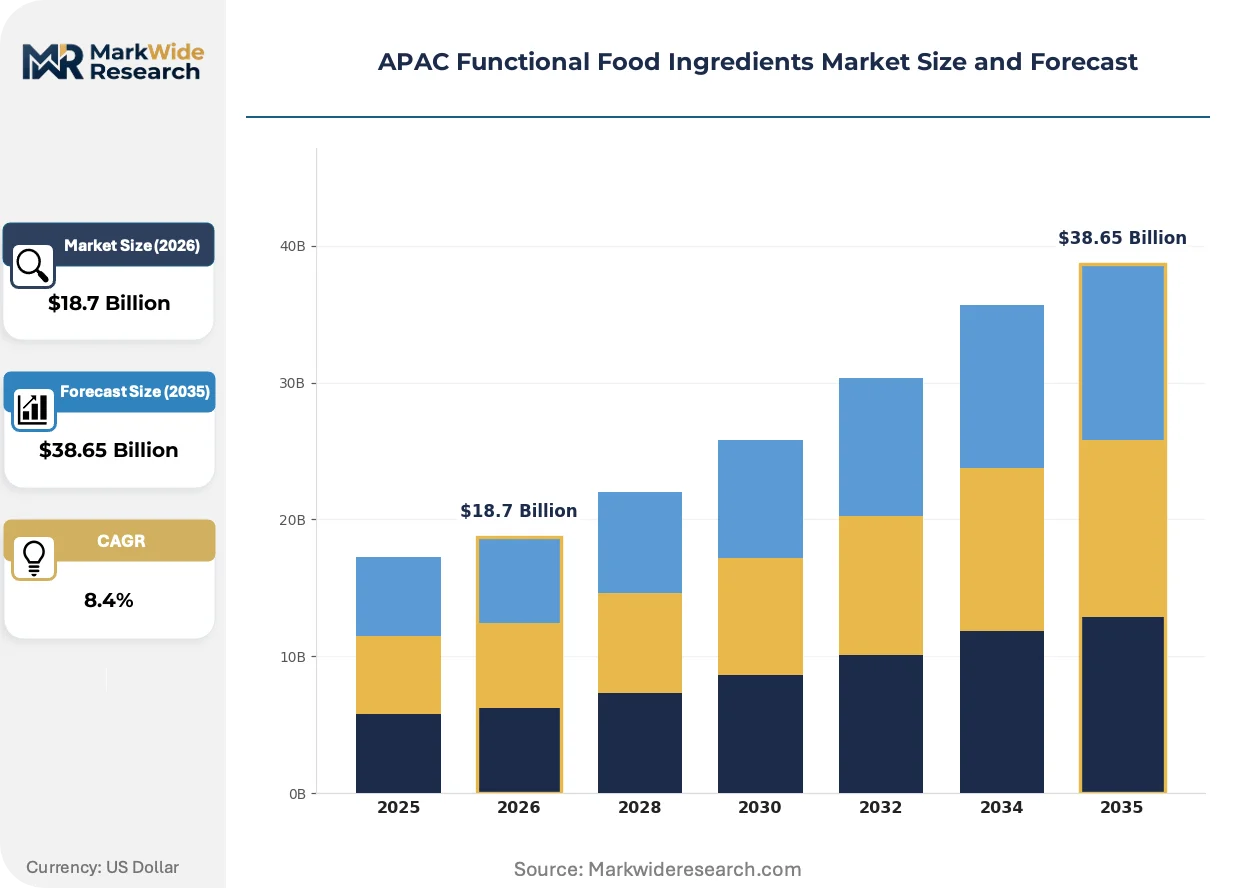
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Probiotics, Fiber, Amino Acids, Vitamins Application: Functional Beverages, Dietary Supplements, Snacks, Bakery Products End User: Health-conscious Consumers, Athletes, Seniors, Patients Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, BASF SE, DSM Nutritional Products, Ajinomoto Co., Inc., Ingredion Inc, Tate & Lyle PLC, Arla Foods Ingredients Group P/S, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Functional Food Ingredients Market Strategic Shifts
Ingredient suppliers are racing to integrate bioactive stability technologies with clean-label positioning as thermal processing demands and consumer transparency expectations tighten simultaneously across East Asian manufacturing.
Microencapsulation via spray-drying and coacervation is consolidating control over probiotic and omega-3 shelf-life extension. Beverage manufacturers in Thailand and Vietnam are adopting these systems to launch ambient-stable functional drinks without refrigeration dependency. The technology is consolidating supplier margins by reducing spoilage claims and enabling wider retail distribution reach.
China's GB standards for food fortification are tightening contaminant thresholds and documentation requirements for vitamin and mineral premixes. Domestic ingredient blenders must now maintain batch-level traceability systems that rival pharmaceutical GMP standards. Dairy and infant nutrition manufacturers in Shandong and Hebei provinces are absorbing compliance costs through dedicated quality control hires.
Urban Indian consumers are prioritizing immunity-positioned products with verifiable active dosages over generic wellness claims. Pharmacy and modern trade buyers in Mumbai and Delhi are demanding third-party assay certificates before listing functional beverages and supplements. This verification-driven preference is compressing shelf space for unvalidated heritage brands while rewarding suppliers with in-house analytical laboratories.
APAC Functional Food Ingredients Market Segmentation
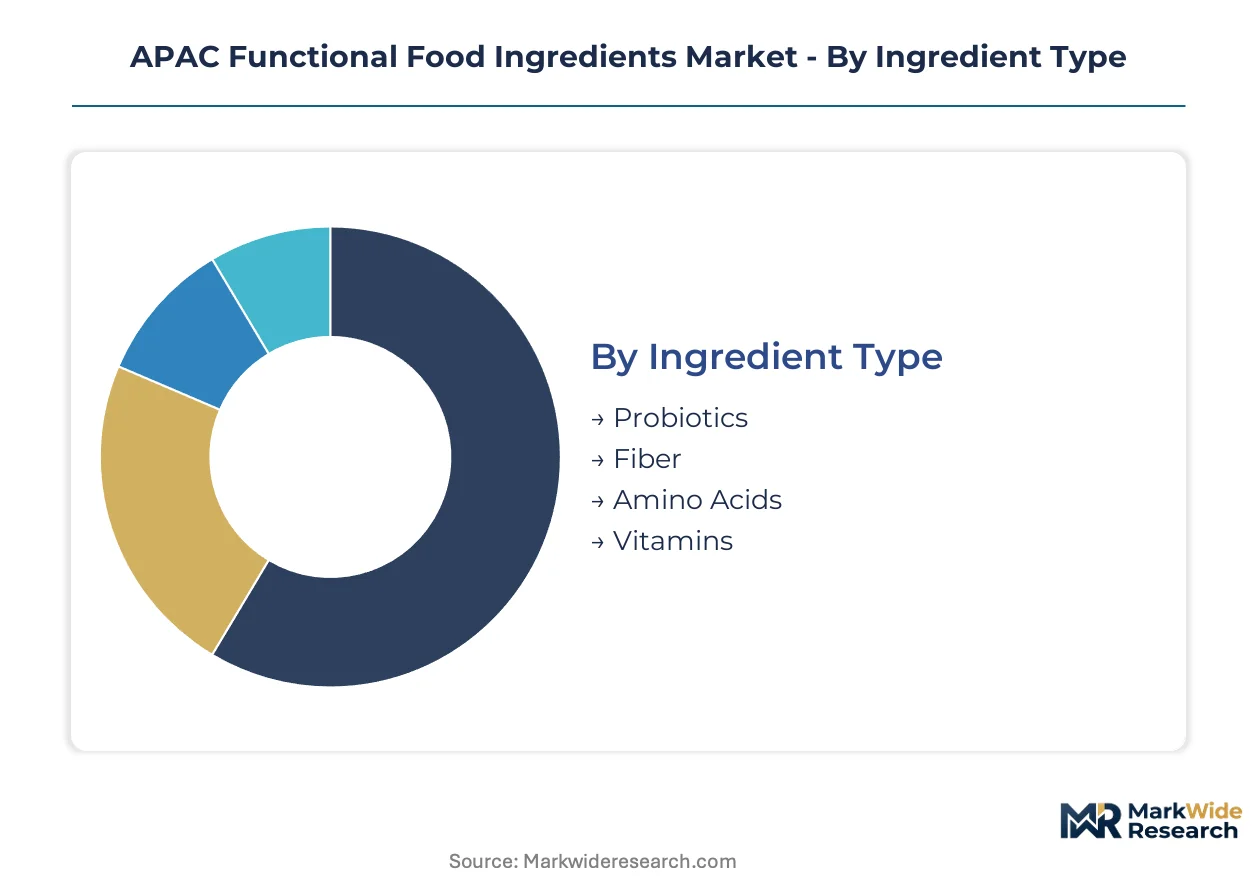
Ingredient positioning in the APAC Functional Food Ingredients Market hinges on whether bioactive compounds function as standalone supplements or embedded fortifiers within processed foods. Regulatory frameworks across China, Japan, and India treat these integration depths differently, shaping supplier R&D allocation and margin structures.
Ingredient Type:
Standalone isolates command premium pricing in clinical applications, while embedded systems face thermal stability constraints and cleaner-label reformulation pressures.
- Probiotics:Live microbial cultures including Lactobacillus and Bifidobacterium strains selected for gastric acid survival and colonization efficacy. Demand clusters in Japan's FOSHU-authorized dairy beverages and South Korean fermented drink formulations, where strain-specific clinical validation determines shelf placement.
- Fiber:Soluble and insoluble variants from chicory root, oat beta-glucan, and resistant starch engineered for digestive health claims. Indian flour millers in Maharashtra and Gujarat are accelerating procurement under FSSAI fortification mandates for wheat and edible oil systems.
- Amino Acids:Branched-chain and essential amino acid isolates for muscle protein synthesis support.
- Vitamins:Fat-soluble and water-soluble premixes subject to China's tightening GB contaminant thresholds.
Volume placements concentrate in Probiotics; the faster expansion belongs to Amino Acids.
Application:
Margin structures diverge sharply between ambient-stable mass-market formats and cold-chain-dependent premium positioning.
- Functional Beverages:Ready-to-drink formats incorporating heat-stable probiotics, protein isolates, and vitamin premixes via microencapsulation. Thai and Vietnamese manufacturers are adopting spray-drying systems to launch ambient-stable SKUs without refrigeration dependency, expanding retail reach into convenience stores.
- Dietary Supplements:Capsule, tablet, and powder formats delivering concentrated bioactive doses for targeted health outcomes. Australia's TGA registration requirements and India's pharmacy channel verification demands are compressing shelf space for unvalidated heritage brands.
- Snacks:Protein-fortified bars and extruded products targeting sports nutrition occasions.
- Bakery Products:Vitamin-enriched breads and omega-3 fortified baked goods facing thermal degradation challenges.
Revenue concentration sits with Dietary Supplements; Functional Beverages are climbing the fastest as Southeast Asian manufacturing scales.
End User:
User sophistication determines dosage precision requirements and willingness to pay for clinical validation.
- Health-conscious Consumers:Urban professionals seeking preventive wellness through daily fortified foods and beverages. Mumbai and Delhi modern trade buyers are demanding third-party assay certificates before listing functional products, filtering out generic wellness claims.
- Athletes:Competitive and recreational fitness participants prioritizing amino acid timing and protein isolate bioavailability. South Korean CrossFit and marathon communities are driving procurement of leucine-rich formulations with batch-tested purity documentation.
- Seniors:Japan's aging demographic generates sarcopenia-prevention demand for vitamin D and calcium-fortified convenience foods.
- Patients:Medically supervised nutrition for diabetes, cardiovascular, and malabsorption conditions.
The largest addressable base lies with Health-conscious Consumers; Athletes show the steepest per-capita spending trajectory.
Distribution Channel:
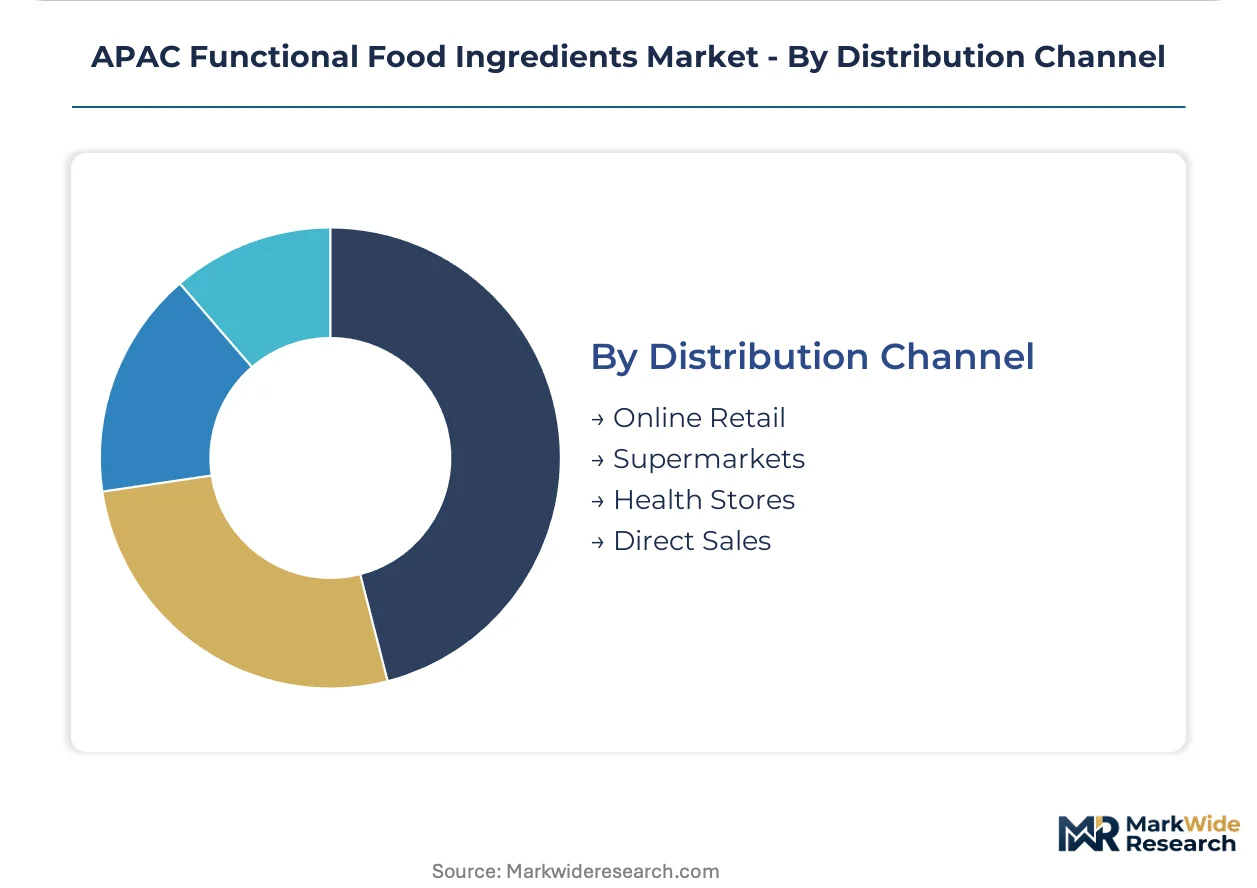
Channel selection determines margin capture versus volume velocity trade-offs across urban and tier-2 penetration strategies.
- Online Retail:Platform-specific SKUs on Reliance JioMart, Amazon India, and Tmall enabling direct brand-consumer relationships. Supplement brands are bypassing traditional pharmacy distribution through algorithm-driven personalization and subscription replenishment models.
- Supermarkets:Mass-market functional beverages and fortified staples in modern trade formats. China's Hema Fresh and Japan's AEON chains are allocating dedicated shelf space to FOSHU-labeled products with visible strain designations.
- Health Stores:Specialty retailers catering to enthusiast segments with practitioner-grade formulations.
- Direct Sales:Multi-level marketing and clinic-based dispensing for premium therapeutic nutrition.
Supermarkets dominate volume throughput; Online Retail is expanding most quickly as Indian and Southeast Asian logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban consumers across East Asian and South Asian metropolitan corridors are concentrating demand for clinically validated functional ingredients, with regulatory divergence between national frameworks fragmenting supplier compliance strategies.
China
Shanghai and Beijing manufacturers are absorbing GB standards compliance costs for vitamin premix traceability systems. SAMR registration timelines for novel probiotics extend commercialization cycles by 18-36 months. Dairy processors in Shandong province are hiring dedicated quality control teams to meet tightening contaminant thresholds.
Japan
Tokyo and Osaka food manufacturers prioritize FOSHU-authorized strain formulations for digestive health claims. METI-aligned clinical trial investments determine shelf placement in AEON and 7-Eleven chains. Kansai region fermentation facilities specialize in gastric acid-resistant Lactobacillus cultures.
India
Mumbai and Delhi modern trade buyers demand third-party assay certificates for immunity-positioned products. FSSAI fortification guidelines accelerate premix procurement by Maharashtra and Gujarat flour millers. Bangalore supplement brands bypass pharmacy distribution through Reliance JioMart platform-specific SKUs.
South Korea
Seoul CrossFit and marathon communities drive leucine-rich amino acid procurement with batch-tested purity documentation. MFDS regulations shape sports nutrition labeling requirements. Busan-Ulsan manufacturing corridors scale fermentation-derived protein isolate capacity for export markets.
Australia
Sydney and Melbourne health-conscious consumers prioritize TGA-registered supplement formats with verifiable active dosages. Pharmacy channel verification demands compress shelf space for unvalidated heritage brands. Queensland ingredient distributors expand cold-chain infrastructure for probiotic beverage logistics.
APAC Functional Food Ingredients Market Competitive Environment
North American and European multinationals anchor one tier; East Asian specialists hold differentiated positions in fermentation-derived ingredients and taste-system integration. The supplier base stratifies across three tiers: integrated nutrition conglomerates with oilseed and fermentation infrastructure, mid-scale premix blenders with country-specific regulatory capabilities, and niche strain developers serving FOSHU and TGA authorization pathways. Dominant competitive moves include capacity expansion in renewable-powered fermentation facilities and strategic partnerships with e-commerce platforms for direct-to-consumer supplement distribution.
Within the integrated conglomerate tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positions leveraging oilseed processing networks across East Asia. Kerry Group plc occupies a taste-and-nutrition integration specialist role with regional laboratory infrastructure. These three entities represent contrasting archetypes: agricultural commodity verticals, applied nutrition systems, and sensory-science platforms.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| BASF SE |
| DSM Nutritional Products |
| Ajinomoto Co., Inc. |
| Ingredion Inc |
| Tate & Lyle PLC |
| Arla Foods Ingredients Group P/S |
| Others |
Value Chain & Pricing Dynamics
Large flour millers and edible oil processors in Maharashtra and Gujarat operate on contract-based procurement models that index premix pricing to volume commitments and certification tiers. This buyer concentration amplifies negotiating leverage against mid-tier suppliers lacking FSSAI-authorized laboratory infrastructure.
Pricing Analysis
Short lead-time premiums for validated probiotic strains command 15-25% markups over standard inventory cycles in India's metropolitan procurement channels. Three-tier pricing structure across FOSHU-authorized, FSSAI-compliant, and unvalidated economy tiers separates Japanese clinical-grade formulations from Indian mass-market fortifiers. Cost compression in omega-3 isolates is intensifying because Peruvian catch-quota volatility feeds raw material uncertainty into processor margins. Pharmacy channel buyers in Mumbai and Delhi show highest price sensitivity, while sports nutrition brands in Seoul prioritize batch-tested purity documentation over unit economics.
Supply Chain Analysis
Marine oil supply rests on Peruvian and Chilean fisheries for omega-3 raw materials, while fermentation-derived amino acids draw from Chinese and South Korean bioreactor capacity. Probiotic culture banks concentrate in Danish, Japanese, and American specialist facilities with temperature-controlled distribution networks. Single-source vulnerability in Peruvian anchovy catch quotas exposes APAC processors to protein isolate cost spikes. Distribution runs through temperature-controlled logistics corridors from Busan-Ulsan manufacturing clusters into Southeast Asian retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology is displacing conventional spray-drying in heat-stable probiotic applications, forcing legacy suppliers to retool preservation infrastructure or cede ambient-stable beverage contracts.
For Market Incumbents: Hedge against fermentation capacity commoditization by securing renewable-powered facility certifications in Shandong and Hebei provinces. Anchor margin protection through backward integration into oilseed crushing networks that captive supply omega-3 precursors. Cargill-type agricultural conglomerates face margin compression from precision-fermentation entrants engineering amino acids without agricultural feedstocks. For New Entrants and Emerging Players: The mid-market gap between FOSHU-authorized premium strains and unvalidated economy cultures offers white-space entry for FSSAI-compliant intermediate tier suppliers. Target India's tier-2 cities where pharmacy channel verification demands are tightening but incumbent laboratory infrastructure remains thin. Launch platform-specific SKUs through Reliance JioMart's algorithmic personalization engines to bypass traditional distribution gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale premix blenders with dedicated Mumbai regulatory affairs teams during FSSAI harmonization turbulence. Long-term viability centers on suppliers bridging taste-system integration with clinical validation capabilities over the next decade. Watch MFDS and TGA authorization pathway convergence as the inflection signal for regional consolidation appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable-Powered Fermentation Capacity | China's dual carbon goals penalize carbon-intensive extraction, advantaging solar-powered bioreactor operators in Shandong. |
| FOSHU Clinical Trial Investment | Tokyo manufacturers securing METI-aligned strain validation capture premium shelf placement in AEON and 7-Eleven chains. |
| E-commerce Platform Partnership | Direct-to-consumer supplement brands on Amazon India and Tmall bypass pharmacy margin stacking through subscription replenishment. |
| Backward Integration into Oilseed Processing | Cargill-type infrastructure anchors omega-3 cost positions against marine oil price volatility from Peruvian quota restrictions. |
| Microencapsulation Technology Licensing | Thai and Vietnamese beverage manufacturers license spray-drying systems to launch ambient-stable SKUs without refrigeration dependency. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fermentation facility managers, FSSAI regulatory consultants, pharmacy procurement officers, and sports nutrition brand formulators combined with secondary validation from SAMR registration databases, FOSHU approval lists, and Indian customs import records. Bottom-up volume modeling across ingredient types triangulated against top-down category spending estimates from modern trade audit data.
Data-stream reconciliation integrated shipment volumes, production capacity disclosures, and channel inventory turns across the projection horizon. Segmentation dimensions modeled include ingredient type, application format, end-user sophistication tier, and distribution channel structure. CAGRs were derived from slope analysis of annualized growth trajectories. Forecast inputs incorporated FSSAI fortification mandate implementation pace and FOSHU authorization pathway throughput rates.
Inputs from SAMR, FSSAI, and MFDS regulatory databases were available through the study window; gaps in real-time probiotic strain registration timelines introduce uncertainty bands around novel ingredient commercialization forecasts. Assumptions regarding GB standards enforcement consistency and BIS-Codex harmonization pace could revise volume projections if regulatory timelines diverge from modeled pathways. A small set of triggers—marine oil quota announcements, renewable energy certificate pricing, and e-commerce platform commission structures—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
North America Functional Water Market