
 Beer Bottle Market | 2026-2036
Beer Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Bottle Market Intelligence
Large-scale glass manufacturing capacity is consolidating among a few multinational producers. O-I Glass leverages its extensive global production network to serve major breweries with standardized bottle formats. Ardagh Group specializes in sustainable glass and metal packaging solutions for a diverse range of beverage clients. Distributors like TricorBraun provide a crucial link to the fragmented craft brewer segment, offering flexible supply options and customized bottle designs.
A beer bottle is a rigid container, predominantly manufactured from amber or green glass, designed for packaging, carbonation retention, and preservation of beer. The container's chemical inertness and opacity to specific light wavelengths protect the beverage from degradation, ensuring flavor stability. Glass continues to dominate the material segment due to consumer perception of quality, though aluminum bottles are gaining traction in specific niches. Within capacity segments, the 330 ml and 500 ml formats remain standard for mass-market breweries.
Packaging standards are governed by food contact material regulations, such as those from the US FDA and the EU's REACH framework for chemical safety. In China, national GB standards dictate material composition and safety for all beverage containers. Navigating evolving bottle deposit schemes and extended producer responsibility laws in jurisdictions like Germany and Canada is becoming a central strategic challenge for all stakeholders in the value chain.
Market Dynamics
The beer bottle market's central dynamic is the tension between large-scale production efficiency for macro-breweries and the demand for flexible, customized packaging from the burgeoning craft beer sector. This requires a bifurcated supply chain strategy from glass manufacturers.
Growth Catalysts
- Craft Brewery Expansion:The proliferation of microbreweries and brewpubs, particularly in North America and Western Europe, drives demand for unique bottle shapes, sizes, and embossing to establish brand identity on crowded retail shelves.
- Lightweighting Technology:Innovations in narrow-neck press-and-blow (NNPB) manufacturing processes reduce glass mass per bottle. This lowers material and transportation costs for brewers while decreasing the overall carbon footprint of their packaging.
- Heritage Market Demand:Established beer markets, including Germany and the Czech Republic, exhibit consistent demand for glass bottles. Consumers in these regions associate glass with quality, tradition, and superior taste preservation for premium lagers and pilsners.
Market Restraints
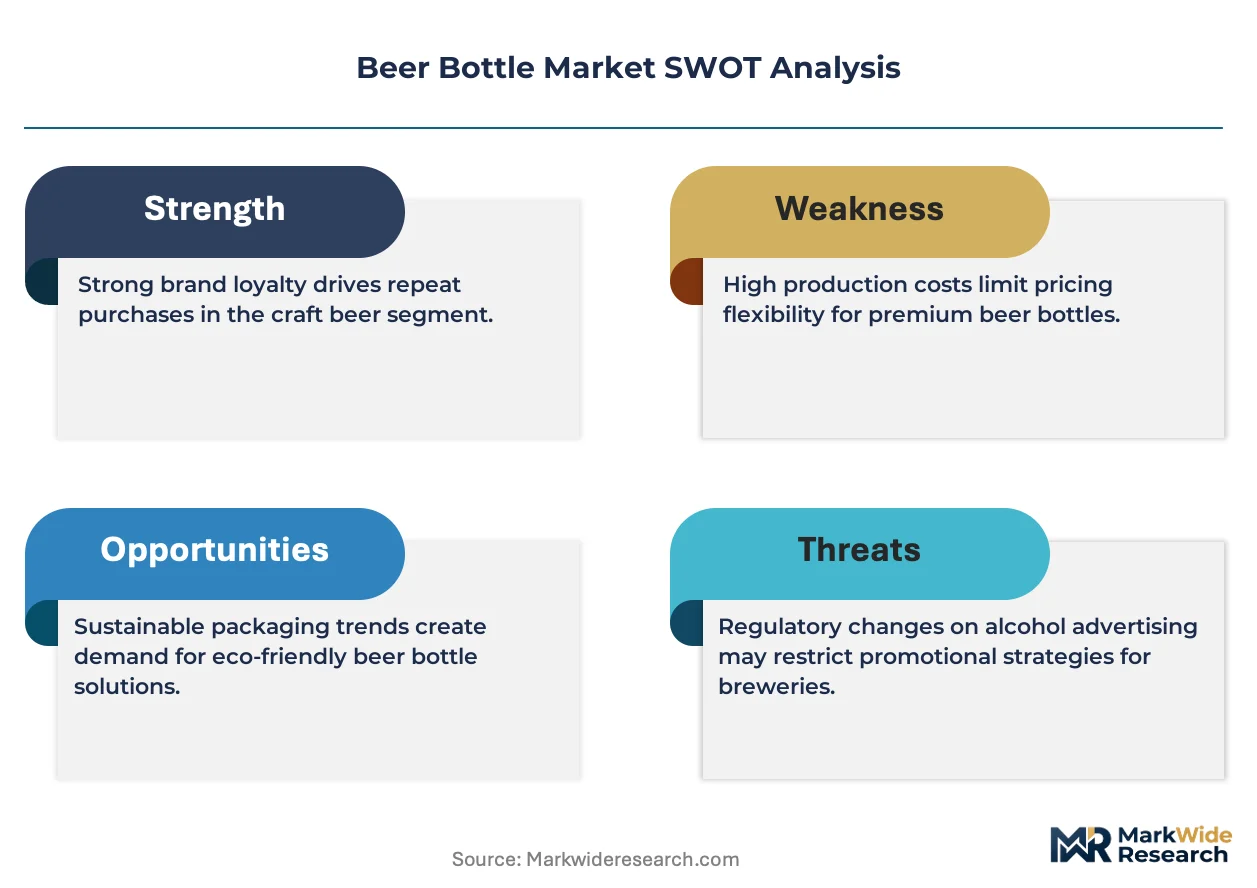
- Energy Price Volatility:Glass manufacturing is an energy-intensive process, with furnace operations highly dependent on natural gas. Fluctuations in global energy prices directly impact production costs, creating price instability for bottle purchasers.
- Substitution from Aluminum:Aluminum cans and bottles present a significant substitution threat, offering advantages in weight, shipping efficiency, and total light-blocking capability, which appeals to brewers focused on logistics and specific beer styles like IPAs.
- Consolidated Glass Supply:The supply of beer bottles is concentrated among a few large, multinational glass producers. This limits the negotiating power of even major breweries and can lead to supply constraints for smaller, non-contracted buyers.
Strategic Opportunities
- Small-Format Bottles:Developing smaller capacity bottles, such as 187 ml or 250 ml formats, creates opportunities for brewers to market high-ABV, barrel-aged, or limited-edition beers as premium, single-serving products.
- Circular Economy Alignment:Proactive engagement with bottle deposit schemes and extended producer responsibility (EPR) laws, such as those in Canada and parts of the EU, can position glass as a superior sustainable packaging choice.
- Digital Printing Integration:The convergence of direct-to-glass digital printing technology with bottling lines allows for late-stage customization. This enables craft brewers to produce short runs with varied label designs without requiring paper labels.
Industry Challenges
- High Capital Expenditure:The construction of new glass furnaces and forming lines requires immense upfront capital investment and long lead times. This high barrier to entry reinforces market concentration and limits supply-side agility.
- Regulatory Compliance Burden:Navigating the complex and divergent web of food contact material regulations, such as the EU's REACH framework and China's GB standards, alongside evolving recycling mandates, consumes significant administrative resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Bottle Market |
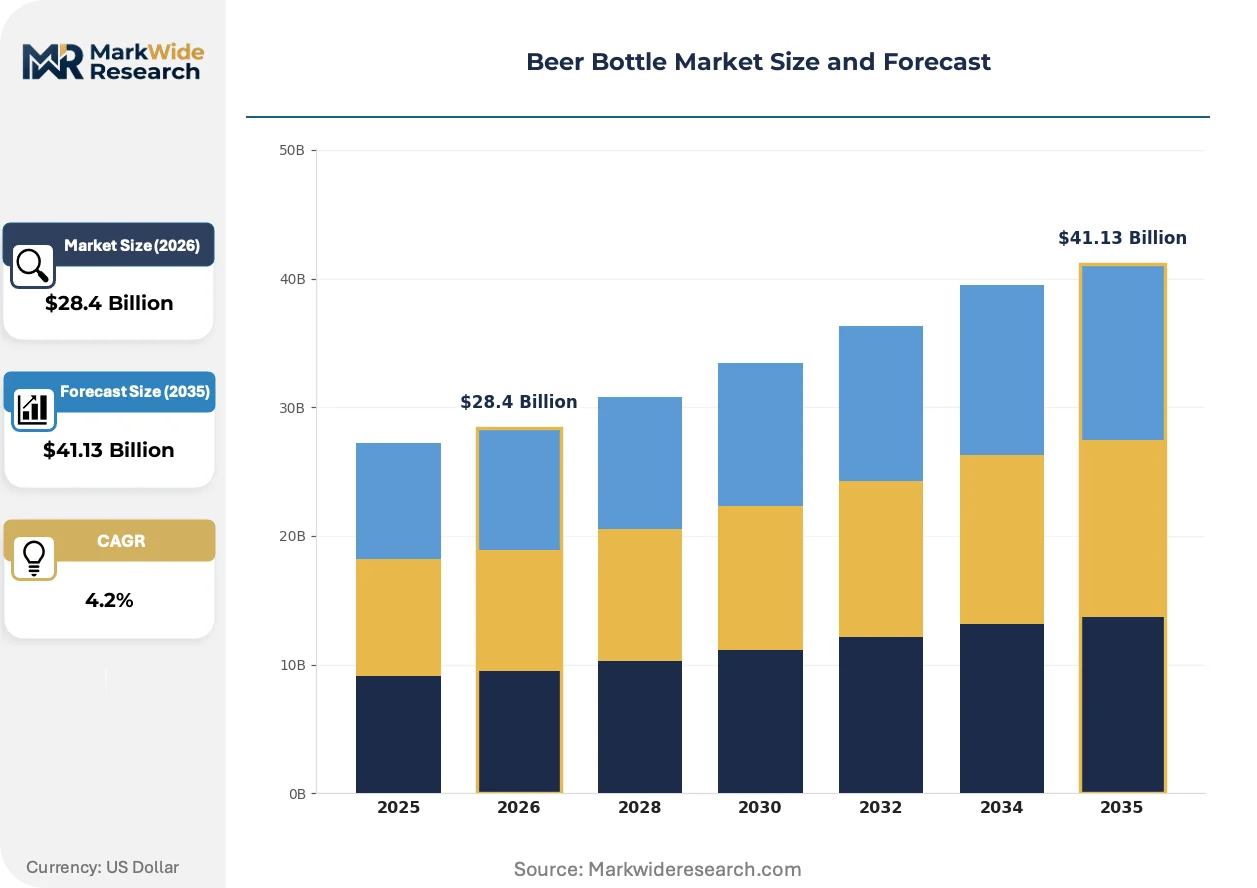
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Aluminum, PET, Tin, Steel Capacity: 250 ml, 330 ml, 500 ml, 750 ml, 1000 ml Closure Type: Crown Cap, Screw Cap, Flip Top, Synthetic Cork, Natural Cork End User: Brewery, Bar, Restaurant, Event Organizer, Retailer |
| Companies Covered | TP Glass Bottle, MJS Packaging, O-I Glass, TricorBraun, The Cary Company, Ardagh Group, Gallo Glass Company, WB Bottle Supply Co., Inc., Anchor Glass Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Bottle Market Strategic Shifts & Innovations
Sustainability mandates and digital technologies are fundamentally altering beer bottle manufacturing and design. These forces are compelling a shift from a purely volume-driven production model toward one that prioritizes material circularity, energy efficiency, and packaging differentiation for specific market segments.
Furnace technology advancements are a primary focus for decarbonization. The electrification of glass melting, which replaces natural gas burners with electric heating systems, is the core innovation. Major glass manufacturers are adopting this in response to both regulatory pressure and ESG commitments from their large brewery clients. This technological shift is electrifying the production process, enabling a lower carbon footprint and better aligning glass packaging with circular economy goals.
European Union regulations are setting a new global benchmark for packaging sustainability. The proposed Packaging and Packaging Waste Regulation (PPWR) introduces ambitious targets for recycled content and promotes reusable packaging systems. This directly impacts bottle design, material sourcing, and reverse logistics for all brewers operating in the EU. Producers in Germany and France are actively redesigning bottles and investing in collection infrastructure to comply with these future mandates.
Consumer purchasing behavior is shifting toward e-commerce and direct-to-consumer (DTC) channels, altering packaging needs. This movement away from traditional retail distribution requires more robust bottles and secondary packaging designed for parcel shipment. The trend is most prominent among craft brewers in the United States and the United Kingdom, who use online platforms to bypass distributors and connect directly with customers nationwide.
Beer Bottle Market Segmentation
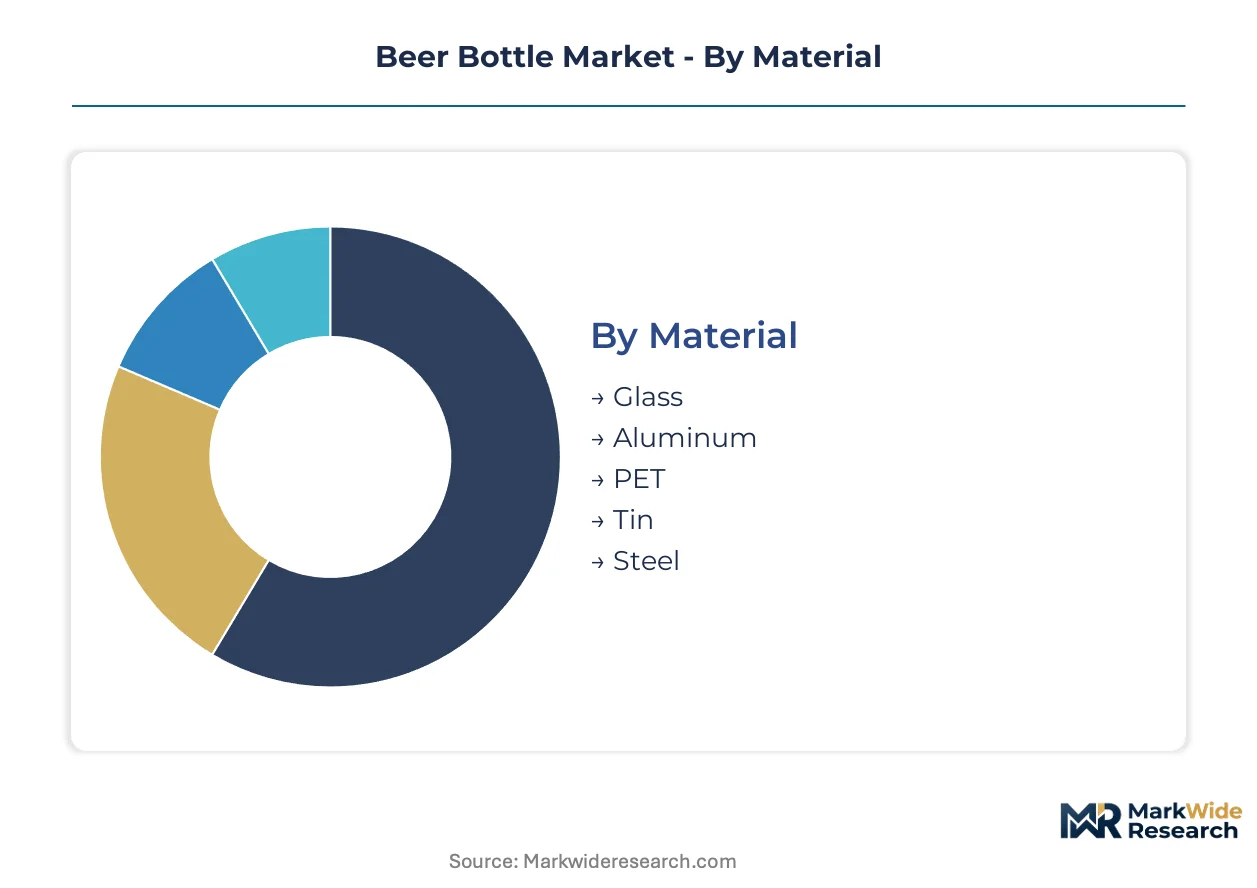
The beer bottle market's segmentation highlights the diverse packaging solutions required by brewers to meet consumer preferences and regulatory mandates. Understanding these distinct categories allows stakeholders to tailor product offerings and supply chain strategies effectively. Each segment reflects specific material properties, functional requirements, or end-user applications within the dynamic beverage industry.
Material:
The beer bottle market's material segmentation reflects ongoing shifts in packaging preferences driven by material innovation and sustainability mandates.
- Glass:This material forms the traditional backbone of beer packaging, valued for its chemical inertness and barrier properties against oxygen and UV light. Established beer markets, including Germany and the Czech Republic, maintain high demand for glass due to strong consumer associations with quality.
- Aluminum:Aluminum bottles offer significant advantages in weight reduction and complete light-blocking capabilities, which are particularly beneficial for light-sensitive beer styles like IPAs. Their lower shipping costs and recyclability appeal to brewers focused on logistics efficiency and environmental footprint reduction.
- PET:Polyethylene terephthalate bottles provide a lightweight, shatter-resistant alternative for specific applications like outdoor events or venues where glass is prohibited.
- Tin:Tin containers are less common for beer bottles but sometimes appear in specialty or limited-edition packaging for their unique aesthetic appeal.
- Steel:Steel is primarily used for larger kegs or growlers rather than individual bottles, offering robust durability for bulk transport and dispensing.
Volume placements concentrate in Glass; the faster expansion belongs to Aluminum.
Capacity:
Capacity segmentation directly influences consumer consumption patterns and product positioning across various beer styles.
- 330 ml:This capacity is a standard individual serving size, frequently adopted by craft breweries and for premium lagers in European markets. Its compact format supports multi-packs and single-serve premiumization strategies.
- 500 ml:The 500 ml bottle remains a prevalent format for mass-market lagers and everyday consumption, especially across European countries. This size balances consumer value with convenient handling for widespread distribution.
- 250 ml:Smaller capacity bottles cater to high-ABV, barrel-aged, or limited-edition beers, positioning them as premium single-serving products.
- 750 ml:This larger format is typically reserved for specialty beers, often corked, including Belgian ales, sours, or bottle-conditioned brews.
- 1000 ml:One-liter bottles, sometimes referred to as 'steins' or 'liter bottles,' are common for traditional German and Czech beers, reflecting cultural serving sizes.
The largest volume sales occur in the 500 ml segment, while 250 ml formats are gaining share quickly for premium offerings.
Closure Type:
Closure type differentiation caters to varying consumer convenience demands and preservation requirements for diverse beer products.
- Crown Cap:The traditional crown cap provides a highly secure and cost-effective seal, essential for retaining carbonation and protecting beer integrity. This closure dominates mass-market and craft beer packaging globally.
- Screw Cap:Screw caps offer resealability and convenience for consumers, gaining traction in markets where re-closing a bottle is a valued feature. Brewers of certain beer styles increasingly adopt this option.
- Flip Top:Flip top closures provide a reusable and distinctive sealing mechanism, often associated with traditional or artisanal beer brands.
- Synthetic Cork:Synthetic corks are used for specialty beers, particularly those designed for aging, offering a consistent seal without cork taint issues.
- Natural Cork:Natural cork closures are reserved for high-end, bottle-conditioned, or barrel-aged beers, imparting a premium perception and facilitating further maturation.
Crown Cap remains the dominant closure for carbonated beers, but Screw Cap adoption is accelerating for re-sealable convenience.
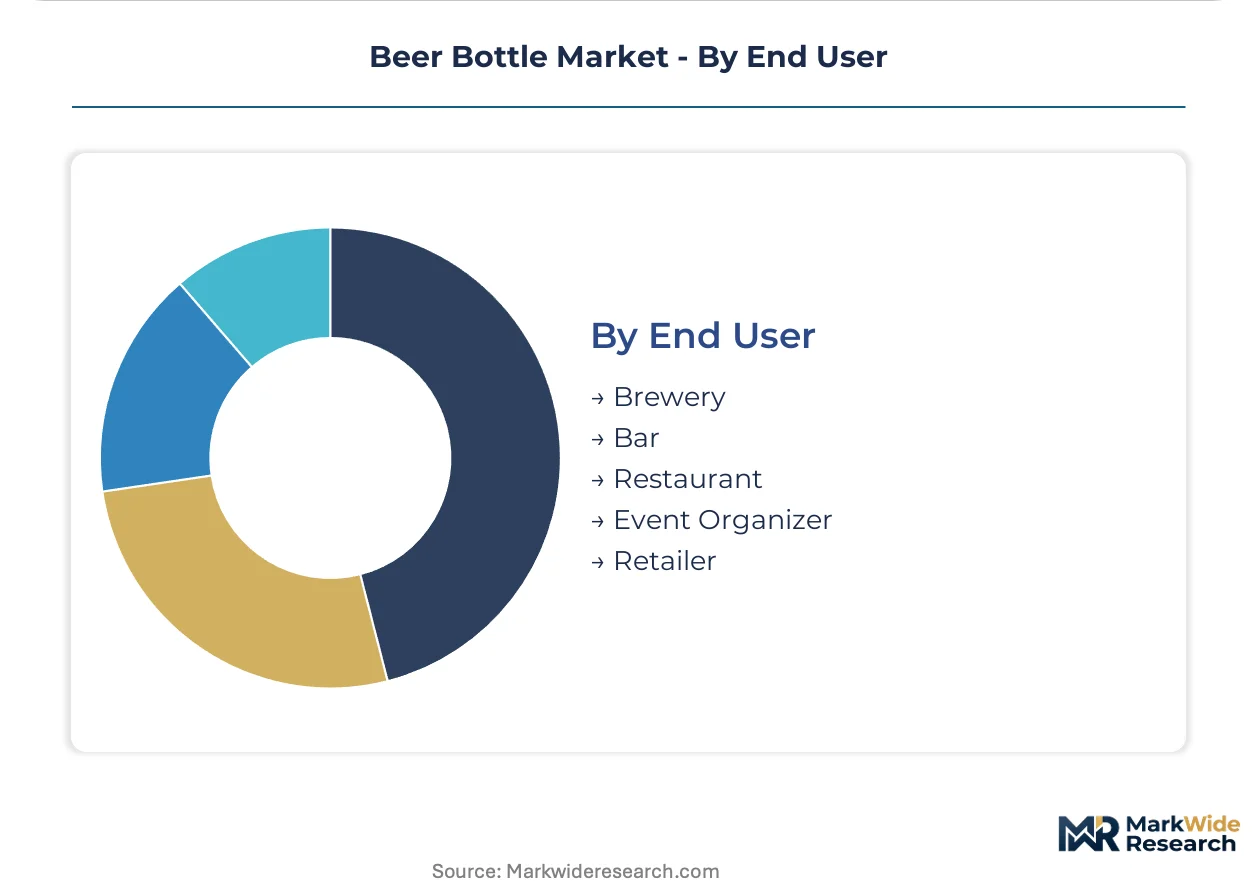
End User:
End-user segmentation determines bottle specifications and supply chain logistics, reflecting diverse business models within the beer industry.
- Brewery:Breweries represent the direct point of packaging, requiring bottles that align with their brand identity, production line specifications, and distribution models. Craft brewers often demand customized designs and smaller batch flexibility.
- Retailer:Retailers serve as the primary point of sale for packaged beer, influencing bottle design for shelf appeal and efficient display. Consumer purchasing decisions at retail drive demand for specific bottle formats and labeling.
- Bar:Bars primarily serve draft beer but also stock bottled options for variety or premium selections, often preferring specific capacities for individual servings.
- Restaurant:Restaurants offer bottled beer as part of their beverage menu, with bottle selection often aligning with the restaurant's cuisine or premium offerings.
- Event Organizer:Event organizers require bulk quantities of bottled beer, often prioritizing convenience, safety (e.g., non-glass options), and efficient handling for large crowds.
Retailer channels drive the largest bottle volumes, with Event Organizer demand showing significant seasonal peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, a major hub for glass manufacturing and beer consumption, anchors significant demand for beer bottles within the global market. Established beer markets and the expanding craft brewing sector drive bottle requirements across diverse geographies. Regional packaging regulations and consumer preferences shape specific bottle formats and material choices.
Germany
German consumers maintain a strong preference for glass bottles, associating them with quality and tradition for premium lagers and pilsners. The EU's Packaging and Packaging Waste Regulation (PPWR) heavily influences bottle design and recycling infrastructure here. Bavaria, with its rich brewing heritage, shows consistent demand for traditional glass formats and refillable systems.
United States
The United States market sees robust demand for distinctive packaging from its burgeoning craft brewery segment. The US FDA regulates food contact materials, ensuring safety for all beverage containers. California's craft brewing scene, particularly in cities like San Diego, drives innovation in bottle shapes and customized designs.
China
China's large and evolving beer market generates substantial demand for both mass-market and premium beer bottles. National GB standards dictate material composition and safety for all beverage packaging. The Yangtze River Delta region, a major economic zone, experiences high volume sales for standard bottle capacities due to its urban population density.
Canada
Canadian brewers navigate evolving bottle deposit schemes and extended producer responsibility (EPR) laws, which encourage sustainable packaging choices. Health Canada sets stringent safety standards for food contact materials. Ontario's craft brewing sector benefits from flexible supply options and customized bottle designs offered by local distributors.
Beer Bottle Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized packaging solutions for niche segments. The market structure features a mix of multinational corporations and regional specialists, creating a tiered competitive environment. Strategic archetypes include large-scale glass manufacturers, specialized packaging providers, and distribution intermediaries. Dominant competitive moves involve expanding production capacity and forming strategic partnerships to streamline supply chains.
Within the large-scale glass manufacturing tier, O-I Glass exemplifies global reach and standardized production for major breweries. Ardagh Group, an Ireland-based company, occupies a position as a specialist in sustainable glass and metal packaging solutions. TricorBraun, a US-based distributor, represents a crucial link to the fragmented craft brewer segment, offering flexible supply options and customized bottle designs.
| Leading Market Players |
|---|
| TP Glass Bottle |
| MJS Packaging |
| O-I Glass |
| TricorBraun |
| The Cary Company |
| Ardagh Group |
| Gallo Glass Company |
| WB Bottle Supply Co., Inc. |
| Anchor Glass Container Corporation |
| Others |
Cost & Logistics Intelligence
Energy costs, particularly for natural gas, directly influence glass manufacturing expenses, which then feed into the transactional pricing for mass-market bottle formats. This cost structure impacts the profitability of both producers and brewers.
Pricing Analysis
Value-added services, including customized bottle design and inventory management for craft brewers, are often bundled into long-term contracts. The dominant pricing structure is per-unit transactional, heavily influenced by volume scale and geographic delivery costs. Price differentiation arises from glass quality grade and specific certifications like those for food contact materials. Pricing softness reflects intense competition from alternative packaging and supply concentration among a few large producers. Craft brewers, requiring smaller batches and unique designs, exhibit lower price sensitivity compared to large breweries prioritizing cost efficiency.
Supply Chain Analysis
Silica sand, a primary raw material for glass, sources heavily from countries including Germany and the United States. Glass bottle manufacturing centers on a few multinational producers, leading to concentrated supply in Europe and North America. This concentration creates single-source vulnerability for smaller brewers. Natural gas price volatility for furnace operations represents a significant structural risk for the entire supply chain. Distribution runs through a bifurcated model, serving large breweries directly and craft brewers via specialized distributors like TricorBraun.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beer bottle market is entering a vertical-integration race, driven by glass manufacturers seeking to control raw material sourcing and optimize energy-intensive production processes. This strategy aims to stabilize costs and secure supply.
For Market Incumbents: Deploy advanced lightweighting technology to reduce material consumption and transportation costs, countering substitution threats from aluminum packaging. Consolidate production capacity in key European and North American regions to leverage economies of scale and optimize logistics. Invest in R&D for electric melting furnaces to meet ESG commitments from major brewery clients and mitigate energy price volatility. This defends against margin pressure from rising input costs and evolving sustainability mandates.
For New Entrants and Emerging Players: Launch specialized small-batch bottle production lines to serve the fragmented craft brewing sector in North America and Western Europe. Target the 250 ml premium segment for high-ABV or limited-edition beers, offering digital printing capabilities for late-stage customization. Focus on developing robust packaging for direct-to-consumer e-commerce channels in the United States and the United Kingdom. A flexible supply model through regional distributors provides the most penetrable segment entry.
For Investors and Strategic Acquirers: The widespread adoption of electric melting furnaces by major glass producers is the leading indicator that decarbonization efforts are becoming economically viable. Long-term viability for glass packaging over the next decade hinges on achieving material circularity and energy efficiency. Acquisition targets should be specialized packaging providers with strong R&D in sustainable glass or digital printing capabilities. The signal to watch is the market share growth of refillable bottle systems in Germany and Canada.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for NNPB Technology | Expanding NNPB technology capacity reduces glass mass, lowering transportation costs for brewers. |
| Investment in Electric Melting | Electric melting furnace investment lowers the carbon footprint of glass production for O-I Glass. |
| Digital Printing Integration | Digital printing integration enables craft brewers to customize short runs without paper labels. |
| Circular Economy Infrastructure | Developing collection infrastructure aligns with EU PPWR and strengthens glass's sustainable position. |
| Small-Format Bottle Development | Developing 250 ml formats enables premium single-serving products for high-ABV beers. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and trade association data underwrites the qualitative findings. Primary interviews with brewery procurement managers, glass manufacturing executives, and packaging distributors provided granular insights. Secondary data from governmental agencies like the US FDA and EU REACH framework, alongside company 10-K filings, validated market dynamics. A bottom-up and top-down triangulation approach ensured data consistency.
Rate-of-change decomposition models market expansion across the analysis window, segmenting by material, capacity, closure type, and end-user. Growth rates were derived from historical data analysis and projected demand shifts, particularly for craft beer. Key inputs included global beer consumption trends and glass manufacturing capacity utilization. This framework provides a robust outlook for the beer bottle market.
Energy price volatility, evolving packaging regulations, and aluminum substitution are the dominant revision risks for future forecasts. These projections reflect current assumptions about technological adoption and consumer preferences. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Beer Fermenter Market