
 Ice Flaking Machine Market | 2026-2036
Ice Flaking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Flaking Machine Market Intelligence
The divergence between high-capacity, automated systems and smaller, standalone units is recalibrating the market's competitive landscape. GEA Group AG specializes in large-scale refrigerated flakers for industrial seafood processing and concrete cooling. Hoshizaki America, Inc. leverages its strong distribution network to serve the food service sector. Scotsman Ice Systems differentiates with energy-efficient designs across its commercial product lines.
Ice flaking machines are refrigeration systems that produce thin, sub-cooled ice fragments, ideal for rapid cooling. These units typically operate by freezing water onto a refrigerated drum, which is then scraped off to create flakes with a large surface-to-volume ratio. Refrigerated flakers constitute the largest product type segment, serving high-volume needs. The seafood processing application continues to be the primary volume driver, with food processing plants representing the largest end-user category.
Regulatory frameworks from the US EPA and the EU via its F-Gas Regulation are compelling a shift away from high-GWP refrigerants. Food safety standards, enforced by bodies like the FDA and EFSA, dictate the materials used in components that contact water and ice. Consequently, vendor success hinges on navigating these dual pressures of environmental compliance and material safety. Future competitiveness will be defined by the ability to engineer energy-efficient systems using compliant refrigerants.
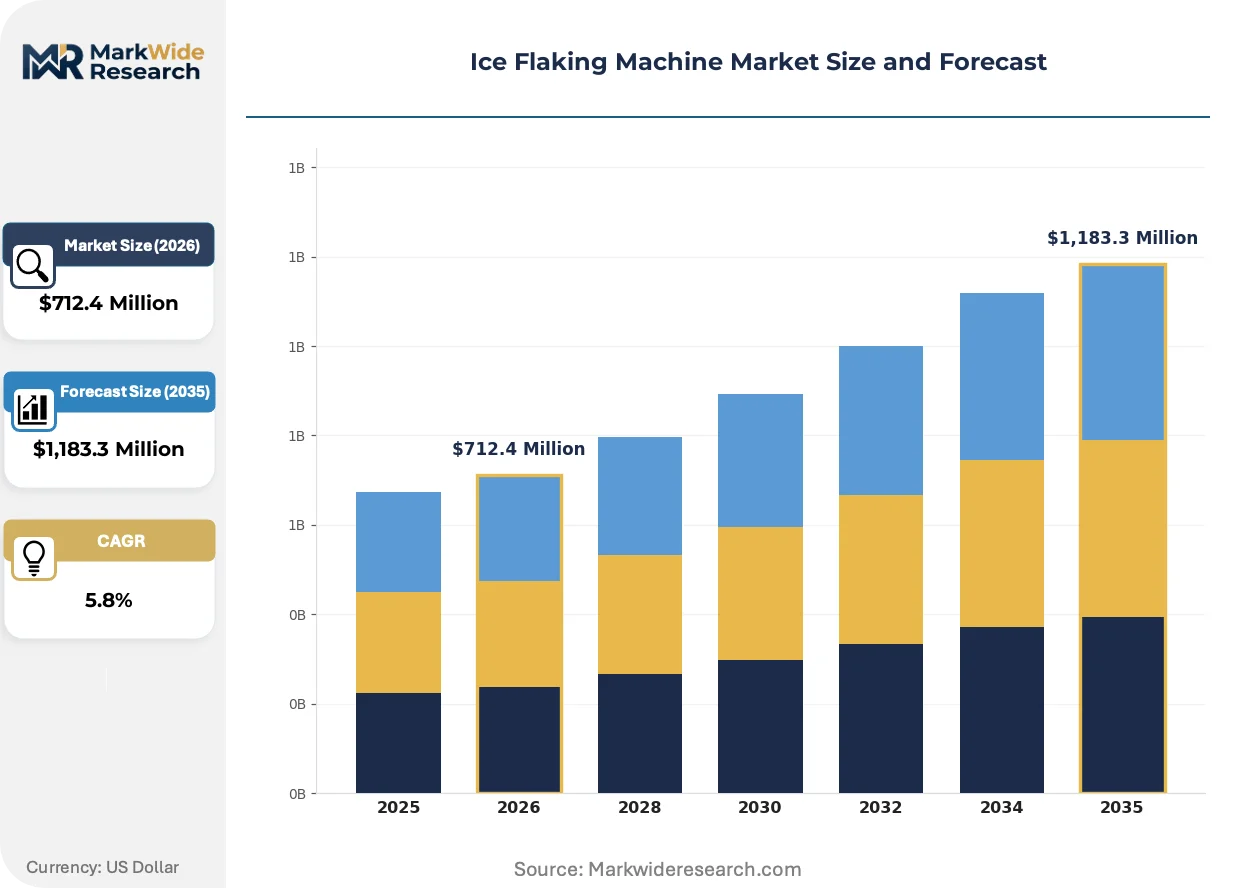
Market Dynamics
The convergence of stringent environmental regulations on refrigerants and food safety mandates on materials of construction is the central force shaping product design. This dual pressure compels manufacturers to innovate on both cooling system architecture and ice-contact surface engineering, defining the competitive landscape.
Growth Catalysts
- Seafood Industry Demand:The global seafood processing sector's need to preserve catch quality from vessel to market remains the primary volume driver for high-capacity flaking systems.
- Regulatory Mandates:The EU F-Gas Regulation is accelerating the development and adoption of systems using lower GWP refrigerants, creating a replacement cycle for older equipment.
- Industrial Applications:Use in large-scale concrete cooling for major construction projects and in chemical processing provides a stable source of demand for industrial-grade flakers.
Market Restraints
- High Capital Cost:The significant upfront investment required for large-scale, automated ice flaking systems presents a barrier to entry for smaller food processing operations.
- Energy Consumption:Older or poorly maintained units exhibit high energy consumption, representing a substantial portion of the total cost of ownership and deterring some potential buyers.
- Substitution Risk:In less critical, low-volume applications, readily available and lower-cost cubed or crushed ice can serve as a functional substitute for flake ice.
Strategic Opportunities
- Biomedical Sector Expansion:Penetration into laboratories, hospitals, and life science research facilities for precise sample cooling and preservation represents a high-margin growth vector.
- Low-GWP Retrofitting:The phase-out of high-GWP refrigerants under frameworks like the US EPA's SNAP program creates a service-based opportunity for retrofitting and replacing existing systems.
- Emerging Market Food Chains:Expansion of modern food retail and quick-service restaurants in Southeast Asia and Latin America opens new markets for compact, commercial-grade units.
Industry Challenges
- Compliance Navigation:Managing the complex, multi-layered certification process for both refrigerant use via the EPA and food contact materials via NSF or EFSA extends product development timelines.
- Technician Skill Gap:A shortage of service technicians trained to handle new-generation natural refrigerants, such as CO2 and propane, impedes maintenance and repair capabilities in the field.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Flaking Machine Market |
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Flakers, Direct Expansion Flakers, Indirect Expansion Flakers, Hybrid Flakers, Rotary Drum Flakers Technology: Compression Cooling, Absorption Cooling, Cascade Cooling, Thermoelectric Cooling, Magnetic Cooling Application: Seafood Processing, Concrete Cooling, Fishery, Laboratory Use, Chemical Preservation End User: Cold Storage Facilities, Food Processing Plants, Pharmaceutical Labs, Restaurants, Sports Complexes |
| Companies Covered | BUUS Refrigeration A/S, Focusun Refrigeration Corporation, Follett LLC, GEA Group AG, Hoshizaki America, Inc., Scotsman Ice Systems, Manitowoc Ice, MAJA-Maschinenfabrik Hermann Schill GmbH, Ice-O-Matic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Flaking Machine Market Strategic Shifts & Innovations
Efficiency and regulatory compliance are the primary themes driving innovation. Manufacturers are focusing on developing systems that reduce energy and water consumption while simultaneously adhering to evolving global standards for refrigerant use and food safety, creating a new basis for competition.
Smart control systems integrated with IoT connectivity allow for remote monitoring and diagnostics. Food service chains and large industrial processors are adopting these systems to optimize energy usage, ensure operational uptime, and schedule predictive maintenance. This data-driven approach to equipment management is overtaking traditional, reactive service models and reducing the total cost of ownership for end-users.
The EU F-Gas Regulation mandates a progressive phase-down of hydrofluorocarbons based on their Global Warming Potential. This regulation compels manufacturers to redesign refrigeration circuits for natural refrigerants like CO2 and propane. The commercial food service segment is most affected, accelerating a transition to compact, self-contained units using compliant, low-GWP cooling agents.
A clear preference for certified energy and water efficiency is emerging among institutional buyers. This shifts purchasing criteria away from initial capital cost toward total lifecycle cost, favoring models with ENERGY STAR or equivalent certifications. The trend is most pronounced in the United States and European Union hospitality sectors, driven by corporate sustainability goals.
Ice Flaking Machine Market Segmentation
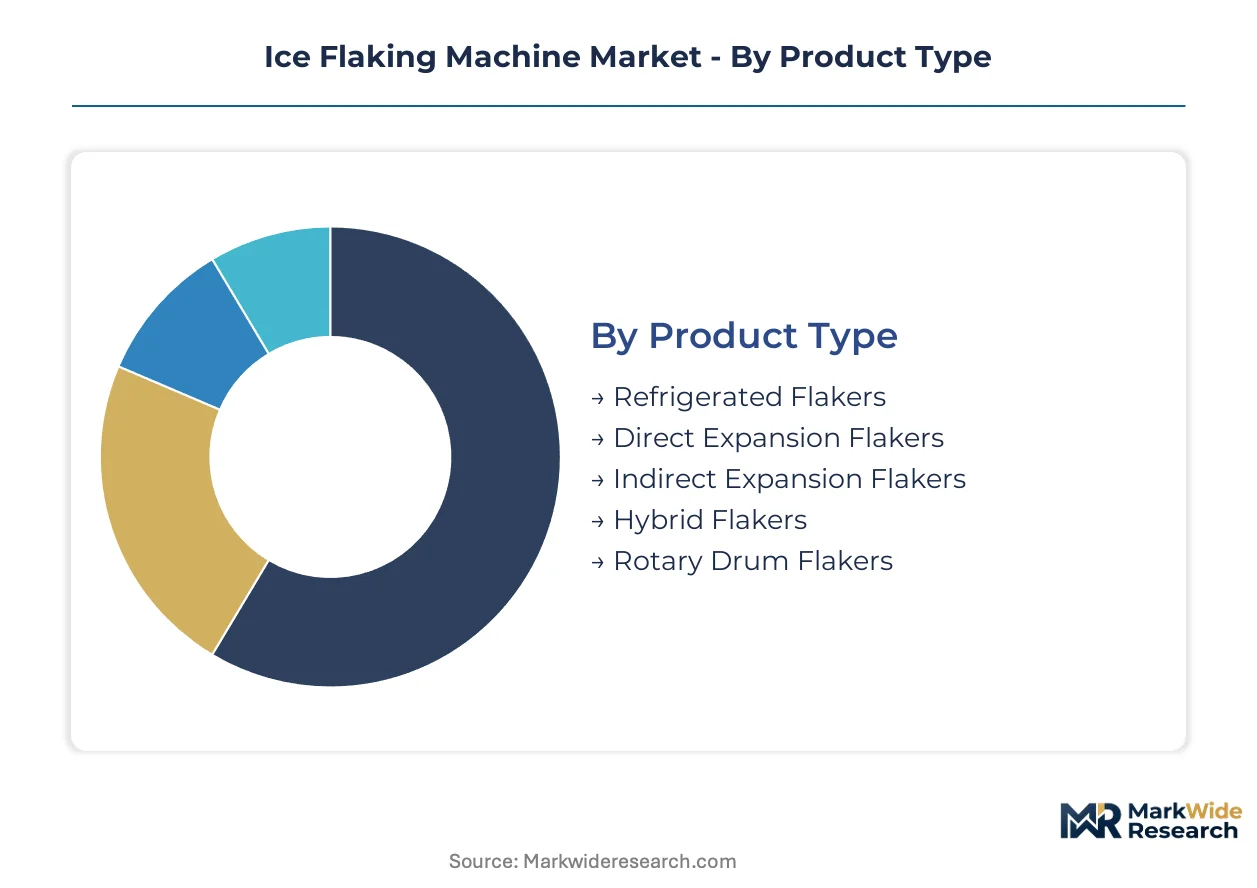
Understanding the segmentation of the ice flaking machine market reveals how diverse end-user needs drive product development and market dynamics. This analysis highlights the specific attributes and applications that define competitive niches and growth opportunities within the industry.
Product Type:
The product type segmentation highlights the spectrum from standardized units to highly customized systems tailored for specific operational demands.
- Refrigerated Flakers:These systems produce thin, sub-cooled ice fragments by freezing water onto an internal drum, then scraping it off. Demand from food processing plants for high-volume, rapid cooling remains a primary driver.
- Rotary Drum Flakers:These machines feature a rotating drum where water freezes and is subsequently harvested as flakes, offering continuous, high-capacity ice production. Large-scale industrial applications, such as concrete cooling, concentrate demand.
- Direct Expansion Flakers:These units directly cool the ice-forming surface using refrigerant, offering efficient heat transfer.
- Indirect Expansion Flakers:These systems use a secondary fluid to transfer cooling to the ice-forming surface, enhancing operational flexibility.
- Hybrid Flakers:Hybrid models combine different cooling mechanisms or ice production methods to optimize performance for varied requirements.
Most installed capacity flows through Refrigerated Flakers. Expansion is steepest in Hybrid Flakers.
Technology:
The technology segmentation reflects varying cost structures and energy efficiency profiles, influencing initial investment and operational expenditure.
- Compression Cooling:This widely adopted technology uses a compressor to circulate refrigerant, making it the most common method for ice flaking machines. Its prevalence is driven by a balance of cost-effectiveness and reliable performance across commercial applications.
- Cascade Cooling:Cascade systems employ two refrigeration circuits with different refrigerants to achieve very low temperatures, crucial for specific industrial processes and specialized ice production. Regulatory shifts towards lower GWP refrigerants influence its adoption.
- Absorption Cooling:These systems utilize heat rather than mechanical compression to drive the refrigeration cycle, offering an alternative for waste heat recovery.
- Thermoelectric Cooling:Based on the Peltier effect, this technology provides compact, solid-state cooling solutions for smaller, specialized ice flaking units.
- Magnetic Cooling:This emerging technology uses magnetocaloric materials for refrigeration, promising higher efficiency and environmental benefits in future designs.
Compression Cooling dominates the installed base. Magnetic Cooling is climbing the fastest due to its innovative potential.
Application:
The application segmentation highlights the diverse operational environments and specific ice quality demands influencing machine selection.
- Seafood Processing:This application demands rapid and consistent flake ice to maintain the freshness and quality of catch from harvesting to market. Demand from global fishing fleets and shore-based processing plants drives significant volume.
- Concrete Cooling:Flake ice is essential in large construction projects to control concrete temperature during mixing and curing, preventing cracking from exothermic reactions. Major infrastructure developments globally sustain demand for these industrial-grade systems.
- Fishery:This segment involves onboard and dockside ice production for preserving freshly caught fish, ensuring product integrity throughout the supply chain.
- Laboratory Use:Precise temperature control and sterile ice are critical for scientific experiments and sample preservation in research and medical facilities.
- Chemical Preservation:Flake ice provides controlled cooling for various chemical reactions and material storage, preventing degradation and ensuring process stability.
Seafood Processing represents the largest volume. Laboratory Use is gaining share fastest, driven by biomedical sector expansion.
End User:
The end-user segmentation differentiates between industrial-scale consumers and commercial entities, each with distinct volume and operational requirements.
- Food Processing Plants:These facilities require high volumes of flake ice for chilling ingredients, maintaining product temperature during processing, and preserving finished goods. Stringent food safety standards from bodies like the FDA and EFSA influence equipment choices.
- Restaurants:Quick-service and fine-dining establishments use flake ice for beverage service, salad bars, and temporary food preservation, prioritizing compact and efficient units. North American food service demand for efficient units is notable.
- Cold Storage Facilities:These operations use flake ice to supplement refrigeration systems and maintain optimal temperatures for perishable goods during storage and transit.
- Pharmaceutical Labs:Laboratories require precise, contamination-free flake ice for research, sample cooling, and controlled environment applications, often seeking specialized units.
- Sports Complexes:Ice flaking machines provide ice for injury treatment, cold therapy, and maintaining cold food and beverage stations within athletic facilities.
Food Processing Plants constitute the largest end-user category. Pharmaceutical Labs exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized engineering talent for refrigeration systems across key manufacturing hubs anchors the global ice flaking machine market. These regions combine advanced industrial capabilities with stringent regulatory environments. This fosters innovation in energy-efficient and compliant ice production technologies.
United States
Demand for compact, efficient units from the food service sector drives ice flaking machine adoption. The US EPA's SNAP program mandates a shift towards lower GWP refrigerants, creating a replacement cycle for older equipment. California's stringent environmental regulations further accelerate this transition, impacting equipment procurement across the West Coast food industry.
Germany
Industrial food processing and chemical preservation applications generate substantial demand for high-capacity flaking systems. The EU F-Gas Regulation compels manufacturers to integrate natural refrigerants into new cooling system designs. Engineering hubs in Bavaria and North Rhine-Westphalia focus on developing precise, energy-efficient units for pharmaceutical and laboratory uses.
China
Large-scale infrastructure projects requiring concrete cooling and a rapidly expanding seafood processing industry fuel demand. China's dual carbon goals and MEE standards are influencing the adoption of more environmentally friendly refrigeration technologies. Manufacturing clusters in the Yangtze River Delta are scaling production of industrial-grade flakers for domestic and export markets.
Brazil
Expansion of modern food retail and quick-service restaurants creates new opportunities for commercial-grade ice flaking units. The country's national environmental regulations are gradually pushing for more sustainable industrial practices. Sao Paulo's burgeoning food service and hospitality sectors are driving localized demand for compact, efficient ice production solutions.
Japan
The robust fishery and food processing sectors require reliable ice flaking machines for product preservation. METI initiatives encourage energy efficiency and technological advancement in industrial refrigeration equipment. Manufacturing facilities in the Kansai region specialize in precision engineering for advanced, automated ice flaking systems.
Ice Flaking Machine Market Key Industry Players
Top-tier vendors anchor the high-capacity, industrial segment, while specialized manufacturers focus on niche applications and compact units. The market structure exhibits a tiered consolidation, with a few large players dominating industrial and commercial segments globally. Strategic archetypes include large industrial solution providers, commercial equipment specialists, and emerging technology innovators focusing on low-GWP refrigerants. Geographic expansion into emerging markets and portfolio diversification into biomedical applications represent dominant competitive moves among these players.
Within the industrial solution provider archetype, GEA Group AG occupies a significant position with its focus on large-scale refrigerated flakers for industrial seafood processing and concrete cooling applications across multiple continents. Hoshizaki America, Inc. exemplifies a commercial equipment specialist, leveraging its strong distribution network to serve the diverse needs of the food service sector, particularly in North America. Scotsman Ice Systems represents another commercial specialist, known for its commitment to energy-efficient designs across its broad commercial product lines, appealing to institutional buyers. These companies collectively anchor different segments of the market, from high-volume industrial demand to compact, efficient food service units, defining their respective competitive niches.
| Leading Market Players |
|---|
| BUUS Refrigeration A/S |
| Focusun Refrigeration Corporation |
| Follett LLC |
| GEA Group AG |
| Hoshizaki America, Inc. |
| Scotsman Ice Systems |
| Manitowoc Ice |
| MAJA-Maschinenfabrik Hermann Schill GmbH |
| Ice-O-Matic |
| Others |
Cost & Logistics Intelligence
Global steel price fluctuations impact the cost of stainless steel components, cascading through the ice flaking machine supply chain and influencing final product pricing tiers for both industrial and commercial units. This affects manufacturers' ability to maintain stable margins across diverse product lines.
Pricing Analysis
Bundled service contracts, integrating installation and long-term maintenance, differentiate pricing for high-capacity industrial flakers from standalone commercial unit sales. Project-based pricing dominates large-scale system deployments, reflecting customization and complex integration needs. Energy efficiency certifications, like ENERGY STAR, drive price differentiation, allowing premium pricing for models with lower operational costs. Pricing pressure stems from intense competition in the commercial segment, particularly for compact units, while industrial buyers demonstrate lower price sensitivity due to critical application requirements and total cost of ownership considerations.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns facilitate efficient delivery of commercial ice flaking machines to food service and hospitality sectors. Manufacturing concentrates in Germany, Japan, and China, which are key global production hubs for refrigeration components and finished systems. The supply chain relies heavily on specialized compressors, stainless steel, and low-GWP refrigerants. Regulatory restrictions on high-GWP refrigerants represent a structural supply chain risk, compelling manufacturers to re-engineer product lines. Downstream distribution typically runs through specialized equipment dealers and direct sales teams for industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ice flaking machine market is evolving into a late-cycle quality story, driven by a pronounced demand-shift towards energy-efficient and environmentally compliant systems, particularly in regulated geographies.
For Market Incumbents:
Lock in long-term refrigerant supply agreements to mitigate volatility and ensure compliance with evolving regulations like the EU F-Gas Regulation. Invest heavily in R&D for next-generation natural refrigerant systems, anticipating the technician skill gap as a future constraint. Expand certified service networks to maintain operational uptime for high-value industrial clients, countering the threat of specialized third-party maintenance providers. Leverage existing channel control to push high-efficiency models.
For New Entrants and Emerging Players:
Specialized B2B e-commerce platforms offer a direct route to market for compact, energy-efficient units targeting smaller food service operations. Penetration into the biomedical sector, particularly for laboratory use, represents a high-margin white-space opportunity. Focus on providing low-GWP compliant solutions tailored for emerging market food chains in Southeast Asia, where demand for modern refrigeration is expanding. Emphasize modular designs for easier installation and maintenance.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized technology firms developing advanced low-GWP refrigeration circuits or smart control systems. The long-term viability of this market hinges on continuous innovation in energy efficiency and regulatory compliance. Target regional service providers with strong technician training programs for natural refrigerants, addressing the looming skill gap. The accelerated adoption rate of CO2 and propane-based systems in commercial segments serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop low-GWP refrigerant systems | Ensures compliance with environmental regulations and captures demand from sustainability-focused buyers. |
| Expand certified service technician networks | Addresses the critical skill gap for natural refrigerants, ensuring reliable after-sales support. |
| Acquire specialized control system developers | Integrates IoT capabilities for predictive maintenance and optimized energy consumption in flaking units. |
| Target emerging market food retail chains | Opens new volume opportunities for compact, commercial-grade units in high-growth regions. |
| Invest in advanced material science for ice-contact surfaces | Enhances food safety compliance and extends equipment lifespan in demanding processing environments. |
Research Approach
Direct dialogue with refrigeration engineers, plant managers, procurement heads, and food safety officers provided qualitative grounding for this analysis. Secondary validation drew from US EPA reports, EU F-Gas Regulation documents, FDA guidelines, and company financial statements. This approach combined bottom-up market sizing with top-down validation to ensure data integrity.
A bottom-up analytical lens was applied to forecast market growth across the analysis window, aggregating demand from key end-user segments. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical data trends and projected shifts in technology adoption and regulatory mandates. Key forecast inputs included refrigerant phase-down schedules and global seafood catch volumes.
The model assumes a particular technology adoption path; alternative pathways for magnetic cooling would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement and economic stability in key regions. Unforeseen raw material supply disruptions or accelerated climate policy shifts represent specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market