
 Flame-Retardant Phosphate Esters for EV E-Drivetrains Market | 2026-2036
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market Size, Share, and Industry Trends Forecast 2026-2036
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market Insights
Software-defined thermal management subscriptions is realigning how flame-retardant phosphate esters get specified into long-term supply contracts. ICL Group leverages its integrated phosphorus supply chain to dominate technical-grade triphenyl phosphate output for European OEMs. LANXESS anchors its position through specialized halogen-free formulations that meet emerging motor cooling fluid specifications. BASF SE competes on R&D intensity, sustaining patent coverage across isopropylated triphenyl phosphate synthesis routes.
Flame-retardant phosphate esters for EV e-drivetrains are organophosphorus compounds, typically featuring aryl or alkyl-aryl substituents, that function by forming char layers and scavenging free radicals at temperatures above 300°C to suppress combustion in high-voltage electrical systems. Their primary industrial purpose centers on replacing halogenated flame retardants in battery thermal management fluids and powertrain insulation where thermal runaway propagation must be contained. Among product types, resorcinol bis(diphenyl phosphate) leads volume allocation due to its superior hydrolytic stability in glycol-based coolants, while isopropylated triphenyl phosphate represents the fastest-growing category as OEMs seek lower-viscosity formulations for direct motor cooling applications. By deployment mode, OEM integration captures the dominant margin pool since Tier-1 supplier solutions face persistent price compression from captive blending operations at major battery pack producers.
REACH restrictions on halogenated alternatives and the EU F-Gas Regulation on fluorinated cooling media are redirecting formulation demand toward aryl phosphate esters in European electric vehicle manufacturing. China's MIIT new-energy vehicle safety standards and GB/T battery testing protocols mandate flame-retardant performance in thermal management fluids, creating compliance-driven procurement thresholds for domestic suppliers. In the United States, EPA scrutiny of persistent organic pollutants and NHTSA battery safety guidelines shape product qualification timelines for phosphate ester entrants. Stakeholders must monitor how regulatory divergence between Brussels and Beijing on additive concentration thresholds affects formulation standardization across multinational supply contracts.
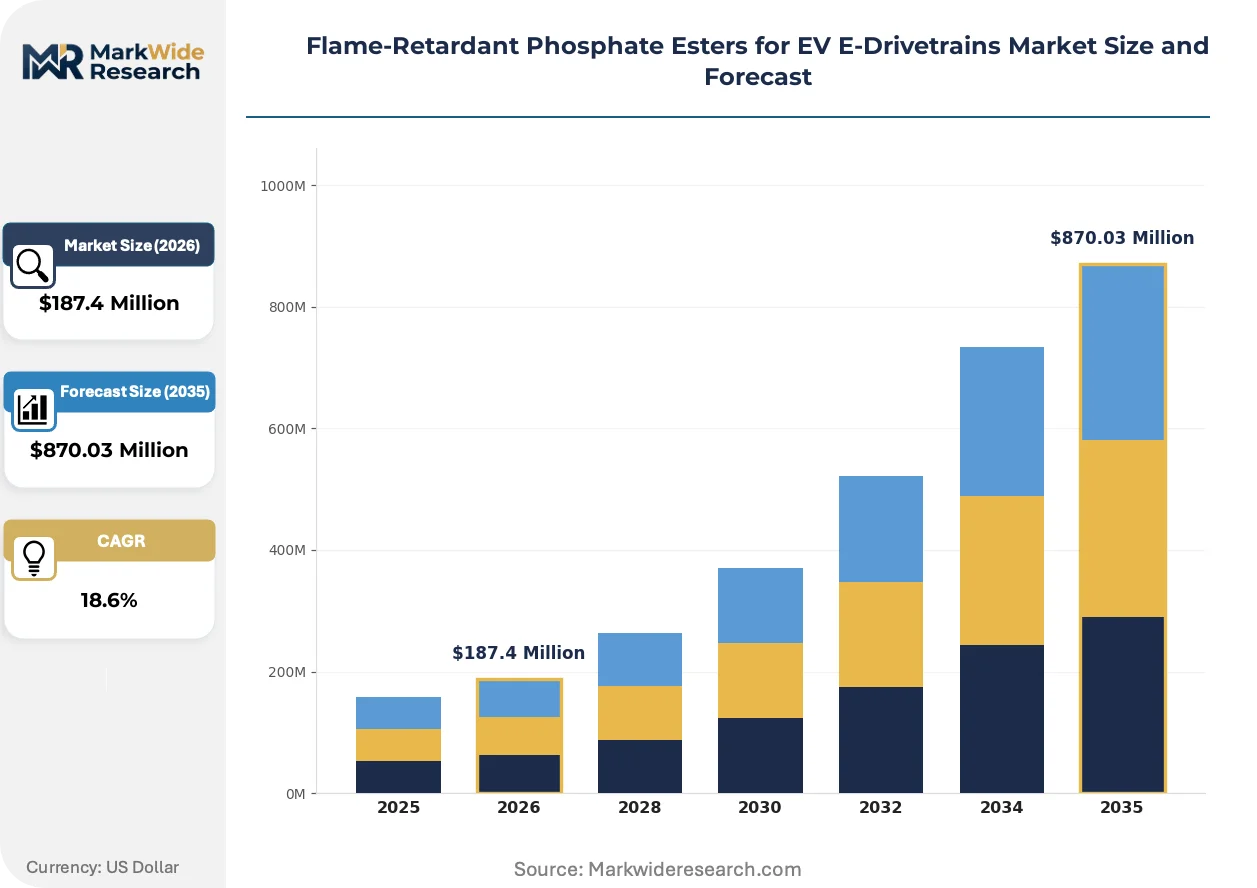
Market Dynamics
The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants are forcing battery pack producers and OEMs to requalify thermal management fluids around aryl phosphate esters, compressing formulation timelines and reshaping long-term supply contracting.
Growth Catalysts
- EU Green Deal material safety mandates:Battery thermal management fluid specifications in Germany and France now require halogen-free flame-retardant performance, directing procurement toward resorcinol bis(diphenyl phosphate) formulations.
- China's MIIT new-energy vehicle safety standards:GB/T battery testing protocols mandate flame-retardant additives in glycol-based coolants, creating compliance thresholds that domestic Jiangsu province suppliers must meet for CATL and BYD integration.
- Direct motor cooling applications:Lower-viscosity isopropylated triphenyl phosphate is gaining traction as OEMs redesign powertrain thermal architectures around single-loop cooling systems.
Market Restraints
- Phosphorus feedstock concentration:Technical-grade triphenyl phosphate output depends on captive phosphate rock processing in Morocco and China, exposing European formulators to raw material access risk.
- Hydrolytic stability limitations:Alkyl-aryl phosphate esters degrade in aqueous coolant environments above 120°C, restricting deployment in high-temperature battery pack designs.
- Fluorinated cooling media substitution:Partial recovery of PFAS-based thermal fluids for extreme-performance motorsports and aviation applications fragments demand in premium EV segments.
Strategic Opportunities
- US EPA persistent organic pollutant scrutiny:NHTSA battery safety guidelines and state-level chemical disclosure rules are opening qualification pathways for phosphate ester entrants in Michigan and California manufacturing clusters.
- Solid-state battery thermal interface materials:Next-generation cell architectures require flame-retardant potting compounds and gap fillers, extending phosphate ester application beyond liquid coolants.
- Software-defined thermal management subscriptions:OEMs are unbundling fluid specification from hardware procurement, creating service-contract channels for formulation suppliers with predictive monitoring capabilities.
Industry Challenges
- REACH registration dossier complexity:ECHA substance evaluation timelines for novel isopropylated triphenyl phosphate derivatives extend commercialization cycles by 18-24 months.
- Formulation-service integration:Battery pack producers are internalizing blending operations, compressing margins for independent phosphate ester compounders and forcing capability investments in application engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame-Retardant Phosphate Esters for EV E-Drivetrains Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triphenyl Phosphate, Tricresyl Phosphate, Resorcinol Bis(Diphenyl Phosphate), Isopropylated Triphenyl Phosphate, Phenylcresyl Phosphate Application: Electric Powertrain Insulation, Battery Thermal Management, Motor Cooling Fluids, Electronic Components Protection, Wiring Systems End User Industry: Electric Vehicle Manufacturers, Battery Pack Producers, Power Electronics Suppliers, Insulation Material Providers Deployment: OEM Integration, Aftermarket Upgrades, Tier-1 Supplier Solutions, Component Retrofitting |
| Companies Covered | ICL Group, LANXESS, BASF SE, Eastman Chemical Company, Clariant, Solvay, Dover Chemical, Adeka Corporation, KPX Green Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market Trends and Innovations
Formulation chemistry, regulatory chemistry, and procurement architecture are converging to redefine how flame-retardant phosphate esters enter EV supply chains. Three developments dominate the current transition.
Isopropylated triphenyl phosphate is electrifying direct motor cooling applications by delivering sub-100 cSt viscosity at 40°C while maintaining char-forming efficiency above 300°C. European OEM thermal management teams are fast-tracking this chemistry into 2026-2027 platform designs. The technology is electrifying competitive positioning around fluid longevity rather than upfront additive cost.
REACH Annex XIV authorization requirements for halogenated flame retardants are eliminating legacy brominated options from battery pack specifications. German KBA type-approval processes now reference phosphate ester performance in thermal runaway propagation tests. Tier-1 suppliers in Stuttgart and Munich are reconfiguring blending lines to accommodate resorcinol bis(diphenyl phosphate) masterbatches.
Long-term offtake agreements are displacing spot purchasing as the dominant contracting mode for phosphate ester volumes. Battery producers in China's Jiangsu province are locking five-year supply commitments with integrated phosphorus producers to secure price stability. This pattern is most visible in procurement relationships serving CATL's European gigafactory network.
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market Segmentation
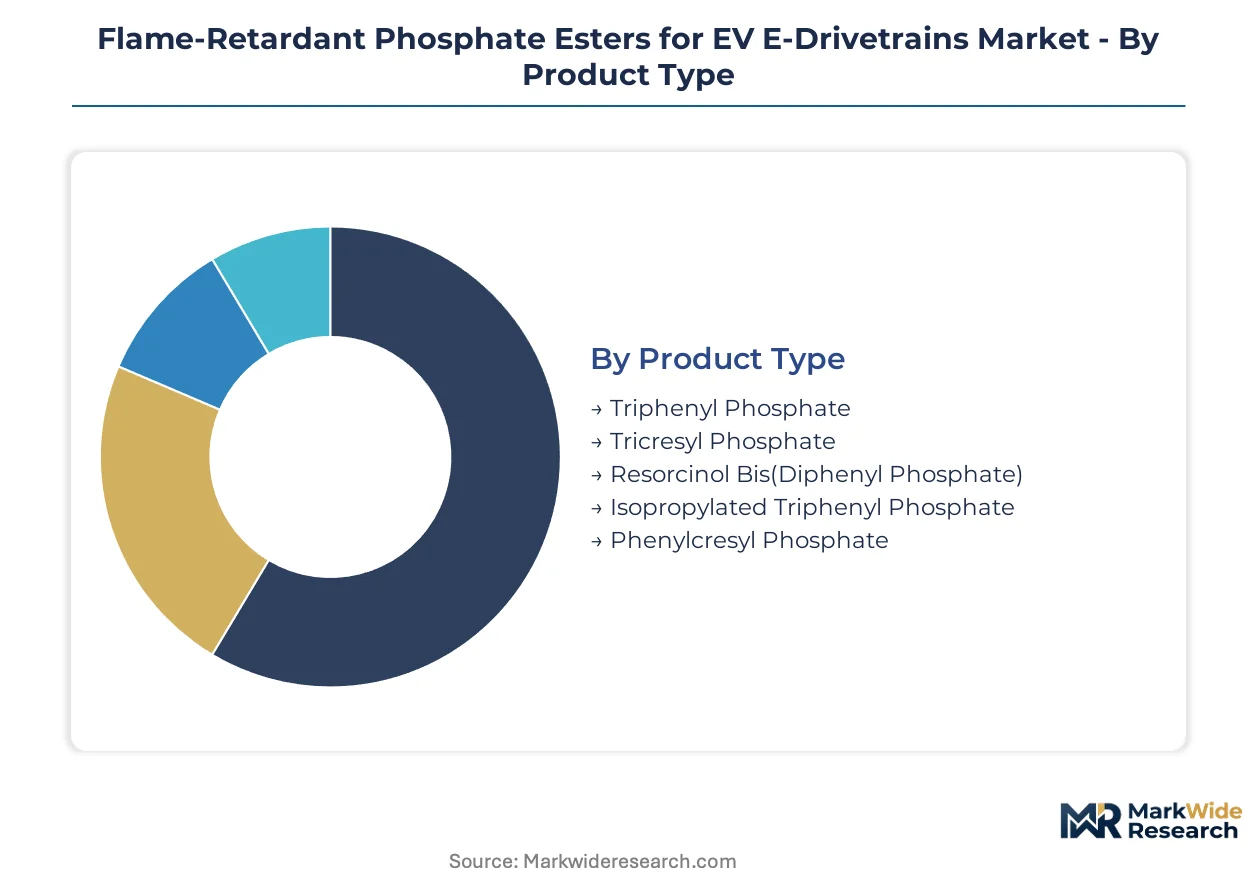
Phosphate ester specification varies sharply across thermal management architectures. Formulation chemistry, deployment mode, and end-user integration depth each create distinct procurement channels with divergent margin structures and qualification timelines.
Product Type:
Technical specifications around phosphorus content, aryl substitution patterns, and hydrolytic stability define how each chemistry enters EV supply chains.
- Triphenyl Phosphate:The foundational aryl phosphate ester delivers char-forming efficiency at 300°C-plus temperatures through pure phenyl substitution. German OEMs specify this chemistry for battery pack insulation where thermal runaway containment is mandatory under KBA type-approval protocols.
- Resorcinol Bis(Diphenyl Phosphate):This oligomeric structure provides superior hydrolytic stability in glycol-based coolants compared to monomeric alternatives. Procurement concentrates in Jiangsu province where domestic capacity serves CATL and BYD supply chains under MIIT safety standards.
- Tricresyl Phosphate:Methyl-substituted aryl rings reduce melting point for easier compounding into flexible insulation materials.
- Isopropylated Triphenyl Phosphate:Branched alkyl substitution cuts viscosity below 100 cSt at 40°C for direct motor cooling applications.
- Phenylcresyl Phosphate:Mixed aryl substitution balances cost and performance for mid-tier electronic component protection.
Mature deployment sits with triphenyl phosphate in conventional battery insulation. Newer deployment is concentrated in resorcinol bis(diphenyl phosphate) for next-generation coolant formulations.
Application:
Functional requirements around operating temperature, electrical load, and fluid contact duration determine which phosphate ester chemistry gets specified.
- Battery Thermal Management:Glycol-based coolant systems require hydrolytically stable phosphate esters that resist degradation above 120°C. ECHA REACH restrictions on halogenated alternatives are redirecting European demand toward aryl phosphate formulations in Stuttgart and Munich manufacturing clusters.
- Motor Cooling Fluids:Direct cooling architectures demand low-viscosity phosphate esters that maintain pumpability across -40°C to 150°C operating windows. Isopropylated triphenyl phosphate is expanding most quickly here as OEMs consolidate thermal loops.
- Electric Powertrain Insulation:High-voltage cable and busbar protection relies on phosphate ester-plasticized compounds.
- Electronic Components Protection:Printed circuit board coatings and potting compounds use lower-loading phosphate ester blends.
- Wiring Systems:Harness insulation employs phosphate ester synergists with metal hydroxides for cost-sensitive applications.
Established volume sits with battery thermal management. Emerging specification activity clusters in motor cooling fluid reformulation.
End User Industry:
Integration depth and captive blending capability separate how different buyer types procure phosphate ester formulations.
- Battery Pack Producers:CATL, BYD, and European gigafactory operators are internalizing formulation blending to control additive loading precision. These buyers negotiate long-term offtake agreements with integrated phosphorus suppliers rather than purchasing compounded products.
- Electric Vehicle Manufacturers:OEM thermal management teams specify phosphate ester performance targets but increasingly delegate formulation development to fluid suppliers.
- Power Electronics Suppliers:Inverter and converter manufacturers specify phosphate ester content in potting compounds for silicon carbide module protection.
- Insulation Material Providers:Wire and cable compounders purchase phosphate ester masterbatches for integration into flexible PVC and TPE formulations.
Contracting sophistication sits with battery pack producers. Specification authority is migrating toward electric vehicle manufacturers.
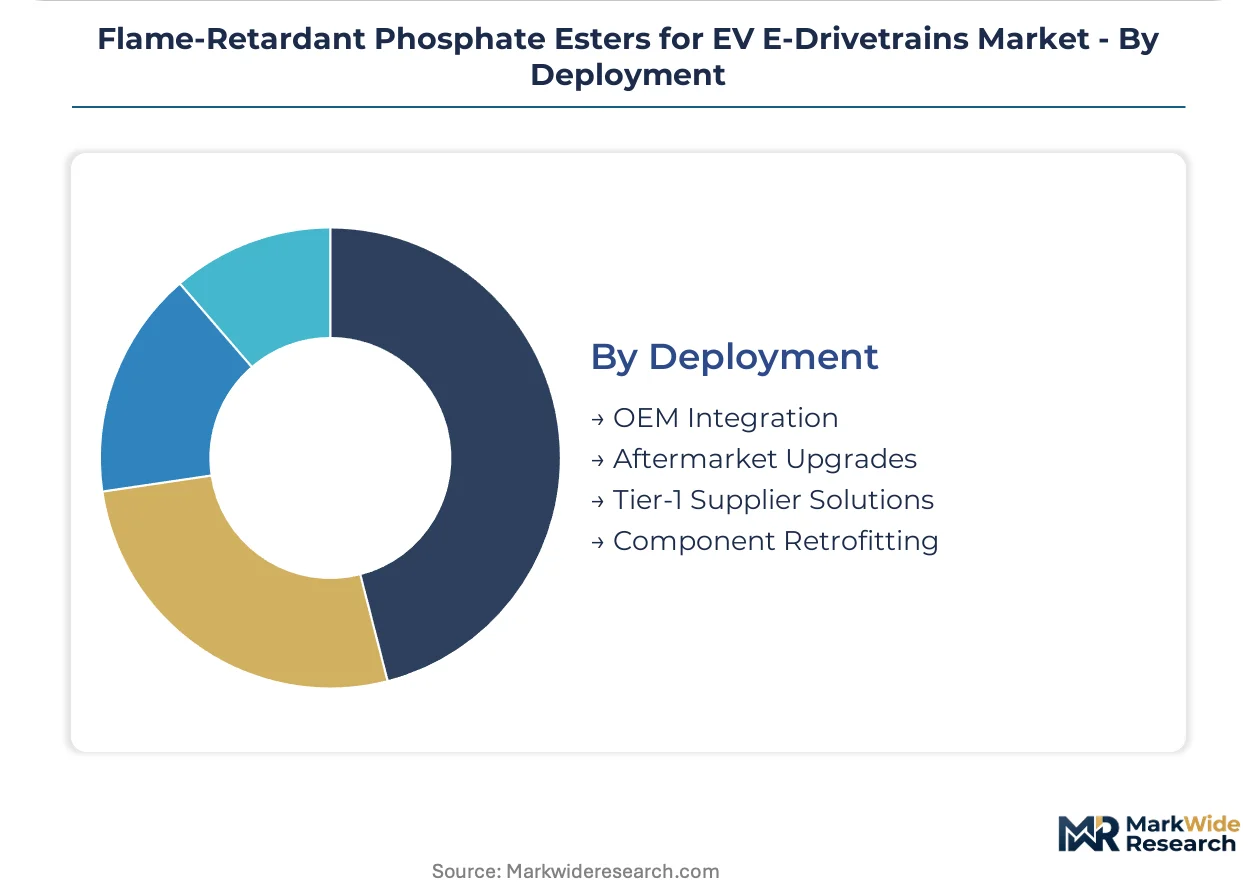
Deployment:
Channel structure determines margin capture and technical service intensity across the value chain.
- OEM Integration:Direct supply relationships with vehicle manufacturers capture premium pricing through embedded formulation engineering support. ICL Group and LANXESS compete aggressively for these contracts in European OEM thermal management programs.
- Tier-1 Supplier Solutions:Fluid formulators and insulation compounders purchase technical-grade phosphate esters for captive blending. Price compression is acute as battery producers internalize these capabilities.
- Aftermarket Upgrades:Retrofit coolant formulations and insulation repair materials represent fragmented demand with lower specification barriers.
- Component Retrofitting:Legacy fleet thermal system modifications create sporadic demand for phosphate ester-compatible replacement fluids.
Margin concentration sits with OEM integration. Volume scaling is concentrating in Tier-1 supplier channels facing margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates phosphate rock processing and aryl phosphate ester manufacturing capacity, while Germany and the United States drive consumption through EV production scale and regulatory mandates on halogen-free thermal management fluids.
Germany
Battery pack producers in Stuttgart and Munich are scaling procurement of resorcinol bis(diphenyl phosphate) formulations as KBA type-approval processes now reference phosphate ester performance in thermal runaway propagation tests. The EU F-Gas Regulation and REACH restrictions on halogenated alternatives are compressing formulation timelines for domestic OEMs. German chemical formulators in North Rhine-Westphalia are reconfiguring blending lines to accommodate oligomeric phosphate masterbatches.
China
Jiangsu province anchors domestic phosphate ester capacity serving BYD and CATL supply chains under MIIT new-energy vehicle safety standards and GB/T battery testing protocols. The country's dual carbon goals are accelerating substitution of halogenated flame retardants in glycol-based coolants. Manufacturers in the Yangtze River Delta are locking five-year offtake agreements with integrated phosphorus suppliers to secure price stability for European gigafactory exports.
United States
EPA scrutiny of persistent organic pollutants and NHTSA battery safety guidelines are opening qualification pathways for phosphate ester entrants in Michigan and California manufacturing clusters. State-level chemical disclosure rules in California are creating compliance-driven procurement thresholds distinct from federal timelines. Detroit-area thermal management engineering teams are evaluating isopropylated triphenyl phosphate for direct motor cooling architectures in 2026-2027 platform designs.
Japan
METI industrial policy and JIS standards for electric powertrain safety are redirecting formulation demand toward aryl phosphate esters in domestic EV manufacturing. Automotive suppliers in the Nagoya-Chubu region are qualifying low-viscosity phosphate esters for consolidated thermal loop designs. Japanese chemical producers are leveraging existing phosphorus derivative expertise to supply regional battery joint ventures with South Korean partners.
South Korea
Seoul Capital Area battery producers are integrating phosphate ester blending operations to control additive loading precision for export-bound cell production. Domestic MIIT-equivalent safety standards for new-energy vehicles are mandating flame-retardant performance in thermal management fluids. Busan-Ulsan chemical complexes are expanding technical-grade triphenyl phosphate output to serve captive demand from affiliated battery pack operations.
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct phosphorus supply chain positions. The market exhibits tiered concentration where integrated phosphorus miners and midstream compounders face divergent margin pressures. Three archetypes dominate: upstream-integrated suppliers controlling phosphate rock access, specialized formulators with REACH registration expertise, and captive blenders internalized by battery pack producers. Competitive intensity centers on backward integration into phosphorus feedstocks and strategic partnerships with OEM thermal management engineering teams.
Within the integrated-supplier tier, ICL Group and LANXESS occupy positions anchored by captive phosphorus supply chains and European regulatory compliance capabilities. BASF SE exemplifies the R&D-intensive archetype competing through patent coverage rather than feedstock control. Among Asia-Pacific-based compounders, Adeka Corporation and KPX Green Chemical represent regional formulators serving domestic battery producer specifications. These five entities collectively illustrate how competitive positioning diverges between upstream resource control, technical formulation expertise, and geographic proximity to demand clusters.
| Leading Market Players |
|---|
| ICL Group |
| LANXESS |
| BASF SE |
| Eastman Chemical Company |
| Clariant |
| Solvay |
| Dover Chemical |
| Adeka Corporation |
| KPX Green Chemical |
| Others |
Pricing and Supply Chain Analysis
Isopropylated triphenyl phosphate adoption for direct motor cooling is simultaneously compressing formulation premiums and concentrating procurement leverage among integrated phosphorus producers in Morocco and China. This chemistry shift rewards suppliers with captive phosphate rock processing while forcing independent compounders into price-competitive masterbatch supply.
Pricing Analysis
Margin tightening in Tier-1 supplier channels reflects battery pack producers internalizing blending operations and negotiating long-term offtake agreements directly with integrated phosphorus miners. Three-tier pricing structure across technical-grade, formulated masterbatch, and fully compounded coolant levels separates OEM integration premiums from commodity spot transactions. Cost-down pressure on standard-grade triphenyl phosphate accelerates because Jiangsu province capacity expansion outpaces European demand growth. Battery pack producers exhibit lowest price sensitivity due to captive blending economics, while aftermarket retrofit channels face acute margin compression.
Supply Chain Analysis
Reverse logistics for spent thermal management fluids remains underdeveloped, with most glycol-based coolants disposed rather than reprocessed, creating latent regulatory exposure as ECHA substance evaluation tightens. Phosphate rock processing concentrates in Morocco, China, and the United States, while aryl phosphate ester manufacturing anchors in Jiangsu province and North Rhine-Westphalia. Technical-grade triphenyl phosphate output draws from elemental phosphorus production tethered to captive mining concessions. Single-source vulnerability in Moroccan phosphate rock exports threatens European formulator cost stability. Distribution runs through integrated phosphorus suppliers direct to battery pack producers, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH registration dossier complexity and eighteen-month commercialization timelines will eliminate formulation-only compounders lacking backward integration into phosphorus feedstocks.
For Market Incumbents: Hedge against feedstock access risk by securing captive phosphate rock offtake from Moroccan mining concessions or Jiangsu province integrated producers. Invest simultaneously in REACH registration expertise for novel isopropylated triphenyl phosphate derivatives to defend formulation premium capture against halogen-free regulatory mandates tightening across European OEM specifications. For New Entrants and Emerging Players: Enter via solid-state battery thermal interface materials as the most penetrable white-space segment, where flame-retardant potting compound demand extends phosphate ester application beyond liquid coolant saturation. Target Michigan and California manufacturing clusters with EPA-compliant qualification pathways for direct motor cooling formulations, leveraging NHTSA battery safety guideline alignment as technical credibility anchor. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of REACH-registered formulators with established OEM thermal management engineering relationships, as regulatory compliance timelines create defensive moats. Five-to-ten year viability favors integrated suppliers controlling phosphorus supply chains over asset-light designers facing persistent margin compression. Monitor ECHA substance evaluation acceleration for isopropylated triphenyl phosphate derivatives as inflection signal for competitive repositioning urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive Moroccan or Chinese mining concessions insulate European formulators from raw material access volatility under tightening EU F-Gas Regulation compliance timelines. |
| REACH Registration Acceleration | Early dossier submission for novel isopropylated triphenyl phosphate derivatives compresses eighteen-month commercialization cycles before competitor lock-in solidifies. |
| Long-term Supply Agreement | Five-year offtake commitments with CATL and BYD supply chains in Jiangsu province secure volume allocation as battery producers internalize blending capabilities. |
| Solid-State Battery Materials Development | Flame-retardant potting compound R&D extends phosphate ester addressable market beyond liquid coolant saturation into next-generation cell architectures. |
| Software-Defined Thermal Management Partnership | Predictive monitoring service contracts with OEM thermal engineering teams unbundle fluid specification from hardware procurement, creating recurring revenue streams. |
Research Methodology
Multi-period observation of formulation chemistry adoption rates, regulatory registration timelines, and long-term offtake contracting patterns anchored the trend analysis, supplemented by interviews with thermal management engineering directors at European OEMs, procurement leads at Jiangsu province battery pack producers, phosphate ester plant managers in North Rhine-Westphalia, and ECHA regulatory affairs specialists. Secondary validation drew from EU REACH registration databases, MIIT new-energy vehicle safety standard filings, SEC 10-K disclosures from integrated phosphorus suppliers, and German KBA type-approval documentation. Bottom-up volume estimates from individual production facility outputs triangulated against top-down demand projections from EV platform thermal architecture specifications.
Segment-weighting across product type, application, and deployment mode dimensions structured the analytical framework, with resorcinol bis(diphenyl phosphate) and isopropylated triphenyl phosphate chemistry splits modeled separately given divergent viscosity and hydrolytic stability performance profiles. CAGRs derived from regression analysis of historical procurement volumes against EV production forecasts and battery pack thermal management fluid content per vehicle assumptions. Industry-specific inputs included GB/T battery testing protocol compliance thresholds and direct motor cooling architecture adoption curves across European and Chinese OEM platforms.
Revisions become necessary when ECHA accelerates substance evaluation timelines, when Moroccan phosphate rock export restrictions materialize, or when solid-state battery commercialization displaces liquid coolant demand faster than projected. Forecasts reflect documented assumptions around regulatory enforcement consistency and OEM thermal architecture consolidation patterns. Practitioners should monitor KBA type-approval protocol updates and MIIT standard revision announcements for early signals of qualification pathway shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Emulsion Explosive Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Continuous Reactors Market